
 Commercial Greenhouse Market | 2026-2036
Commercial Greenhouse Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Greenhouse Market Intelligence
The divergence in capital investment for advanced automation and climate control systems is bifurcating the market. Large-scale operators like Richel Group leverage their manufacturing capacity to supply massive, multi-hectare projects globally. In contrast, Certhon differentiates through turnkey, high-tech solutions integrating robotics and data analytics for precision agriculture. Argus Control Systems specializes in the critical software layer, providing the environmental management platforms that optimize growing conditions across different greenhouse structures.
A commercial greenhouse is a structure designed for the cultivation of plants on a commercial scale under controlled environmental conditions. These structures utilize coverings such as glass, polycarbonate, or plastic film to regulate light transmission, temperature, and humidity. Their primary purpose is to enable year-round production, protect crops from adverse weather, and optimize resource use like water and nutrients. While glass greenhouses offer maximum light transmission and longevity, polycarbonate and plastic film structures represent a growing segment due to their lower initial cost and improved material durability. The vegetables segment, including tomatoes and leafy greens, constitutes the largest application by crop type, driven by consumer demand for locally sourced produce.
Regulatory frameworks significantly influence technology adoption and operational standards in the commercial greenhouse industry. The EU Green Deal, particularly its Farm to Fork strategy, encourages sustainable practices and reduced pesticide use, steering investment toward integrated pest management and closed-loop irrigation systems. In the United States, USDA grants for specialty crops and controlled environment agriculture support new facility construction. Global ISO standards for greenhouse construction provide benchmarks for structural integrity and material safety. Future profitability for operators will hinge on balancing capital-intensive technology adoption with volatile energy costs and tightening water use regulations.
Market Dynamics
The commercial greenhouse market is shaped by the divergence between capital-intensive automation for large-scale operations and the demand for accessible technology from smaller growers. This tension is driven by volatile energy costs and persistent agricultural labor shortages.
Growth Catalysts
- EU Green Deal:The Farm to Fork strategy encourages reduced pesticide use, directly benefiting controlled environment agriculture by promoting investment in integrated pest management and closed-loop systems.
- Consumer Demand Patterns:Preference for year-round availability of locally sourced produce, especially leafy greens and vine crops, supports investment in urban and peri-urban greenhouse facilities.
- Technology Maturation:Advances in energy-efficient LED lighting and automated climate control systems are lowering operational expenditures, making greenhouse cultivation economically viable for more crops and regions.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced glass greenhouses with integrated automation and climate control systems creates a substantial barrier to entry.
- Energy Price Volatility:Fluctuating prices for natural gas and electricity, critical inputs for heating and lighting in climates like Canada and the Netherlands, directly threaten operational profitability.
- Water Scarcity:A dependency on stable, high-quality water sources poses a structural constraint for facility development and expansion in arid or water-stressed agricultural regions.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in the Middle East, including the UAE and Saudi Arabia, present opportunities for specialized greenhouse solutions engineered for hot and arid climates.
- High-Value Crop Cultivation:The production of pharmaceutical-grade botanicals and ingredients for the cosmetics industry offers a new, high-margin application beyond traditional food crops.
- Technology Convergence:Integrating AI-driven predictive analytics with robotic harvesting systems creates pathways toward fully autonomous operations that can mitigate labor shortages and optimize crop yields.
Industry Challenges
- Specialized Talent Gap:A persistent shortage of skilled personnel, including horticulturalists with data science expertise and technicians for automated systems, constrains operational efficiency and growth.
- Compliance Complexity:Adhering to varied global food safety and traceability standards, such as GlobalG.A.P., demands significant investment in process control, documentation, and certification.
- Legacy System Integration:Connecting new automation and software platforms with existing, often proprietary, greenhouse infrastructure presents significant technical and financial hurdles for established operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Greenhouse Market |
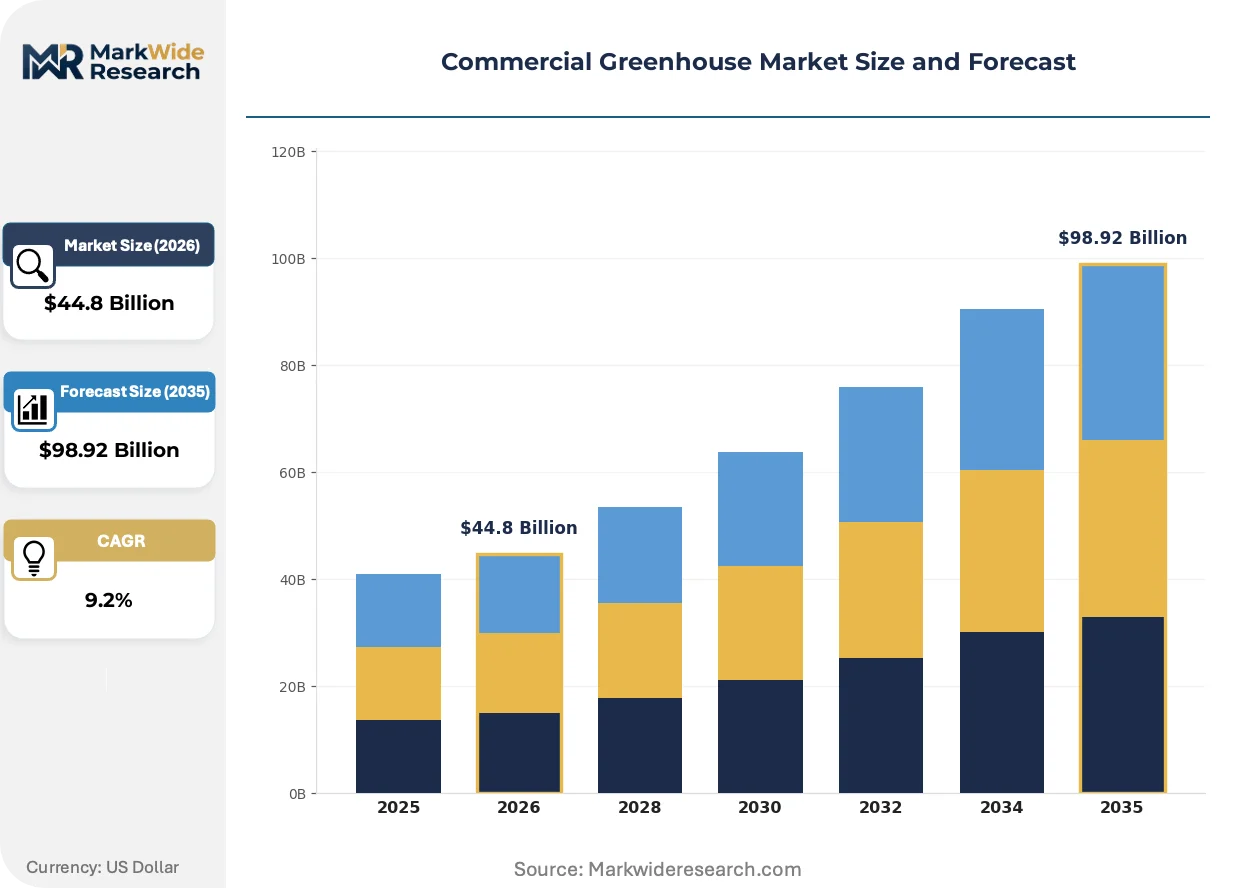
| Market Size in 2026 | $44.8 Billion |
| Market Size in 2035 | $98.92 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Structure Type: Glass Greenhouses, Polycarbonate Greenhouses, Plastic Film Greenhouses, Tunnel Greenhouses Crop Type: Vegetables, Flowers, Herbs, Fruits, Seedlings End User: Commercial Growers, Research Institutions, Specialty Farms, Horticulture Businesses Heating Technology: Electric Heating, Gas Heating, Solar Heating, Biomass Heating, Hot Water Heating |
| Companies Covered | Richel Group, Certhon, Argus Control Systems, Rough Brothers, Logiqs, Netafim, Agra Tech, Stuppy Greenhouse, Gibraltar Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Greenhouse Market Strategic Shifts & Innovations
Data-driven automation is actively transforming greenhouse operations, moving the industry from reactive management to predictive, autonomous control. This pivot is enabled by the convergence of IoT sensors, artificial intelligence, and advanced robotics for precision agriculture.
Dynamic, semi-closed greenhouse designs incorporate active ventilation and energy recovery systems to create a more controlled microclimate. Large-scale commercial growers in regions with variable climates, such as the Netherlands and parts of North America, are rapidly adopting these systems. This approach is supplanting traditional, fully vented structures by offering superior pest control and resource efficiency, particularly for water and CO2.
Canada's national carbon pricing framework imposes direct costs on fossil fuel consumption for greenhouse heating. This policy financially incentivizes growers to invest in technologies like thermal screens, biomass boilers, and combined heat and power systems. The vegetable segment, particularly large tomato producers in Ontario, is accelerating adoption of these capital-intensive upgrades to mitigate rising energy expenses.
Major food retailers are entering into long-term, direct-sourcing contracts with large-scale greenhouse operators. This model disrupts traditional wholesale market channels, favoring growers who can guarantee year-round volume, consistent quality, and full traceability. The trend is most visible in North America and Europe for high-demand categories like leafy greens and berries.
Commercial Greenhouse Market Segmentation
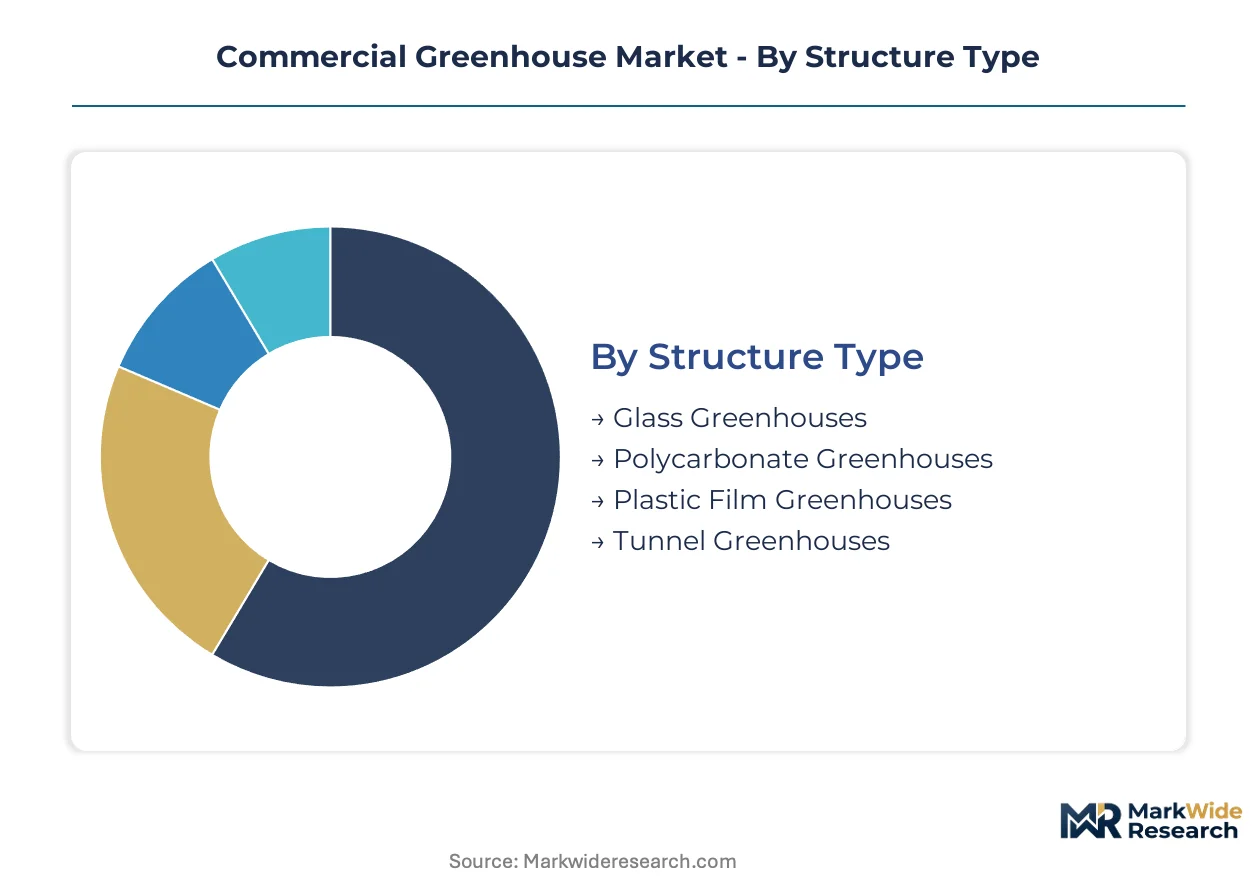
The commercial greenhouse market segments across diverse structural designs, crop applications, and operational technologies. Understanding these distinctions clarifies investment priorities and technological integration paths for operators seeking efficiency and yield optimization. Each segment reflects specific cultivation needs and economic drivers.
Structure Type:
Regulatory frameworks differentiate commercial greenhouse structures based on material and design specifications, influencing adoption rates across various climate zones.
- Glass Greenhouses:Glass greenhouses feature high light transmission properties and superior structural longevity, often employing advanced climate control systems. Demand concentrates in established horticultural regions like the Netherlands, driven by high-value crop production and long-term operational stability.
- Polycarbonate Greenhouses:Polycarbonate greenhouses utilize multi-wall panels providing better insulation and impact resistance than glass, reducing heating costs. Operators in colder climates, including Canada, increasingly adopt polycarbonate for improved energy efficiency and enhanced crop protection.
- Plastic Film Greenhouses:Plastic film greenhouses offer a cost-effective solution for crop protection, particularly in regions with moderate climates and seasonal cultivation cycles.
- Tunnel Greenhouses:Tunnel greenhouses provide basic environmental control for vegetables and herbs, favored by smaller growers due to their low initial investment and ease of installation.
Glass Greenhouses handle the majority of throughput; Polycarbonate Greenhouses are the fastest mover on share.
Crop Type:
Commercial greenhouse operators prioritize crop types based on consumer demand patterns and specific cultivation requirements.
- Vegetables:The vegetables segment encompasses high-yield crops such as tomatoes, cucumbers, and leafy greens, requiring precise climate and nutrient management. Consumer demand for year-round availability of locally sourced produce drives significant investment in urban and peri-urban facilities.
- Flowers:The flowers segment focuses on ornamental plants and cut flowers, where consistent quality and bloom timing are critical for market competitiveness.
- Herbs:Greenhouse cultivation of herbs provides fresh, pesticide-free options for culinary and medicinal markets, with specialized facilities adopting hydroponic systems.
- Fruits:Greenhouse-grown fruits, including strawberries and berries, benefit from controlled environments that optimize sweetness and extend growing seasons. High-value markets in Europe and North America drive demand for consistent quality and volume, reducing reliance on seasonal outdoor harvests.
- Seedlings:The seedlings segment supports agricultural industries by providing young plants with optimized growth conditions before field transplanting, ensuring robust starts.
Vegetables command the largest market share; Fruits are expanding most quickly.
End User:
End-user segments define the scale and technological sophistication required for commercial greenhouse operations.
- Commercial Growers:Commercial growers operate large-scale facilities focused on high-volume production of food crops, requiring advanced automation and integrated climate control. This segment dominates the market, driven by consumer demand for consistent produce supply and efficiency in resource utilization.
- Research Institutions:Research institutions utilize greenhouses for plant breeding, genetic modification studies, and controlled environment agriculture experimentation. They demand highly precise environmental controls and data analytics capabilities to ensure experimental integrity and validate new cultivation techniques.
- Specialty Farms:Specialty farms focus on niche crops like rare botanicals or pharmaceutical-grade plants, prioritizing precise environmental conditions and stringent quality controls.
- Horticulture Businesses:Horticulture businesses encompass nurseries and plant propagation centers, requiring adaptable greenhouse solutions for diverse plant species and growth stages.
Commercial Growers represent the largest user base; Specialty Farms exhibit the steepest expansion trajectory.
Heating Technology:
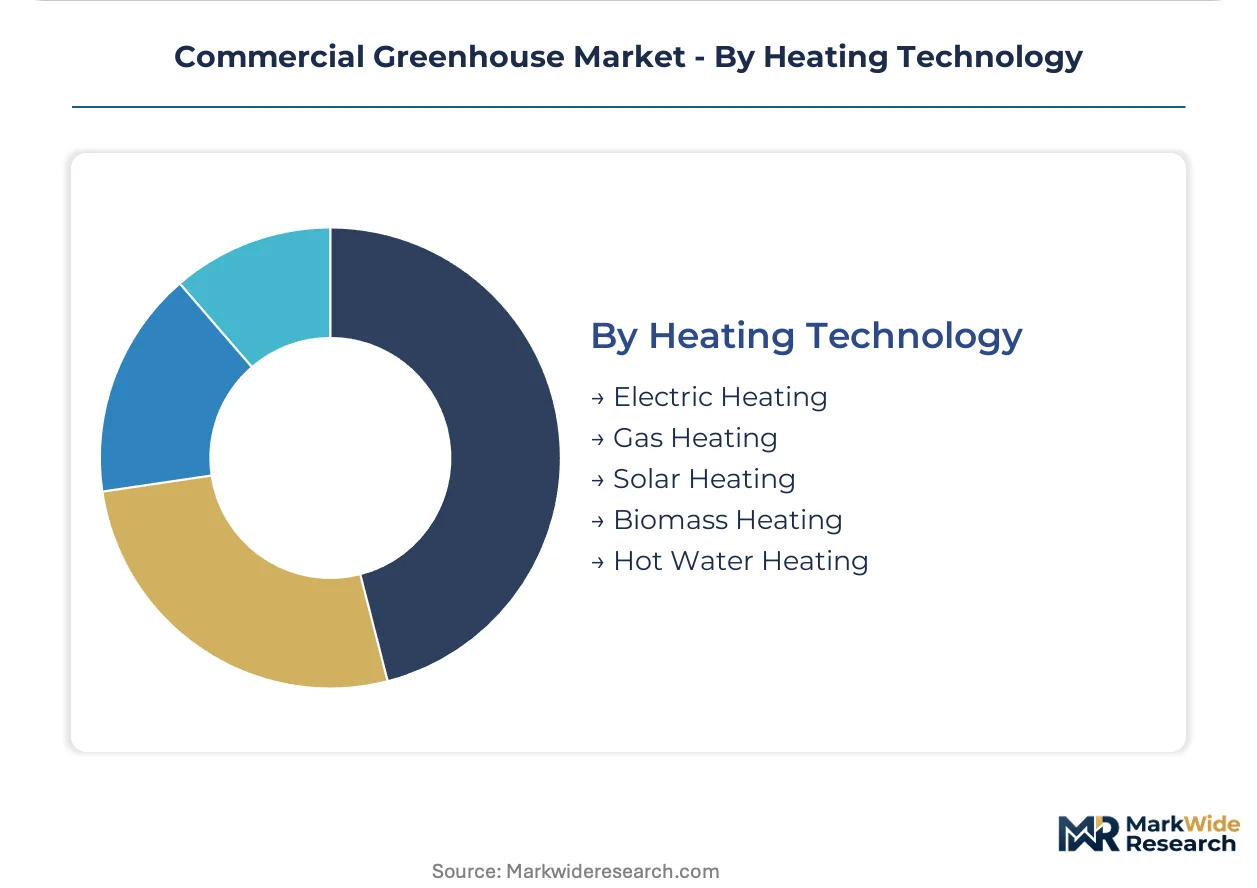
Heating technologies are selected based on energy efficiency, operational costs, and regional sustainability mandates.
- Electric Heating:Electric heating offers precise control for smaller greenhouse zones or as a supplementary heat source, often integrated with renewable electricity grids.
- Gas Heating:Gas heating systems, primarily using natural gas, provide efficient and responsive temperature control for large commercial greenhouses. Operators in regions with established gas infrastructure, such as parts of North America and Europe, rely on this technology despite energy price volatility.
- Solar Heating:Solar heating systems harness solar energy for passive or active greenhouse warming, reducing energy consumption and carbon footprint in sunnier climates.
- Biomass Heating:Biomass heating systems utilize organic materials like wood chips or agricultural waste, offering a renewable energy source for greenhouse climate control. Canadian growers, particularly large tomato producers, increasingly adopt biomass to mitigate carbon taxes and reduce reliance on fossil fuels.
- Hot Water Heating:Hot water heating distributes warmth through pipes, providing uniform temperature across large cultivation areas, often powered by centralized boilers.
Gas Heating remains a dominant choice; Biomass Heating is gaining share fastest due to sustainability incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the commercial greenhouse market varies significantly, with established regions like the Netherlands facing upward cost pressures from energy price volatility. In contrast, emerging markets such as the UAE present opportunities for specialized solutions, leveraging different resource costs and government incentives. This divergence shapes investment flows.
Netherlands
The Netherlands remains a central hub for commercial greenhouse technology, driven by demand for high-value crops and advanced automation. The EU Green Deal, particularly its Farm to Fork strategy, steers investment towards sustainable practices and closed-loop irrigation systems. Westland, known as the 'Glass City', continues to innovate with energy-efficient semi-closed greenhouse designs and advanced climate control solutions.
Canada
Canadian demand for commercial greenhouses stems from consumer preference for locally sourced produce and extended growing seasons. Canada's national carbon pricing framework incentivizes growers to adopt biomass boilers and combined heat and power systems. Large tomato producers in Ontario are accelerating capital-intensive upgrades to mitigate rising energy expenses.
United States
United States demand for greenhouse cultivation focuses on year-round availability of leafy greens and specialty vegetables. USDA grants for specialty crops and controlled environment agriculture support new facility construction across various states. California's central valley sees significant investment in advanced facilities, driven by both consumer demand and water conservation efforts.
UAE
The UAE presents a significant opportunity for specialized greenhouse solutions, driven by food security initiatives and arid climate challenges. Government policies, such as the National Food Security Strategy 2051, support investment in advanced agricultural technologies. Dubai is becoming a hub for innovative vertical farms and climate-controlled greenhouses designed for extreme heat.
Saudi Arabia
Saudi Arabia's commercial greenhouse market expands due to strategic national initiatives aimed at diversifying food sources and reducing import reliance. The Saudi Vision 2030 program encourages foreign direct investment in high-tech agriculture and sustainable farming practices. Riyadh and NEOM are attracting significant capital for large-scale, climate-controlled agricultural projects.
Commercial Greenhouse Market Key Industry Players
Concentration sits with large-scale facility providers and specialized technology integrators within the commercial greenhouse market. The industry structure exhibits a tiered approach, with a few dominant players offering comprehensive, integrated solutions alongside numerous niche providers focusing on specific components. Strategic archetypes include turn-key solution providers, advanced automation software specialists, and material suppliers. Companies engage in significant capacity expansion and geographic diversification to capture new market opportunities, alongside strategic partnerships to integrate diverse technologies.
Within the large-scale facility provision segment, Richel Group exemplifies a global operator leveraging extensive manufacturing capacity for massive, multi-hectare projects across continents. Certhon, a provider of high-tech solutions, occupies a distinct position focused on integrating advanced robotics and data analytics to enable precision agriculture. Argus Control Systems anchors the critical software layer, specializing in environmental management platforms that optimize growing conditions and resource utilization across diverse greenhouse structures. These companies collectively represent the market's drive towards both scale and technological sophistication.
| Leading Market Players |
|---|
| Richel Group |
| Certhon |
| Argus Control Systems |
| Rough Brothers |
| Logiqs |
| Netafim |
| Agra Tech |
| Stuppy Greenhouse |
| Gibraltar Industries |
| Others |
Cost & Logistics Intelligence
Large-scale capacity utilization in commercial greenhouse operations shapes supply concentration and influences price floors across different crop types. This dynamic ensures that operators with significant infrastructure investments can achieve economies of scale, impacting market competitiveness.
Pricing Analysis
The customization-premium spread differentiates pricing in the commercial greenhouse market, with project-based solutions commanding higher values than standardized module sales. Contract-based long-term offtake agreements for produce represent a dominant pricing model for large growers. Price differentiation stems from the level of technology integration and after-sales service provided. Pricing pressure intensifies for basic greenhouse structures due to material cost fluctuations. Smaller growers exhibit higher price sensitivity for initial capital expenditure compared to large commercial operators.
Supply Chain Analysis
Just-in-time inventory management characterizes the supply chain for perishable inputs like growing media and specialized nutrients, while strategic stockpiles secure critical components. Geographic supply concentration for advanced greenhouse technology centers in the Netherlands and Canada, with raw materials like glass and polycarbonate sourced globally. The supply chain relies on specialized LED components and automation software from diverse vendors. Commodity price volatility for natural gas and electricity presents a structural risk to operational costs. Distribution runs through specialized integrators and direct-to-grower channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial greenhouse market presents a fragmentation opportunity, driven by evolving consumer demand for hyper-local and specialized produce.
For Market Incumbents: Consolidate manufacturing capabilities and distribution networks to counter rising energy costs and maintain competitive scale. Invest in advanced R&D for energy-efficient climate control systems and AI-driven predictive analytics to mitigate margin pressure. Pursue strategic geographic expansion into underpenetrated markets like the Middle East. Secure long-term contracts with major food retailers to stabilize revenue streams against market volatility.
For New Entrants and Emerging Players: Certification fast-track programs, such as GlobalG.A.P. compliance, offer a rapid entry point for new greenhouse operators targeting high-value produce segments. Focus on niche crops like pharmaceutical-grade botanicals or exotic fruits in regions with supportive government incentives, such as the UAE. Develop turnkey, data-analytics-driven solutions for smaller growers to address the specialized talent gap. Leverage modular, cost-effective plastic film or tunnel greenhouse designs for initial market penetration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized software and automation providers within the commercial greenhouse sector, offering robust returns. These companies possess intellectual property crucial for optimizing resource use and mitigating labor shortages over the long term. Target acquisition profiles include firms specializing in AI-driven environmental management platforms or robotic harvesting systems. The signal to watch is the stabilization of energy prices coupled with increased regulatory mandates for sustainable agriculture.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Arid Regions | Increases food security in water-stressed areas like the UAE and Saudi Arabia. |
| AI-Driven Climate Control Development | Optimizes resource utilization and crop yields for large-scale commercial growers. |
| Biomass Heating System Integration | Reduces operational costs and carbon footprint for Canadian greenhouse operators. |
| Strategic Partnerships with Food Retailers | Ensures consistent demand and supply chain stability for high-volume produce. |
| Precision Robotics for Harvesting | Mitigates agricultural labor shortages and enhances operational efficiency for specialty farms. |
Research Approach
Desk research of academic journals, government reports, and corporate filings preceded structured interviews with horticulturalists, greenhouse operators, technology developers, and policy advisors. This primary research gathered qualitative insights into market dynamics, technology adoption, and regulatory landscapes. Data triangulation across these sources validated market trends and competitive positioning. Both bottom-up and top-down approaches refined market sizing and segmentation estimates.
Variance-decomposition analysis underpins the analytical framework, quantifying the influence of key market drivers on projected growth across the analysis window. The model incorporates segmentation across structure type, crop type, end user, heating technology, and regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived by projecting demand-side shifts and supply-side capacity additions over the projection horizon. Industry-specific forecast inputs included energy price forecasts and agricultural labor availability trends.
Decision-makers should treat outputs as directional under current energy price and regulatory stability assumptions; material deviation would warrant model refresh. Forecasts reflect a comprehensive assessment of available data and expert insights. Practitioners should keep alternative scenarios live as climate policy and technology adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
LED Farming Market
Indoor Farming Technologies
Global Horticulture Lighting Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
Hydroponic System Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Controlled Environment Agriculture Market
Indoor Farming Technologies
LED Grow Lights Market
Indoor Farming Technologies
United States Grow Light Market
Indoor Farming Technologies
Europe Vertical Farming Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Global Grow Lights Market
Indoor Farming Technologies
Canada Indoor Farming Market
Indoor Farming Technologies
China Greenhouse Horticulture Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
US Vertical Farming Market