
 Global Grow Lights Market | 2026-2036
Global Grow Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grow Lights Market Analysis
Aftermarket service revenue is reshaping profitability across the grow lights industry. Signify Holding leverages its digital services platform to capture recurring maintenance contracts. Hortilux Schréder anchors its position through specialized photobiology consulting bundled with fixture sales. Valoya competes on spectral recipe IP, extending its reach into research institution partnerships.
Grow lights are electrically powered luminaires engineered to emit specific photosynthetically active radiation wavelengths, typically spanning 400–700 nanometers, designed to stimulate plant growth in environments with insufficient natural sunlight. LED systems now dominate product type dynamics due to their tunable spectra and thermal efficiency, while HPS retains share in large-scale greenhouse retrofits where capital constraints persist. Vertical farming applications command premium positioning within the application dimension, though commercial growers as an end user segment represent the broadest volume base.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant and material choices in climate-controlled growing infrastructure, indirectly shaping fixture thermal design requirements. The US EPA Energy Star program and FDA food safety guidelines influence commercial grower procurement standards for indoor cultivation environments. Stakeholders must monitor how evolving carbon border adjustments and agricultural electricity tariff structures alter total cost-of-ownership calculations across regional deployment strategies.
Market Dynamics
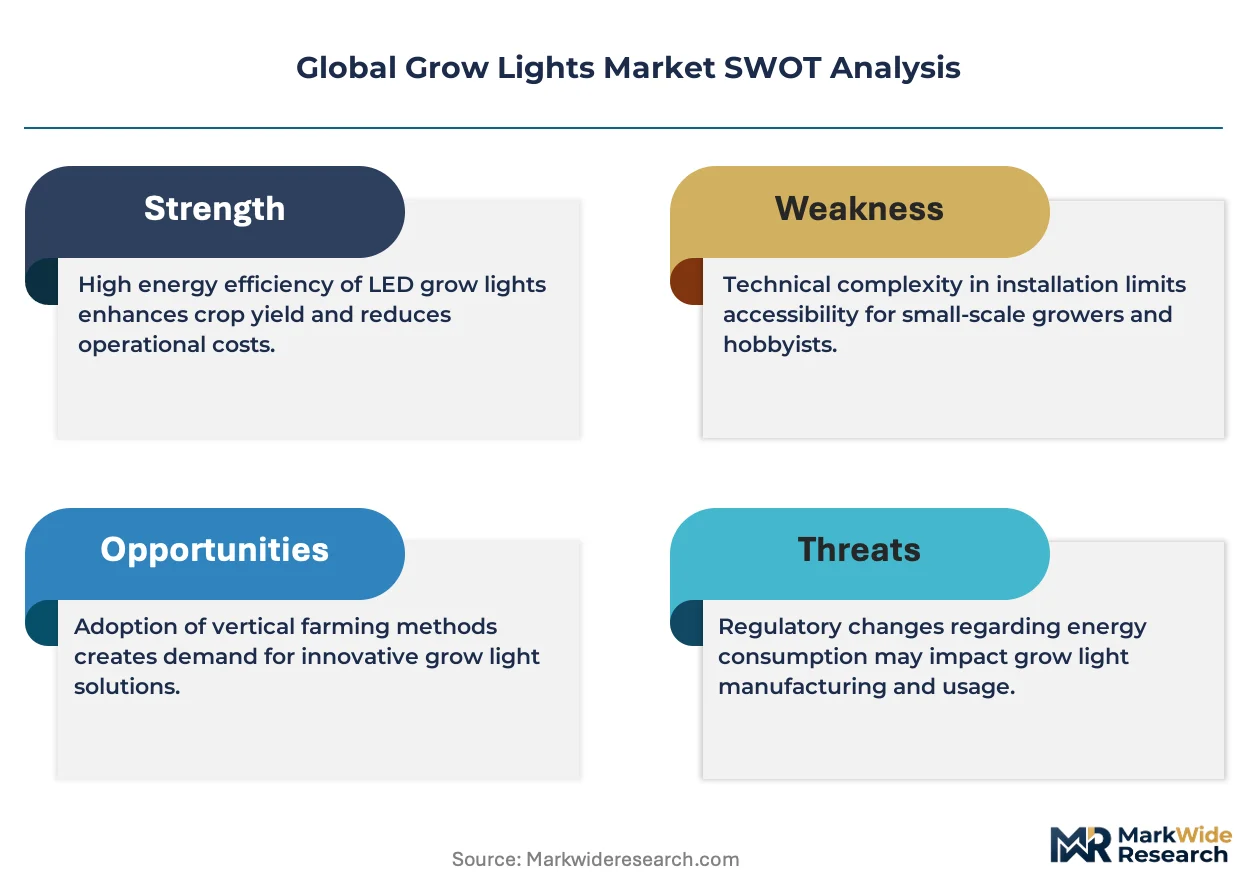
LED spectral tunability is compressing replacement cycles across controlled-environment agriculture while EU energy-efficiency mandates force premature HPS decommissioning in Dutch, Danish, and Belgian greenhouse clusters.
Growth Catalysts
- EU Green Deal energy mandates:Dutch commercial growers face binding efficiency targets that accelerate LED retrofits in existing greenhouse infrastructure.
- Controlled-environment agriculture expansion:Vertical farming operators in Singapore, UAE, and Japan deploy spectrally optimized fixtures to offset land scarcity and import dependency.
- Dual carbon goals:China's domestic manufacturing of energy-efficient luminaires receives state support for agricultural electricity reduction targets.
Market Restraints
- Phosphor and rare-earth supply concentration:LED phosphor materials depend heavily on Chinese processing capacity, creating input cost volatility exposure.
- Capital intensity of full-spectrum retrofits:Large-scale greenhouse operators in Spain and Italy delay LED transitions due to upfront fixture and climate-system reconfiguration costs.
- Technical limitation in deep canopy penetration:LED point-source geometry struggles to match HPS uniform radiation distribution in tall vine crops without fixture density increases.
Strategic Opportunities
- Underpenetrated Indian protected cultivation:Polyhouse expansion under national horticulture missions creates demand for cost-optimized supplemental lighting in Maharashtra and Karnataka.
- Research institution partnerships:Spectral recipe IP licensing to university agricultural programs builds captive demand pipelines for photobiology-optimized fixtures.
- EU F-Gas Regulation thermal design convergence:Climate-controlled growing infrastructure requirements favor LED thermal profiles that reduce HVAC load integration complexity.
Industry Challenges
- Photobiology skill scarcity:Commercial growers lack in-house expertise to optimize spectral recipes for cultivar-specific yield targets without vendor consulting dependency.
- Legacy HPS infrastructure lock-in:Existing ballast and reflector investments in Spanish Almería greenhouse complexes create switching cost friction for LED transitions.
- REACH compliance timeline pressure:Material substitution requirements for driver electronics and housing alloys compress product redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grow Lights Market |
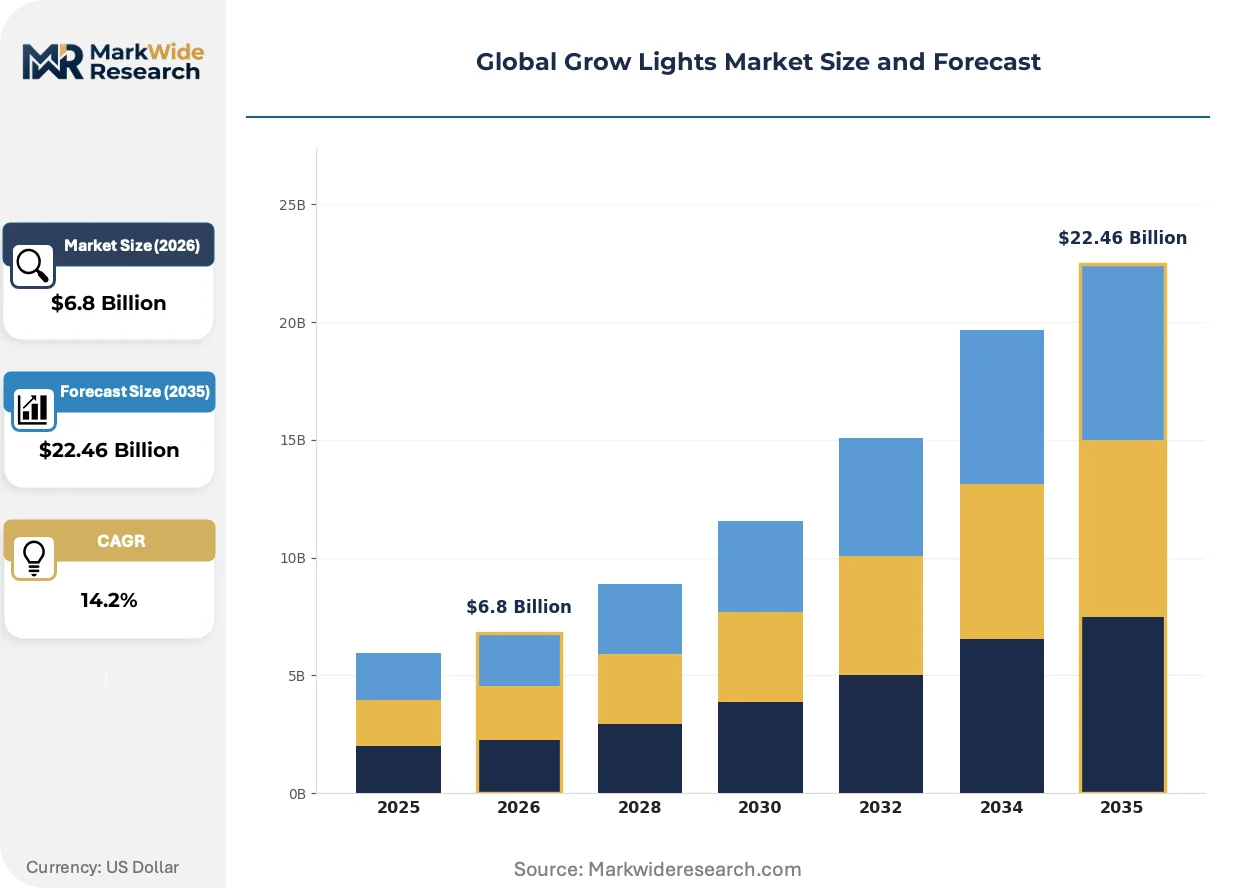
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, HPS, Fluorescent, CMH Application: Agriculture, Horticulture, Greenhouses, Vertical Farming End User: Commercial Growers, Home Gardeners, Research Institutions, Nurseries Technology: Smart Lighting, Control Systems, Manual, Hybrid |
| Companies Covered | Gavita International B.V., Hortilux Schréder, Signify Holding, Illumitex, Valoya, ams-OSRAM AG, California LightWorks, LumiGrow Inc, Heliospectra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grow Lights Market Emerging Trajectories
Digital spectral control is transforming fixture value from hardware commodity to programmable cultivation input, while service unbundling separates photobiology consulting from equipment procurement.
Dynamic LED arrays with zone-level spectral tuning are rendering obsolete fixed-spectrum fixtures in high-value crop segments. Dutch tomato and cucumber producers in Westland municipality deploy tunable systems to manipulate flowering photoperiods without shade curtain manipulation. The technology is rendering obsolete capital-intensive climate infrastructure previously required for light-period control.
REACH substance restrictions and EU F-Gas Regulation thermal requirements are reshaping fixture material selection and heat dissipation architecture. Driver electronics manufacturers reformulate solder and capacitor chemistries to maintain CE marking compliance. Greenhouse builders in Belgium and the Netherlands now specify LED-optimized climate system designs that reduce refrigeration load through lower waste heat rejection.
Aftermarket service unbundling is separating hardware procurement from recurring photobiology support contracts. Large North American cannabis operators negotiate fixture purchases independently from spectral programming subscriptions. This bifurcation is most visible in California and Colorado cultivation facilities where in-house agronomy teams demand control over recipe intellectual property.
Global Grow Lights Market Segmentation
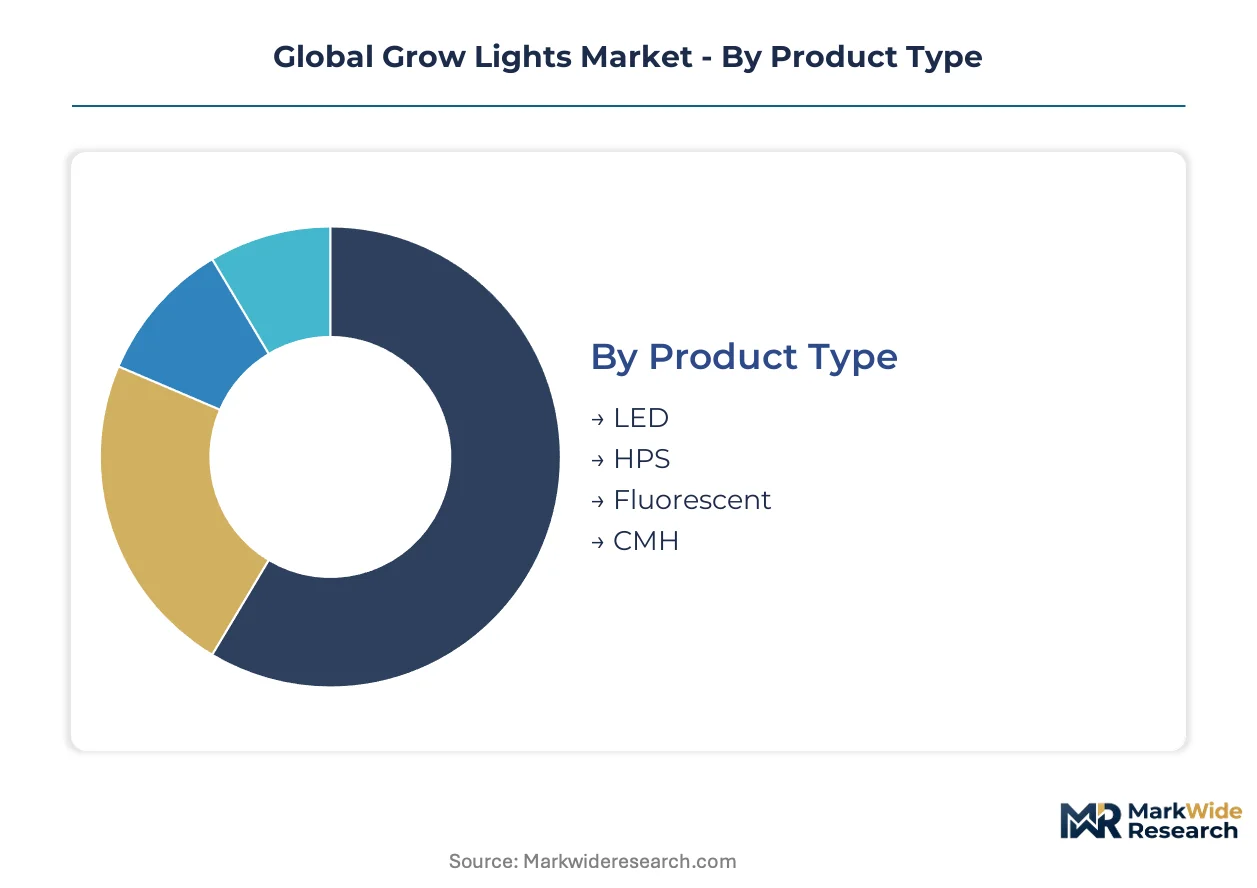
Segmentation in grow lights determines procurement cycles, margin profiles, and vendor relationships across controlled-environment agriculture. Fixture replacement intervals vary dramatically by technology maturity and application intensity, reshaping how suppliers structure service revenue and financing.
Product Type:
LED systems compress replacement cycles to 5-7 years through phosphor degradation and driver electronics failure, while HPS installations persist 10-15 years in capital-constrained operations.
- LED:Solid-state luminaires utilizing semiconductor diodes with tunable 400-700nm spectral output and 40% lower thermal load than legacy alternatives. Dutch Westland greenhouse operators under EU Green Deal mandates are retrofitting HPS infrastructure at accelerated rates despite upfront capital requirements.
- HPS:High-pressure sodium vapor lamps delivering broad-spectrum radiation with established ballast infrastructure and lower unit economics. Spanish Almería tomato producers delay LED transitions due to existing reflector investments and technical comfort with uniform canopy penetration in tall vine crops.
- Fluorescent:Linear tube fixtures with limited spectral tunability, concentrated in research propagation chambers and low-budget home cultivation.
- CMH:Ceramic metal halide systems offering improved color rendering over HPS, finding niche adoption in ornamental flower production where visual assessment matters.
LED dominates installed base in new vertical farming construction. HPS is where replacement revenue concentrates among legacy greenhouse operators.
Application:
Capital deployment intensity separates high-automation vertical farms from seasonal supplemental lighting in traditional greenhouse operations.
- Vertical Farming:Fully enclosed multi-tier cultivation requiring sole-source lighting with precise photoperiod control and spectral recipe programming. Singapore and UAE operators deploy spectrally optimized fixtures to offset land scarcity and agricultural import dependency, commanding premium pricing for precision hardware.
- Greenhouses:Mixed natural and artificial light environments where fixtures provide supplemental radiation during winter months or cloudy periods. Belgian and Dutch clusters specify LED-optimized climate system designs that reduce HVAC refrigeration load through lower waste heat rejection.
- Agriculture:Broadacre field applications with limited penetration, primarily seedling hardening and transplant preparation in protected nursery environments.
- Horticulture:Ornamental and specialty crop production with moderate lighting intensity requirements compared to food-grade operations.
Greenhouses dominate installed base across European and North American protected cultivation. Vertical farming is climbing the fastest in capital deployment and spectral complexity requirements.
End User:
Technical sophistication and in-house agronomy capability determine whether buyers purchase hardware alone or bundled photobiology consulting services.
- Commercial Growers:Large-scale operations with dedicated procurement teams negotiating fixture purchases independently from spectral programming subscriptions. North American cannabis operators in California and Colorado cultivation facilities demand control over recipe intellectual property, driving service unbundling.
- Research Institutions:University agricultural programs requiring reproducible spectral conditions for peer-reviewed studies. Valoya and Hortilux Schréder compete through spectral recipe IP licensing that builds captive demand pipelines for photobiology-optimized fixtures.
- Home Gardeners:Small-scale residential cultivation with price-sensitive purchasing and minimal technical support requirements.
- Nurseries:Propagation-focused operations with seasonal demand patterns and lower fixture utilization rates than year-round producers.
Commercial growers dominate revenue concentration and technology adoption. Research institutions represent the steepest expansion trajectory for spectral recipe licensing and partnership-based revenue models.
Technology:
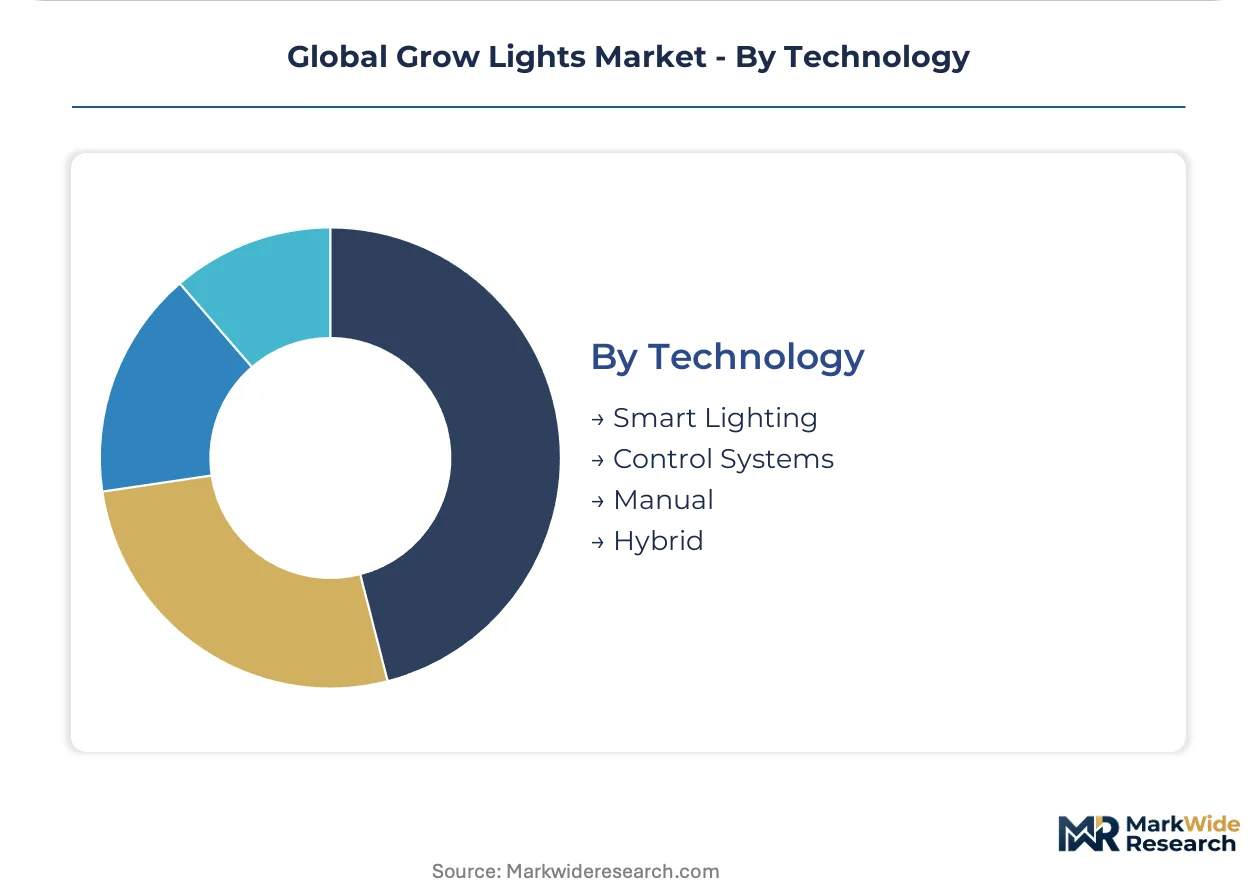
Control architecture sophistication separates programmable cultivation inputs from static hardware commodities, reshaping vendor profitability toward recurring service revenue.
- Smart Lighting:Networked fixtures with zone-level spectral tuning, cloud-based monitoring, and automated photoperiod adjustment. Dynamic LED arrays in Dutch tomato and cucumber production render obsolete capital-intensive climate infrastructure previously required for light-period control.
- Control Systems:Centralized building management integration for multi-zone cultivation facilities, requiring specialized commissioning expertise.
- Manual:Basic on-off switching and fixed spectrum output, concentrated in legacy installations and price-constrained emerging markets.
- Hybrid:Partial automation with manual override capabilities, serving transitional operators upgrading from fixed infrastructure.
Manual systems dominate legacy installed base in Southern European greenhouse clusters. Smart lighting is where vendor R&D investment and margin expansion concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers dominate LED phosphor processing and fixture assembly, concentrating upstream supply leverage while EU energy mandates reshape downstream deployment patterns across Dutch, Belgian, and Danish greenhouse clusters.
Netherlands
Commercial greenhouse operators in Westland municipality face binding EU Green Deal efficiency targets that accelerate HPS decommissioning. The national government enforces strict renewable energy quotas for agricultural electricity consumption. Dutch tomato and cucumber producers deploy tunable LED arrays to manipulate flowering photoperiods without capital-intensive shade curtain systems.
China
Domestic manufacturers scale spectrally optimized fixture production under state-backed dual carbon goals for agricultural electricity reduction. The Ministry of Ecology and Environment enforces industrial energy-intensity standards that favor LED thermal efficiency. Guangdong and Zhejiang province factories supply cost-optimized luminaires for emerging protected cultivation markets across Asia and Africa.
United States
North American cannabis operators in California and Colorado cultivation facilities negotiate fixture purchases independently from spectral programming subscriptions. The EPA Energy Star program influences procurement standards for commercial indoor cultivation environments. Michigan and Oklahoma greenhouse clusters adopt smart lighting with zone-level spectral tuning for high-value crop segments.
Spain
Almería greenhouse complexes delay LED transitions due to existing HPS ballast and reflector investments creating switching cost friction. The national climate action plan imposes gradual efficiency requirements on agricultural energy use. Andalusian tomato producers maintain technical preference for HPS uniform canopy penetration in tall vine crop architectures.
Singapore
Vertical farming operators deploy sole-source lighting to offset land scarcity and agricultural import dependency in this city-state. The national food security strategy mandates domestic production capacity targets for leafy greens and herbs. Jurong and Lim Chu Kang industrial zones host multi-tier cultivation facilities commanding premium pricing for precision hardware.
Global Grow Lights Market Vendor Landscape
Lighting conglomerates and specialized horticultural technology firms split the market between scale-driven component supply and photobiology-integrated service models. The vendor base concentrates around three strategic archetypes: diversified electronics majors with agricultural divisions, pure-play horticultural lighting specialists, and LED component manufacturers forward-integrating into finished fixtures. Consolidation pressure intensifies as spectral recipe IP becomes the primary differentiation vector, driving technology licensing agreements and research institution partnerships.
Among Dutch-anchored specialists, Gavita International B.V., Hortilux Schréder, and Signify Holding exemplify divergent competitive positioning within the premium tier. Gavita International B.V. occupies a position associated with professional greenhouse infrastructure heritage. Hortilux Schréder represents the photobiology consulting bundling archetype. Signify Holding anchors the diversified electronics major category with digital services platform capabilities. These three entities collectively illustrate how geographic clustering around Dutch greenhouse expertise correlates with distinct strategic postures in spectral optimization and service integration.
| Leading Market Players |
|---|
| Gavita International B.V. |
| Hortilux Schréder |
| Signify Holding |
| Illumitex |
| Valoya |
| ams-OSRAM AG |
| California LightWorks |
| LumiGrow Inc |
| Heliospectra |
| Others |
Supply Flow & Price Mechanics
Guangdong province LED assembly clusters concentrate phosphor processing capacity and driver electronics manufacturing, translating upstream scale into pricing leverage over European and North American fixture importers facing carbon border adjustment exposure.
Pricing Analysis
Aftermarket photobiology consulting and spectral recipe subscriptions now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium tunable systems, standard fixed-spectrum fixtures, and economy supplemental units separates vendors by control architecture sophistication. Pricing pressure stems from Chinese manufacturers scaling cost-optimized luminaires for emerging protected cultivation markets. Research institutions exhibit lowest price sensitivity due to grant-funded procurement and reproducibility requirements, while Indian polyhouse operators under national horticulture missions face acute capital constraints.
Supply Chain Analysis
Phosphor materials and rare-earth processing feed from Chinese refining capacity in Jiangxi and Inner Mongolia, with LED chip fabrication concentrated in Taiwan and South Korea. Driver electronics depend on Malaysian and Vietnamese PCB assembly, while aluminum heat sinks source from domestic extrusion across fixture manufacturing geographies. Single-source vulnerability in phosphor supply creates input cost volatility exposure. Distribution runs through greenhouse construction contractors in European clusters and direct OEM relationships in vertical farming deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as spectral recipe IP and recurring consulting contracts reshape vendor economics in controlled-environment agriculture.
For Market Incumbents: Harden spectral recipe IP portfolios through exclusive university agricultural program partnerships that build captive demand pipelines. Deepen backward integration into phosphor formulation to offset Chinese processing concentration risk. Prioritize CE marking and REACH compliance investments ahead of material substitution deadlines to compress competitor redesign cycles. For New Entrants and Emerging Players: Indian protected cultivation under national horticulture missions offers the most penetrable geography for cost-optimized supplemental lighting. Research institution partnerships provide lowest-friction entry for spectral recipe credibility. Pursue direct distribution through Maharashtra and Karnataka polyhouse contractors rather than competing for Dutch greenhouse retrofit contracts. For Investors and Strategic Acquirers: Long-term, this sits as a vertical farming infrastructure play because land-scarce city-states are mandating domestic production capacity targets that lock in sole-source lighting demand. Acquisition targets with zone-level spectral tuning software and established photobiology consulting teams command premium positioning. Watch for EU carbon border adjustment implementation on imported fixtures as inflection indicator for regional manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Spectral Recipe IP Licensing | University agricultural program partnerships build reproducible demand pipelines for photobiology-optimized fixtures. |
| Backward Integration into Phosphor Processing | Captive rare-earth processing capacity insulates margin from Chinese supply concentration volatility. |
| Smart Lighting Platform Integration | Cloud-based zone-level tuning renders obsolete capital-intensive climate infrastructure for photoperiod control. |
| Research Institution Partnership Expansion | Peer-reviewed spectral validation creates differentiation barrier against commodity fixture competitors. |
| EU Regulatory Compliance Pre-positioning | REACH-substituted driver electronics and F-Gas-aligned thermal designs compress rival product cycles. |
Methodological Framework
Initial hypotheses were tested against primary input from greenhouse operations managers, vertical farming CTOs, LED component procurement leads, and agricultural extension researchers and refined through secondary validation against EU F-Gas Regulation filings, EPA Energy Star certification databases, Chinese customs luminaire export records, and SEC 10-K disclosures from lighting conglomerates. Bottom-up fixture shipment estimates triangulated against top-down agricultural electricity consumption projections.
Demand-supply balance modeling across the analysis window incorporated product type segmentation by technology maturity, application intensity by cultivation architecture, end-user technical sophistication tiers, and control system automation levels. CAGRs derived from regression against historical retrofit cycle compression rates and EU Green Deal mandate implementation timelines. Forecast inputs included phosphor degradation curves for LED lumen maintenance and HPS decommissioning schedules under binding efficiency targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed manufacturers into European premium segments would shift outcomes beyond modeled ranges. Cross-checking against IEA agricultural electricity consumption projections and national horticulture mission budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Indoor Farming Technologies
Vertical Farming Market
Indoor Farming Technologies
Cannabis Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Lighting Market
Indoor Farming Technologies
US Vertical Farming Market
Indoor Farming Technologies
Mexico Vertical Farming Market
Indoor Farming Technologies
Vertical Farming Produce Market
Indoor Farming Technologies
Indoor Farming Market
Indoor Farming Technologies
Europe Plant Growth Chambers Market
Indoor Farming Technologies
Vertical Farming Technology Market
Indoor Farming Technologies
North America Vertical Farming Market
Indoor Farming Technologies
Global Indoor Farming Technology Market
Indoor Farming Technologies
Commercial Greenhouse Market
Indoor Farming Technologies
Europe Indoor Farming Market
Indoor Farming Technologies
Europe Grow Light Market
Indoor Farming Technologies
Smart Indoor Gardening System Market
Indoor Farming Technologies
Spain Commercial Green House Market