
 Goat Creep Feeder Market | 2026-2036
Goat Creep Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Goat Creep Feeder Market Foresight
ISO 9001 quality management certification is redrawing competitive boundaries in livestock equipment manufacturing. M-B Companies leverages its powder-coating and welding infrastructure to dominate commercial-scale metal feeder production. Priefert sustains brand loyalty through dealer networks concentrated in Oklahoma and Texas ranching corridors. Tarter Farm and Ranch Equipment anchors its position with galvanized steel fabrication capabilities that extend product lifespans in humid climates.
A goat creep feeder is a height-restricted feeding apparatus that permits young goats to access supplemental grain while excluding adult animals, typically constructed from galvanized steel, high-density polyethylene, or pressure-treated lumber with adjustable panel gaps of 15–20 centimeters. Metal feeders command the largest installed base due to durability expectations in outdoor confinement systems, while plastic feeders represent the fastest-growing category as rotational grazing operations prioritize portability and corrosion resistance. Small farmers drive volume through replacement cycles of entry-level wooden units, but commercial farms concentrate margin pools through custom-capacity orders with integrated mineral compartments.
USDA organic certification requirements restrict synthetic preservative use in wooden feeder components, redirecting material sourcing toward thermally modified lumber or recycled polymer formulations. The EPA's Clean Water Act provisions on concentrated animal feeding operations influence feeder placement protocols and waste management accessories in larger installations. State-level agricultural extension programs in Texas, Tennessee, and Pennsylvania shape producer education on creep feeding economics and equipment selection. Stakeholders must monitor evolving animal welfare audit standards from third-party certifiers and assess whether adjustable-design platforms justify premium positioning against fixed-configuration alternatives.
Market Dynamics
Commercial goat dairies in Texas and Pennsylvania are consolidating feeding infrastructure around automated systems that synchronize creep feeding with herd management software, compressing replacement cycles for legacy wooden units and elevating specifications for corrosion-resistant materials.
Growth Catalysts
- USDA Organic Livestock Standards:Certification requirements for synthetic-free feed systems are redirecting material sourcing toward thermally modified lumber and recycled polymers in Pennsylvania and Tennessee dairy clusters.
- Rotational Grazing Incentives:State agricultural extension programs in Texas are subsidizing portable feeder purchases, accelerating polyethylene unit adoption among pasture-based operations.
- Labor Efficiency Mandates:Commercial farms exceeding 500 head are automating creep feeding stations to reduce manual grain distribution hours and improve kid survival metrics.
Market Restraints
- Galvanized Steel Price Volatility:Zinc input cost swings are compressing margins for metal feeder manufacturers serving humid climate installations in the Southeast.
- Wooden Component Supply Concentration:Thermally modified lumber sourcing depends on a limited base of certified treatment facilities concentrated in the Great Lakes region.
- EPA Concentrated Animal Feeding Operation Permitting:Feeder placement protocols and waste management accessory requirements add compliance friction for operations exceeding 1,000 animal units.
Strategic Opportunities
- Appalachian Goat Dairy Expansion:Underpenetrated counties in West Virginia and eastern Kentucky present white space for integrated feeder-mineral station bundles.
- Telematics Convergence:RFID-enabled creep gates combined with cloud-based intake monitoring are opening premium pricing tiers among tech-adopting commercial herds.
- USDA Rural Energy for America Program:REAP grants covering 25% of equipment costs for energy-efficient feeding systems are accelerating replacement demand in qualifying counties.
Industry Challenges
- Welding Certification Bottlenecks:AWS-certified aluminum welders capable of portable feeder fabrication remain scarce in rural manufacturing corridors.
- Third-Party Animal Welfare Audit Alignment:Feeder designs must simultaneously satisfy overlapping standards from Certified Humane, American Grassfed Association, and individual processor protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goat Creep Feeder Market |
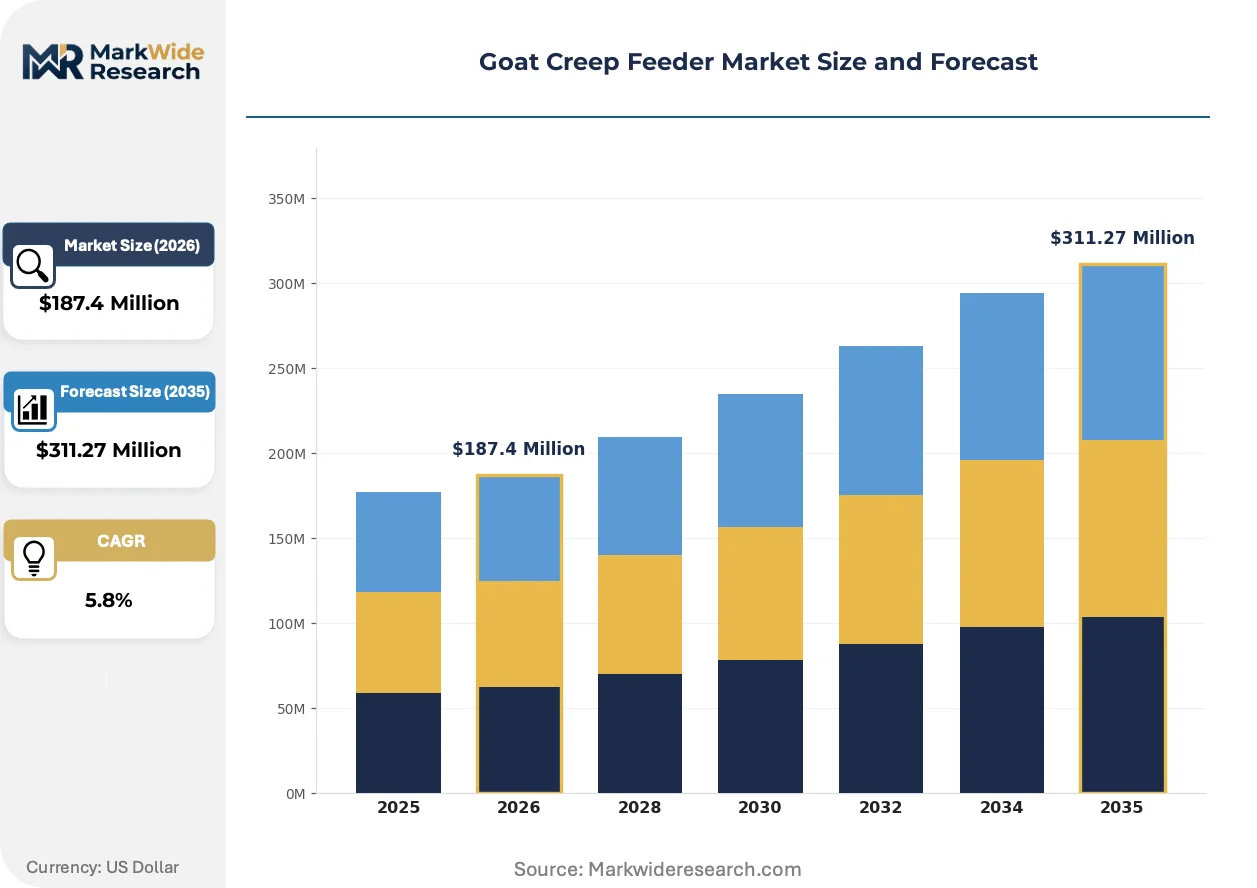
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Feeders, Metal Feeders, Plastic Feeders, Modular Feeders Design: Open Design, Closed Design, Adjustable Design, Portable Design Capacity: Small Capacity, Medium Capacity, Large Capacity, Custom Capacity End User: Small Farmers, Commercial Farms, Ranchers, Agricultural Cooperatives |
| Companies Covered | M-B Companies, Priefert, Tarter Farm and Ranch Equipment, Powder River, High Country Plastics, Behlen Country, Sioux Steel Company, Big Dutchman, Farmco Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goat Creep Feeder Market Shifts & Advancements
Feeder engineering is pivoting toward modularity and sensor integration as commercial herds demand equipment that adapts to shifting flock demographics and integrates with broader farm management platforms.
Solar-powered automated creep gates with adjustable height sensors are miniaturizing control hardware to withstand pasture conditions without external power infrastructure. Mid-scale dairies in Texas Hill Country are piloting these units at replacement rates twice the industry average. This technology is miniaturizing the capital threshold for automated feeding, enabling 200-head operations to access capabilities previously reserved for 1,000-head facilities.
EPA Clean Water Act provisions on nutrient management are forcing concentrated operations to reposition feeders away from riparian zones and install catchment accessories. Facilities in the Chesapeake Bay watershed face the strictest placement protocols. Metal feeder manufacturers are responding with integrated trough designs that simplify manure collection compliance.
Direct procurement from manufacturer websites is displacing traditional agricultural supply house channels for standard-capacity units. Younger operators in Tennessee and Virginia are bypassing dealer networks entirely, compressing price transparency and compressing regional distributor margins. This channel rotation is most pronounced among farms under 100 head purchasing replacement polyethylene feeders.
Goat Creep Feeder Market Segmentation
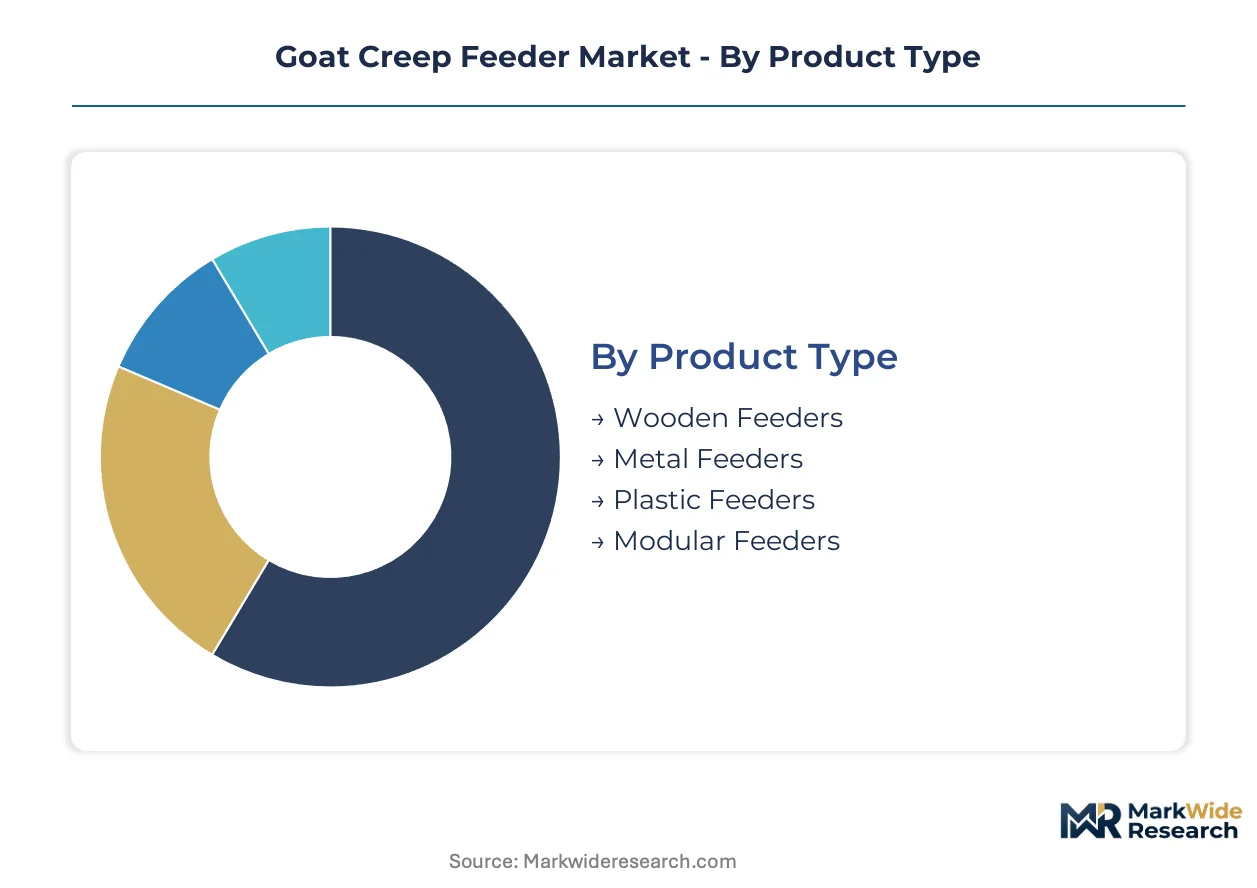
Goat creep feeder purchasing decisions fragment across material durability expectations, mobility requirements, and scale economics. Each segmentation dimension reveals distinct margin concentration points and technology adoption patterns that shape manufacturer positioning strategies.
Product Type:
Metal feeders capture the largest installed base revenue pools, while plastic units concentrate the fastest margin expansion as rotational grazing operations prioritize field portability.
- Metal Feeders:Galvanized steel construction dominates outdoor confinement installations across Texas hill country and humid Southeast climates. Commercial dairies in Pennsylvania and Tennessee specify metal units for 10-15 year replacement cycles despite zinc price volatility compressing manufacturer margins.
- Plastic Feeders:High-density polyethylene formulations deliver corrosion resistance and sub-50-pound field mobility. Pasture-based operations in USDA-subsidized Texas extension districts are displacing wooden units at twice the regional replacement rate.
- Wooden Feeders:Pressure-treated lumber entry points serve small farmers in Appalachian clusters with sub-$500 replacement economics.
- Modular Feeders:Interchangeable panel systems allow capacity scaling without full unit replacement, concentrating in custom orders from 500-head commercial herds.
The dominant share belongs to Metal Feeders, while Plastic Feeders is closing the gap fastest.
Design:
Configuration choices reflect trade-offs between predator protection, labor efficiency, and capital deployment flexibility across operation scales.
- Adjustable Design:Height-variable creep gates with 15-20 centimeter panel gaps accommodate kid growth stages without equipment swaps. Texas commercial dairies integrating these units with herd management software are compressing wooden feeder replacement cycles.
- Portable Design:Lightweight frame construction enables rotational grazing compliance without permanent pad installation. Appalachian pasture operations in West Virginia and eastern Kentucky specify these for REAP grant-eligible equipment bundles.
- Open Design:Three-sided access maximizes kid throughput in protected barn environments, concentrating in small-farm dairy clusters.
- Closed Design:Fully enclosed construction with roof assemblies serves predator-dense regions and extends feed protection in exposed pasture systems.
Adjustable Design holds the revenue concentration, though Portable Design is expanding most quickly among subsidized grazing operations.
Capacity:
Volume specifications directly correlate with automation integration depth and mineral compartment bundling rates.
- Custom Capacity:Built-to-specification units with integrated mineral stations and RFID-enabled intake monitoring command premium positioning. Commercial farms exceeding 500 head in Texas and Pennsylvania concentrate orders here, synchronizing creep feeding with automated grain distribution systems.
- Large Capacity:50-plus head simultaneous access designs serve concentrated animal feeding operations navigating EPA Clean Water Act placement protocols.
- Small Capacity:10-15 head units dominate replacement cycles among under-100-head operations purchasing through direct manufacturer channels.
- Medium Capacity:20-40 head configurations bridge entry-level and commercial specifications, capturing volume in Tennessee and Virginia agricultural cooperative purchasing.
Custom Capacity commands the margin pool, while Large Capacity is gaining share fastest among consolidating commercial dairies.
End User:
Customer type determines channel structure, with direct procurement displacing dealer networks below 100-head scale.
- Commercial Farms:Operations exceeding 500 head drive specification elevation toward corrosion-resistant materials and cloud-integrated monitoring. These buyers compress replacement cycles for legacy wooden units while demanding AWS-certified welding quality in aluminum portable fabrication.
- Small Farmers:Under-100-head operations in Tennessee and Virginia bypass agricultural supply houses entirely for standard polyethylene units, collapsing regional distributor margins through manufacturer website direct procurement.
- Ranchers:Mixed livestock operations prioritize multi-species creep gate compatibility, concentrating demand in Oklahoma and Texas ranching corridors.
- Agricultural Cooperatives:Pooled purchasing vehicles aggregate medium-capacity orders for member farms, shaping volume pricing in Pennsylvania dairy clusters.
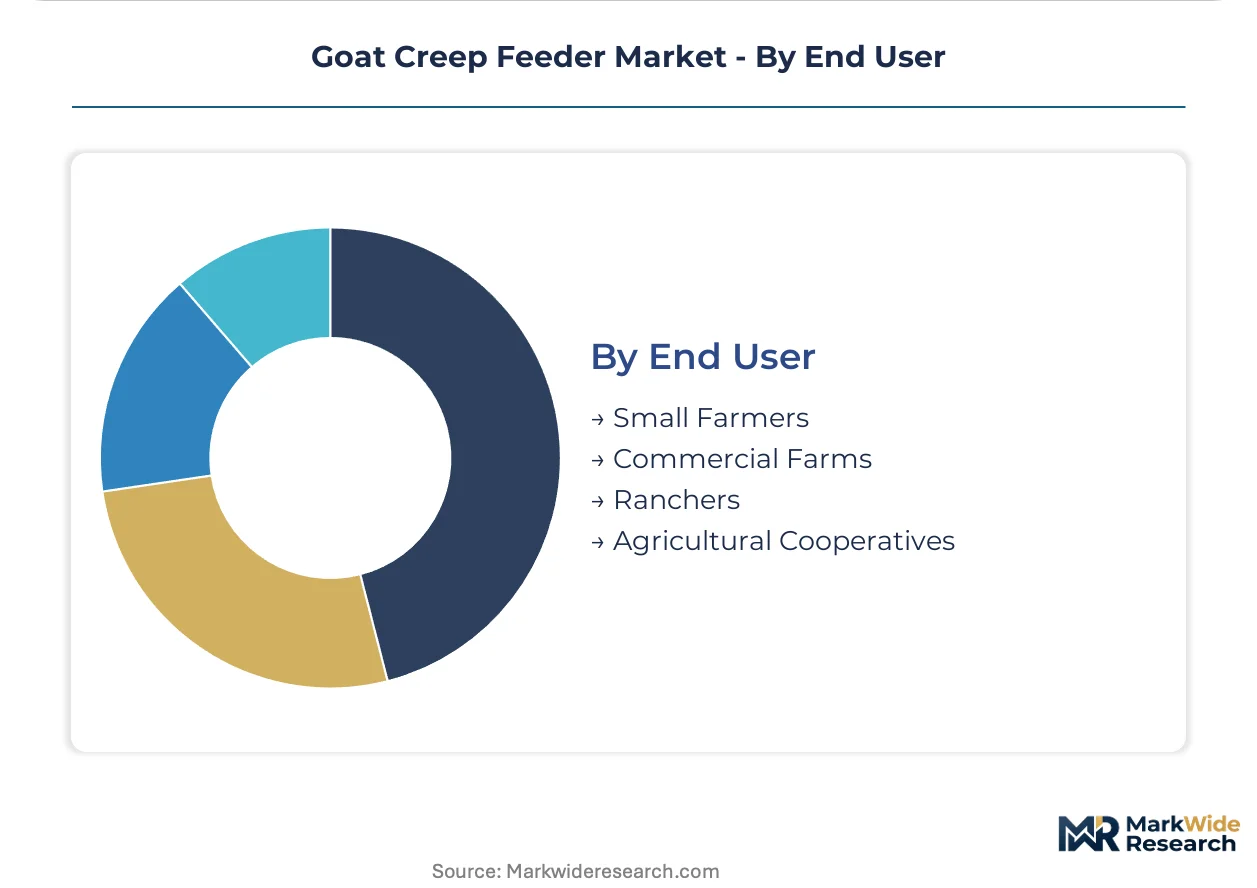
Commercial Farms anchor the revenue base, though Small Farmers is climbing the fastest as direct channels democratize equipment access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's container throughput underwrites Texas hill country's dominance in livestock equipment distribution, while Appalachian rail corridors feed Pennsylvania and Tennessee dairy clusters. Interstate highway density and USDA extension office networks shape regional adoption velocity.
United States
Texas hill country and Appalachian goat dairy clusters concentrate commercial-scale demand for automated creep feeding infrastructure. USDA Rural Energy for America Program grants covering 25% of equipment costs accelerate replacement cycles in qualifying counties. Pennsylvania's Lancaster County and Tennessee's Cookeville region anchor metal feeder fabrication capacity.
Canada
Ontario's Golden Horseshoe and Alberta's livestock corridors drive specification elevation toward corrosion-resistant polyethylene units. Health Canada veterinary biologics regulations influence feeder hygiene protocols in provincial dairy operations. Quebec's Montérégie region concentrates small-farm adoption through agricultural cooperative purchasing.
Australia
Victoria's Gippsland and New South Wales' Hunter Valley sustain pasture-based rotational grazing demand for portable feeder designs. The country's national agricultural regulator enforces strict biosecurity standards on imported livestock equipment. Queensland's Darling Downs region pilots solar-powered automated creep gates at replacement rates above national averages.
Germany
Bavaria's dairy cooperatives and Lower Saxony's livestock research stations drive precision feeding technology adoption. EU Green Deal agricultural sustainability requirements redirect material sourcing toward recycled polymer formulations. Baden-Württemberg's equipment manufacturers supply modular feeder systems across Central European goat operations.
France
Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur sustain Mediterranean goat cheese production demand for adjustable-design creep feeders. ECHA REACH regulations govern chemical treatment standards for wooden feeder components. Île-de-France's agricultural technology distributors channel French-speaking African export demand.
Goat Creep Feeder Market Competitive Landscape
Listed leaders compete with private specialists across welding certification and powder-coating capabilities. The vendor base stratifies into three tiers: integrated metal fabricators with captive galvanizing capacity, regional specialists in rotational-molded polyethylene, and diversified agricultural equipment conglomerates. Strategic archetypes include corrosion-resistant material specialists, automation-integrated system providers, and direct-to-farm digital distributors. Capacity expansion and USDA compliance certification represent the dominant competitive moves.
Among North American metal fabricators, M-B Companies and Priefert exemplify scale-driven manufacturing archetypes, while Tarter Farm and Ranch Equipment occupies a position within galvanized steel durability specialists. These three anchors represent distinct geographic clustering patterns—Midwest powder-coating infrastructure, Oklahoma-Texas dealer network density, and humid-climate product lifespan engineering.
| Leading Market Players |
|---|
| M-B Companies |
| Priefert |
| Tarter Farm and Ranch Equipment |
| Powder River |
| High Country Plastics |
| Behlen Country |
| Sioux Steel Company |
| Big Dutchman |
| Farmco Manufacturing |
| Others |
Supply & Pricing Matrix
High-density polyethylene's displacement of pressure-treated lumber in rotational grazing applications simultaneously redraws supply geography toward Gulf Coast petrochemical corridors and compresses price premiums previously commanded by thermally modified wood specialists.
Pricing Analysis
Volume-discount tiering structures separate custom-capacity orders with integrated mineral stations from standard polyethylene units and entry-level wooden configurations. Price differentiation hinges on corrosion-resistance certification tiers and AWS welding quality standards in metal fabrication. Pricing pressure stems from zinc input volatility compressing margins for galvanized steel manufacturers serving humid Southeast climates. Small farmers under 100 head exhibit highest price sensitivity, while commercial dairies exceeding 500 head prioritize automation integration over unit cost.
Supply Chain Analysis
Pennsylvania and Tennessee anchor domestic metal feeder fabrication capacity, while Texas hill country distribution clusters feed Southwest demand. Raw material flows draw from Great Lakes thermally modified lumber facilities, Gulf Coast polyethylene resin production, and domestic zinc galvanizing operations. Supply chain risk centers on single-source vulnerability for certified aluminum welding talent in rural manufacturing corridors. Distribution runs through agricultural supply houses for commercial accounts and direct manufacturer websites for sub-100-head operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Goat creep feeder penetration sits at early-cycle expansion, with USDA Rural Energy for America Program subsidies accelerating replacement demand in qualifying counties.
For Market Incumbents: Fortify dealer network control in Oklahoma-Texas ranching corridors against direct-to-farm digital disintermediation. Invest in captive powder-coating capacity to offset zinc price volatility compressing metal feeder margins. Prioritize ISO 9001 certification maintenance as competitive boundaries harden around quality management systems.
For New Entrants and Emerging Players: USDA organic certification fast-tracks open white space in Appalachian dairy clusters lacking integrated feeder-mineral station bundles. Target West Virginia and eastern Kentucky pasture operations with REAP grant-eligible portable designs. Pursue telematics convergence partnerships to bypass capital-intensive fabrication infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metal fabrication specialists holding captive galvanizing capacity but lacking software integration capabilities. Five-to-ten-year viability favors corrosion-resistant material specialists over wooden component legacy players. Watch RFID-enabled intake monitoring adoption rates as consolidation inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | RFID-enabled creep gates with cloud monitoring open premium pricing tiers among tech-adopting Texas commercial dairies. |
| REAP Grant Certification Pathway | USDA Rural Energy for America Program qualification accelerates replacement demand in subsidized extension districts. |
| Corrosion-Resistant Material Expansion | High-density polyethylene formulation investments capture rotational grazing prioritization of field portability. |
| AWS Welding Certification Program | Certified aluminum fabrication capacity addresses scarcity constraining portable feeder production in rural corridors. |
| Direct-to-Farm Digital Channel | Manufacturer website procurement captures price-transparent small farmers bypassing traditional agricultural supply houses. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment manufacturing executives, USDA extension program coordinators, and commercial dairy operations managers; and secondary validation against EPA Clean Water Act regulatory filings, state agricultural subsidy disbursement records, and livestock equipment trade association shipment data. Bottom-up unit economics triangulated against top-down market sizing across material type, design configuration, and capacity tier segmentation dimensions.
The forecast boundary spans the full projection horizon without interim year specificity. The analytical framework models demand across product type, design architecture, capacity specification, and end-user scale dimensions. CAGRs derive from replacement cycle compression rates and subsidy-driven adoption velocity. Industry-specific inputs include zinc price volatility indices and rotational grazing incentive program enrollment trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained USDA program funding and stable galvanized steel input costs; material deviation would warrant model refresh. Recalibration cycles align with material shifts in EPA permitting thresholds and third-party animal welfare audit standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Hog Feeder Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Livestock Trailers Market