
 Gulf Cooperation Council Frozen Bakery Products Market | 2026-2036
Gulf Cooperation Council Frozen Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Cooperation Council Frozen Bakery Products Market Foresight
SFDA's tightened frozen food labeling requirements is pivoting the cost-of-entry calculus toward manufacturers with in-house regulatory compliance teams. Sunbulah Group leverages its Saudi manufacturing footprint to navigate certification demands without third-party dependency. Almarai Company sustains refrigerated distribution dominance through controlled cold-chain assets spanning Riyadh, Jeddah, and Dammam. Aryzta AG competes on European formulation expertise adapted to Gulf halal specifications, occupying premium hotel and airline catering channels.
Frozen bakery products comprise dough, partially baked, and fully baked items preserved at sub-zero temperatures to extend shelf life while retaining sensory and nutritional properties; blast freezing at minus thirty-five to minus forty degrees Celsius arrests starch retrogradation and preserves crust texture for institutional reheating. Bread and pastries lead product-type volume due to daily consumption frequency in Gulf hospitality and foodservice, while pizza registers the fastest growth trajectory aligned with quick-service restaurant expansion. Restaurants and cafes anchor end-user demand, though online distribution channels are capturing incremental share as delivery platforms consolidate procurement.
SFDA, UAE's Ministry of Climate Change and Environment, and GCC Standardization Organization frameworks collectively govern ingredient sourcing, halal certification, and cold-chain integrity across member states. These standards shape demand by disqualifying non-compliant imports and rewarding local production with faster customs clearance. Stakeholders must monitor evolving shelf-life disclosure mandates and carbon-footprint reporting requirements that will reshape supplier qualification criteria.
Market Dynamics
SFDA's shelf-life disclosure mandates and the UAE's Ministry of Climate Change and Environment cold-chain integrity rules are compressing margins for non-compliant importers while rewarding domestic manufacturers with faster customs clearance and institutional procurement access.
Growth Catalysts
- Quick-service restaurant procurement scaling:Saudi Arabia and UAE-based QSR chains are expanding frozen pastry volumes to reduce kitchen labor and standardize output quality across franchise networks.
- Halal certification standardization:GCC Standardization Organization frameworks are creating regulatory clarity that accelerates cross-border product flows between member states.
- Blast freezing at minus thirty-five to minus forty degrees Celsius:This temperature threshold arrests starch retrogradation and preserves crust texture, enabling institutional reheating without sensory degradation.
Market Restraints
- Energy input cost volatility:Diesel and electricity price fluctuations in Saudi Arabia and Kuwait directly compress cold-chain operating margins for distributors maintaining sub-zero logistics.
- Supply concentration in European formulation expertise:Premium hotel and airline catering channels depend on imported European halal-adapted formulations, creating currency and lead-time exposure.
- Shelf-life disclosure compliance friction:SFDA's updated labeling rules impose documentation burdens that smaller importers struggle to satisfy without dedicated regulatory staff.
Strategic Opportunities
- Bahrain and Oman underpenetration:These smaller GCC markets show lower frozen bakery penetration in foodservice, presenting first-mover expansion potential for compliant manufacturers.
- Online distribution channel consolidation:Delivery platform procurement aggregation is capturing incremental share from traditional foodservice distributors in Dubai and Abu Dhabi.
- Carbon-footprint reporting preparation:Anticipated GCC-wide environmental disclosure requirements will reward early adopters with preferred supplier status in government and institutional tenders.
Industry Challenges
- Cold-chain technician skill scarcity:Qualified personnel for maintaining blast freezing equipment and refrigerated transport are in short supply across Saudi Arabia's secondary cities.
- Halal certification timeline compression:Multiple overlapping approvals from national religious authorities and the GCC Standardization Organization extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Cooperation Council Frozen Bakery Products Market |
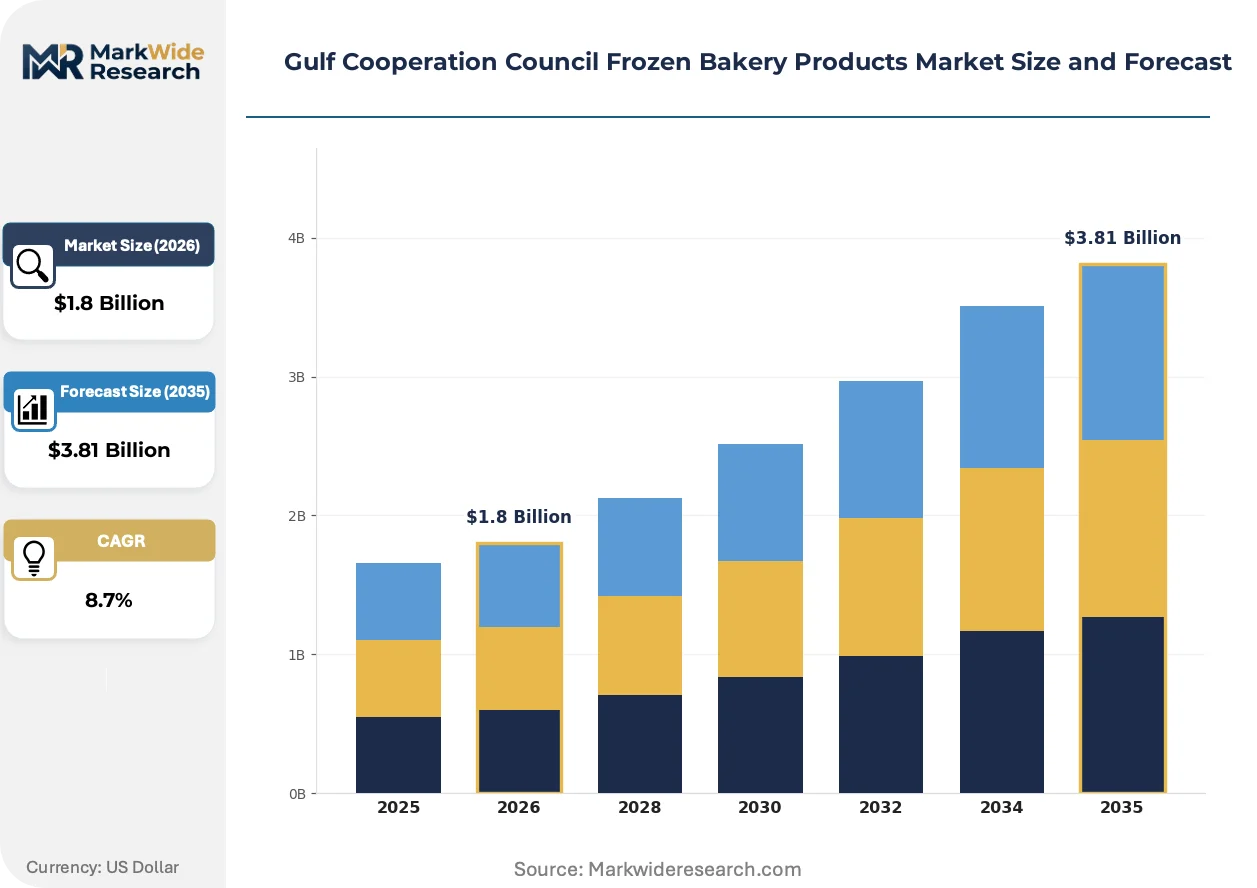
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Pizza End User: Restaurants, Cafes, Retailers, Catering Services Packaging Type: Bags, Boxes, Trays, Pouches Distribution Channel: Supermarkets, Online, Wholesale, Convenience Stores |
| Companies Covered | Sunbulah Group, Almarai Company, IFFCO, Aryzta AG, Dawn Food Products, Inc., Switz Group, Agthia Group, Americana Group Inc., General Mills, Inc., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Cooperation Council Frozen Bakery Products Market Shifts & Advancements
Automation in production and logistics, tightening regulatory disclosure requirements, and the consolidation of procurement through digital platforms are restructuring competitive advantage in Gulf frozen bakery supply.
Robotic dough portioning and automated blast freezing lines are automating labor-intensive production steps previously dependent on manual intervention. Saudi manufacturers with capital access are deploying these systems to reduce per-unit labor costs and achieve batch consistency that satisfies QSR franchise specifications. This automation is compressing the cost advantage previously held by low-wage manual production in competing supply bases.
SFDA's enforcement of updated food labeling and shelf-life disclosure rules is elevating compliance costs and disqualifying non-compliant imports from institutional procurement channels. The industrial consequence is a pivot toward manufacturers with in-house regulatory teams capable of navigating certification without third-party dependency. Saudi Arabia's domestic producers are responding fastest, leveraging local manufacturing footprints to accelerate approval timelines.
Hotel and catering procurement in Dubai and Abu Dhabi is consolidating through digital platform aggregation that disintermediates traditional distributor relationships. Large hospitality groups are shifting toward direct manufacturer contracts with volume commitments and specification standardization. This behavioral shift is most visible in the UAE's premium hotel corridor, where procurement centralization is compressing supplier counts and rewarding scale-capable manufacturers.
Gulf Cooperation Council Frozen Bakery Products Market Segmentation
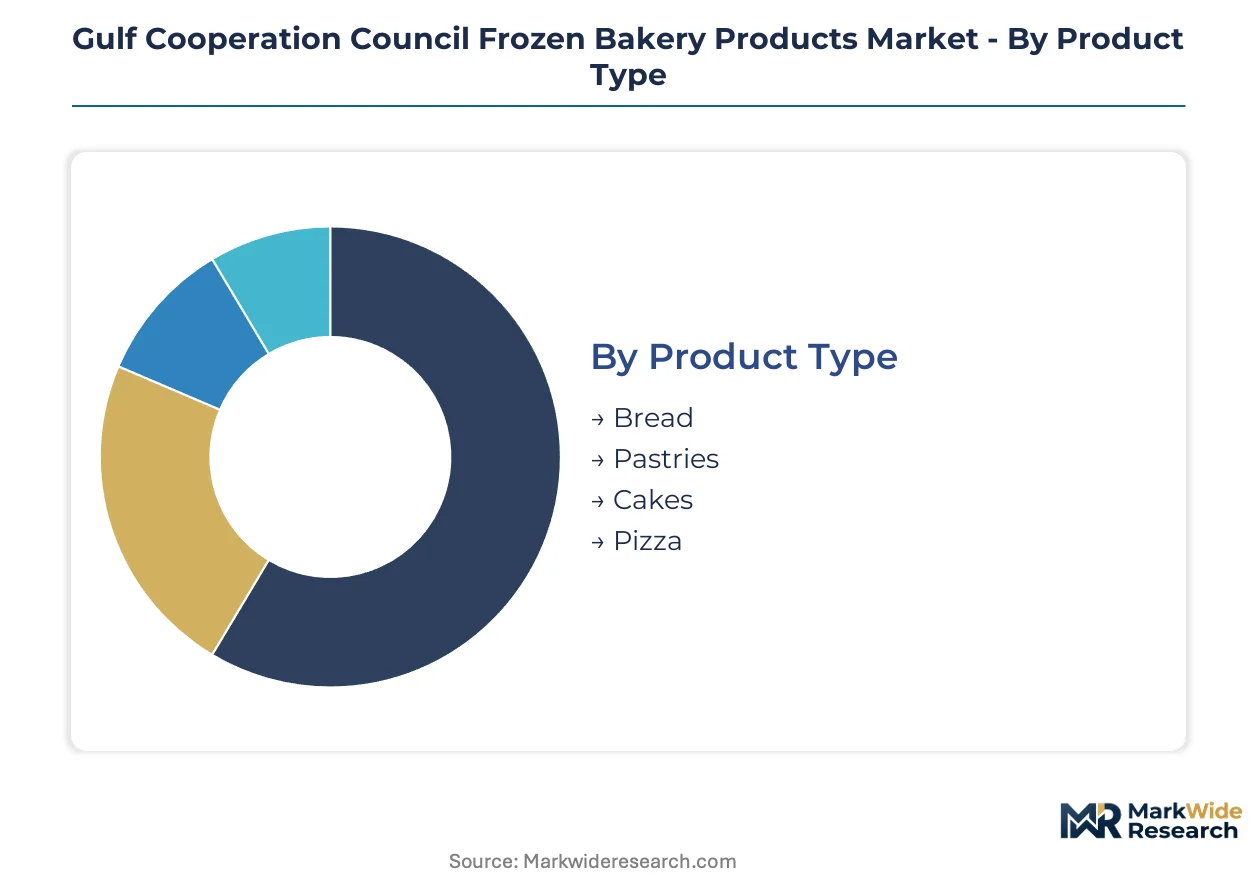
Frozen bakery procurement across the Gulf Cooperation Council stratifies sharply by production technology requirements and end-use temperature protocols. Capital deployment patterns reveal which segments reward scale economies and which remain accessible to mid-size entrants.
Product Type:
Blast freezing infrastructure and dough conditioning equipment represent the dominant capital outlays, with temperature precision requirements varying substantially across product categories.
- Bread:Frozen loaves and rolls require controlled thaw-and-serve systems that preserve crust integrity through the starch retrogradation threshold. Saudi quick-service restaurants and UAE hotel breakfast operations concentrate procurement volumes here, driven by labor reduction targets in high-turnover kitchen environments.
- Pastries:Croissants, Danish, and laminated doughs demand specialized sheeting and blast freezing lines to maintain butter layer separation. Dubai and Abu Dhabi catering channels absorb the majority of Gulf pastry volumes, with procurement centralization rewarding manufacturers holding GCC-wide halal certification.
- Cakes:Frozen layer cakes and dessert portions target institutional foodservice with extended ambient display tolerance after thawing.
- Pizza:Frozen pizza bases and topped products serve the expanding QSR delivery segment across Saudi Arabia's Riyadh-Jeddah corridor.
Most installed capacity flows through Bread. Expansion is steepest in Pizza.
End User:
Customer procurement scale and specification stringency separate segments by margin profile and contract duration.
- Restaurants:Full-service dining operations specify frozen bakery for menu consistency across franchise locations, with procurement volumes tied to seating capacity and table turnover rates. Saudi Arabia's Riyadh and Jeddah restaurant clusters drive regional demand concentration, constrained by SFDA shelf-life disclosure documentation requirements.
- Catering Services:Hotel and airline caterers impose the most rigorous halal traceability and batch-lot documentation standards. Dubai's premium hospitality procurement aggregates through centralized purchasing platforms, displacing traditional distributor relationships.
- Cafes:Coffee-focused operations prioritize pastry SKUs with rapid thaw-and-serve characteristics for display case rotation.
- Retailers:Supermarket and hypermarket frozen aisles stock consumer-format products with extended home-freezer tolerance.
Margin concentration sits with Catering Services. Volume expansion runs through Restaurants.
Packaging Type:
Packaging capital intensity clusters around barrier film extrusion and modified atmosphere sealing equipment.
- Trays:Rigid thermoformed containers protect layered and decorated products through distribution handling, absorbing the highest per-unit packaging cost in the category.
- Boxes:Corrugated and folding carton formats dominate pizza and cake transport, with printing customization supporting brand differentiation in retail channels.
- Bags:Flexible polyethylene and polypropylene formats serve bread and roll products with cost-minimized material profiles.
- Pouches:Stand-up and flat pouch configurations target single-serve pastry portions for convenience retail.
Equipment utilization peaks with Trays. Material cost pressure concentrates on Bags.
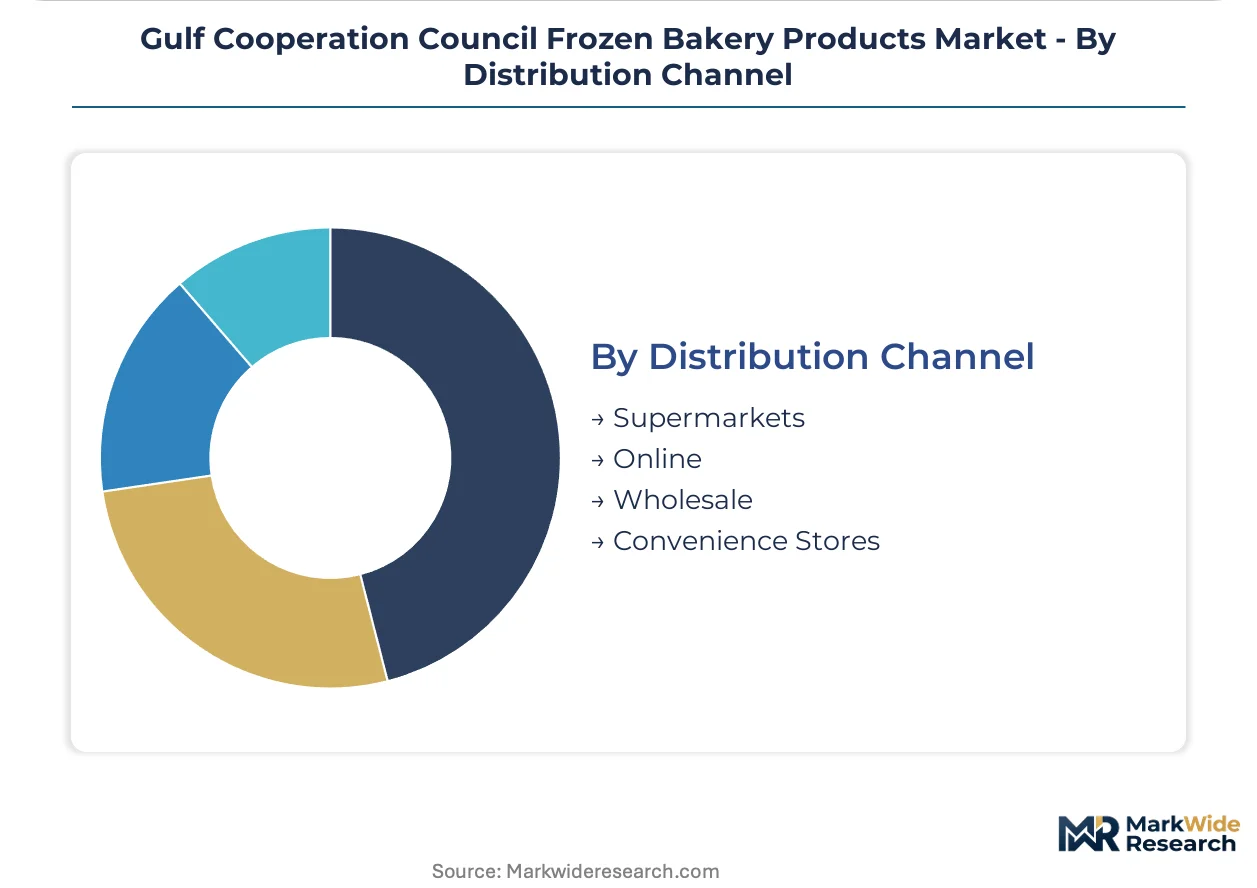
Distribution Channel:
Cold-chain asset requirements and inventory velocity separate channel economics.
- Wholesale:Foodservice distributors maintaining sub-zero warehouse and fleet infrastructure capture institutional procurement volumes across Saudi Arabia's secondary cities. Diesel and electricity price volatility in the Kingdom directly compress operating margins for these operators.
- Online:Delivery platform procurement aggregation is consolidating restaurant supply relationships in Dubai and Abu Dhabi, with volume commitments displacing traditional distributor intermediaries.
- Supermarkets:Retail freezer case space allocation determines SKU survival, with private-label penetration rising in UAE hypermarket chains.
- Convenience Stores:Limited freezer capacity restricts assortment breadth to high-velocity bread and pastry items.
Revenue concentration rests with Wholesale. Digital capture rates climb fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled cold-chain technicians and blast freezing equipment operators concentrate in Saudi Arabia's Riyadh-Jeddah corridor and the UAE's Dubai-Abu Dhabi axis, anchoring the Gulf's frozen bakery production capacity.
Saudi Arabia
Quick-service restaurant chains across Riyadh and Jeddah are scaling frozen pastry procurement to reduce kitchen labor costs. SFDA's updated shelf-life disclosure mandates are compressing margins for smaller importers lacking dedicated regulatory staff. The Eastern Province's Dammam industrial cluster hosts domestic manufacturers leveraging local production footprints to accelerate certification timelines.
United Arab Emirates
Dubai's hotel and catering procurement volumes outpace other Gulf cities, with centralized purchasing platforms disintermediating traditional distributor relationships. The Ministry of Climate Change and Environment enforces cold-chain integrity rules that reward compliant manufacturers with faster customs clearance. Abu Dhabi's hospitality corridor is consolidating supplier counts through direct manufacturer contracts with volume commitments.
Kuwait
Diesel and electricity price volatility directly compresses cold-chain operating margins for distributors maintaining sub-zero logistics. The country's national food safety regulator aligns with GCC Standardization Organization frameworks for halal certification standardization. Kuwait City's foodservice distribution hub faces margin pressure from energy input cost fluctuations affecting refrigerated transport fleets.
Qatar
Airline catering procurement imposes rigorous halal traceability and batch-lot documentation standards for frozen bakery suppliers. The Qatar General Organization for Standardization coordinates with GCC frameworks to accelerate cross-border product flows. Doha's premium hospitality sector concentrates procurement through centralized platforms similar to Dubai's model.
Bahrain
Lower frozen bakery penetration in foodservice presents first-mover expansion potential for compliant manufacturers with GCC-wide certification. The national standards body implements GCC Standardization Organization halal frameworks to reduce import friction. Manama's hospitality sector remains underdeveloped relative to Riyadh and Dubai, creating whitespace for scale-capable entrants.
Gulf Cooperation Council Frozen Bakery Products Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Gulf frozen bakery supply base, creating a tiered structure where scale advantages separate institutional procurement winners from marginal players. Domestic Saudi and UAE-based manufacturers leverage regulatory compliance speed against European formulation specialists competing on premium channel access. Three archetypes dominate: vertically integrated food conglomerates with captive distribution, European-origin specialists with halal-adapted product lines, and regional pure-plays with GCC-wide certification coverage. Competitive moves concentrate on backward integration into blast freezing capacity and strategic partnerships with QSR franchise networks.
Among Saudi-based diversified food groups, Sunbulah Group and Almarai Company occupy positions anchored by controlled cold-chain assets spanning Riyadh, Jeddah, and Dammam. Aryzta AG represents the European specialist archetype, with its positioning shaped by formulation expertise adapted to Gulf halal specifications. These three exemplify the competitive tension between domestic regulatory speed and imported technical sophistication.
| Leading Market Players |
|---|
| Sunbulah Group |
| Almarai Company |
| IFFCO |
| Aryzta AG |
| Dawn Food Products, Inc. |
| Switz Group |
| Agthia Group |
| Americana Group Inc. |
| General Mills, Inc. |
| Others |
Supply & Pricing Matrix
Blast freezing automation across Saudi Arabia's Riyadh-Jeddah corridor is compressing per-unit labor costs while simultaneously concentrating production capacity among manufacturers with capital access, reshaping both cost economics and supplier market power in institutional procurement channels.
Pricing Analysis
Service bundling separates frozen bakery procurement into unbundled product-only contracts versus bundled cold-chain logistics agreements. Three-tier pricing structure across premium hotel-grade, standard foodservice, and economy QSR levels reflects halal certification grade and blast freezing temperature precision. Cost compression in the economy tier is intensifying because diesel and electricity volatility in Saudi Arabia and Kuwait squeezes distributor margins. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement and franchise-standardized specifications, while airline catering channels accept premium pricing for batch-lot traceability documentation.
Supply Chain Analysis
Direct-to-hospitality channels handle premium Dubai and Abu Dhabi hotel procurement through centralized purchasing platforms that disintermediates traditional wholesale distributors. Supply concentrates in Saudi Arabia, the UAE, and European formulation specialists supplying halal-adapted premium channels. Raw material flows draw from wheat and butter commodities, specialized laminated dough ingredients, and blast freezing equipment components. Single-source vulnerability sits with European formulation expertise for premium hotel and airline catering segments. Distribution runs through wholesale foodservice networks with sub-zero warehouse infrastructure across Saudi secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gulf Cooperation Council frozen bakery market functions as a stable compounder anchored by quick-service restaurant procurement scaling that generates recurring volume commitments across franchise networks.
For Market Incumbents: Lock in QSR franchise relationships through long-term supply agreements with volume commitments and specification standardization. Deepen backward integration into blast freezing capacity to reduce third-party cold-chain dependency. SFDA's tightening shelf-life disclosure mandates threaten smaller importers, creating acquisition opportunities for compliant domestic manufacturers with in-house regulatory teams. For New Entrants and Emerging Players: Begin with Bahrain and Oman foodservice channels where frozen bakery penetration remains underdeveloped relative to Saudi Arabia and the UAE. Target compliant manufacturers with GCC-wide halal certification to accelerate market entry timelines. Pursue direct-to-hospitality contracts in Manama's emerging hospitality sector before wholesale distributor relationships crystallize. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size Saudi manufacturers with local production footprints and incomplete cold-chain asset coverage. The five-to-ten year viability thesis rests on automation-driven margin expansion and regulatory compliance barriers protecting domestic incumbents. Monitor SFDA enforcement intensity as the inflection signal for import displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Blast Freezing Capacity Expansion | Captures QSR franchise standardization contracts requiring minus-thirty-five degree Celsius precision. |
| Backward Integration into Cold-Chain Logistics | Reduces diesel and electricity cost exposure for Saudi distributors operating refrigerated fleets. |
| GCC-Wide Halal Certification Investment | Accelerates customs clearance across member states under Standardization Organization frameworks. |
| Direct Manufacturer-Hospitality Contracts | Displaces traditional wholesale intermediaries in Dubai's centralized procurement platforms. |
| Automation of Dough Portioning Lines | Achieves batch consistency that satisfies quick-service restaurant franchise specifications. |
Research Methodology
Multiple input streams — primary interviews with frozen bakery procurement directors, secondary validation through SFDA regulatory filings and GCC trade customs data, and operational metrics from cold-chain logistics operators — were reconciled to construct segment-level demand estimates. Stakeholder consultations included quick-service restaurant supply chain managers, hotel catering procurement leads, blast freezing equipment technicians, and wholesale foodservice distributors. Secondary sources comprised Saudi Food and Drug Authority disclosure requirements, UAE Ministry of Climate Change and Environment cold-chain regulations, and foodservice distributor operational filings. Bottom-up product-type volume builds and top-down regional demand aggregates were cross-validated through triangulation.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to derive value and volume trajectories. Segmentation dimensions modeled include product type, end-user category, packaging format, and distribution channel, with additional granularity on blast freezing temperature protocol tiers. CAGRs were computed from fitted trend lines across the analysis window, incorporating QSR expansion rates, hotel construction pipelines, and regulatory compliance cost inflation as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt SFDA regulatory reversals, sustained energy price spikes beyond historical volatility bands, and geopolitical disruptions to European formulation supply routes. Forecasts reflect documented assumptions regarding QSR franchise rollout timelines and automation adoption curves. Periodic stress-testing of base assumptions is recommended given regulatory disclosure mandate evolution and carbon-footprint reporting preparation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
United States Bread Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Muffins Market
Bakery Products
Toasted Flour Market
Bakery Products
Cake Base Discs Market
Bakery Products
Pastry Margarine Market
Bakery Products
Teaseed Cake Market
Bakery Products
Packaged Bread Market
Bakery Products
Bread Crumbs Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Flatbread Market