
 Pancakes Market | 2026-2036
Pancakes Market Size, Share, and Industry Trends Forecast 2026-2036
Pancakes Market Analysis
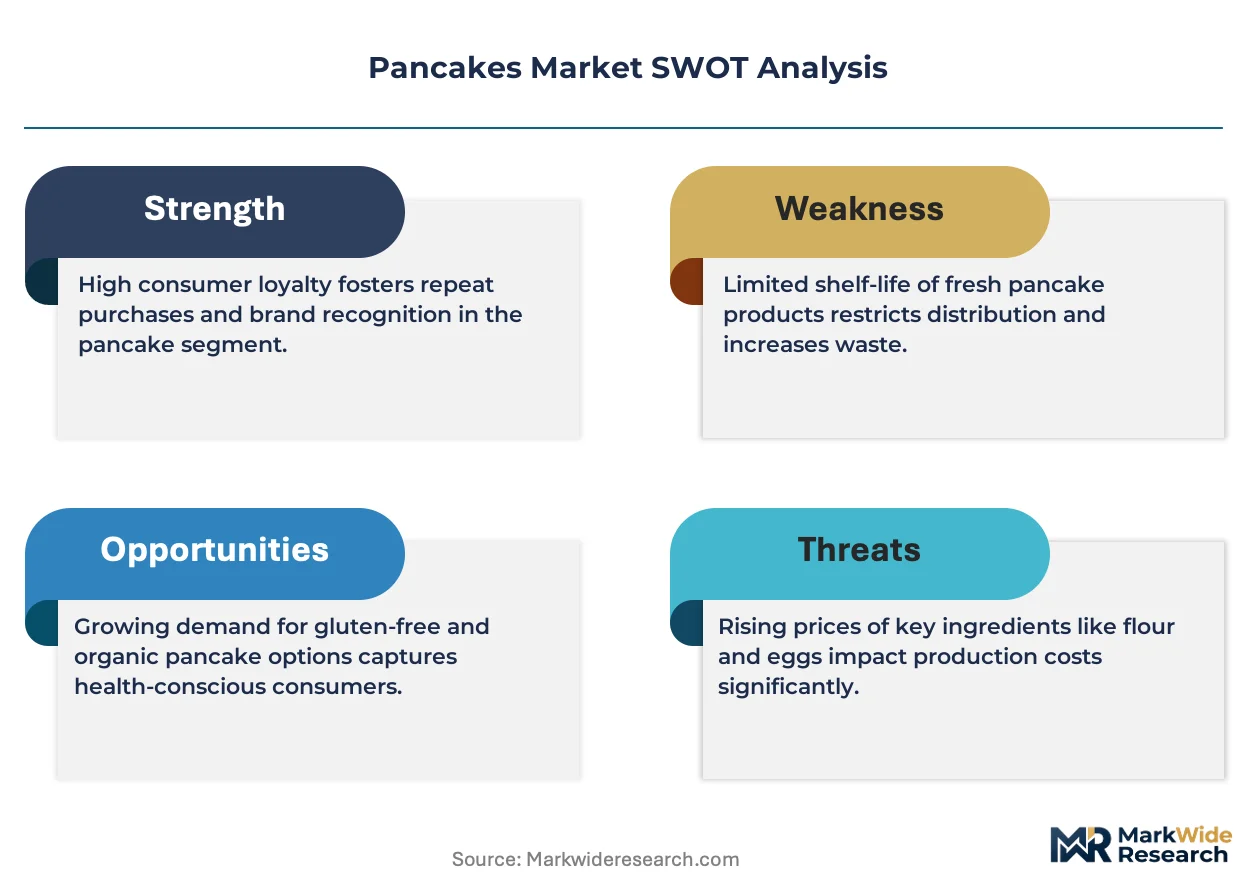
North American flour milling capacity is broadening as regional grain processors expand output for batter-based products. General Mills leverages its cereal-adjacent manufacturing infrastructure to sustain pancake mix production at scale. Kodiak Cakes differentiates through protein-fortified formulations that command premium shelf positioning in specialty retail channels.
Pancakes comprise flat, circular griddle-cooked batter products typically formulated from wheat flour, leavening agents, liquid dairy or alternatives, and eggs, with thickness ranging from one to three centimeters depending on regional style and leavening method. The primary commercial purpose spans home preparation, food service plating, and ready-to-eat frozen breakfast programs across retail and institutional channels. Frozen pancakes currently lead volume due to operational efficiency in hotel and quick-service restaurant back-of-house workflows, while organic and gluten-free variants capture expanding margin pools as specialty diet adherence rises among health-conscious households. Online retail channels represent the fastest-growing distribution vector, though supermarkets still anchor mass-market penetration through dedicated breakfast aisles.
The FDA governs pancake mix labeling under Food Allergen Labeling and Consumer Protection Act requirements, while the USDA oversees egg and dairy ingredient safety in batter formulations, collectively elevating clean-label transparency as a baseline market access condition. The EU EFSA and national food safety authorities across member states enforce additive limits and nutritional claim verification that constrain formulation flexibility for exporters. Stakeholders must monitor evolving protein-fortification claim standards and plant-based dairy substitution rules as these regulatory boundaries increasingly determine which product architectures can cross jurisdictions profitably.
Market Dynamics
Clean-label ingredient mandates from the FDA and EU EFSA are forcing wholesale reformulation across frozen and dry-mix categories, compressing margins for manufacturers dependent on legacy additive portfolios.
Growth Catalysts
- Quick-service restaurant expansion:Hotel breakfast programs and QSR chains are broadening pancake menu placements to capture morning traffic, driving institutional volume demand.
- REACH additive restrictions:European chemical safety frameworks are accelerating clean-label migration, creating first-mover advantages for reformulated product lines.
- Protein fortification technology:Whey and plant-protein integration into batter systems is commanding premium shelf positioning in specialty retail channels.
Market Restraints
- Wheat flour input volatility:Regional grain price swings constrain margin predictability for batter-based product manufacturers.
- Supply concentration in US milling:North American flour processing dominance creates geographic risk exposure for global formulation consistency.
- Clean-label transition costs:EFSA and FDA compliance timelines extend product development cycles, delaying revenue recognition.
Strategic Opportunities
- Underpenetrated European frozen segments:Southern and Eastern European markets show limited ready-to-eat pancake penetration versus Northern European adoption rates.
- Direct-to-consumer subscription channels:Recurring delivery models for premium mix portfolios bypass traditional retail slotting fee structures.
- EU Green Deal packaging mandates:Compostable and recyclable material requirements favor early adopters with sustainable supply chain infrastructure.
Industry Challenges
- Food science talent scarcity:Protein chemistry and alternative leavening expertise commands premium compensation, constraining R&D team scaling.
- Legacy equipment retrofit requirements:Existing griddle and freezer line configurations require substantial capital outlay to accommodate reformulated batter rheology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancakes Market |
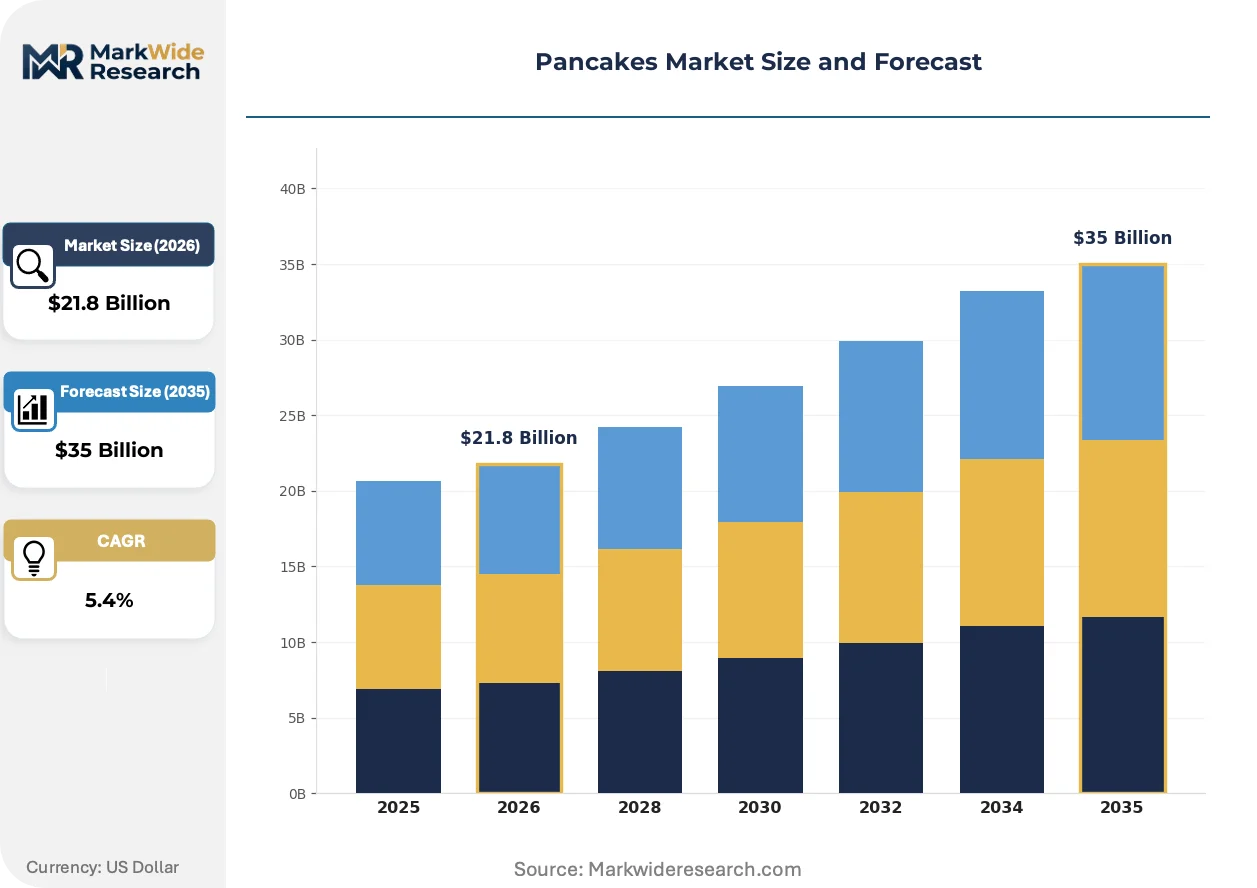
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Pancakes, Organic Pancakes, Gluten-Free Pancakes, Whole Wheat Pancakes Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Cafés, Hotels Packaging Type: Boxed, Pouch, Bulk, Ready-to-Eat |
| Companies Covered | Bob's Red Mill Natural Foods, C.H. Guenther & Son, General Mills, Premier Nutrition, Kodiak Cakes, PepsiCo, Kraft Heinz, King Arthur Baking Company, Continental Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancakes Market Emerging Trajectories
Automation and regulatory stringency are converging to reshape production economics and product architecture across frozen and dry-mix segments. Three developments warrant particular attention.
Continuous batter mixing and portioning systems are automating back-of-house labor deployment in hotel and institutional food service operations. Marriott and Hilton franchise operators are retrofitting breakfast bars with automated griddle equipment that reduces hourly labor requirements. This compression of labor input is automating cost structures that previously favored manual preparation in mid-scale hospitality settings.
EFSA clean-label additive restrictions are eliminating potassium bromate and certain phosphate leavening agents from formulations sold across European Union member states. Manufacturers must reformulate with alternative acidulants and natural leavening systems to maintain market access. Frozen pancake exporters to Germany, France, and Italy are accelerating reformulation timelines to meet phased compliance deadlines.
Health-conscious households are rotating toward protein-fortified and gluten-free variants, compressing traditional wheat-based mix demand in premium retail channels. Specialty diet adherence is displacing conventional pancake purchases in urban and suburban supermarket environments. This consumption-pattern shift concentrates in United States coastal metropolitan markets with elevated wellness-oriented consumer density.
Pancakes Market Segmentation
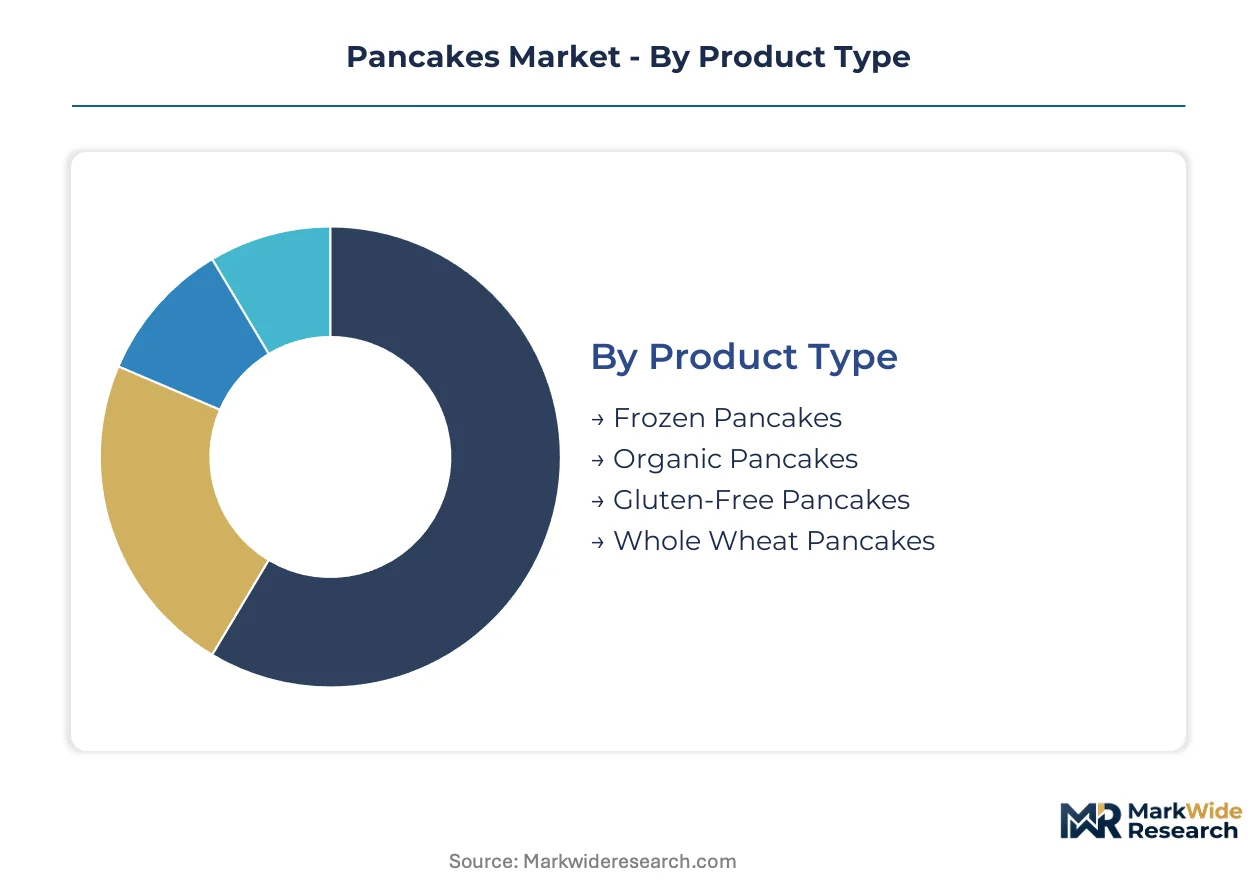
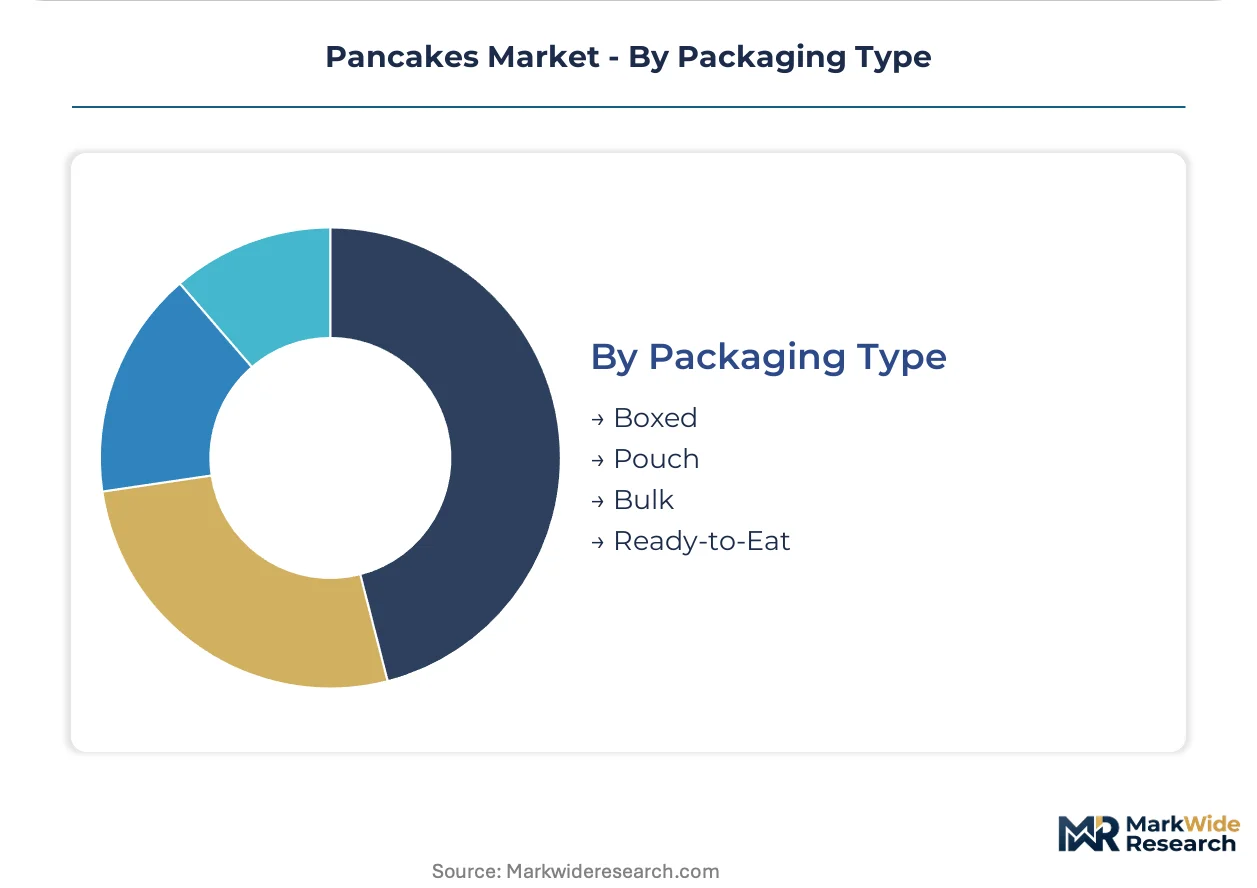
Pancake segmentation reflects divergent operational requirements across retail and food service channels. Product architecture, packaging format, and distribution pathway each determine margin structure and regulatory exposure for manufacturers.
Product Type:
Standardization dominates at the commodity end while premium tiers command formulation flexibility and ingredient provenance premiums.
- Frozen Pancakes:Pre-cooked and flash-frozen batter discs formulated for extended shelf stability through modified atmosphere packaging. Demand concentrates in United States hotel breakfast programs and QSR back-of-house operations where labor minimization overrides preparation authenticity. Operational efficiency in institutional channels sustains volume leadership despite lower per-unit margins.
- Organic Pancakes:USDA-certified or EU organic-compliant formulations excluding synthetic pesticides and GMO-derived ingredients. Demand concentrates in United States coastal metropolitan markets where household willingness-to-pay for clean-label credentials peaks. Premium shelf positioning in specialty retail channels captures margin pools unavailable to conventional alternatives.
- Gluten-Free Pancakes:Alternative grain formulations using rice, oat, or almond flour to address celiac disease and gluten sensitivity adherence.
- Whole Wheat Pancakes:Higher-fiber formulations retaining bran and germ components for health-positioned retail segments.
Leading the category by volume: Frozen Pancakes. Growing fastest: Organic Pancakes.
Distribution Channel:
Channel selection determines slotting fee exposure, inventory velocity, and direct consumer relationship depth.
- Online Retail:Direct-to-consumer and third-party marketplace distribution enabling subscription models and premium mix portfolios. Demand concentrates in United States suburban households seeking convenience without supermarket transit time. Bypassing traditional retail slotting fee structures improves net margin capture for specialty brands.
- Supermarkets:Mass-market penetration through dedicated breakfast aisles with high-frequency inventory turns. Demand concentrates in United States exurban and rural markets where physical retail remains the dominant procurement pathway. Volume scale compensates for compressed per-unit margins and promotional spending requirements.
- Specialty Stores:Curated retail environments emphasizing organic, gluten-free, and protein-fortified variants.
- Food Service:Institutional supply to hotels, restaurants, and cafeterias with bulk procurement specifications.
Leading the category by volume: Supermarkets. Climbing the fastest: Online Retail.
End User:
User type dictates portion sizing, packaging configuration, and preparation equipment requirements.
- Households:Individual and family consumption units purchasing retail formats for at-home preparation. Demand concentrates in United States time-constrained dual-income households prioritizing convenience breakfast solutions. Frozen and dry-mix formats compete based on preparation speed and storage flexibility.
- Restaurants:Full-service and limited-service establishments plating pancakes as menu staples or breakfast combo components. Demand concentrates in United States QSR chains expanding morning daypart offerings to capture commuter traffic. Standardized portioning and holding equipment compatibility drive supplier selection.
- Cafés:Coffee-forward establishments incorporating pancakes into extended breakfast and brunch menus.
- Hotels:Complimentary breakfast programs and paid restaurant operations requiring high-volume, low-labor solutions.
Leading the category by volume: Households. Expanding most quickly: Hotels.
Packaging Type:
Packaging economics reflect material cost trajectories and EU Green Deal sustainability mandates.
- Boxed:Paperboard cartons containing multiple serving units with printed preparation instructions and nutritional labeling. Demand concentrates in United States supermarket retail where shelf visibility and stacking stability influence purchase decisions. Recyclable material specifications align with emerging retailer sustainability requirements.
- Pouch:Flexible film packaging for single-serve or small-format dry mixes with reduced material weight. Demand concentrates in United States online retail and convenience store channels where shipping cost minimization matters. Lightweighting reduces transportation emissions and packaging waste fees.
- Bulk:Large-format institutional packaging for food service procurement with minimal unit costs.
- Ready-to-Eat:Individual portion packaging for immediate consumption without preparation.
Leading the category by volume: Boxed. Gaining share fastest: Pouch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hard red winter wheat from Kansas and Oklahoma anchors North American milling supply chains for batter-based breakfast products. This grain corridor feeds processing infrastructure concentrated in the United States, with secondary milling clusters in Canada and Mexico supporting cross-border formulation trade.
United States
Hotel breakfast programs and quick-service restaurant chains drive frozen pancake volume across the Midwest and Southeast. FDA enforcement of Food Allergen Labeling and Consumer Protection Act standards compels reformulation of legacy additive portfolios. Minneapolis-St. Paul hosts General Mills manufacturing infrastructure optimized for cereal-adjacent production.
Germany
EFSA additive restrictions under REACH frameworks are accelerating clean-label migration among frozen pancake exporters. Southern and Eastern European markets show underpenetration versus Northern European adoption rates. Bavarian food processors are retrofitting griddle lines to accommodate reformulated batter rheology for EU compliance deadlines.
Canada
Prairie wheat production supports regional milling capacity for dry-mix exports to United States markets. Health Canada and PMRA standards govern pesticide residue limits in organic-certified formulations. Ontario-based processors leverage Great Lakes logistics corridors for just-in-time delivery to Midwestern retail distribution centers.
United Kingdom
Supermarket breakfast aisles anchor mass-market penetration while online retail channels capture suburban household convenience demand. FSA allergen labeling requirements align with EU EFSA nutritional claim verification standards. Greater London metropolitan markets concentrate premium organic and gluten-free variant consumption.
France
Traditional crêpe consumption patterns create hybrid demand for American-style pancake formats in urban café channels. ANSM and DGCCRF enforce additive limits that constrain formulation flexibility for imported frozen products. Parisian hospitality operators are testing automated griddle equipment to compress breakfast-service labor inputs.
Pancakes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue protein-fortified and clean-label positioning. The vendor base stratifies across three maturity levels: multinational CPG conglomerates with cereal-adjacent infrastructure, mid-scale specialty brands commanding premium shelf positioning, and private-label suppliers serving institutional food service procurement. Three strategic archetypes dominate: scale-driven commodity manufacturers, formulation specialists leveraging protein chemistry differentiation, and direct-to-consumer subscription operators bypassing retail slotting structures. Competitive moves concentrate on portfolio diversification into organic and gluten-free variants, plus backward integration into regional grain sourcing to secure input cost stability.
Among United States-based CPG conglomerates, General Mills and Kraft Heinz exemplify scale-driven commodity manufacturing archetypes with breakfast-category infrastructure. Kodiak Cakes occupies the specialty-tier position, representing protein-fortified formulation specialists that command premium retail placement through differentiated batter systems. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| C.H. Guenther & Son |
| General Mills |
| Premier Nutrition |
| Kodiak Cakes |
| PepsiCo |
| Kraft Heinz |
| King Arthur Baking Company |
| Continental Mills |
| Others |
Supply Flow & Price Mechanics
Automated griddle equipment retrofits in hotel breakfast programs simultaneously compress labor economics and concentrate procurement power among institutional buyers. This production-method transition reshapes cost structures while tilting negotiating leverage toward volume purchasers in the United States hospitality sector.
Pricing Analysis
Service bundling separates equipment-inclusive contracts from unbundled product-only supply. Three-tier pricing structure across premium, standard, and economy levels captures formulation complexity and certification grade. Price differentiation centers on organic certification tier and protein fortification level. Cost compression in frozen commodity tiers is intensifying because clean-label reformulation extends product development cycles. Quick-service restaurant chains exhibit highest price sensitivity; specialty retail channels show lowest.
Supply Chain Analysis
USDA organic certification and EFSA additive compliance act as qualification gates for market access. Supply concentrates in the United States, Canada, and Germany for milling and formulation. Raw material flows draw from hard red winter wheat, whey protein isolates, and alternative grain flours. Single-source vulnerability in North American milling creates geographic risk exposure. Distribution runs through food service broadline distributors and retail grocery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue backward integration into regional grain sourcing to secure input cost stability against wheat price volatility.
For Market Incumbents: Anchor market position through captive flour milling capacity in Kansas-Oklahoma grain corridors and accelerated clean-label certification investment. Protein-fortified entrants threaten premium positioning; defend through R&D scale in alternative leavening systems. Channel control via direct-to-consumer subscription infrastructure offsets retail slotting fee pressure. For New Entrants and Emerging Players: Protein chemistry expertise offers a technology-first wedge into specialty retail placement. Southern and Eastern European frozen segments present the most penetrable geography with limited incumbent saturation. A direct-to-consumer subscription go-to-market angle bypasses supermarket slotting structures entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by CPG conglomerates seeking breakfast-category expansion. Long-term viability favors mid-scale specialists with certified organic supply chains and established food service relationships. Watch EFSA enforcement timelines as inflection indicator for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Sourcing | Captive wheat supply from Kansas-Oklahoma corridors insulates margin from commodity volatility. |
| Clean-Label Reformulation Investment | EFSA-compliant additive portfolios secure European market access ahead of compliance deadlines. |
| Direct-to-Consumer Channel Launch | Subscription models bypass retail slotting fees and capture recurring revenue from suburban households. |
| Protein Fortification R&D Scale-Up | Whey and plant-protein batter systems command premium shelf positioning in specialty retail. |
| Automated Production Equipment Deployment | Continuous griddle systems reduce labor input for hotel and QSR institutional customers. |
Methodological Framework
USDA agricultural statistics, FDA food additive petitions, and EFSA scientific opinions formed the secondary backbone of this analysis. Primary interviews with flour milling executives, hotel food service procurement managers, specialty retail category buyers, and protein ingredient suppliers validated demand assumptions. Bottom-up volume estimates from segment-level consumption patterns triangulated against top-down macroeconomic indicators.
Historical trendline analysis anchored growth trajectory modeling across the projection horizon. Segmentation dimensions included product type, distribution channel, end user, and packaging format. CAGRs derived from fitted trend extrapolation adjusted for regulatory phase-in schedules and technology adoption curves. Wheat futures price volatility and clean-label compliance timelines served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA enforcement acceleration or sustained grain price spikes. A model refresh is warranted upon material change in FDA protein-fortification claim standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Bakery Premixes Market
Bakery Products
Low Calorie Bread Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Biscuits Market
Bakery Products
Low Calorie Cake Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Personalized Bakery Products Market
Bakery Products
Bakery Cases Market
Bakery Products
Pancake Mixes Market
Bakery Products
Low-Calorie Breakfast Muffins Market