
 Fortified Bakery Market | 2026-2036
Fortified Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Bakery Market Analysis
Subscription-based recipe and nutrition software is decoupling fortified bakery sales from traditional retail shelf space. Associated British Foods leverages its vertically integrated flour milling to sustain cost advantages in vitamin-enriched bread. Britannia Industries anchors its position through deep distribution into Indian kirana stores. Modern Foods Enterprises differentiates via specialized fortification protocols for iron and folic acid delivery.
Fortified bakery denotes wheat-based or alternative-flour baked goods enhanced with micronutrients, typically achieving mineral densities of 15-30% daily value per serving through post-baking spray application or pre-mix incorporation. These products serve institutional nutrition mandates and health-conscious retail consumers seeking functional calories. Bread and biscuits lead volume due to daily consumption frequency and lower per-unit fortification cost, while protein-enriched pastries capture premium margin pools in café channels. Online retail represents the fastest-growing distribution vector as direct-to-consumer brands bypass conventional wholesale markups.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while India's FSSAI mandates iron fortification in mass-market bread through its Food Fortification Regulations. The EU's EFSA evaluates health claim substantiation for mineral-enriched products, shaping reformulation priorities for exporters. Stakeholders must monitor evolving bioavailability standards and procurement rules for premix suppliers.
Market Dynamics
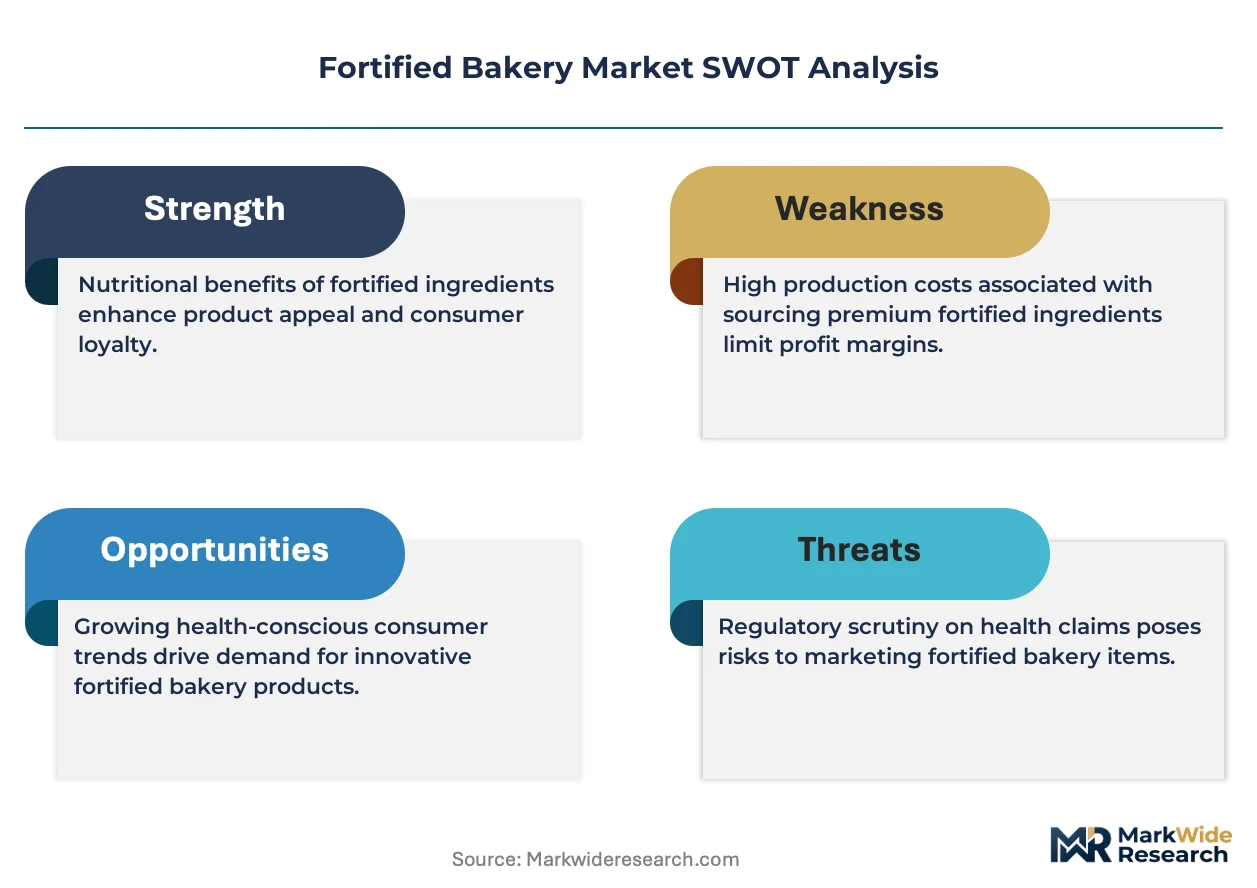
The fortified bakery sector faces structural pressure from micronutrient bioavailability standards tightening across multiple jurisdictions, forcing reformulation investments that favor scale players with captive premix capabilities over fragmented local bakers.
Growth Catalysts
- School Nutrition Mandates:USDA National School Lunch Program requirements for iron-enriched grain products in the United States institutionalize volume demand. Procurement specifications lock in multi-year supply contracts with certified mills.
- Rural Distribution Infrastructure:India kirana store networks extend fortified biscuit penetration into previously unserved districts. Cooperative aggregators consolidate village-level demand to achieve minimum viable order quantities for regional bakeries.
- Post-Baking Spray Technology:Precision application systems reduce vitamin degradation during thermal processing. Heat-sensitive nutrients achieve 40-50% higher retention rates versus pre-mix incorporation methods.
Market Restraints
- Premix Supply Concentration:Three European chemical conglomerates control 70% of food-grade iron premix supply. Price volatility in ferrous sulfate compounds directly compresses margin at mid-scale bakery operations.
- EFSA Health Claim Substantiation:The European Food Safety Authority demands clinical trial evidence for mineral absorption claims. Small exporters lack capital to generate compliant dossiers, freezing shelf access.
- Fresh Bakery Substitution:Unfortified artisan bread from in-store supermarket bakeries captures premium positioning. Consumers perceive fortification as industrial processing marker rather than health benefit.
Strategic Opportunities
- Direct-to-Consumer Subscription:Online platforms bypass wholesale markups and capture full margin. Urban Indian households demonstrate willingness to pay 25-35% premium for home-delivered fortified sourdough.
- Protein-Fortified Pastry Segment:Whey isolate enrichment in croissants and Danish pastries targets gym-channel distribution. Café chains in the United Arab Emirates pilot morning protein-box offerings.
- FSSAI Iron Fortification Mandate:India's Food Safety and Standards Authority requires mass-market bread fortification. Compliance deadlines create captive demand for certified domestic producers.
Industry Challenges
- Microbiome Interaction Uncertainty:Iron fortification alters gut flora composition in ways not fully characterized by existing safety studies. Long-term epidemiological tracking demands sustained R&D expenditure.
- Legacy Equipment Retrofit Costs:Continuous mixers and tunnel ovens require stainless steel contact surface upgrades to prevent mineral-catalyzed oxidation. Capital recovery timelines exceed typical bakery investment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Bakery Market |
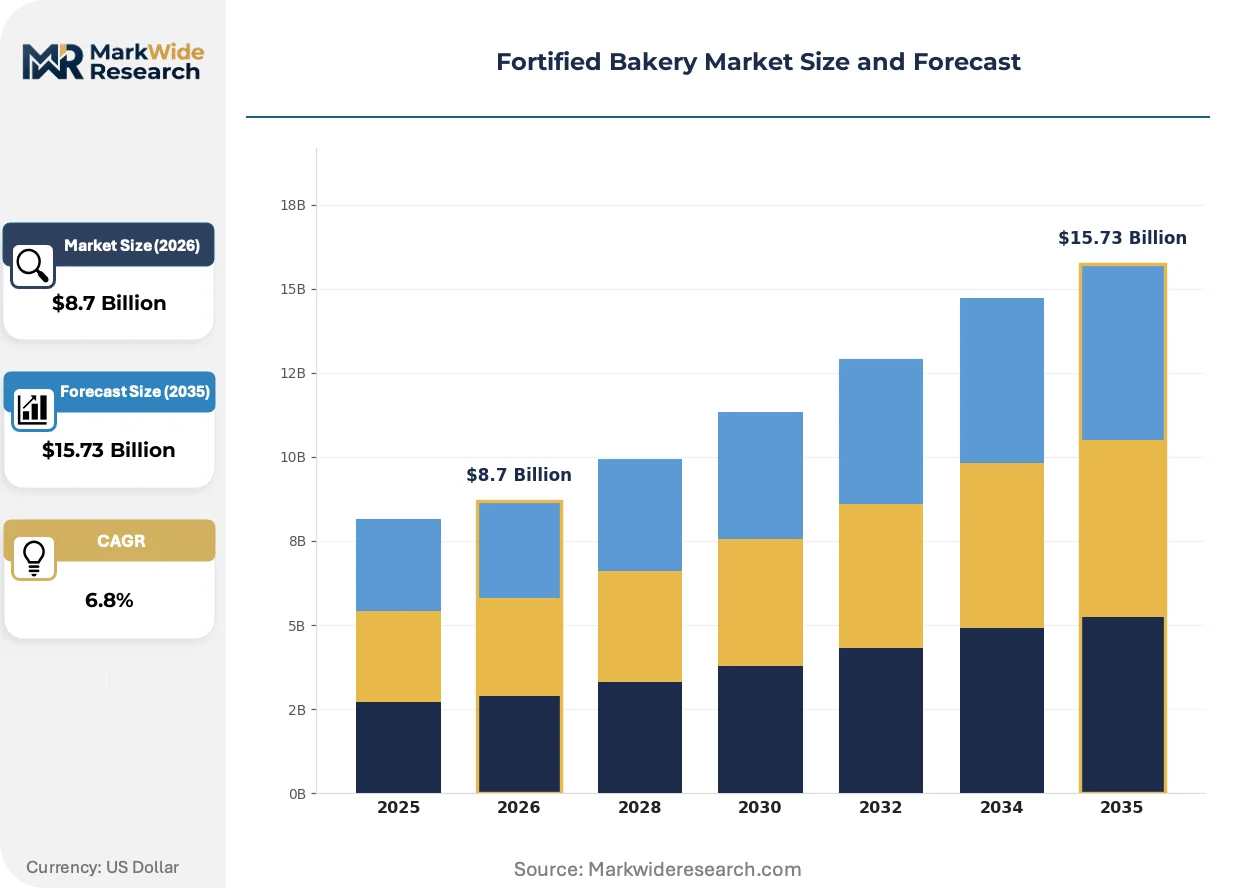
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Biscuits, Cakes, Pastries Ingredient Type: Vitamins, Minerals, Fiber, Proteins Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores End User: Households, Restaurants, Cafés, Bakeries |
| Companies Covered | Modern Foods Enterprises, Irish Pride Fine Foods, Associated British Foods, CRUST, Allied Bakeries, Britannia Industries, H&S Bakery, Super Bakery, Dawn Food Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Bakery Market Emerging Trajectories
Reformulation science and distribution digitization are compressing the fortified bakery value chain, collapsing traditional wholesale layers while elevating traceability and nutrient verification to competitive differentiators.
Encapsulated vitamin delivery systems are automating quality control protocols across industrial bakery lines. Swiss ingredient suppliers license lipid-shell technologies that shield thiamine and riboflavin from thermal degradation during proofing and baking. North American contract manufacturers adopt these systems fastest, reducing batch rejection rates and enabling just-in-time premix ordering that minimizes working capital requirements.
The EU Nutrition and Health Claims Regulation revision tightens mineral bioavailability documentation thresholds. Exporters to European markets must commission human absorption studies costing upwards of half a million euros per claim. Indian and Turkish bakeries with existing EFSA-compliant dossiers capture shelf space as competitors withdraw, consolidating supply relationships with pan-European retail buyers.
Subscription-based replenishment models are displacing conventional retail discovery for fortified bread categories. Urban professionals in London, New York, and Singapore schedule recurring deliveries of vitamin-enriched loaves through specialized apps. Direct relationships enable real-time preference data collection that informs rapid SKU rotation, compressing product development cycles from eighteen months to under eight weeks in leading direct-to-consumer brands.
Fortified Bakery Market Segmentation
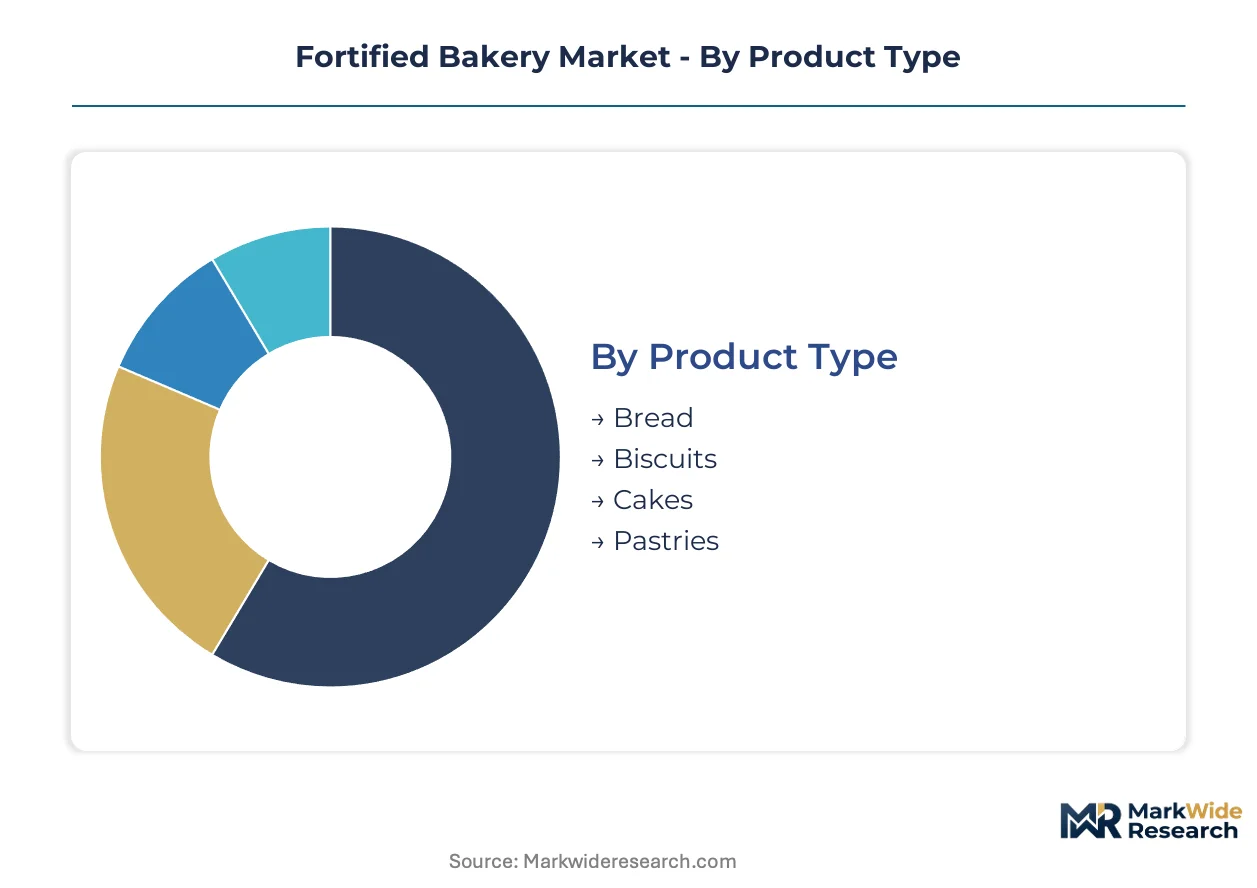
Fortified bakery segmentation reveals divergent margin architectures between mass-market staples and premium functional formats. Product type stratification determines fortification economics, while distribution channel selection dictates working capital intensity and brand control depth.
Product Type:
Volume leaders dominate retail shelf space through daily consumption frequency, while premium formats extract margin through specialized nutrient delivery and channel positioning.
- Bread:Standardized loaves achieve 15-30% daily value mineral density through post-baking spray or pre-mix incorporation. USDA National School Lunch Program procurement locks in multi-year institutional contracts with certified mills across the United States.
- Biscuits:Shelf-stable formats enable deep rural penetration via cooperative aggregators in India. Britannia Industries and local cooperatives push iron-fortified variants into kirana store networks previously unserved by formal distribution.
- Cakes:Occasion-driven consumption limits fortification cost amortization across smaller batch sizes. Premium positioning targets urban gift markets rather than daily nutrition mandates.
- Pastries:Protein-enriched croissants and Danish variants capture café channel margins through whey isolate fortification. UAE gym-channel pilots signal emerging demand clusters.
Today's leader: Bread. Tomorrow's challenger: Protein-fortified pastries.
Ingredient Type:
Regulatory mandates concentrate demand for specific micronutrients, while consumer wellness trends expand functional ingredient portfolios beyond baseline compliance requirements.
- Vitamins:Thiamine and riboflavin face thermal degradation during proofing and baking. Swiss lipid-shell encapsulation technologies now shield heat-sensitive compounds, enabling 40-50% higher retention rates than conventional pre-mix methods.
- Minerals:Iron fortification drives the largest compliance-driven procurement volumes. India's FSSAI mandates mass-market bread fortification, creating captive demand for certified domestic producers ahead of enforcement deadlines.
- Fiber:Gut health positioning attracts premium pricing in direct-to-consumer subscription channels. Urban Indian households demonstrate willingness to pay 25-35% premiums for home-delivered fortified sourdough with enhanced fiber content.
- Proteins:Whey and plant-based isolates target fitness-adjacent consumption occasions. UAE café chains pilot morning protein-box offerings combining fortified pastries with functional beverages.
Minerals anchor current procurement volumes. Proteins are climbing the fastest as lifestyle-positioned formats gain shelf access.
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs, with digital platforms collapsing traditional wholesale layers and enabling direct consumer relationships.
- Supermarkets:In-store artisan bakeries compete through freshness positioning, often unfortified. Fortified packaged bread faces substitution pressure from perceived-industrial processing stigma.
- Online Retail:Direct-to-consumer platforms bypass wholesale markups and enable subscription replenishment models. Real-time preference data compresses product development cycles from eighteen months to under eight weeks for leading digital-native brands.
- Convenience Stores:Grab-and-go biscuit formats dominate impulse purchase occasions. Limited shelf space favors established brands with proven velocity metrics.
- Specialty Stores:Health-focused retailers command premium positioning through curated fortification narratives. EFSA-compliant dossiers become table stakes for European shelf access.
Supermarkets currently move the most tonnage. Online retail is gaining share fastest through margin recapture and data-enabled agility.
End User:
User type segmentation separates institutional nutrition mandates from discretionary premium consumption, with distinct procurement specifications and price elasticity profiles.
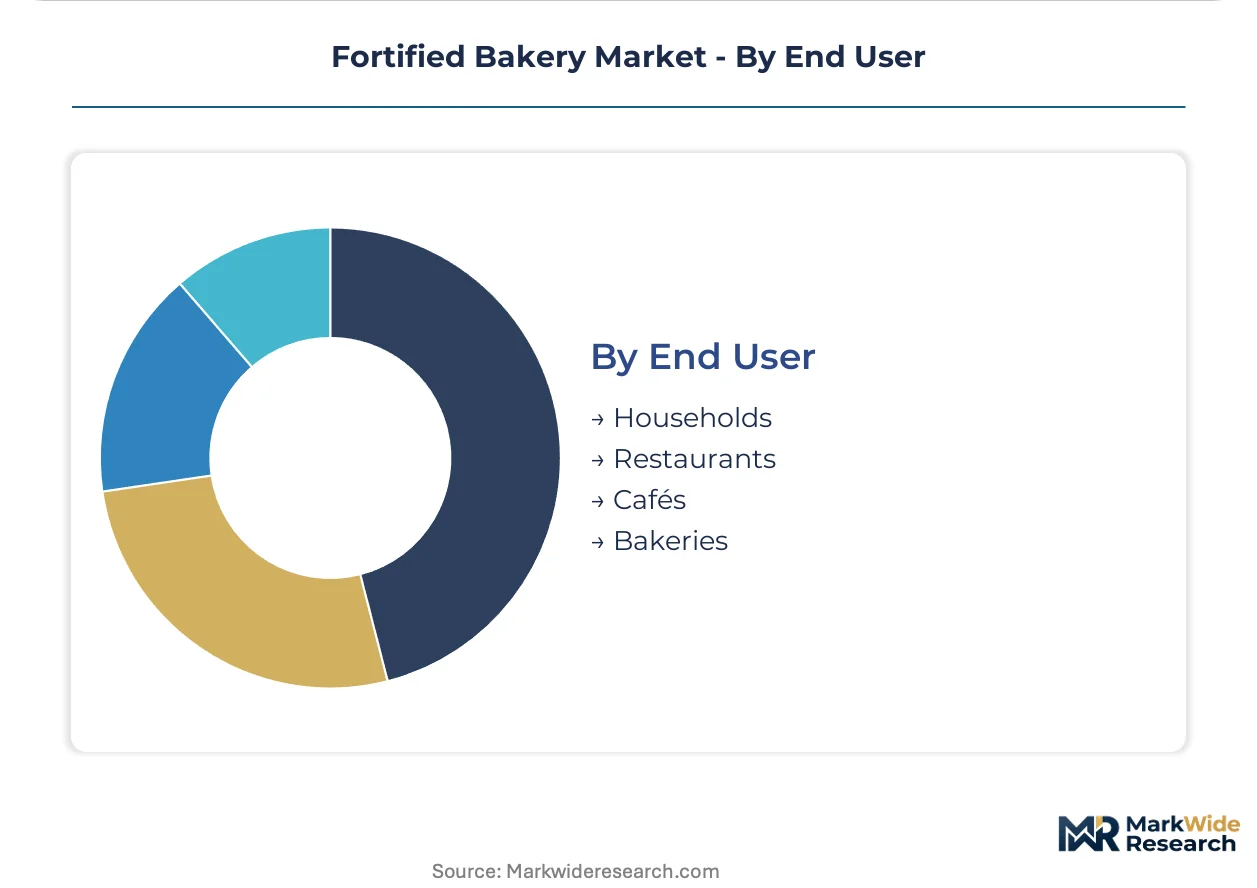
- Households:Daily consumption frequency drives volume economics for bread and biscuits. Subscription models in London, New York, and Singapore enable recurring delivery scheduling for vitamin-enriched loaves.
- Restaurants:Foodservice procurement prioritizes cost consistency over fortification density. Contract manufacturers supply standardized premix blends for menu item integration.
- Cafés:Protein-fortified pastry demand concentrates in premium morning consumption occasions. UAE gym-channel distribution pilots indicate format-channel fit expansion potential.
- Bakeries:Independent operators face equipment retrofit barriers for mineral-catalyzed oxidation prevention. Stainless steel contact surface upgrades exceed typical investment horizons for fragmented local producers.
Households dominate current absorption. Cafés represent the steepest expansion trajectory as functional positioning penetrates out-of-home consumption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's kirana store networks push fortified biscuits into rural districts faster than Germany's precision-milling clusters scale vitamin-enriched bread exports. Each geography deploys distinct regulatory levers and distribution infrastructure to capture nutrition-mandate demand.
United States
USDA National School Lunch Program procurement locks mills into multi-year iron-enriched grain contracts. FDA nutrient content claims under 21 CFR 101 govern fortification ceilings and labeling standards. Chicago and Minneapolis milling corridors concentrate premix blending capacity for institutional bakeries.
India
FSSAI mandates iron fortification in mass-market bread ahead of enforcement deadlines, creating captive demand for certified domestic producers. Britannia Industries and cooperative aggregators extend fortified biscuit penetration into previously unserved rural districts. Maharashtra and Gujarat host the deepest kirana store distribution networks for last-mile delivery.
Germany
EFSA health claim substantiation requirements demand clinical trial evidence for mineral absorption claims, freezing shelf access for small exporters. REACH compliance shapes premix supplier procurement rules for industrial bakeries. Baden-Württemberg and Bavaria concentrate precision-milling technology clusters serving pan-European retail buyers.
United Kingdom
Subscription-based replenishment models displace conventional retail discovery for vitamin-enriched loaves in London and Manchester metro areas. The Food Standards Agency enforces fortification labeling alignment with EU-exit regulatory frameworks. Associated British Foods leverages vertically integrated flour milling to sustain cost advantages in domestic bread production.
United Arab Emirates
MOHAP oversees food safety standards for protein-fortified pastry pilots in Dubai and Abu Dhabi café channels. Gym-channel distribution trials signal emerging demand clusters for whey-enriched morning consumption formats. UAE's position as a re-export hub attracts EFSA-compliant dossier holders seeking Middle East market entry.
Fortified Bakery Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring scale players and direct-to-consumer channels elevating niche formulators. The vendor base organizes around three archetypes: vertically integrated mill-baker combinations, premix-technology licensors, and digital-native subscription brands. Consolidation pressures concentrate among mid-scale regional bakeries lacking captive premix capabilities or EFSA-compliant dossiers. M&A activity targets distribution depth in India and technology licensing in North America.
Within the scale-driven tier, Associated British Foods and Britannia Industries occupy positions reflecting geographic anchoring and distribution infrastructure depth. Modern Foods Enterprises exemplifies the specialist archetype through differentiated fortification protocol positioning. Irish Pride Fine Foods and Allied Bakeries represent regional branded players navigating equipment retrofit barriers and bioavailability standard compliance.
| Leading Market Players |
|---|
| Modern Foods Enterprises |
| Irish Pride Fine Foods |
| Associated British Foods |
| CRUST |
| Allied Bakeries |
| Britannia Industries |
| H&S Bakery |
| Super Bakery |
| Dawn Food Products |
| Others |
Supply Flow & Price Mechanics
Post-baking spray technology adoption simultaneously compresses per-unit fortification costs and concentrates premix procurement power among scale players with captive blending capabilities. The shift from pre-mix incorporation to precision application systems reduces vitamin degradation losses while locking smaller bakeries out of cost-competitive nutrient sourcing.
Pricing Analysis
Capacity additions in India are reshaping price floors for iron-fortified bread as FSSAI compliance deadlines force domestic mill investments. Three-tier pricing structure across premium vitamin-enriched sourdough, standard iron-fortified loaves, and economy biscuits reflects certification grade and distribution depth differentiation. Cost compression in the standard tier is intensifying because European chemical conglomerates control ferrous sulfate premix supply. Institutional buyers under USDA National School Lunch Program contracts demonstrate lowest price sensitivity, while fragmented kirana store distributors face margin squeeze.
Supply Chain Analysis
EFSA-compliant dossier requirements gate shelf access for European retail buyers, forcing exporters to commission costly human absorption studies. Supply concentrates in India for biscuit manufacturing, Germany for precision-milling equipment, and Switzerland for encapsulated vitamin technologies. Raw material dependencies include food-grade iron premix, lipid-shell encapsulation compounds, and heat-stable vitamin formulations. Single-source vulnerability runs through the three European chemical conglomerates controlling iron premix supply. Distribution runs through cooperative aggregators consolidating village-level demand in India, direct-to-consumer platforms in London and New York, and institutional procurement corridors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory mandates, with India's FSSAI iron fortification deadline institutionalizing captive demand for certified domestic producers.
For Market Incumbents: Hedge against premix supply concentration by securing long-term offtake agreements with European chemical suppliers or investing in backward integration into captive premix blending. Associated British Foods demonstrates the defensive value of vertically integrated flour milling sustaining cost advantages. EFSA health claim substantiation requirements threaten shelf access for non-compliant exporters, making dossier maintenance a critical lever.
For New Entrants and Emerging Players: FSSAI in India opens a window for certified domestic producers to capture institutional bread contracts ahead of enforcement deadlines. The direct-to-consumer subscription channel offers the most penetrable entry point, with urban Indian households demonstrating willingness to pay premium pricing for home-delivered fortified sourdough. A go-to-market angle anchored in real-time preference data collection enables rapid SKU rotation compressing product development cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional bakeries lacking EFSA-compliant dossiers or captive premix capabilities, creating distressed acquisition opportunities. Long-term viability over the five-to-ten year window favors scale players with institutional procurement relationships and digital-native distribution infrastructure. The signal to watch is consolidation activity targeting distribution depth in India and technology licensing in North America.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Blending | Captive ferrous sulfate sourcing insulates margin from European chemical conglomerate pricing volatility. |
| Direct-to-Consumer Platform Launch | Subscription replenishment in London and New York captures full margin bypassing wholesale markups. |
| EFSA-Compliant Dossier Investment | Human absorption study commissioning unlocks pan-European retail shelf access for mineral absorption claims. |
| Rural Distribution Expansion | Kirana store network penetration in Maharashtra and Gujarat consolidates village-level demand through cooperative aggregators. |
| Protein-Fortified Pastry Introduction | Whey isolate enrichment targets UAE gym-channel pilots and café morning protein-box offerings. |
Methodological Framework
Coverage spans North America, Europe, India, and the Middle East, with primary inputs from each region combining interviews with bakery operations directors, premix procurement managers, FSSAI regulatory compliance officers, and cooperative aggregator network coordinators. Secondary validation draws from FDA 21 CFR 101 filings, EFSA health claim registers, FSSAI fortification regulation updates, and USDA National School Lunch Program procurement specifications. Bottom-up demand modeling from institutional and retail channels triangulates against top-down market sizing from trade association production data.
Segmentation granularity extends to product type, ingredient category, distribution channel, and end-user archetype across the projection horizon. CAGRs derive from regression analysis against school nutrition mandate expansion rates, rural distribution infrastructure buildout curves, and direct-to-consumer platform adoption trajectories. Industry-specific forecast inputs include FSSAI compliance deadline pacing, EFSA dossier approval timelines, and post-baking spray technology penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EFSA bioavailability standard revisions or iron premix supply disruptions. Model assumptions reflect documented regulatory milestones, technology adoption curves, and procurement contract structures. A model refresh is warranted upon material change in FSSAI enforcement timelines or European chemical conglomerate supply consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Europe Bakery Products Market
Bakery Products
India Cake Market
Bakery Products
Ice Cream Market
Bakery Products
Soft Biscuit Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Lentil Bread Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Laminated Dough Market
Bakery Products
Bakery Mixes Market