
 Global Cake Mix Market | 2026-2036
Global Cake Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cake Mix Market Analysis
Supermarket shelf space allocation is reconfiguring as private-label cake mixes gain prominence alongside branded portfolios. General Mills leverages its Betty Crocker heritage to sustain brand loyalty across North American retail channels. Associated British Foods competes through dual distribution, anchoring its presence in both European supermarkets and foodservice supply chains. Grupo Bimbo dominates Latin American mass-market retail with localized flavor variants and cost-optimized packaging formats.
Cake mix denotes a pre-blended dry formulation of refined wheat flour, leavening agents, sugar, and emulsifiers requiring only liquid addition and thermal processing to produce finished cake structures, with commercial variants calibrated to specific moisture retention and crumb density parameters for consistent bake outcomes. Chocolate cake mix occupies the largest revenue pool among product types due to universal flavor acceptance across age demographics and occasion-based purchasing. Gluten-free cake mix registers the fastest expansion trajectory as celiac awareness and voluntary wheat-avoidance patterns reshape household pantry composition. Online retailers capture disproportionate growth within distribution channels, driven by subscription bundling and direct-to-pantry replenishment models that reduce stockout friction.
FDA labeling requirements in the United States and EU Green Deal sustainability frameworks in Europe compel reformulation toward reduced additive content and responsibly sourced palm oil derivatives. BIS fortification standards in India and EFSA novel food assessments create divergent compliance pathways that fragment regional product specifications. Stakeholders must monitor evolving clean-label thresholds and packaging waste directives as these frameworks increasingly determine market access eligibility and consumer trust metrics.
Market Dynamics
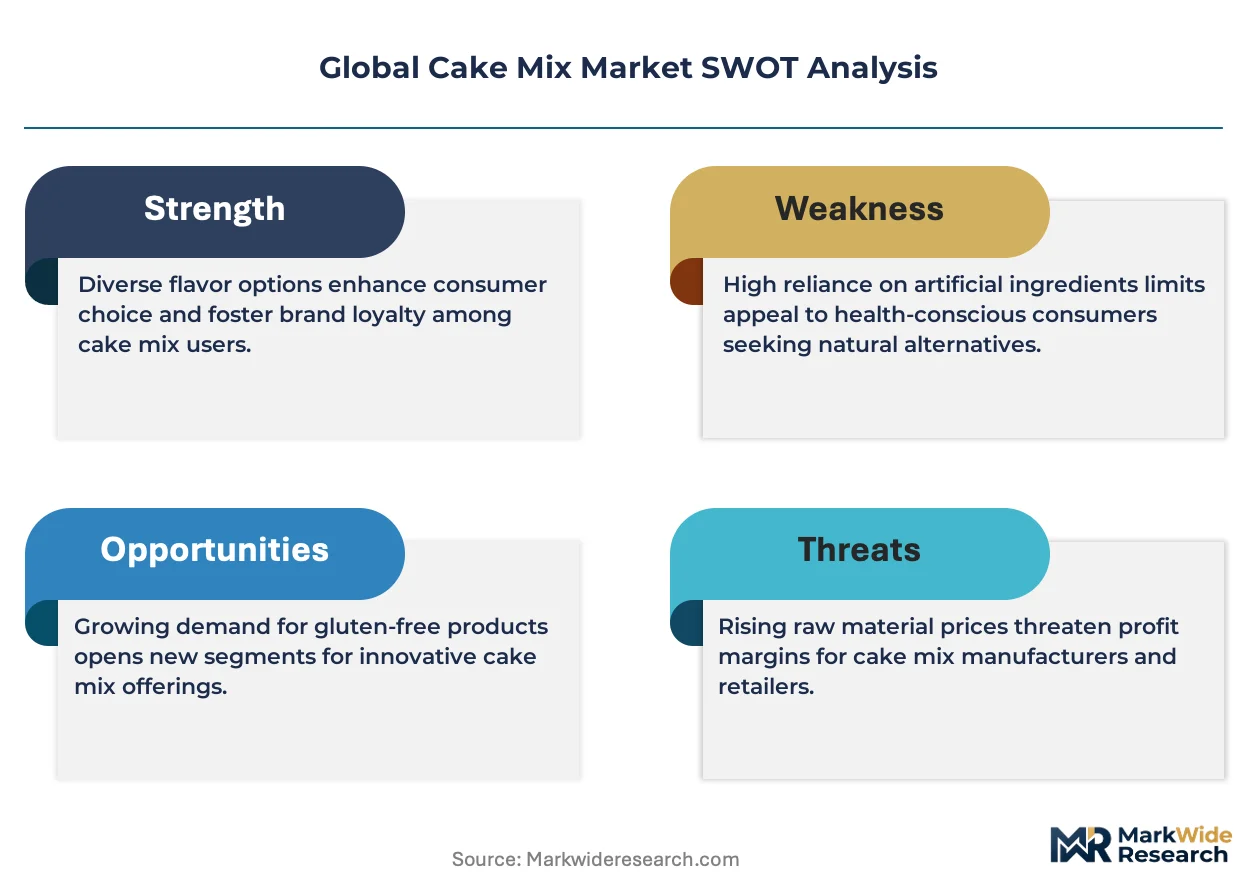
Clean-label mandates from FDA and EFSA are forcing simultaneous reformulation of leavening systems and emulsifier portfolios, compressing R&D timelines while opening premium positioning for compliant portfolios.
Growth Catalysts
- EU Green Deal sustainability frameworks:Mandatory deforestation-free supply chain verification accelerates certified palm oil sourcing among European manufacturers.
- Home baking retention post-pandemic:Sustained pantry-stocking behavior in United States, German, and Japanese households stabilizes baseline demand volatility.
- Enzyme-based clean-label leavening:Biotechnology advances replace traditional phosphate systems, enabling shorter ingredient declarations without volume sacrifice.
Market Restraints
- Wheat futures volatility:Hard red winter wheat price swings compress margin predictability for standard flour-based formulations.
- Supply concentration in Malaysian-Indonesian palm oil:Geopolitical friction and weather disruption create raw material access risk for emulsifier-dependent products.
- EFSA novel food assessment timelines:Extended approval windows for alternative protein or fiber fortification delay regional launch schedules.
Strategic Opportunities
- India BIS fortification standards:Mandatory micronutrient enrichment creates compliant product demand in underpenetrated urban retail.
- Direct-to-pantry subscription bundling:Online retailers capture recurring revenue through flavor-rotation algorithms and auto-replenishment interfaces.
- Algae-derived emulsifier convergence:Marine biotechnology meets clean-label requirements while differentiating premium tier positioning.
Industry Challenges
- Food technologist specialization gap:Shortage of formulation chemists skilled in enzyme stabilization and clean-label texture engineering constrains innovation velocity.
- Legacy equipment retrofit requirements:Existing production lines require capital-intensive modification to handle hygroscopic alternative flour blends without cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cake Mix Market |
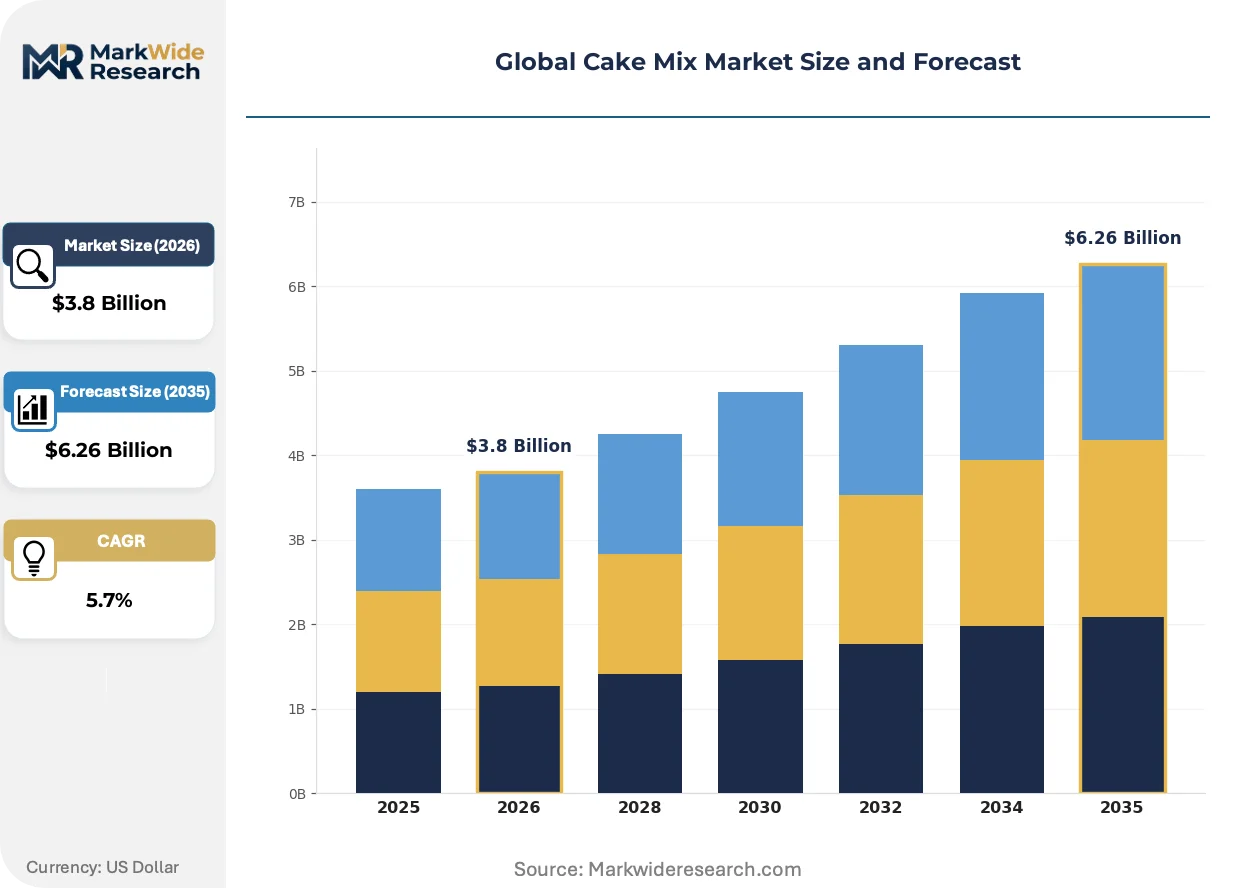
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cake Mix, Vanilla Cake Mix, Red Velvet Cake Mix, Gluten-Free Cake Mix Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores End User: Households, Bakeries, Restaurants, Catering Services Packaging Type: Boxed Mixes, Pouches, Bulk Packaging, Ready-to-Use |
| Companies Covered | General Mills, Conagra Brands, ADM, Associated British Foods, Cargill, Dawn Food Products, Chelsea Milling Co., Grupo Bimbo, Dr. Oetker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cake Mix Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel transformation, with biotechnology and digital channel structures redefining competitive advantage.
Spray-dried fat encapsulation technology extends shelf stability without synthetic antioxidants. Premium private-label manufacturers in Germany and Japan are adopting these systems to support extended supply chain reach. The technology is migrating from pharmaceutical excipient applications into mainstream baking ingredient portfolios.
FDA updated guidance on "healthy" nutrient content claims tightens added sugar thresholds for voluntary labeling. Manufacturers must reformulate or forfeit marketing advantage in United States retail channels. Chocolate and vanilla cake mix segments face the steepest compositional adjustment requirements.
Pantry replenishment algorithms now trigger automatic reorder based on consumption velocity detected through smart appliance integration. Subscription platforms displace traditional supermarket restocking cycles among millennial and Gen Z households in United States and United Kingdom urban centers.
Global Cake Mix Market Segmentation
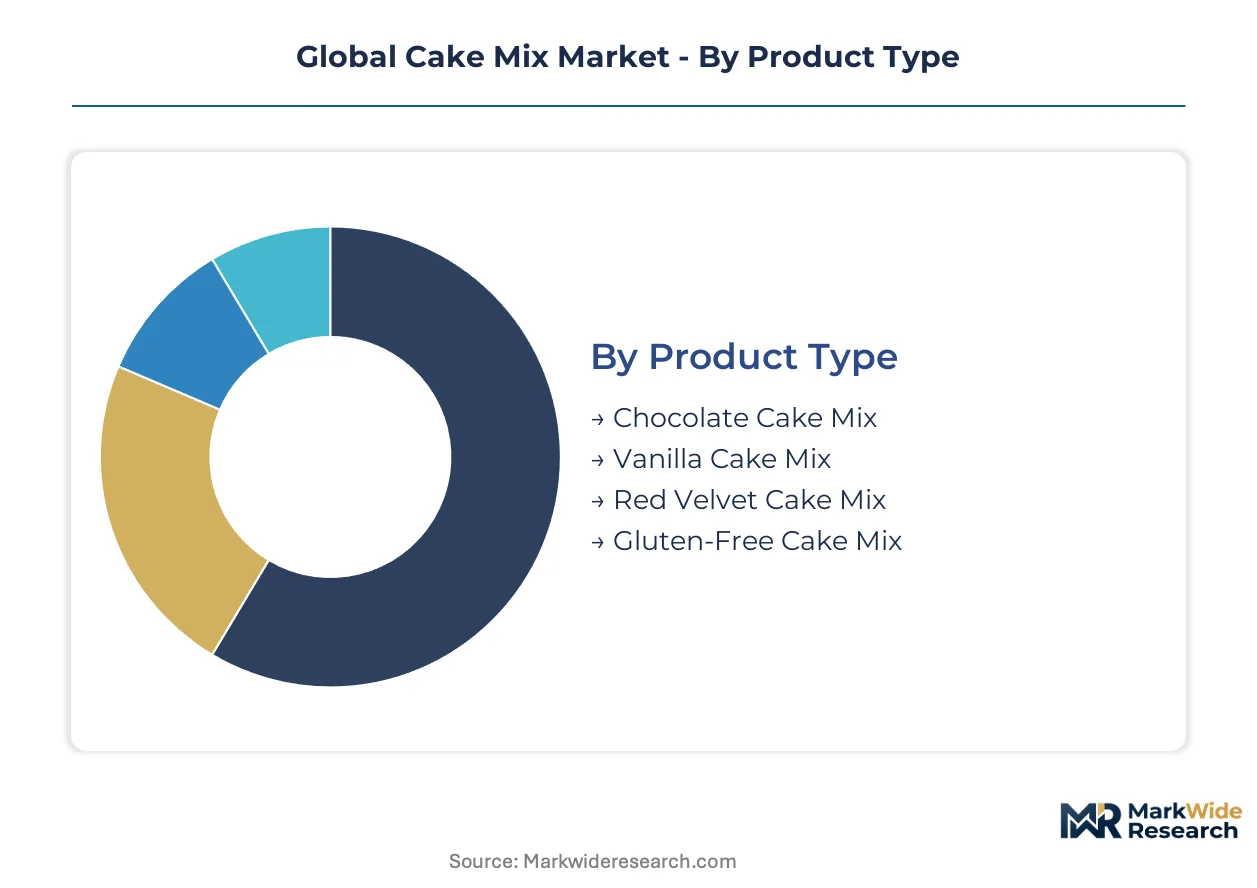
Segmentation in cake mix markets reveals divergent formulation requirements across distribution channels and end-use contexts. Technical specifications vary sharply between household convenience formats and professional bakery applications, while packaging economics reshape margin structures at each tier.
Product Type:
After-sales intensity remains minimal for standard formulations, but gluten-free variants demand substantial consumer education and technical support infrastructure.
- Chocolate Cake Mix:Cocoa-based formulations with calibrated fat encapsulation systems deliver consistent moisture retention across bake environments. Demand concentrates in United States and German retail channels where occasion-based purchasing sustains baseline volumes despite reformulation pressures from FDA added-sugar thresholds.
- Gluten-Free Cake Mix:Rice flour, tapioca starch, and xanthan gum systems replace wheat protein structures, requiring precise hydration protocols. Celiac awareness in United Kingdom and voluntary wheat-avoidance patterns in United States urban households are expanding most quickly, though EFSA novel food assessments delay alternative protein fortification launches.
- Vanilla Cake Mix:Neutral base formulations support customization through frosting and filling pairings, anchoring private-label portfolios in European supermarket channels.
- Red Velvet Cake Mix:Cocoa-tinted formulations with cream cheese frosting associations target celebration occasions in United States and Japanese markets.
Chocolate cake mix holds the largest share; momentum sits with gluten-free cake mix.
Distribution Channel:
Cost tier differentiation separates premium subscription models from mass-market retail economics.
- Supermarkets:Shelf-space allocation reconfigures around private-label expansion and branded heritage positioning, with General Mills and Associated British Foods competing for end-cap placement in United States and United Kingdom channels.
- Online Retailers:Direct-to-pantry algorithms and auto-replenishment interfaces capture recurring revenue from millennial households in United States and United Kingdom urban centers, climbing the fastest among all channels.
- Specialty Stores:Curated assortments of clean-label and allergen-free variants serve health-conscious consumers in German and Japanese metropolitan markets.
- Convenience Stores:Single-serve pouch formats target impulse purchases and emergency bake occasions in high-traffic urban locations.
Supermarkets retain volume leadership; online retailers gain share fastest through subscription bundling.
End User:
Application requirements diverge sharply between home bakers seeking foolproof outcomes and professionals demanding batch consistency.
- Households:Convenience-driven purchasers dominate volume, with sustained pantry-stocking behavior in United States, German, and Japanese markets stabilizing demand volatility post-pandemic.
- Bakeries:Commercial formulations require precise crumb density and moisture parameters, with Grupo Bimbo supplying cost-optimized bulk formats across Latin American foodservice networks.
- Restaurants:Dessert menu standardization drives demand for consistent bake outcomes with minimal labor input.
- Catering Services:Volume-scale procurement favors bulk packaging with extended shelf stability for event-based production cycles.
Households anchor consumption volume; bakeries present the steepest expansion trajectory through foodservice channel growth.
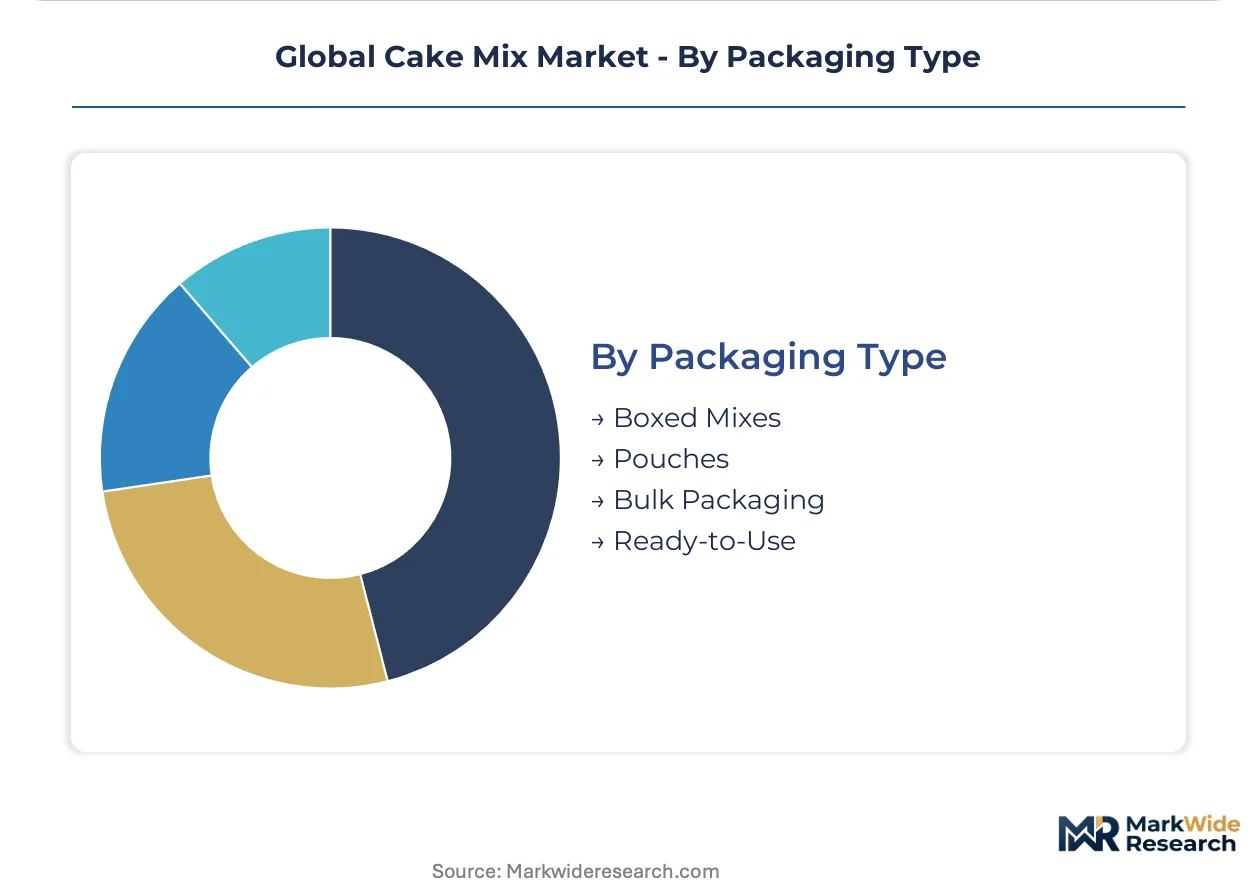
Packaging Type:
Supply concentration in paperboard and flexible film supply chains shapes format availability across price tiers.
- Boxed Mixes:Traditional paperboard cartons with inner moisture barriers support retail shelf presence and brand billboard effects in United States and European supermarkets.
- Pouches:Flexible film formats reduce material cost and shipping cube, gaining traction in online retail and convenience channels.
- Bulk Packaging:Foodservice sacks and totes serve bakery and catering procurement with per-unit cost optimization.
- Ready-to-Use:Pre-hydrated refrigerated formats eliminate consumer error but constrain distribution radius through cold-chain requirements.
Boxed mixes maintain format dominance; pouches are displacing rigid packaging fastest through e-commerce channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainability frameworks and FDA labeling mandates are reshaping formulation requirements across major consumption centers, while divergent fortification standards create distinct compliance pathways in emerging markets.
United States
Pantry-stocking behavior among households sustains baseline demand volatility post-pandemic, with chocolate and vanilla segments facing steep compositional adjustments. FDA updated guidance on "healthy" nutrient content claims tightens added sugar thresholds for voluntary labeling. Minneapolis-based General Mills leverages Betty Crocker heritage to sustain brand loyalty across North American retail channels.
Germany
Clean-label adoption in metropolitan markets drives demand for enzyme-based leavening systems and spray-dried fat encapsulation technology. EFSA novel food assessments delay alternative protein fortification launches, compressing R&D timelines for reformulated portfolios. Premium private-label manufacturers in Bavaria and North Rhine-Westphalia adopt pharmaceutical-grade excipient systems to support extended supply chain reach.
Japan
Celebration-occasion purchasing sustains red velvet and customized base formulations in urban households. METI standards for food labeling and sustainability disclosures align with consumer expectations for transparent ingredient sourcing. Tokyo and Osaka industrial clusters concentrate formulation expertise for moisture-retention calibration across diverse bake environments.
India
Urban retail penetration expands as mandatory micronutrient enrichment under BIS fortification standards creates compliant product demand. FSSAI enforcement of labeling and safety protocols accelerates formalization of previously fragmented domestic supply. Maharashtra and Gujarat manufacturing hubs scale cost-optimized packaging formats for mass-market distribution.
Brazil
Foodservice channel growth through bakery and catering procurement drives demand for bulk packaging with extended shelf stability. ANVISA regulatory frameworks for food additives and fortification align with regional formulation preferences. São Paulo and Minas Gerais production centers anchor Grupo Bimbo's Latin American supply network for localized flavor variants.
Global Cake Mix Market Vendor Landscape
On the supply side, the industry is consolidating around heritage brands with deep retail relationships and diversified ingredient suppliers with backward integration into raw material sourcing. Three strategic archetypes dominate: multinational CPG conglomerates with portfolio breadth, regional baking specialists with flavor localization expertise, and commodity processors with captive supply chains. Competitive intensity manifests through private-label expansion into premium tiers and direct-to-pantry subscription bundling that bypasses traditional retail gatekeepers.
Among North American CPG conglomerates, General Mills and Conagra Brands exemplify heritage-brand positioning that leverages decades of consumer trust to defend shelf space against private-label encroachment. Associated British Foods occupies a position bridging European supermarket dominance with foodservice supply chain penetration. Grupo Bimbo anchors the Latin American mass-market vector through scale-driven manufacturing and localized portfolio adaptation.
| Leading Market Players |
|---|
| General Mills |
| Conagra Brands |
| ADM |
| Associated British Foods |
| Cargill |
| Dawn Food Products |
| Chelsea Milling Co. |
| Grupo Bimbo |
| Dr. Oetker |
| Others |
Supply Flow & Price Mechanics
Wheat futures volatility and Malaysian-Indonesian palm oil supply concentration determine both pricing tier spreads and supply chain configuration for cake mix manufacturers. Hard red winter wheat price swings compress margin predictability across standard flour-based formulations, while geopolitical friction in Southeast Asian emulsifier sourcing forces dual-track procurement strategies that reshape cost structures.
Pricing Analysis
Certification level creates the primary spread between premium clean-label tiers and economy formulations. Three-tier pricing structure across premium enzyme-leavened, standard phosphate-based, and private-label economy levels separates buyers by ingredient transparency preference. Pricing pressure stems from FDA added-sugar threshold compliance costs and reformulation investments. Household purchasers in United States urban centers show highest price sensitivity, while German specialty store channels absorb premium markups for EFSA-compliant portfolios.
Supply Chain Analysis
Upstream wheat sourcing draws from United States hard red winter belts, Canadian prairie provinces, and Australian export corridors. Rice flour and tapioca starch for gluten-free variants hinge on Thai and Vietnamese milling capacity. Single-source vulnerability concentrates in Malaysian-Indonesian palm oil derivatives for emulsifier production. Distribution runs through supermarket centralized distribution centers in North America and Europe, with direct-to-pantry subscription platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retailer consolidation into omnichannel purchasing coalitions shifts negotiating leverage toward buyers, fragmenting manufacturer pricing power across United States and European markets.
For Market Incumbents: Insulate margin structures through backward integration into certified palm oil sourcing and enzyme-based leavening R&D. General Mills and Associated British Foods must defend against private-label encroachment by locking end-cap placement through multi-year category captain agreements. Capacity addition in Maharashtra and Gujarat manufacturing hubs addresses Indian BIS fortification compliance while reducing logistics exposure. For New Entrants and Emerging Players: Establish a beachhead in gluten-free subscription bundling among United Kingdom celiac-aware households and United States voluntary wheat-avoidance segments. Direct-to-pantry algorithms offer the most penetrable channel, bypassing supermarket slotting fee barriers. Algae-derived emulsifier positioning unlocks premium tier access with clean-label differentiation. For Investors and Strategic Acquirers: EU Green Deal deforestation-free verification deadlines reshape the acquisition landscape toward suppliers with certified supply chain documentation. Five-to-ten year viability favors enzyme biotechnology specialists and regional flavor localization platforms over commodity flour processors. Monitor EFSA novel food assessment timeline acceleration as inflection signal for alternative protein fortification plays.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | FDA and EFSA compliance investments unlock premium positioning in United States and German retail channels. |
| Direct-to-Pantry Subscription Launch | Auto-replenishment algorithms capture recurring revenue from millennial households in United Kingdom urban centers. |
| Certified Palm Oil Backward Integration | EU Green Deal verification requirements mandate deforestation-free supply chain control for European market access. |
| Gluten-Free Production Line Expansion | Rice flour and tapioca starch handling capacity addresses fastest-expanding segment in celiac-aware demographics. |
| India BIS Fortification Compliance | Mandatory micronutrient enrichment creates first-mover advantage in underpenetrated Maharashtra and Gujarat retail. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers at General Mills and Associated British Foods, category buyers at United States and United Kingdom supermarket chains, supply planners at Grupo Bimbo, and food technologists specializing in enzyme stabilization. Secondary validation drew from FDA labeling guidance documents, EFSA novel food assessment registers, BIS fortification standards, and customs trade data for wheat and palm oil derivatives. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Calibration anchored historical consumption patterns to forward-looking regulatory milestone impacts across the analysis window. Segmentation dimensions modeled included product type, distribution channel, end-user application, and packaging format. CAGRs derived from elasticity-adjusted volume projections incorporating pantry-stocking behavior persistence and clean-label adoption curves. Wheat futures volatility and EFSA approval timeline uncertainty fed directly into scenario-weighted outputs.
Sensitivities concentrate around hard red winter wheat price spikes, Malaysian-Indonesian palm oil supply disruptions, and EFSA novel food assessment delays. Forecasts reflect documented assumptions on regulatory enforcement intensity and consumer clean-label willingness-to-pay thresholds. Cross-checking against Nielsen retail audit data and customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Ice Cream Cones Market
Bakery Products
Bread Premix Market
Bakery Products
Packaged Bread Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Instant Cake Gel Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Bakery Improvers Market
Bakery Products
Ice Cream Cake Market
Bakery Products
On-The-Go Breakfast Products Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Europe Sourdough Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bread Mix Market