
 Gluten-Free Bakery Premixes Market | 2026-2036
Gluten-Free Bakery Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Bakery Premixes Market Intelligence
A scarcity of skilled food technologists specializing in hydrocolloid and alternative flour formulation is reorganizing the competitive landscape. This capability gap favors large-scale producers with dedicated research and development teams. Bakels Worldwide leverages its extensive distribution network to serve industrial bakeries across numerous countries. Lesaffre Australia Pacific Pty Ltd differentiates through its expertise in yeast and fermentation-derived ingredients for improved bread texture.
Gluten-free bakery premixes are formulated dry blends of ingredients designed to replace traditional wheat flour in baking applications. These formulations combine alternative flours, such as rice or corn, with starches and hydrocolloids like xanthan gum to replicate the structure and texture normally provided by gluten. The breads category represents a foundational product segment, driven by its status as a dietary staple. Demand from commercial bakeries and food service establishments is expanding faster than the home baker segment.
Allergen labeling mandates from regulators like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) are fundamental to market access. These regulations define the 'gluten-free' claim, typically setting a maximum threshold of 20 parts per million of gluten, which dictates production and testing protocols. Future competitive advantage will hinge on developing clean-label premixes that reduce reliance on modified starches and artificial additives.
Market Dynamics
The market's central dynamic is the technical capability gap in gluten-free formulation. A scarcity of food technologists skilled in using hydrocolloids and alternative flours to mimic gluten's properties creates a high barrier to entry, favoring large producers with established R&D infrastructure.
Growth Catalysts
- Stringent Labeling Regulations:Mandates from bodies like the US FDA and the European Commission, which define the "gluten-free" claim, build consumer confidence and compel food manufacturers to source certified premixes, directly stimulating demand.
- Food Service Sector Expansion:Restaurants and commercial bakeries are broadening their menus to cater to diners with celiac disease or gluten sensitivity, creating a substantial B2B demand channel that is outpacing the home-use segment.
- Concentrated European Demand:Significant market penetration and consumer awareness in key countries, particularly Germany and the United Kingdom, act as a powerful engine for regional growth and product innovation.
Market Restraints
- Input Cost Volatility:Alternative flours like almond or quinoa and functional hydrocolloids such as xanthan gum have higher and more volatile pricing than traditional wheat flour, compressing manufacturer margins.
- Specialized Talent Shortage:A limited pool of food scientists with expertise in gluten-free formulation restricts the ability of small and mid-sized enterprises to innovate and compete on product quality and texture.
- Technical Performance Gaps:Achieving the desired taste, texture, and shelf-life comparable to conventional baked goods remains a significant technical hurdle, which can limit broader consumer adoption beyond the core medical-need segment.
Strategic Opportunities
- Clean-Label Formulations:There is a significant market opportunity in developing premixes that eliminate modified starches, artificial flavors, and preservatives, appealing to health-conscious consumers seeking minimally processed foods.
- Specialized Pastry Applications:Expanding beyond bread to create high-performance premixes for delicate applications like laminated doughs, choux pastry, or Viennoiserie represents an untapped, high-value market segment.
- Growth in Latin American Markets:Rising disposable incomes and wellness trends in countries such as Brazil and Mexico present an underpenetrated geographic region for market expansion, particularly within urban centers.
Industry Challenges
- Cross-Contamination Risk Management:Maintaining a certifiably gluten-free supply chain requires dedicated production lines and stringent handling protocols, posing a significant operational and capital investment challenge for manufacturers.
- Compliance and Testing Burden:The need for frequent, rigorous batch testing to verify gluten levels below the 20 parts per million threshold dictated by regulators like EFSA imposes ongoing operational costs and complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Bakery Premixes Market |
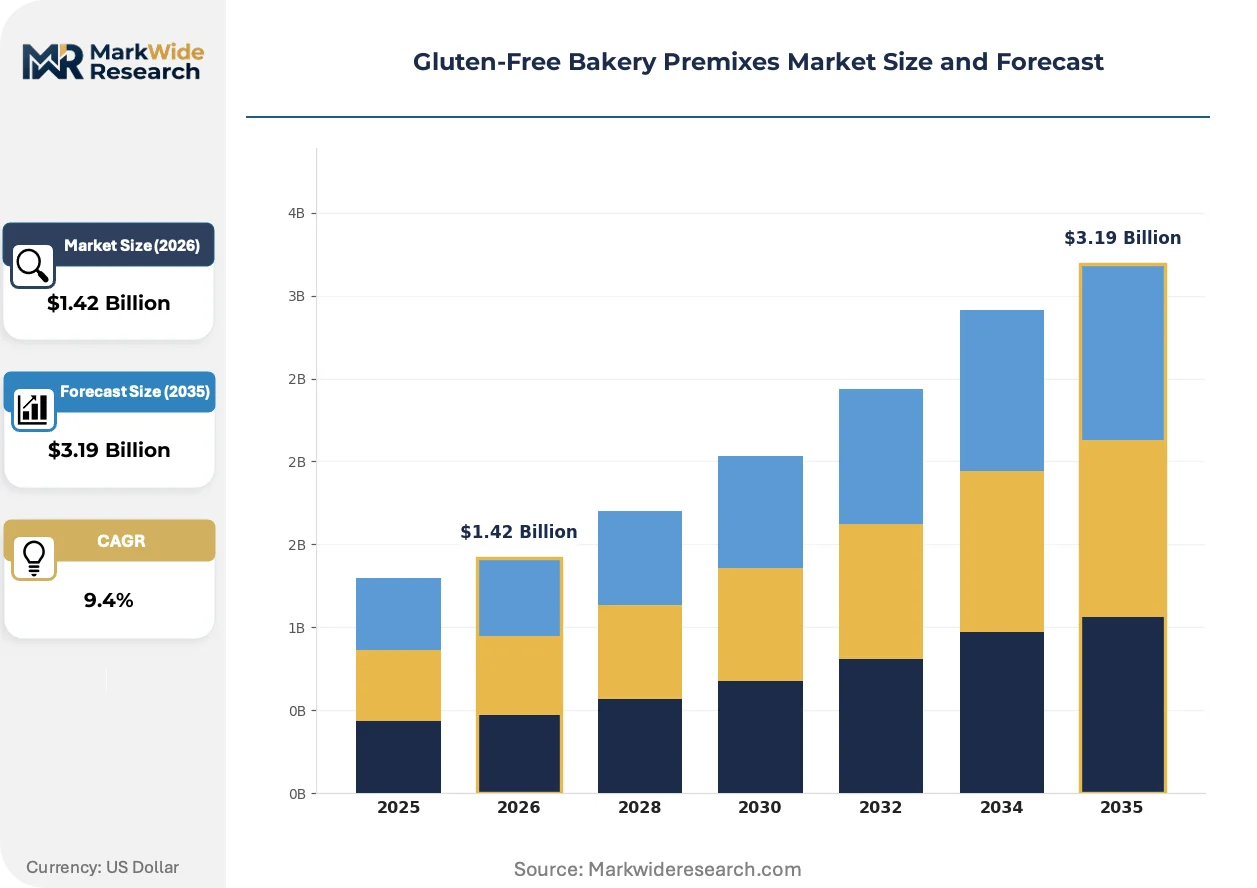
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.19 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Cakes, Muffins, Pancakes Ingredient Type: Flours, Starches, Sweeteners, Binders End User: Bakeries, Restaurants, Home Bakers, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Lesaffre Australia Pacific Pty Ltd, Theodor Rietmann Gmbh, Myosyn Industries, Bakels Worldwide, Caremoli, MELINDA'S GLUTEN FREE GOODIES, Naturally Organic, Watson Inc., Choices Gluten-free, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Bakery Premixes Market Strategic Shifts & Innovations
The evolution of gluten-free premixes is driven by a convergence of material science and consumer demand for cleaner labels. Ingredient innovation is focused on improving functionality to more closely replicate the properties of gluten without relying on artificial additives or complex chemical compounds.
Advanced enzyme cocktails and novel hydrocolloid systems are being engineered to enhance dough rheology, gas retention, and moisture control. Industrial bakeries and food service providers are the primary adopters, seeking to improve product consistency and extend the shelf life of finished goods. This sophisticated ingredient science is supplanting older formulations that depended heavily on modified starches and a combination of multiple gums to achieve structure.
Allergen labeling requirements are becoming increasingly stringent, extending beyond just gluten. Regulations like the US Food Allergen Labeling and Consumer Protection Act (FALCPA) and parallel EU directives mandate greater transparency for all ingredients. This forces premix producers to provide meticulous documentation for their entire supply chain. The breads and cakes category is most impacted, as manufacturers must now manage and declare a wider array of potential allergens.
A notable behavioral shift is underway as procurement models evolve from transactional purchases to strategic partnerships. Large buyers in the food service and industrial bakery sectors are increasingly seeking customized premix formulations through long-term supply contracts. This trend disrupts traditional distribution channels that primarily served smaller, independent bakeries and the retail segment. The shift is most pronounced in North America, where restaurant chains demand standardized product quality across numerous locations.
Gluten-Free Bakery Premixes Market Segmentation
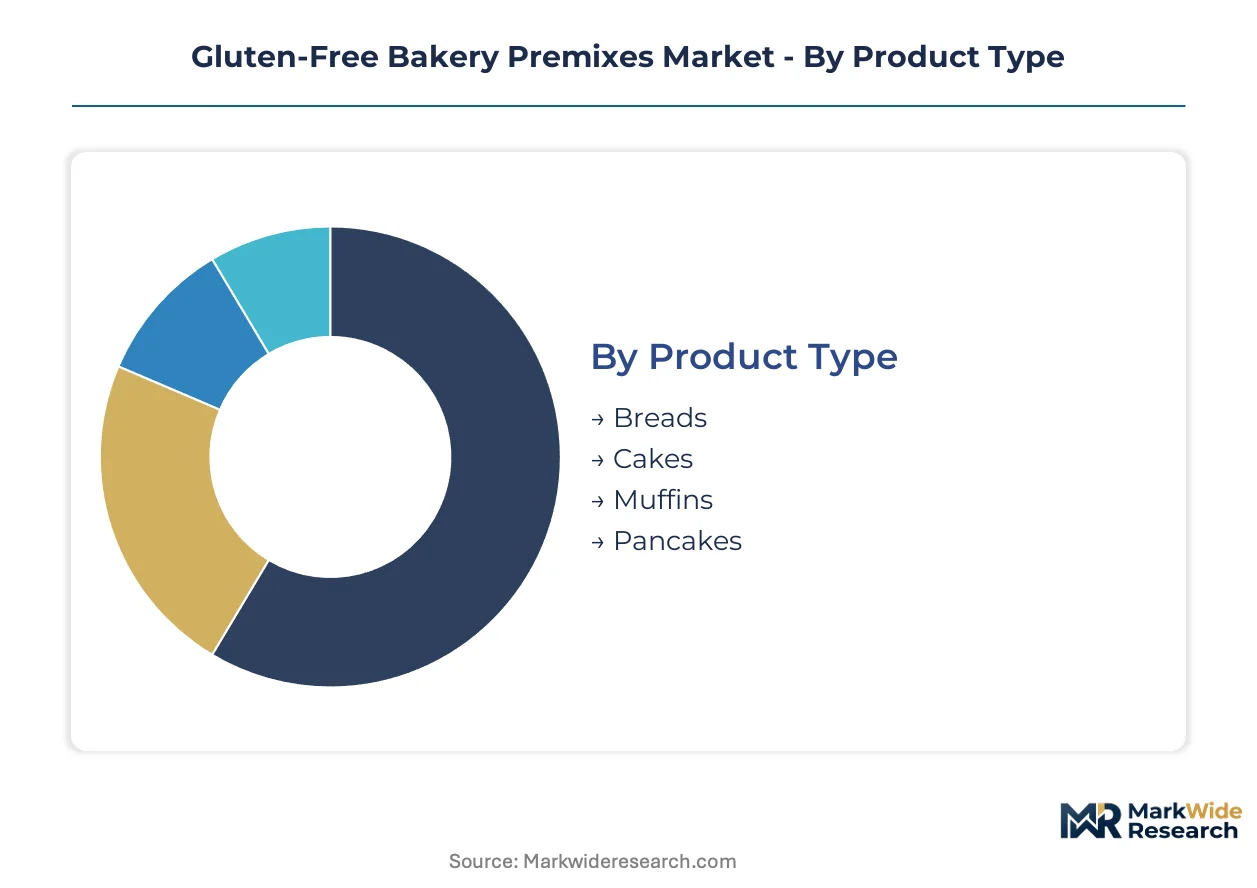
Segmentation helps define market dynamics within the gluten-free bakery premixes sector. Understanding distinct product types, ingredient compositions, end-user preferences, and distribution pathways illuminates varying demand drivers. This granular view allows producers to tailor offerings and distribution strategies effectively across different market niches.
Product Type:
The gluten-free bakery premixes market faces substitution pressure across product types, where consumers often compare premix performance against traditional gluten-containing counterparts.
- Breads:These premixes are engineered to mimic gluten's structure, elasticity, and gas retention in staple bread products. Demand from commercial bakeries and food service establishments in the United Kingdom drives innovation for improved texture and shelf life.
- Cakes:Formulations for cakes focus on achieving a light, moist crumb and consistent rise without gluten. Growth in Germany's food service sector encourages the development of versatile cake premixes for broad menu integration.
- Muffins:Premixes for muffins emphasize moisture retention and a tender crumb, catering to both industrial and home baking needs.
- Pancakes:Pancake premixes prioritize ease of preparation and consistent texture for breakfast and brunch applications across various settings.
Breads anchors the volume base while Cakes gains share at the steepest rate.
Ingredient Type:
Ingredient types exhibit varying supply chain concentrations, influencing both cost structures and formulation flexibility for gluten-free bakery premixes.
- Flours:Alternative flours like rice, corn, or almond form the bulk of gluten-free premix formulations, providing foundational structure and flavor. Industrial bakeries in North America prioritize consistent supply and specific grain blends for product differentiation.
- Binders:Hydrocolloids such as xanthan gum and guar gum are critical binders, replicating gluten's viscoelastic properties and improving dough rheology. European premix manufacturers focus on clean-label binder solutions to meet evolving regulatory standards.
- Starches:Modified and native starches, including tapioca and potato, enhance texture, moisture retention, and shelf life in many gluten-free applications.
- Sweeteners:These ingredients, ranging from natural sugars to artificial alternatives, contribute to taste profiles and browning characteristics in various premix formulations.
Flours directly influence bulk costs, while Binders demonstrate higher margin sensitivity due to their specialized functional role.
End User:
End-user segments define distinct application requirements and volume demands for gluten-free bakery premixes.
- Bakeries:Commercial bakeries require large-scale, consistent premix solutions for diverse product lines, focusing on operational efficiency and scalability. Demand from German industrial bakeries emphasizes premixes that integrate seamlessly into automated production lines.
- Food Service:Restaurants and catering operations seek versatile, easy-to-use premixes to expand gluten-free menu options and ensure consistent quality across locations. US restaurant chains drive innovation in premixes that deliver reliable performance and quick preparation.
- Home Bakers:This segment values convenience, clear instructions, and reliable results for smaller-scale, personal gluten-free baking projects.
- Restaurants:Food establishments require consistent, high-performance premixes to cater to gluten-sensitive diners and expand their menu offerings.
Food Service exhibits the steepest expansion trajectory, while Home Bakers maintain a stable, niche demand profile.
Distribution Channel:
Distribution channels reflect varying levels of market maturity and customer purchasing behaviors for gluten-free bakery premixes.
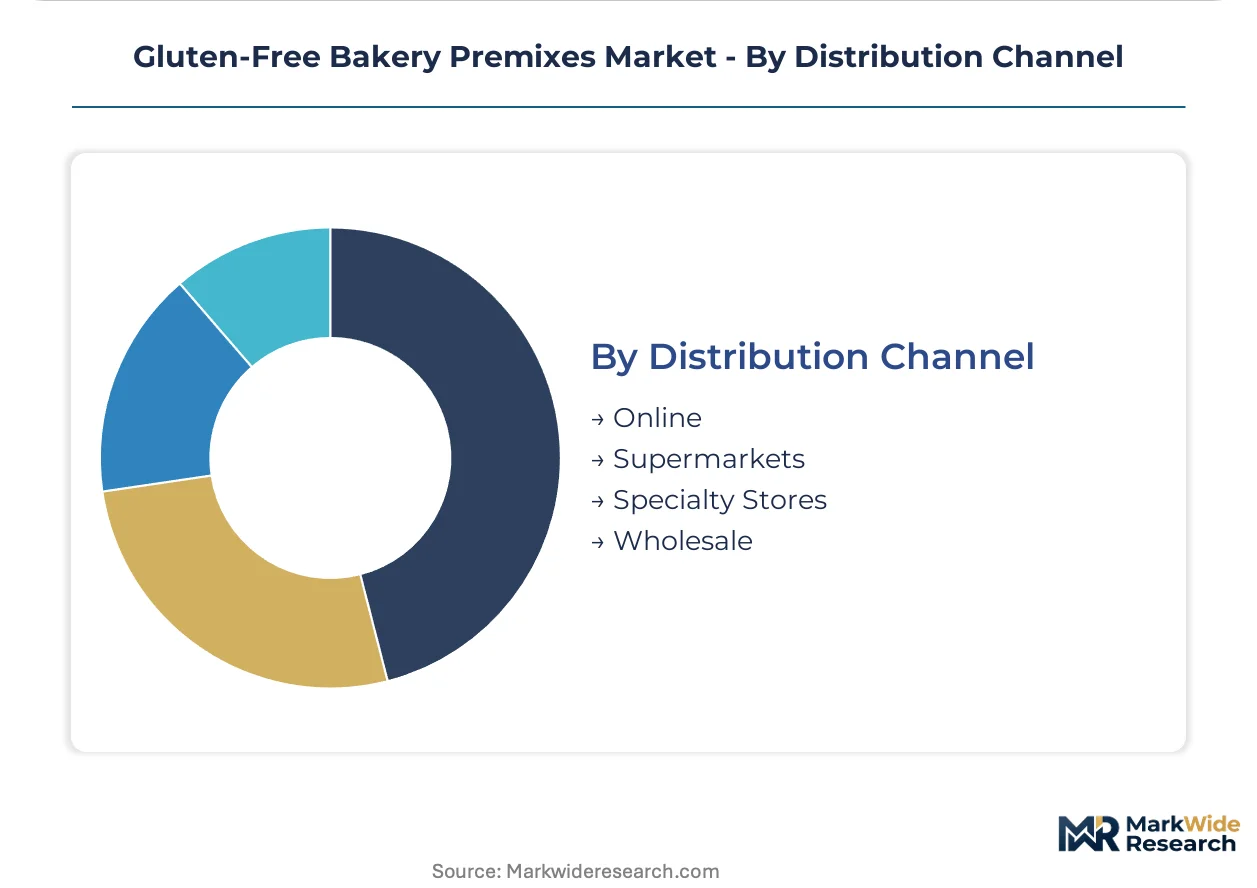
- Wholesale:This channel serves industrial bakeries and large food service providers, prioritizing bulk quantities, competitive pricing, and reliable supply chain logistics. Bakels Worldwide leverages this channel extensively for its global reach.
- Online:E-commerce platforms offer broad accessibility and convenience, reaching both individual consumers and smaller businesses with specialized gluten-free needs. Growth in European markets like Germany demonstrates strong online adoption for niche ingredients.
- Supermarkets:Retail grocery stores provide mainstream access for home bakers and convenience-oriented consumers seeking readily available gluten-free premixes.
- Specialty Stores:These outlets cater to consumers with specific dietary requirements, offering curated selections and expert advice on gluten-free products.
Wholesale optimizes for large-volume efficiency, while Online channels demonstrate rapid growth in consumer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gluten-free bakery premixes market has varied consumption patterns globally. Some regions prioritize industrial bakery applications, while others show strong growth in food service. This differential shapes regional demand and product development strategies.
United States
Demand for gluten-free bakery premixes in the United States reflects expanding food service menus. The US FDA's stringent labeling regulations build consumer confidence in product integrity. Restaurant chains in major metropolitan areas like New York and Los Angeles are driving innovation for consistent, high-performance premixes.
Germany
Germany's market for gluten-free bakery premixes emphasizes industrial bakery applications and consistent quality. The European Commission's 20 ppm gluten threshold ensures product safety and consumer trust. Industrial bakeries in regions like Bavaria and North Rhine-Westphalia integrate premixes into automated production lines.
United Kingdom
The United Kingdom shows strong demand for gluten-free bread premixes, catering to a growing consumer base with dietary needs. EFSA guidelines for allergen labeling compel manufacturers to ensure product compliance. Commercial bakeries in London and Manchester seek improved texture and extended shelf life for staple bread products.
Brazil
Brazil's gluten-free bakery premixes market is expanding due to rising disposable incomes and wellness trends. ANVISA regulations for food labeling provide clarity for consumers seeking gluten-free options. Urban centers like São Paulo and Rio de Janeiro are experiencing increased demand for diverse gluten-free baked goods.
Mexico
Mexico exhibits significant potential for gluten-free bakery premixes, driven by health-conscious consumers and evolving dietary preferences. The country's health authorities enforce labeling standards for gluten-free products. Food service establishments in Mexico City and Guadalajara are broadening their menus to include gluten-free offerings.
Gluten-Free Bakery Premixes Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the gluten-free bakery premixes market. This tiered structure reflects varying capabilities in R&D, production scale, and supply chain management. Strategic archetypes include large-scale ingredient suppliers, specialized texture solution providers, and niche formulators focusing on clean-label solutions. Geographic expansion and strategic partnerships are dominant competitive moves as companies seek to broaden their market reach and product portfolios.
Among the established ingredient suppliers, Bakels Worldwide exemplifies a global distribution network, serving industrial bakeries across numerous countries with its extensive product range. Lesaffre Australia Pacific Pty Ltd, an Australian entity, occupies a position as a specialist in yeast and fermentation-derived ingredients, enhancing bread texture and structure. Germany-based Theodor Rietmann Gmbh represents a traditional European premix manufacturer, catering to diverse baking needs with its regional focus. These companies anchor different facets of the market, from broad-scale ingredient supply to specialized functional additive provision and regional market penetration.
| Leading Market Players |
|---|
| Lesaffre Australia Pacific Pty Ltd |
| Theodor Rietmann Gmbh |
| Myosyn Industries |
| Bakels Worldwide |
| Caremoli |
| MELINDA'S GLUTEN FREE GOODIES |
| Naturally Organic |
| Watson Inc. |
| Choices Gluten-free |
| Others |
Cost & Logistics Intelligence
Large-scale production facilities benefit from economies of scale, leading to more competitive gluten-free premix pricing. This capacity concentration, especially among major ingredient suppliers, influences market price floors and supply stability for industrial buyers.
Pricing Analysis
Long-term offtake agreements characterize pricing for industrial bakeries, securing consistent supply for large-volume purchasers. Price differentiation arises from volume scale and the level of customization in premix formulations for specific applications. Pricing softness stems from input cost volatility for alternative flours like almond or quinoa, compressing manufacturer margins. Home bakers exhibit the highest price sensitivity, contrasting with the lower sensitivity of large food service establishments.
Supply Chain Analysis
China produces a significant portion of hydrocolloids, while North America and Europe cultivate key alternative flours. The supply chain relies on diverse agricultural inputs like rice, corn, and almond flours, alongside functional hydrocolloids such as xanthan gum. Commodity price volatility for these specialized ingredients constitutes a primary supply chain risk. Wholesale channels dominate distribution to industrial bakeries, while online platforms increasingly serve smaller businesses and home bakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gluten-free bakery premixes market requires strategic defense against the continued dominance of traditional gluten-containing baked goods. Incumbents must navigate consumer perception and technical performance gaps compared to conventional offerings.
For Market Incumbents:Fortify R&D capabilities in advanced enzyme cocktails and novel hydrocolloid systems to close technical performance gaps in texture and taste. Invest in dedicated, certified gluten-free production lines to mitigate cross-contamination risks and meet stringent regulatory standards like those from the US FDA. This proactive approach defends against the persistent challenge of mimicking traditional gluten properties. Control over specialized ingredient sourcing also enhances product consistency.
For New Entrants and Emerging Players:Differentiate on clean-label formulations, reducing reliance on modified starches and artificial additives for health-conscious consumers. Target specialized pastry applications like laminated doughs or choux pastry, which represent high-value, underserved niches. The food service sector in Latin American markets, particularly urban centers in Brazil and Mexico, offers a penetrable segment for innovative, high-performance premixes. Focus on convenience and consistent quality for restaurant chains.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among ingredient suppliers with proprietary functional blends serving industrial bakeries through long-term contracts. The market offers long-term viability, driven by expanding dietary needs and the food service sector's menu diversification. Investors should seek mid-sized specialists possessing unique hydrocolloid systems or proven clean-label formulation expertise. Increased M&A activity focused on specialized ingredient IP will signal market consolidation and value creation.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Novel Hydrocolloids | Enhances texture and elasticity in gluten-free breads, addressing a key technical performance gap for European bakeries. |
| Dedicated Gluten-Free Production Lines | Ensures compliance with US FDA 20 ppm gluten thresholds, building consumer trust and market access. |
| Expansion into Latin American Food Service | Captures demand from rising wellness trends in urban centers like São Paulo and Mexico City. |
| Clean-Label Premix Development | Appeals to health-conscious consumers seeking minimally processed foods, expanding market adoption. |
| Strategic Partnerships with Industrial Bakeries | Secures long-term supply contracts and facilitates customized formulations for large-scale operations. |
Research Approach
Initial hypotheses were tested against primary input from food technologists, industrial bakery procurement managers, and ingredient supplier R&D directors, then refined through iterative feedback. This primary research was validated using secondary sources including US FDA guidance documents, European Commission regulations, and academic food science journals. The analysis integrated both bottom-up market sizing and top-down validation to ensure data integrity.
Variance decomposition identified key drivers impacting market expansion across the analysis window. The analytical framework modeled gluten-free bakery premixes across product types, ingredient compositions, end-user segments, and key geographic regions. Compound annual growth rates were derived from historical data and projected forward based on identified growth catalysts. Gluten-free labeling compliance rates and alternative flour price trends served as critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside major shifts in regulatory standards or unforeseen supply chain disruptions would require recalibration. Forecasts reflect assumptions regarding consumer adoption rates and ingredient cost stability over the projection horizon. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Vegan Baking Mix Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Ice Cream Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Biscuits Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Bakery Premixes Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
United States Bread Market
Bakery Products
United States Cookies Market
Bakery Products
Bakery Flavors Market
Bakery Products
Bake Stable Pastry Fillings Market