
 Low Fat Baked Goods Market | 2026-2036
Low Fat Baked Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Baked Goods Market Analytics
Oat fiber is consolidating its position as the preferred structural replacement for conventional fat mimetic systems in reduced-fat cake and muffin formulations. General Mills leverages its grain milling infrastructure to secure captive supply of specialty oat fractions for bakery applications. Mondelez International competes through proprietary emulsion technology that preserves mouthfeel in low-fat cookie recipes without hydrogenated oils.
Low fat baked goods are formulated food products containing no more than three grams of fat per serving, achieved through modified lipid content, hydrocolloid stabilizers, and controlled moisture profiles during baking to maintain structural integrity and sensory acceptance. The ingredient type dimension shows sugar substitutes and low-fat dairy commanding the deepest margin pools as brands reformulate around clean-label positioning. Whole wheat flour and oats represent the fastest-growing input categories as manufacturers respond to fiber-forward nutrition claims in the customer segment targeting health-conscious consumers and weight watchers.
The FDA governs nutrient content claims including "low fat" labeling thresholds under 21 CFR 101.62, while the USDA oversees school nutrition standards that expand institutional procurement of compliant baked snacks. The EU Green Deal and EFSA nutrition profiling criteria shape reformulation roadmaps for exporters serving European supermarkets and specialty stores. Stakeholders must monitor evolving trans-fat restrictions and front-of-pack labeling mandates that will determine which ingredient technologies retain market access across major distribution channels.
Market Dynamics
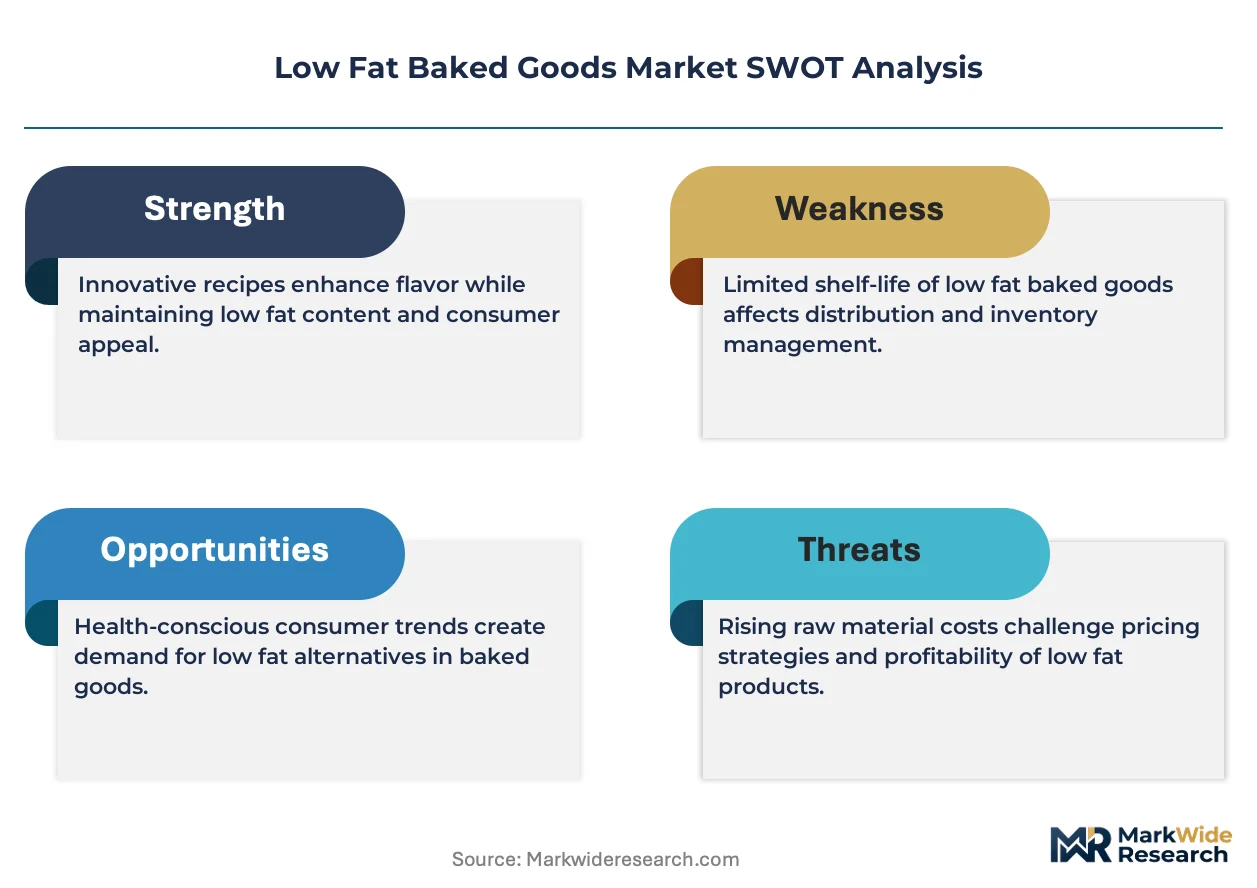
Clean-label reformulation mandates from the EU Green Deal and FDA nutrition labeling updates are compressing formulation cycles across the low fat baked goods sector, forcing manufacturers to rebuild emulsion systems without hydrogenated oils or artificial stabilizers.
Growth Catalysts
- REACH chemical safety standards:The EU's phased restrictions on synthetic emulsifiers accelerate natural hydrocolloid adoption in reduced-fat cake formulations.
- School nutrition procurement:USDA-compliant baked snack mandates expand institutional volume for low-fat muffin and cookie suppliers.
- Oat fractionation technology:Advanced milling processes unlock beta-glucan concentrates that replicate fat mouthfeel in clean-label positioning.
Market Restraints
- Specialty grain supply concentration:Premium oat fiber sourcing clusters in Nordic and North American growing regions, exposing margins to climate volatility.
- Trans-fat elimination technical barriers:Full hydrogenated oil phase-out degrades shelf stability in certain cookie applications without costly reformulation.
- Sugar substitute regulatory fragmentation:EFSA and FDA diverge on novel sweetener approvals, complicating pan-regional product lines.
Strategic Opportunities
- Japan functional foods channel:FOSHU certification pathways reward low-fat, high-fiber bakery claims with premium retail placement.
- Direct-to-consumer subscription models:Fresh-baked delivery platforms bypass conventional retail slotting fees for niche dietetic brands.
- CSRD supply chain disclosure:Early compliance with EU corporate sustainability reporting creates competitive differentiation in European supermarket tenders.
Industry Challenges
- Clean-label emulsion science talent:Formulation chemists skilled in natural stabilizer systems command scarce availability and elevated compensation.
- Front-of-pack labeling compliance timelines:Nutri-Score and traffic-light system adoption across EU member states demands rapid packaging redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Baked Goods Market |
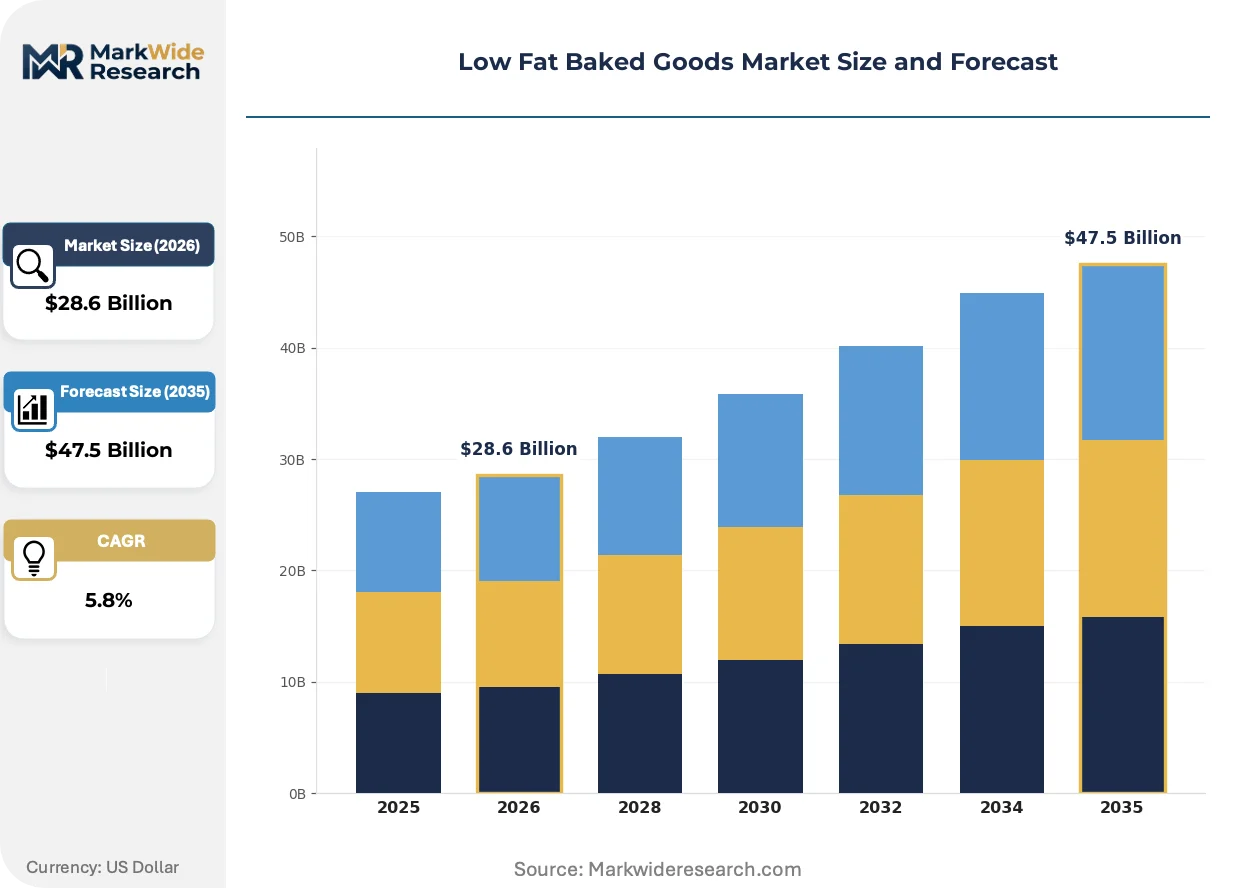
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Muffins, Cakes, Snacks Ingredient Type: Whole Wheat Flour, Sugar Substitutes, Low-Fat Dairy, Oats Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores Customer Segment: Health-Conscious Consumers, Diabetics, Weight Watchers, Families |
| Companies Covered | Nestlé S.A., General Mills, Inc., Mondelez International, Kraft Heinz Company, Danone S.A., Grupo Bimbo S.A.B. de C.V., Arla Foods, Unilever PLC, Britannia Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Baked Goods Market Evolving Landscape
Reformulation science is pivoting from simple fat reduction to integrated texture-engineering platforms that simultaneously address clean-label, fiber-enrichment, and extended shelf-life requirements in a single ingredient system.
Precision fermentation-derived proteins are electrifying structural replacement strategies in reduced-fat pastries. Artisan and industrial bakeries in Germany and California are piloting these ingredients at commercial scale. The technology is electrifying R&D roadmaps by collapsing the trade-off between fat reduction and moisture retention that has constrained formulation freedom for decades.
The EU F-Gas Regulation's indirect pressure on industrial refrigeration is reshaping cold-chain bakery logistics. Manufacturers face accelerated capital replacement cycles for climate-controlled storage and transport assets. Frozen low-fat dough suppliers serving European retail and foodservice are responding with localized micro-bakery networks that reduce refrigeration dependency.
Urban health-conscious consumers are fragmenting purchase occasions across convenience, premium, and value channels simultaneously. Traditional supermarket bakery departments lose traffic to specialty dietetic retailers and direct-brand e-commerce. This behavioral split is most pronounced in Tokyo, London, and New York metropolitan areas where subscription fresh-baked services capture weekday breakfast occasions while premium artisan shops dominate weekend indulgence purchases.
Low Fat Baked Goods Market Segmentation
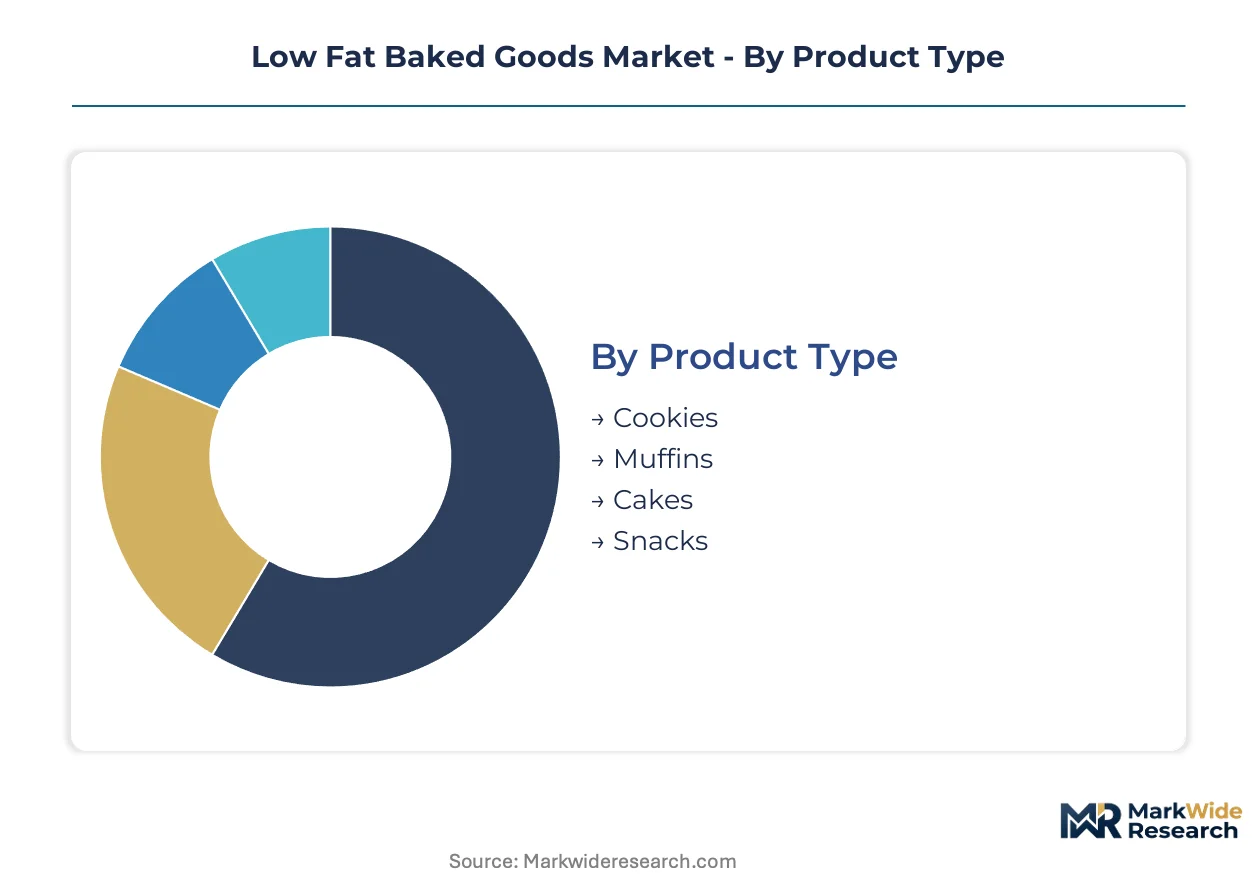
Segmentation in low fat baked goods determines reformulation priorities, margin architecture, and channel access. Each dimension carries distinct regulatory burdens and technical requirements that shape manufacturer investment decisions.
Product Type:
USDA school nutrition standards and FDA serving-size regulations impose divergent compliance burdens across product formats, with institutional channels demanding stricter fat thresholds than retail.
- Cookies:Hydrogenated oil phase-out has forced complete emulsion system rebuilds in reduced-fat formulations. Mondelez and General Mills compete through proprietary fat-mimetic technologies that preserve snap and mouthfeel without trans-fat content. Institutional procurement in US school districts drives volume for compliant sandwich cookies.
- Muffins:Moisture retention challenges dominate technical development, with oat fiber and beta-glucan concentrates replacing conventional shortening systems. German and Japanese bakeries lead commercialization of clean-label reduced-fat muffin platforms for convenience channel placement.
- Cakes:Aeration stability requirements complicate fat reduction without sacrificing crumb structure.
- Snacks:Shelf-life extension needs conflict with clean-label positioning in grab-and-go formats.
Leading the category by volume: Cookies. Growing fastest: Muffins.
Ingredient Type:
Cost tiers separate commodity inputs from specialty fractions, with premium oat derivatives and novel sweeteners commanding three-to-five-fold markups over conventional wheat and sucrose systems.
- Sugar Substitutes:EFSA and FDA divergence on novel sweetener approvals fragments formulation roadmaps for pan-regional brands. Stevia and monk fruit extracts dominate clean-label positioning, while allulose gains traction in US applications despite slower European regulatory clearance. Reformulation cycles accelerate as front-of-pack labeling mandates penalize added sugar content.
- Oats:Advanced fractionation unlocks beta-glucan concentrates that replicate fat mouthfeel while delivering fiber-forward nutrition claims. Nordic and North American supply concentration exposes margins to climate volatility. FOSHU certification in Japan rewards oat-enriched bakery claims with premium retail placement.
- Whole Wheat Flour:Commodity pricing and established supply chains support mass-market penetration.
- Low-Fat Dairy:Refrigerated distribution requirements limit channel flexibility compared to ambient-stable alternatives.
Deepest margin pool: Sugar substitutes. Steepest expansion trajectory: Oats.
Distribution Channel:
Customer acquisition economics vary dramatically by channel, with direct-to-consumer platforms bypassing slotting fees but demanding fulfillment infrastructure that erodes gross margins at scale.
- Supermarkets:Nutri-Score and traffic-light labeling compliance across EU member states forces rapid packaging redesign cycles. Retail bakery departments lose weekday traffic to convenience and online alternatives. German and UK chains lead private-label development of reduced-fat bakery lines.
- Online Stores:Subscription fresh-baked services capture health-conscious urban consumers in Tokyo, London, and New York metropolitan areas. Direct-brand e-commerce bypasses conventional retail margins but requires cold-chain logistics investment. Freshness guarantees compress delivery radii and necessitate localized micro-bakery networks.
- Specialty Stores:Dietetic and organic retailers command premium positioning for certified clean-label products.
- Convenience Stores:Extended shelf-life requirements favor preservative-containing formulations that conflict with clean-label trends.
Highest volume concentration: Supermarkets. Fastest channel expansion: Online stores.
Customer Segment:
Behavioral fragmentation splits purchase occasions across convenience, premium, and value tiers simultaneously, with urban consumers deploying different channels for weekday function versus weekend indulgence.
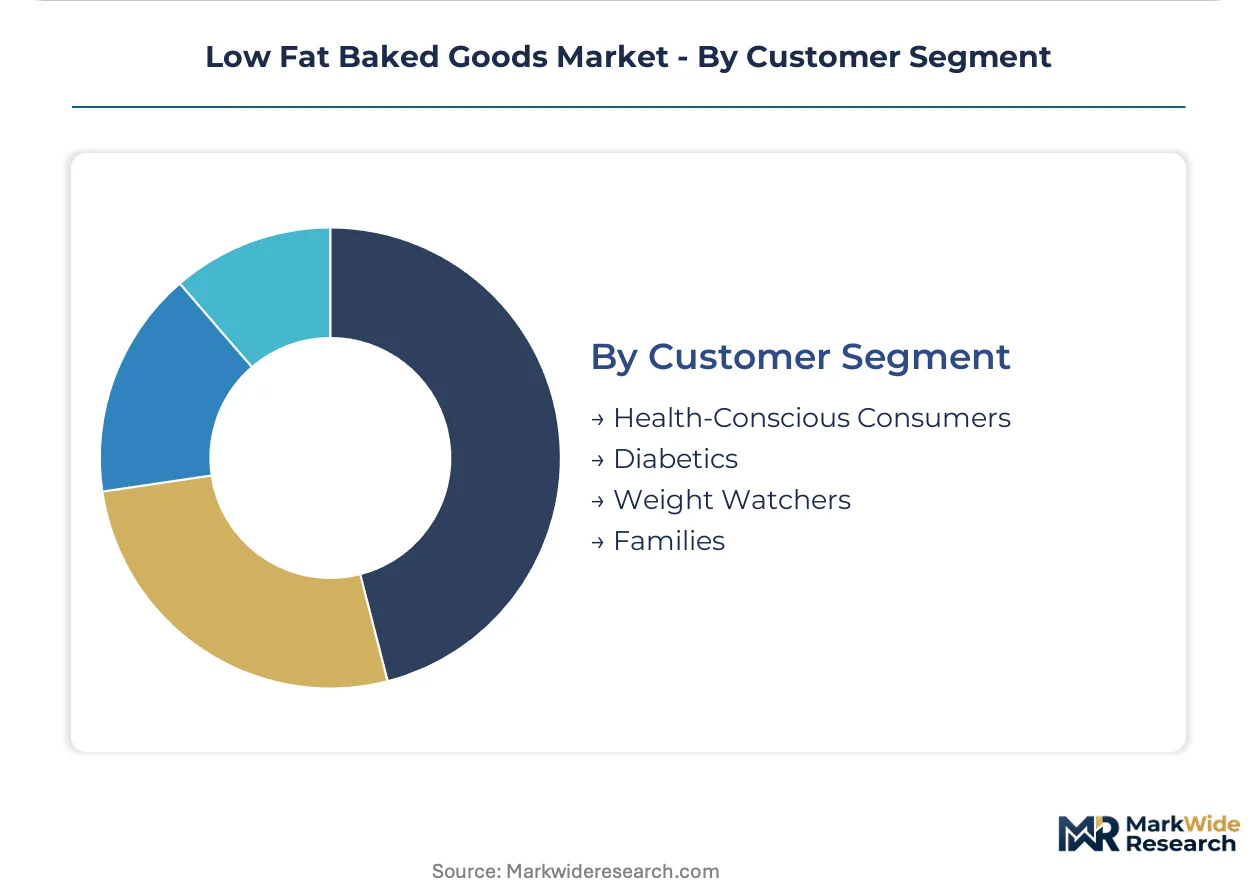
- Health-Conscious Consumers:Fiber-forward nutrition claims and clean-label positioning drive premium willingness-to-pay in Germany, Japan, and US coastal metros. This segment fragments purchases across specialty dietetic retailers, subscription services, and artisan shops depending on occasion. REACH-compliant formulations and EU Green Deal alignment influence brand switching.
- Weight Watchers:Calorie transparency and portion-controlled formats dominate purchase criteria. Reformulated products must balance satiety signaling with indulgence permission. USDA school nutrition procurement expands institutional volume for compliant portion-sized snacks.
- Diabetics:Glycemic index labeling and sugar substitute safety profiles determine product acceptance.
- Families:Value positioning and child-friendly palatability requirements constrain clean-label premiumization.
Largest addressable base: Health-conscious consumers. Most rapid segment growth: Weight watchers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban health-conscious consumers in Germany, the United States, and Japan concentrate demand for reformulated low-fat cookies and muffins with clean-label ingredient systems. Bakery innovation clusters in these markets drive oat-based fat replacement technologies and sugar substitute adoption.
United States
School nutrition procurement and weight management trends propel institutional and retail demand for compliant low-fat muffins and cookies. FDA serving-size regulations under 21 CFR 101.62 govern "low fat" labeling thresholds and nutrient content claims. Minneapolis-based General Mills leverages captive grain milling infrastructure to secure specialty oat fractions for reduced-fat bakery formulations.
Germany
EU Green Deal alignment and REACH chemical safety standards accelerate natural hydrocolloid adoption in clean-label cake and pastry reformulation. EFSA nutrition profiling criteria and Nutri-Score front-of-pack labeling shape supermarket bakery line development. Munich and Hamburg industrial bakeries lead commercialization of beta-glucan concentrate systems for fat mouthfeel replication.
Japan
FOSHU certification pathways reward low-fat, high-fiber bakery claims with premium convenience store placement. METI functional foods frameworks and aging-population health priorities expand the dietetic baked goods channel. Tokyo metropolitan consumers fragment purchases between weekday subscription services and weekend artisan shop indulgence occasions.
United Kingdom
Traffic-light labeling mandates and sugar reduction targets drive rapid packaging redesign cycles for retail bakery departments. EFSA novel food approvals complicate allulose sweetener adoption relative to US regulatory timelines. London-based direct-to-consumer fresh-baked platforms bypass conventional supermarket slotting fees for niche dietetic brands.
India
Rising urban health awareness and diabetes prevalence expand the addressable base for glycemic-index-labeled baked snacks. FSSAI food safety standards and front-of-pack labeling proposals under development will shape reformulation roadmaps. Britannia Industries and regional players in Maharashtra and Karnataka invest in whole wheat and oat-based product line extensions.
Low Fat Baked Goods Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG conglomerates dominating retail shelf space while regional bakeries capture fresh-baked channels. The vendor base concentrates around grain-processing multinationals with captive ingredient supply and emerging oat-fractionation specialists. Three archetypes define competitive positioning: integrated grain-to-bakery operators, proprietary emulsion technology holders, and functional-foods-certified regional champions. Dominant competitive moves include backward integration into specialty oat milling and geographic licensing of clean-label emulsion systems.
Within the integrated grain-processing tier, General Mills, Inc. and Mondelez International exemplify divergent approaches to fat replacement science. General Mills, Inc. anchors its position through upstream control over grain milling infrastructure that supplies captive oat fractions. Mondelez International occupies a technology-focused position centered on proprietary emulsion platforms that preserve mouthfeel without hydrogenated oils. Nestlé S.A. sits within the nutrition-science archetype, leveraging cross-category dairy and cereal expertise to formulate reduced-fat bakery lines with functional positioning.
| Leading Market Players |
|---|
| Nestlé S.A. |
| General Mills, Inc. |
| Mondelez International |
| Kraft Heinz Company |
| Danone S.A. |
| Grupo Bimbo S.A.B. de C.V. |
| Arla Foods |
| Unilever PLC |
| Britannia Industries |
| Others |
Value Network & Pricing Analysis
Oat futures price volatility and Nordic grain harvest benchmarks cascade through formulation costs into three distinct pricing tiers for low-fat baked goods. Premium oat-fractionated ingredients command five-fold markups over conventional wheat systems, compressing margins for mid-tier brands while rewarding integrated operators with captive milling infrastructure.
Pricing Analysis
Volume concentrates in mass-market cookies and muffins where per-unit margins thin below specialty channels. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-certified functional products from conventional clean-label lines and private-label commodity offerings. Cost compression in the standard tier is intensifying as REACH-compliant emulsifier substitutions raise input expenses. Institutional buyers in USDA school nutrition programs exhibit highest price sensitivity, while Japan's convenience channel functional claims support premium price acceptance.
Supply Chain Analysis
Direct-to-retail bakery networks handle fresh-baked demand in Tokyo, London, and New York metropolitan corridors. Raw material sourcing draws from Nordic oat growing regions, North American grain belts, and Indian whole wheat production zones. Beta-glucan concentrate supply hinges on climate-dependent harvests in Scandinavia. Single-source vulnerability in specialty oat fractionation exposes formulation pipelines to weather-driven disruption. Distribution runs through supermarket bakery departments, direct-subscription platforms, and institutional foodservice channels with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over oat milling infrastructure and downstream subscription channel ownership constitute the dual integration race in low-fat baked goods. Players securing captive supply of beta-glucan concentrates while building direct-consumer fulfillment networks capture margin pools unavailable to conventional retail-dependent competitors.
For Market Incumbents: Lock in multi-year offtake agreements with Nordic oat fractionation specialists before climate volatility tightens supply. Expand in-house emulsion R&D capabilities to reduce dependency on scarce formulation chemists skilled in natural stabilizer systems. Patent-protected fat-mimetic technologies from Mondelez and General Mills demonstrate how proprietary science defends against private-label erosion. For New Entrants and Emerging Players: Subscription fresh-baked platforms offer the most penetrable channel wedge for niche dietetic brands bypassing supermarket slotting fees. Target weight-watcher segments in German and Japanese urban markets where clean-label positioning commands premium willingness-to-pay. FOSHU certification investment unlocks convenience store placement unavailable to uncertified competitors. For Investors and Strategic Acquirers: The window for entry favors oat-fractionation specialists with proven beta-glucan concentration technology and established Nordic supply relationships. Long-term viability centers on ingredient technology platforms rather than finished goods brands given private-label pressure. Watch EFSA-FDA convergence timelines on novel sweetener approvals as the signal for pan-regional product line scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Captive beta-glucan supply insulates margins from Nordic climate volatility and REACH chemical restrictions. |
| FOSHU Certification Investment | Premium convenience store placement in Japan rewards functional bakery claims with measurable price premiums. |
| Direct-to-Consumer Subscription Launch | Fresh-baked delivery platforms bypass retail slotting fees while capturing urban health-conscious breakfast occasions. |
| Clean-Label Emulsion R&D Expansion | Natural stabilizer expertise addresses REACH-mandated synthetic emulsifier phase-outs across EU formulations. |
| Micro-Bakery Network Localization | Distributed production nodes reduce EU F-Gas Regulation-driven refrigeration dependency in cold-chain logistics. |
Research Methodology
Trade journals, EFSA novel food approval databases, and USDA school nutrition procurement records formed the secondary backbone of this analysis. Primary interviews with bakery R&D directors, supermarket category buyers, oat mill procurement managers, and regulatory affairs specialists at functional foods companies supplied forward-looking formulation and channel intelligence. Bottom-up volume estimates from ingredient throughput data and top-down market sizing from retail audit records underwent cross-validation to align segmentation outputs.
Bottom-up modeling tracked oat fractionation capacity expansion, clean-label emulsion patent filings, and subscription bakery subscriber growth across the analysis window. Segmentation dimensions included product type, ingredient system, distribution channel, and customer health-claim motivation. CAGRs derived from historical volume trajectories and regulatory-mandated reformulation timelines incorporated EFSA nutrition profiling adoption curves and FDA serving-size enforcement patterns.
Caveats apply where EFSA-FDA sweetener approval divergence or trans-fat elimination technical barriers could materially shift the outlook for pan-regional product lines. Periodic stress-testing of base assumptions against REACH chemical restriction phase-in schedules and EU Green Deal compliance timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Premixed Bread Flour Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Pancakes Market
Bakery Products
Bake Stable Pastry Fillings Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
United States Cookies Market
Bakery Products
Laminated Dough Market
Bakery Products
Waffle Market
Bakery Products
Bread Premix Market