
 Hospital Rubber Sheet Market | 2026-2036
Hospital Rubber Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Rubber Sheet Market Analytics
Asset-light leasing models for medical bedding infrastructure are narrowing the competitive field in the hospital rubber sheet supply chain. Contitech leverages captive polymer compounding to sustain margin control across European hospital networks. Warco Biltrite anchors its position through deep specialization in antimicrobial rubber formulations for operating room surfaces.
A hospital rubber sheet is a vulcanized elastomeric barrier, typically calendered to 1–4 mm thickness, designed to provide fluid impermeability and electrical insulation on medical surfaces. Natural rubber grades dominate procurement volumes in cost-sensitive health facilities, while silicone rubber commands premium positioning in operating rooms where repeated autoclave sterilization cycles degrade lesser elastomers. Synthetic rubber variants occupy the fastest-expanding segment as laboratories seek chemical-resistant surfaces compatible with aggressive disinfectant protocols.
FDA biocompatibility standards under ISO 10993 and EU MDR surface-contact requirements constrain material formulations for any supplier accessing regulated health systems. India's BIS certification and CDSCO medical device rules add compliance layers for domestic manufacturers serving government hospital tenders. Stakeholders must monitor how REACH chemical restrictions and evolving autoclave temperature standards reshape acceptable polymer portfolios before committing to long-term compounding investments.
Market Dynamics
Asset-light leasing models for medical bedding infrastructure are narrowing the competitive field in the hospital rubber sheet supply chain. Contitech leverages captive polymer compounding to sustain margin control across European hospital networks. Warco Biltrite anchors its position through deep specialization in antimicrobial rubber formulations for operating room surfaces.
Growth Catalysts
- EU MDR biocompatibility mandates:Operating room procurement teams now specify silicone rubber grades capable of withstanding repeated autoclave sterilization cycles above 134°C.
- India's PLI scheme for medical rubber products:Domestic manufacturers are expanding calendering capacity to capture government hospital tender volumes in tier-2 and tier-3 cities.
- Rehabilitation center expansion:Patient handling safety protocols are tightening across post-acute care facilities, driving replacement cycles for fluid-impermeable barriers.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian latex supply disruptions transmit directly to cost-sensitive health facility procurement budgets.
- REACH chemical restrictions:Phthalate plasticizer bans are forcing reformulation of legacy PVC-alternative compounds before 2026 compliance deadlines.
- Silicone rubber supply concentration:Dow and Wacker Chemie control over 60% of medical-grade silicone monomer supply, creating input bottleneck risk for mid-tier sheet producers.
Strategic Opportunities
- Home healthcare surfaces:Durable medical equipment suppliers are sourcing hospital-grade rubber sheeting for bariatric patient home care beds.
- BIS certification acceleration:India's streamlined medical device rules are reducing CDSCO registration timelines for domestic rubber sheet manufacturers.
- Antimicrobial additive convergence:Silver-ion and copper-oxide rubber formulations are opening premium positioning in infection control procurement.
Industry Challenges
- ISO 10993-5 cytotoxicity testing backlog:Third-party laboratory capacity constraints are extending biocompatibility certification timelines for new polymer grades.
- Autoclave compatibility validation:Each sterilization cycle protocol requires material-specific aging studies, fragmenting R&D resources across customer-specific requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Rubber Sheet Market |
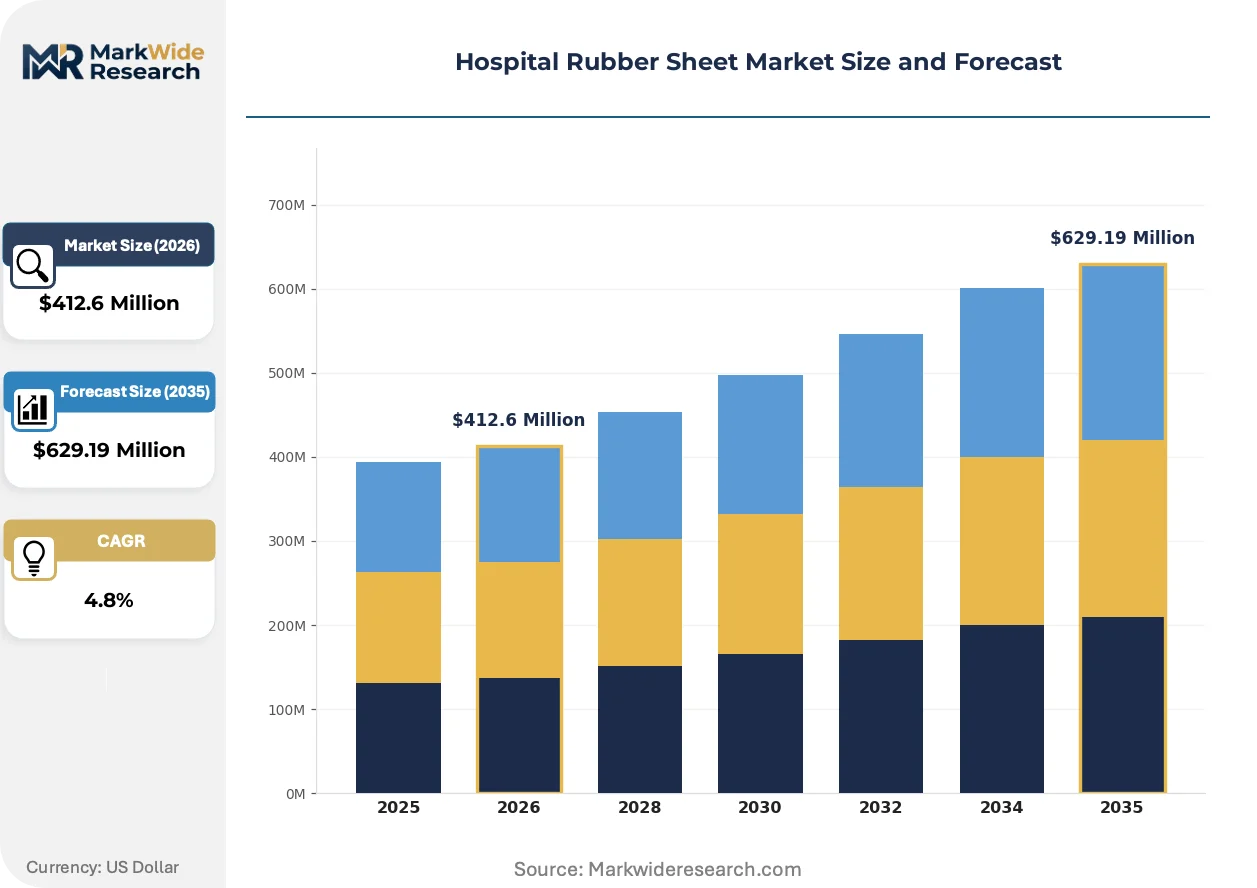
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Foam Rubber, Silicone Rubber End User: Hospitals, Clinics, Rehabilitation Centers, Health Facilities Application: Operating Room, Patient Rooms, Emergency Departments, Laboratories Thickness: 1 mm, 2 mm, 3 mm, 4 mm |
| Companies Covered | Contitech, Warco Biltrite, Aero Rubber, BRP, Hanna Rubber Company, Semperflex, Togawa, American Biltrite, Rubberteck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Rubber Sheet Market Evolving Landscape
Digital manufacturing is compressing specification-to-delivery timelines for custom-calendered hospital rubber sheeting. Suppliers are deploying sensor-equipped production lines to capture real-time thickness uniformity data.
Peroxide-cured silicone rubber is virtualizing the operating room surface market by enabling 500+ autoclave cycles without elastomer degradation. Surgical suite procurement teams at major hospital networks are specifying this grade for table pads and instrument mats. The technology is virtualizing the traditional trade-off between initial cost and total lifecycle replacement frequency.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing compounders to reformulate flame-retardant rubber grades for European hospital tenders. Manufacturers serving EU markets are accelerating migration to phosphate ester alternatives ahead of 2025 enforcement windows. German and French hospital procurement consortiums are now requiring full material disclosure documentation for surface-contact medical devices.
Leasing consortia are unbundling capital expenditure from rubber sheet acquisition across NHS trusts and large Indian hospital chains. Asset-light operators are inserting themselves between manufacturers and end-users, capturing long-term service contracts. This channel shift is most visible in Maharashtra and Karnataka, where private hospital networks are outsourcing entire bedding infrastructure lifecycle management.
Hospital Rubber Sheet Market Segmentation
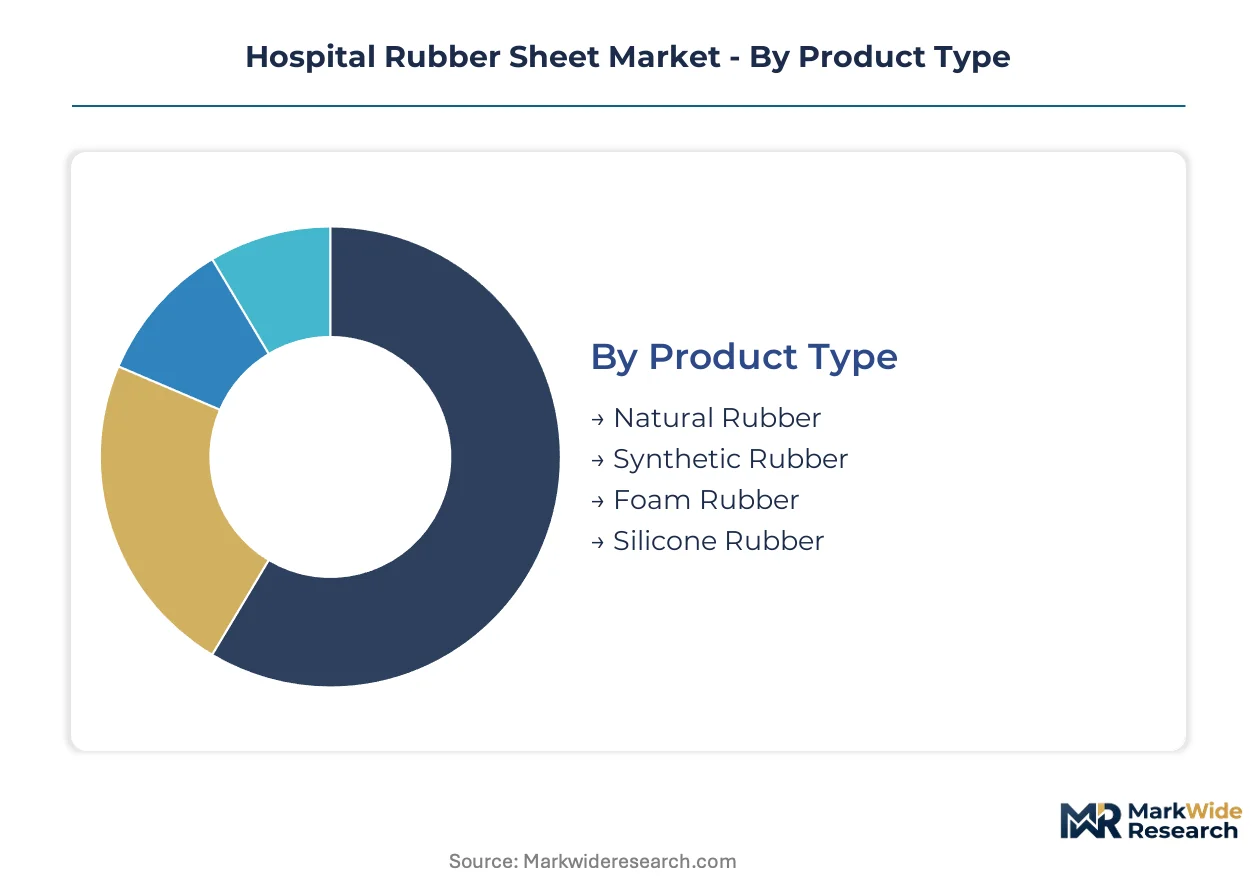
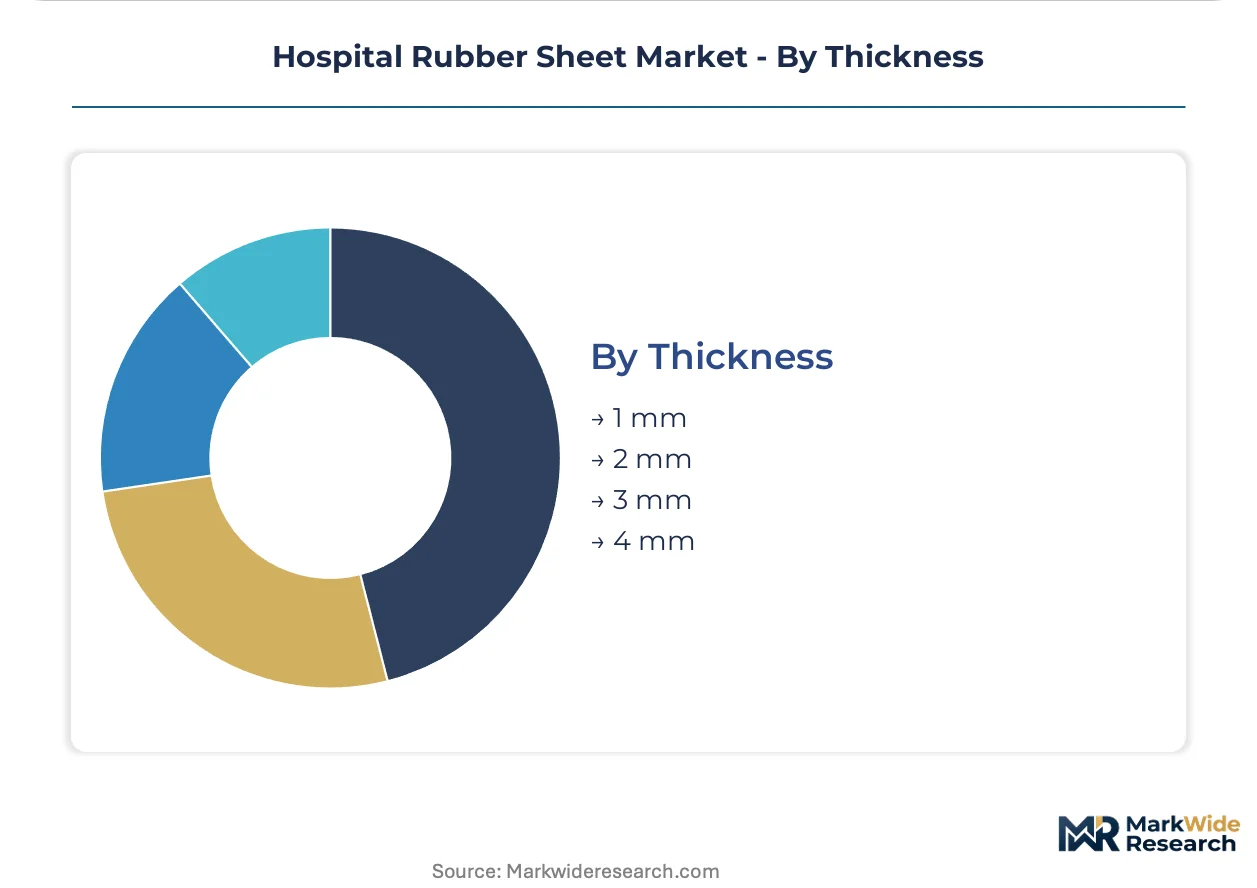
Hospital rubber sheet procurement splits across four critical dimensions that determine material specification, compliance burden, and lifecycle economics. Product chemistry governs sterilization tolerance and regulatory pathway. End-user facility type dictates volume scale and replacement cadence. Application environment shapes thickness and performance requirements. Understanding these intersections enables suppliers to align compounding investments with actual demand concentration.
Product Type:
Use-case spectrum spans cost-driven acute care through precision surgical environments, with chemistry selection directly tied to sterilization protocol intensity.
- Natural Rubber:Vulcanized polyisoprene compounds deliver baseline fluid impermeability at the lowest unit cost. Procurement concentrates in India's government hospital expansion and Southeast Asian public health systems where budget constraints override autoclave cycle frequency.
- Synthetic Rubber:Nitrile and SBR blends offer chemical resistance against aggressive disinfectants. Laboratories in Germany and France specify these grades under REACH-compliant formulations for surfaces exposed to quaternary ammonium and peroxide-based cleaning protocols.
- Foam Rubber:Cellular elastomer structures provide cushioning for extended patient positioning. Bariatric patient handling protocols in US rehabilitation centers are driving specification for pressure redistribution surfaces.
- Silicone Rubber:Peroxide-cured grades withstand 500+ autoclave cycles above 134°C. Operating room procurement at NHS trusts and major US hospital networks specifies this chemistry for surgical table pads and instrument mats where degradation tolerance commands premium positioning.
Established volume favors natural rubber; emerging adoption favors silicone rubber.
End User:
Customer type stratification reflects capital intensity, regulatory scrutiny, and replacement cycle predictability.
- Hospitals:Large-scale integrated delivery networks consolidate procurement through group purchasing organizations. India's AIIMS network and US academic medical centers drive standardized specifications across bed capacity exceeding 500 units per facility.
- Clinics:Outpatient surgical centers and diagnostic facilities prioritize rapid-turnover surfaces with lower sterilization burden. Cost compression dominates material selection.
- Rehabilitation Centers:Post-acute facilities face tightening patient handling safety mandates. Maharashtra's private rehabilitation network expansion is accelerating replacement cycles for fluid-impermeable barriers.
- Health Facilities:Long-term care and nursing homes represent fragmented demand with irregular procurement patterns. BIS certification requirements are filtering supplier access to India's government-subsidized elder care infrastructure.
Procurement consolidation favors hospitals; regulatory tailwinds favor rehabilitation centers.
Application:
Environmental exposure severity creates tiered performance requirements from sterile fields through general patient contact.
- Operating Room:Surgical suites demand ISO 10993-5 cytotoxicity certification and autoclave compatibility validation. FDA biocompatibility standards and EU MDR surface-contact requirements constrain supplier qualification to medical-grade silicone specialists.
- Patient Rooms:General ward surfaces prioritize cost efficiency over sterilization tolerance. Natural rubber dominates procurement volumes in India's tier-2 and tier-3 city hospital expansions under PLI-incentivized domestic manufacturing.
- Emergency Departments:High-throughput trauma environments require rapid-clean compatibility with bleach and accelerated hydrogen peroxide protocols. Synthetic rubber formulations are displacing legacy PVC alternatives under REACH phthalate restrictions.
- Laboratories:Diagnostic and research facilities specify chemical-resistant surfaces for spill containment. German hospital procurement consortiums now require full material disclosure documentation for laboratory-grade rubber sheeting.
Compliance stringency favors operating room specifications; volume scale favors patient room deployment.
Thickness:
Calendered gauge selection balances durability, flexibility, and material cost across surface geometry requirements.
- 1 mm:Ultra-thin profiles suit instrument mat applications and constrained-space surgical setups. Limited to low-mechanical-stress environments.
- 2 mm:Standard ward bed specification balancing cost and puncture resistance. Represents procurement volume concentration in cost-sensitive health systems.
- 3 mm:Enhanced durability for bariatric patient handling and extended positioning protocols. Rehabilitation center safety standards are tightening minimum thickness requirements.
- 4 mm:Maximum cushioning for operating room table pads and pressure injury prevention. Premium positioning commands 40-60% material cost premium over 2 mm baseline.
Standardization pressure favors 2 mm; clinical outcome differentiation favors 4 mm.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States and government hospital procurement bodies in India concentrate buyer power, while German hospital consortiums and NHS trusts in the United Kingdom enforce stringent material disclosure standards that filter supplier access.
United States
Academic medical centers and GPO-driven procurement dominate volume, with Cleveland Clinic and Mayo Clinic networks standardizing specifications across 500+ bed facilities. FDA biocompatibility standards under ISO 10993 constrain material formulations for any supplier accessing Medicare-reimbursed health systems. Akron, Ohio anchors domestic calendering capacity where Aero Rubber and Hanna Rubber Company maintain production footprints.
Germany
Hospital procurement consortiums in Bavaria and North Rhine-Westphalia now require full material disclosure documentation for surface-contact medical devices. REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing compounders to reformulate flame-retardant grades ahead of enforcement windows. Contitech leverages captive polymer compounding from its Hanover operations to sustain margin control across European hospital networks.
India
Government hospital infrastructure expansion under the PLI scheme for medical rubber products is drawing fresh supplier investment to tier-2 and tier-3 cities. BIS certification and CDSCO medical device rules add compliance layers for domestic manufacturers serving AIIMS network tenders. Maharashtra and Karnataka host the most concentrated private hospital network activity, with leasing consortia outsourcing entire bedding infrastructure lifecycle management.
United Kingdom
NHS trusts are consolidating procurement through leasing models that unbundle capital expenditure from rubber sheet acquisition. EU MDR biocompatibility mandates now specify silicone rubber grades capable of withstanding repeated autoclave sterilization cycles above 134°C. London and Manchester anchor the surgical suite procurement concentration where peroxide-cured silicone commands premium positioning.
Japan
Metropolitan hospital networks in Tokyo and Osaka prioritize autoclave compatibility validation for surgical surfaces. JIS standards and PMDA medical device regulations govern material specifications for domestic suppliers. Kanto region manufacturers serve the precision surgical environment segment where degradation tolerance commands material cost premiums.
Hospital Rubber Sheet Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement access across divergent end-user segments. The vendor base separates into three tiers: multinational elastomer compounders with captive raw material supply, regional calendering specialists with deep application expertise, and asset-light leasing operators inserting themselves between manufacturers and hospital networks. M&A activity concentrates among mid-tier compounders seeking biocompatibility certification assets, while capacity expansion dominates in India where PLI incentives accelerate government tender capture.
Among North American fabricators, Aero Rubber and Hanna Rubber Company occupy positions within the regional calendering specialist archetype, serving domestic hospital networks with customized thickness specifications. Contitech represents the multinational compounder tier with European captive polymer operations. Warco Biltrite anchors the antimicrobial formulation specialist segment. These three exemplify how supplier positioning fragments across chemistry expertise, geographic production control, and end-user channel access rather than consolidating around unified scale advantages.
| Leading Market Players |
|---|
| Contitech |
| Warco Biltrite |
| Aero Rubber |
| BRP |
| Hanna Rubber Company |
| Semperflex |
| Togawa |
| American Biltrite |
| Rubberteck |
| Others |
Value Network & Pricing Analysis
Akron, Ohio anchors domestic calendering capacity where concentrated polymer compounding expertise feeds downstream pricing power to hospital procurement networks. Thai and Indonesian latex supply disruptions transmit volatility through cost-sensitive health facility budgets, compressing margins for natural rubber-dependent producers.
Pricing Analysis
Cost-plus contracts with Thai RSS3 latex indexation dominate procurement agreements for natural rubber grades. Price differentiation rests on ISO 10993-5 cytotoxicity certification tier and autoclave cycle tolerance, with peroxide-cured silicone commanding material cost premiums over standard ward specifications. Cost compression in India's government hospital tenders is intensifying because PLI-incentivized domestic manufacturers are absorbing margin pressure to capture volume. Tier-2 city public health systems exhibit highest price sensitivity; NHS trusts and US academic medical centers demonstrate lowest.
Supply Chain Analysis
Tariff exposure between Thailand and India dominates raw material cost planning for latex-dependent compounders. Manufacturing concentrates in India, Germany, and the United States, with natural rubber sourcing tethered to Southeast Asian plantation output. Medical-grade silicone monomer draws from Dow and Wacker Chemie facilities, creating single-source vulnerability for mid-tier sheet producers. Distribution runs through group purchasing organizations in the United States and leasing consortia in the United Kingdom and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through biocompatibility certification creates sticky supplier relationships that resist displacement.
For Market Incumbents: Pre-empt emerging Indian domestic manufacturers by accelerating BIS certification timelines and locking multi-year AIIMS network contracts before PLI capacity fully deploys. Deepen backward integration into captive silicone compounding to offset Dow and Wacker Chemie supply concentration risk. Prioritize antimicrobial formulation R&D to defend premium positioning against commodity natural rubber substitution in cost-sensitive segments. For New Entrants and Emerging Players: Establish a beachhead in India's tier-3 city government hospital expansion where PLI incentives are drawing fresh investment but certification backlogs create temporary access windows. Target home healthcare durable medical equipment suppliers seeking hospital-grade rubber sheeting for bariatric patient beds. Lead with BIS-CDSCO dual certification bundling to differentiate against unqualified regional competitors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because M&A activity concentrates among mid-tier compounders seeking biocompatibility certification assets that unlock hospital network access. Acquisition target archetype: regional calendering specialists with deep application expertise but lacking ISO 10993-5 cytotoxicity validation. Watch autoclave temperature standard evolution as the inflection signal for polymer portfolio obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Investment | Silver-ion and copper-oxide rubber grades open premium infection control procurement at NHS trusts. |
| Backward Integration into Silicone Compounding | Captive medical-grade monomer supply reduces dependency on Dow and Wacker Chemie concentration. |
| BIS-CDSCO Dual Certification Acceleration | Streamlined registration timelines capture AIIMS network tenders ahead of PLI-subsidized domestic competitors. |
| Leasing Consortium Partnership | Asset-light operators in Maharashtra and Karnataka outsource bedding infrastructure lifecycle management. |
| Peroxide-Cured Silicone Capacity Expansion | 500+ autoclave cycle tolerance commands surgical suite premium positioning at Mayo Clinic networks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and calendering plant operations directors; and secondary validation through FDA 510(k) filings, CDSCO medical device registrations, EU MDR technical documentation, and hospital procurement database extracts. Bottom-up segment sizing triangulated against top-down elastomer consumption estimates from customs trade records.
Forecast inputs considered product chemistry, end-user facility type, application environment, and thickness specification across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling incorporating sterilization protocol intensity, regulatory compliance burden, and replacement cycle frequency. Natural rubber price volatility and REACH chemical restriction timelines served as scenario-weighting variables.
Sensitivities concentrate around Thai latex supply disruption severity and EU MDR enforcement acceleration timelines. Forecasts reflect documented assumptions on PLI scheme continuation and autoclave temperature standard stability. Material shifts in FDA biocompatibility testing requirements or BIS certification pathway restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Global Rubber Additives Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Silicone Rubber Market
Rubber
Global Crumb Rubber Market
Rubber
Performance Elastomers Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Rubber Conveyor Belt Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Global Medical Rubber and Balloon Products Consumption Market
Rubber
Neoprene Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market