
 Flooring Installation Adhesives Market | 2026-2036
Flooring Installation Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring Installation Adhesives Market Insights
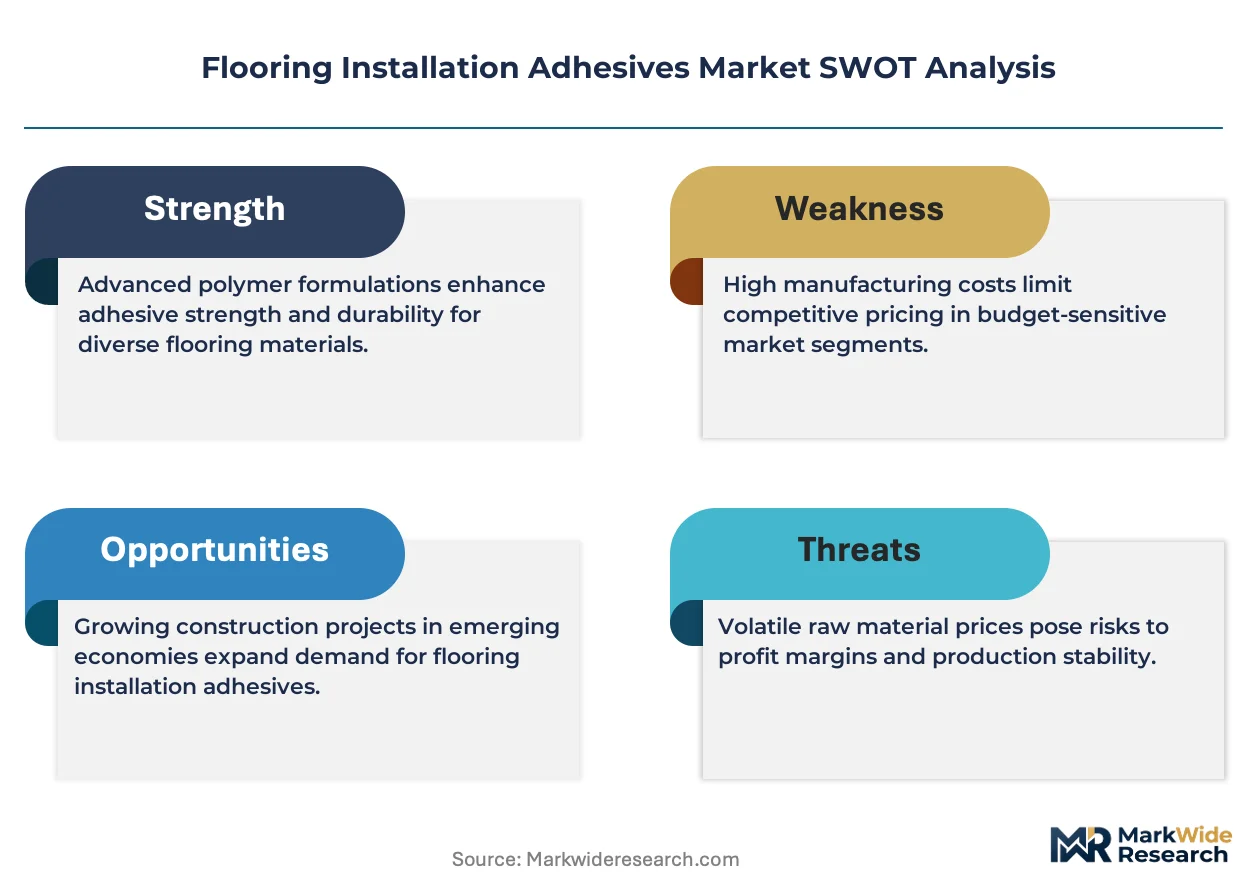
The EU Green Deal's building renovation targets is hardening demand for low-emission flooring adhesives across European construction supply chains. Sika AG leverages its polyurethane technology leadership to sustain specification wins in commercial flooring projects. Henkel AG & Co. KGaA anchors its position through water-based adhesive portfolios tailored to laminate and engineered wood segments. Bostik SA differentiates via silane-modified polymer platforms that compete on installation speed and moisture resistance.
Flooring installation adhesives are bonding agents formulated from polyurethane, epoxy, acrylic, or silane-modified polymer bases, designed to permanently secure floor coverings to substrates under specified temperature and humidity conditions; these formulations must achieve defined tensile adhesion strength and VOC emission thresholds to serve residential, commercial, and industrial construction. Water-based systems dominate volume in regulated European markets where ECHA REACH restrictions on solvent content have reshaped product portfolios, while reactive polyurethane adhesives represent the fastest-expanding technology segment as engineered wood and luxury vinyl tile applications multiply. Pressure-sensitive adhesives occupy stable demand niches in carpet installation where dry-lay convenience commands premium positioning among renovation contractors.
EMA building product directives, EPA VOC regulations in the United States, and China's GB standards for indoor air quality collectively constrain formulation choices and dictate regional product registration requirements. The EU F-Gas Regulation and evolving state-level California Air Resources Board rules further narrow permissible chemistries, pushing manufacturers toward bio-based feedstock development. Stakeholders must monitor regulatory divergence between jurisdictions to determine where regional formulation customization or unified platform strategies offer superior returns.
Market Dynamics
Substitution of solvent-based adhesive systems is compressing legacy formulation margins while expanding water-based and reactive polyurethane platform volumes. ECHA REACH restrictions and EPA VOC regulations are forcing parallel reformulation cycles across regional supply chains.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy efficiency upgrades across Germany, France, and Italy are accelerating specification of low-emission flooring adhesives in residential and commercial retrofit projects.
- Passive house construction standards:Germany's stringent thermal envelope requirements mandate compatible adhesive systems for engineered wood and luxury vinyl tile installations, hardening demand for high-performance formulations.
- Reactive polyurethane technology:Superior tensile adhesion strength and moisture resistance properties are displacing acrylic alternatives in multi-family housing and healthcare facility flooring.
Market Restraints
- Petrochemical feedstock volatility:Isocyanate and polyol price swings compress polyurethane adhesive margins and complicate annual contract negotiations with flooring contractors.
- Specialized applicator skill requirements:Moisture-cure and two-component systems demand certified installation training that limits contractor pool expansion in secondary markets.
- Extended cure-time specifications:Water-based formulations require 24-48 hour set periods that conflict with fast-track commercial construction schedules, restricting segment penetration.
Strategic Opportunities
- India's urban housing expansion:PLI scheme incentives for domestic manufacturing and BIS certification alignment create entry pathways for European adhesive platforms in laminate flooring.
- Silane-modified polymer convergence:Hybrid chemistries combining polyurethane backbone with silane crosslinking are opening specification wins in moisture-prone basement and bathroom applications.
- Direct contractor digital channels:B2B platform procurement by renovation specialists is disintermediating traditional distributor relationships in North American residential markets.
Industry Challenges
- ECHA SVHC notification timelines:Substance of very high concern candidate list updates force 6-12 month reformulation cycles that disrupt inventory planning and regional product registrations.
- Cross-regional certification fragmentation:Divergent VOC thresholds between EPA regulations, ECHA REACH, and China's GB standards require multiple SKUs for nominally identical adhesive chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring Installation Adhesives Market |
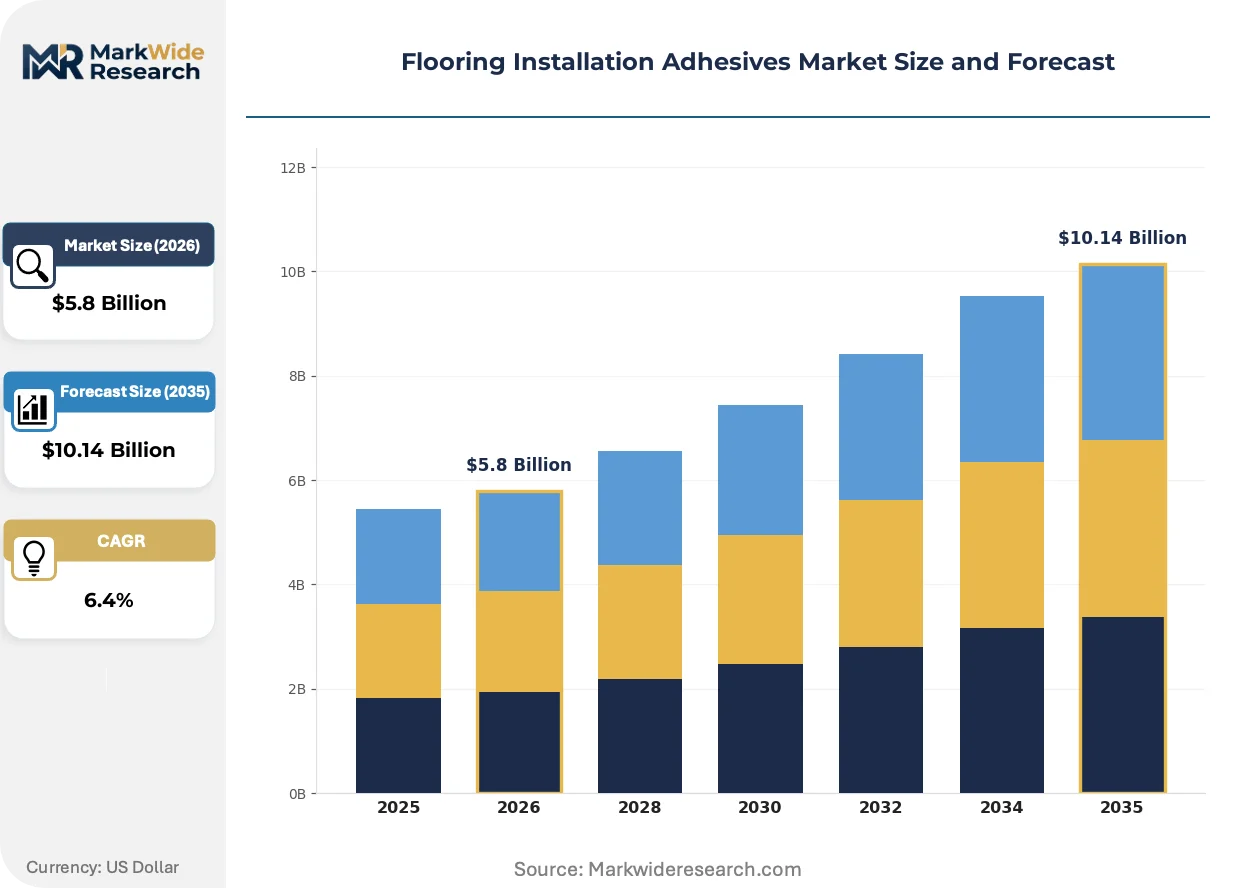
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, Reactive, Pressure-Sensitive, Hot Melt Technology: Polyurethane, Epoxy, Acrylic, Polyvinyl Acetate, Silane-Modified Polymers Application: Vinyl, Carpet, Laminate, Engineered Wood, Ceramic Tile, Bamboo End User: Construction Companies, Renovation Contractors, Flooring Specialists, Facility Managers |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, MAPEI S.p.A., 3M, Dow Inc., Wacker Chemie AG, Bostik SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring Installation Adhesives Market Trends and Innovations
Formulation chemistry is pivoting toward bio-based feedstocks and hybrid polymer architectures that reconcile performance specifications with tightening emission thresholds. Digital specification tools and contractor training platforms are compressing the traditional technical sales cycle.
Silane-modified polymer adhesive systems are modularizing installation protocols across commercial flooring segments. These hybrid platforms combine moisture-cure reliability with primerless substrate adhesion that accelerates project timelines. Large-format retail and hospitality contractors in Germany and France are specifying these systems for 24-hour return-to-service requirements that conventional polyurethanes cannot satisfy.
EPA VOC regulations and evolving California Air Resources Board rules are narrowing permissible solvent content in flooring adhesives sold in US markets. Manufacturers must maintain parallel water-based and reactive product lines to serve states with divergent emission thresholds. The regulatory friction is accelerating bio-based feedstock development as formulators seek chemistries that satisfy both performance and compliance requirements without regional SKU proliferation.
Renovation contractors are consolidating procurement through specialized B2B platforms that unbundle technical support from product supply. Traditional distributor relationships are compressing as mid-sized flooring installers in Texas, Florida, and California migrate to direct manufacturer digital portals. This channel shift is most visible in residential laminate and engineered wood segments where standardized adhesive specifications reduce the value of face-to-face technical consultation.
Flooring Installation Adhesives Market Segmentation
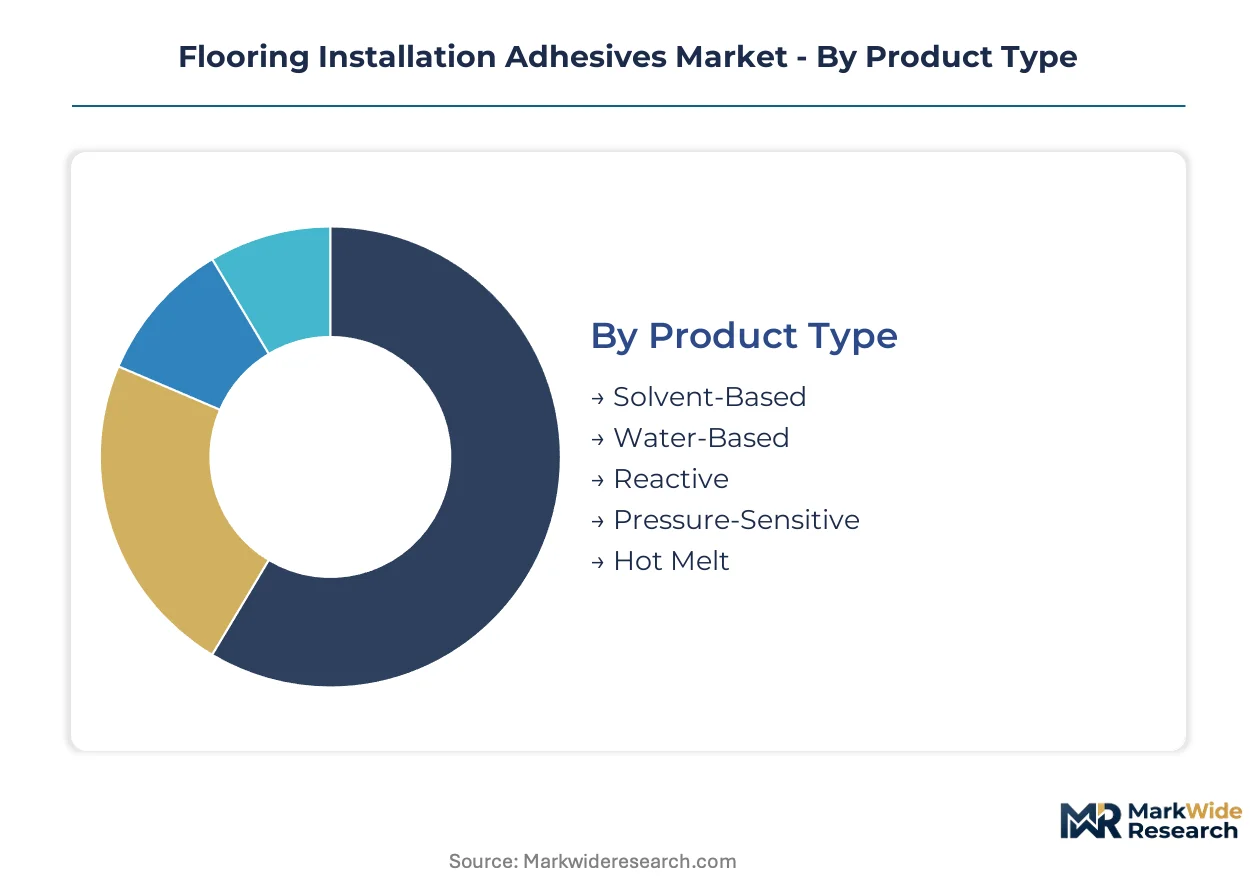
Flooring installation adhesives fragment across four structural dimensions that determine specification pathways and margin architecture. Product chemistry and technology base define regulatory compliance boundaries, while application substrate and end-user channel shape pricing power and technical service requirements.
Product Type:
Standalone adhesive systems dominate specification in new construction where substrate conditions allow direct application, while embedded reactive formulations integrate into multi-layer flooring assemblies for moisture-prone environments.
- Water-Based:Acrylic and polyurethane dispersions suspended in aqueous carriers achieve compliance with EPA VOC regulations and ECHA REACH thresholds. Demand concentrates in residential renovation across Germany and France where low-emission certification governs public housing retrofit specifications.
- Reactive:Two-component polyurethane and epoxy systems cure through chemical crosslinking to deliver tensile adhesion strength exceeding 2 MPa. Engineered wood installations in passive house construction across Germany mandate these formulations for thermal envelope compatibility.
- Solvent-Based:Hydrocarbon-carried systems persist in industrial flooring where rapid tack development and extreme temperature resistance outweigh emission concerns.
- Pressure-Sensitive:Permanent-tack formulations enable dry-lay repositioning before final bond activation. Carpet installation in North American commercial renovation relies on these systems for installer productivity.
- Hot Melt:Thermoplastic adhesives applied at elevated temperatures solidify on cooling for immediate handling. Vinyl plank manufacturing lines integrate these for backing attachment.
Volume placements concentrate in Water-Based systems; the faster expansion belongs to Reactive formulations.
Technology:
Cost tier separation runs from commodity polyvinyl acetate through performance-priced polyurethanes to premium silane-modified platforms.
- Polyurethane:Isocyanate-terminated prepolymers deliver moisture-cure reliability and substrate adhesion across concrete, plywood, and calcium sulfate screeds. Multi-family housing developers in Texas and Florida specify these for luxury vinyl tile installations over uneven subfloors.
- Silane-Modified Polymers:Hybrid architectures combine polyurethane backbone flexibility with silane crosslinking density. Basement and bathroom applications in moisture-exposed German residential construction specify these for primerless adhesion and 24-hour return-to-service.
- Epoxy:Rigid thermoset systems provide chemical resistance and load-bearing capacity. Industrial facility flooring in heavy manufacturing environments specifies these for traffic durability.
- Acrylic:Water-borne emulsions offer cost-efficient bonding for light-traffic residential applications. Laminate flooring installers in price-sensitive segments favor these for dry-back installation.
- Polyvinyl Acetate:Homopolymer and copolymer emulsions serve low-stress wood bonding. Wood parquet manufacturing integrates these for block assembly before site installation.
Revenue concentrates in Polyurethane platforms; Silane-Modified Polymers are climbing the fastest.
Application:
Application substrate determines adhesive selection through dimensional stability requirements, moisture sensitivity, and surface energy characteristics.
- Engineered Wood:Multi-layer timber constructions require adhesives accommodating differential expansion between wood layers and substrate. Passive house certification programs in Germany mandate compatible systems for thermal bridge elimination.
- Luxury Vinyl Tile:Rigid core and flexible variants demand pressure-sensitive or reactive systems balancing dimensional stability with installation speed. Hospitality renovation contractors in France specify fast-cure formulations for minimal downtime.
- Carpet:Broadloom and tile formats use pressure-sensitive or hot-melt backings. Commercial office refurbishment in North American markets drives specification of low-odor systems for occupied building work.
- Laminate:High-density fiberboard cores with decorative overlays require moisture-resistant edge and surface bonding. India's urban housing expansion under PLI scheme incentives is accelerating demand for BIS-certified formulations.
- Ceramic Tile:Cementitious and dispersion adhesives compete based on tile format and substrate preparation. Thin-set and large-format specifications diverge in technical requirements.
- Bamboo:Rapidly renewable material with high silica content demands specialized primers and adhesives for reliable bond formation. Sustainable construction projects in California specify these for LEED contribution.
Specification activity concentrates in Engineered Wood; Luxury Vinyl Tile is gaining share fastest.
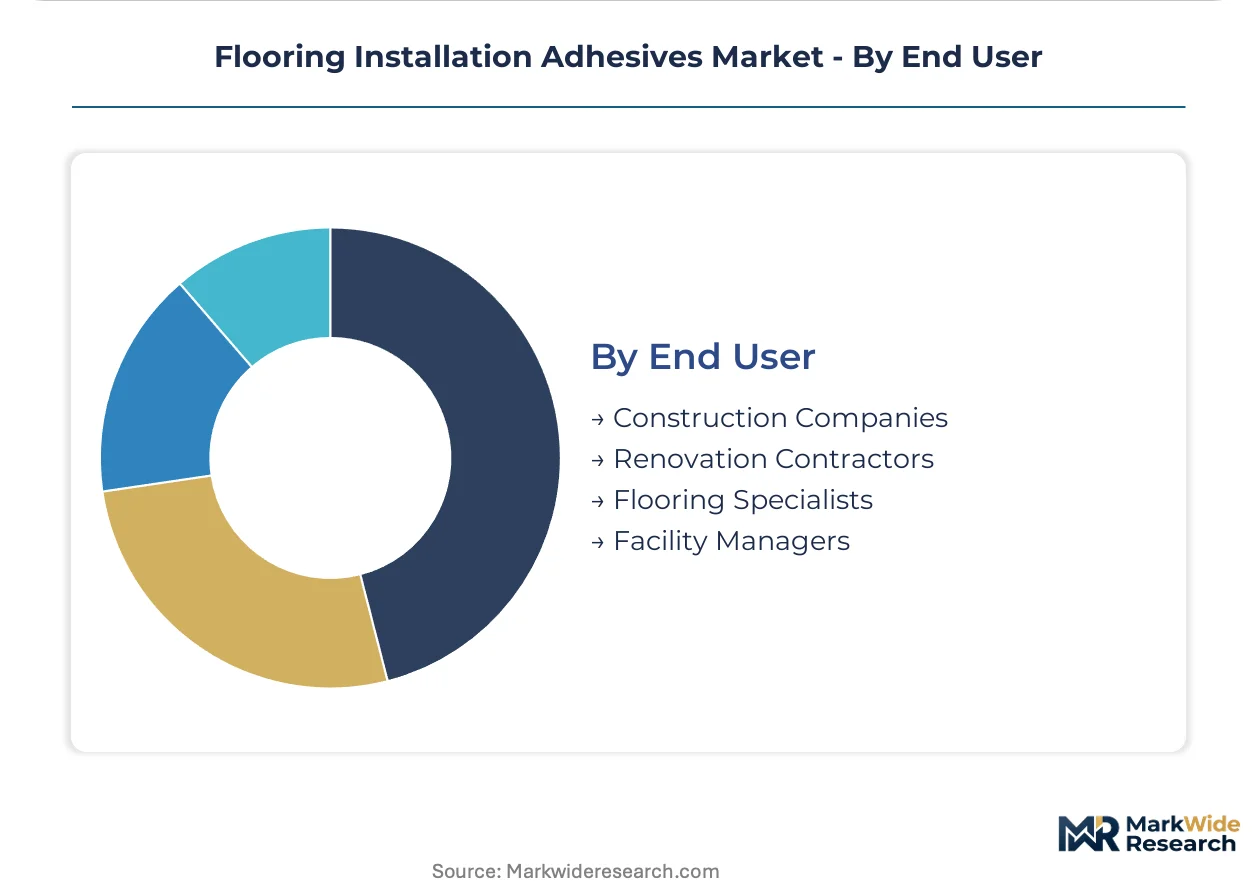
End User:
Customer type segmentation separates high-volume construction procurement from technical specialist channels and facility management retrofit.
- Renovation Contractors:Mid-sized residential specialists consolidate procurement through B2B digital platforms. Texas, Florida, and California markets show migration from distributor relationships to direct manufacturer portals for standardized laminate and engineered wood adhesives.
- Construction Companies:Large-scale new build developers negotiate annual contracts with technical service attachments. Multi-family housing and healthcare facility projects in Germany specify reactive polyurethane systems through framework agreements.
- Flooring Specialists:Certified installers command premium positioning for moisture-cure and two-component system application. Skill requirements limit contractor pool expansion in secondary markets.
- Facility Managers:Commercial and institutional maintenance departments procure for repair and replacement cycles. 24-hour return-to-service requirements drive specification of silane-modified polymer systems in retail and hospitality sectors.
Procurement volume concentrates in Renovation Contractors; Construction Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while consumption concentrates in renovation-heavy European markets and rapidly urbanizing Asian economies. This production-consumption divide shapes regional formulation strategies and regulatory compliance investments.
United States
Residential renovation contractors in Texas, Florida, and California are consolidating procurement through direct manufacturer digital portals. EPA VOC regulations and evolving California Air Resources Board rules narrow permissible solvent content, forcing parallel water-based and reactive product lines. The Southeast construction corridor from Atlanta to Orlando drives specification of fast-cure systems for multi-family housing timelines.
Germany
Passive house construction standards mandate compatible adhesive systems for engineered wood and luxury vinyl tile installations, hardening demand for high-performance formulations. The EU Green Deal's building renovation targets accelerate substitution of solvent-based systems in residential retrofit projects. Industrial clusters in Bavaria and North Rhine-Westphalia anchor polyurethane technology development for commercial flooring specifications.
France
Hospitality renovation contractors specify silane-modified polymer systems for 24-hour return-to-service requirements in retail and hotel projects. ECHA REACH restrictions on solvent content reshape product portfolios toward water-based acrylic and polyurethane dispersions. The Île-de-France region concentrates specification activity for large-format commercial flooring installations.
India
Urban housing expansion under PLI scheme incentives accelerates demand for BIS-certified formulations in laminate flooring applications. Domestic manufacturing alignment with BIS certification creates entry pathways for European adhesive platforms. Maharashtra and Gujarat industrial corridors concentrate production capacity for wood-based panel manufacturing that consumes installation adhesives.
China
GB standards for indoor air quality constrain formulation choices for flooring adhesives serving residential construction. Engineered wood manufacturing clusters in the Yangtze River Delta drive demand for moisture-resistant bonding systems. Provincial environmental regulations in Jiangsu and Zhejiang accelerate water-based formulation adoption in export-oriented flooring production.
Flooring Installation Adhesives Market Competitive Landscape
The competitive structure tilts toward diversified chemical conglomerates with construction sector exposure. Player concentration remains moderate with tiered differentiation between global formulation leaders and regional specialists. Three archetypes dominate: integrated adhesive-chemical platforms, construction-focused specialty suppliers, and diversified industrial conglomerates with flooring divisions. Capacity expansion in Asia-Pacific markets and portfolio diversification into bio-based feedstocks represent the dominant competitive moves.
Among European-based chemical conglomerates, Sika AG and Henkel AG & Co. KGaA exemplify the integrated platform archetype, combining construction chemical portfolios with adhesive specialization. Bostik SA occupies a position within the construction-focused specialty tier, representing silane-modified polymer expertise. These three entities anchor the competitive landscape through technology leadership in polyurethane and hybrid polymer systems, with geographic presence spanning regulated European markets and expansion-oriented Asian economies.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| MAPEI S.p.A. |
| 3M |
| Dow Inc. |
| Wacker Chemie AG |
| Bostik SA |
| Others |
Pricing and Supply Chain Analysis
Certified applicator pools in Germany and France concentrate installation expertise for moisture-cure and two-component systems, creating labor-cost differentials that widen pricing spreads between premium reactive formulations and commodity water-based alternatives. This workforce geography shapes tiered pricing architectures across European markets.
Pricing Analysis
Margin tightening in water-based tiers reflects isocyanate and polyol feedstock volatility compressing polyurethane adhesive margins. Contract-based long-term offtake dominates large-scale construction procurement, while spot purchasing governs renovation contractor segments. Price differentiation traces to certification grade—passive house-compatible formulations command premiums—and volume scale in multi-family housing frameworks. Cost-down pressure on standard acrylic systems accelerates as Indian laminate flooring expansion under PLI scheme incentives draws price-sensitive volume buyers.
Supply Chain Analysis
Isocyanate supply rests on German and Belgian specialty chemical producers, with polyol feedstock drawing from Dutch and Chinese manufacturing bases. Raw material dependencies center on MDI, TDI, and propylene oxide derivatives. Single-source vulnerability concentrates in moisture-cure catalyst supply from Japanese specialty chemical houses. Distribution runs through regional construction chemical distributors in Europe, direct manufacturer portals in North American residential markets, and BIS-certified domestic channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal building renovation targets and ECHA SVHC notification timelines are forcing parallel reformulation cycles that smaller players cannot fund, consolidating competitive structure around diversified chemical conglomerates.
For Market Incumbents: To counter margin compression from petrochemical feedstock volatility, secure backward integration into polyol supply through framework agreements with Middle Eastern feedstock producers, and anchor specification control through passive house certification investments in German and Austrian technical institutes. For New Entrants and Emerging Players: Capture India's urban housing expansion under PLI scheme incentives by aligning BIS certification pathways for laminate flooring adhesives, and penetrate Texas and Florida multi-family housing markets through fast-cure reactive polyurethane formulations sold via direct contractor digital channels. For Investors and Strategic Acquirers: The window for entry favors construction-focused specialty suppliers with silane-modified polymer expertise and established specification relationships in moisture-prone basement and bathroom applications. Watch ECHA substance of very high concern candidate list updates as inflection indicators forcing acquisition-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | Captive feedstock sourcing insulates margin structures from isocyanate price swings in European manufacturing. |
| Passive House Certification Investment | Specification lock-in with German thermal envelope standards hardens demand for compatible adhesive systems. |
| Direct-to-Contractor Digital Platform | Channel disintermediation in Texas and Florida renovation markets compresses distributor margin capture. |
| Silane-Modified Polymer R&D Expansion | Hybrid chemistry platforms open 24-hour return-to-service specifications in French hospitality renovation. |
| BIS Certification Alignment in India | PLI scheme compliance creates entry pathways for European adhesive platforms in laminate flooring. |
Research Methodology
Independent corroboration across primary interviews with flooring installation contractors, construction company procurement directors, and facility management maintenance heads, combined with secondary validation through ECHA REACH registration databases, EPA VOC compliance filings, and BIS certification records, underwrites the qualitative findings. Technical R&D directors at adhesive formulators and distribution channel partners in Germany, France, and India provided bottom-up volume estimates. Top-down triangulation against customs trade data and construction chemical industry association reports anchors market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by product chemistry, technology base, application substrate, and end-user channel. Modeled dimensions include water-based versus reactive versus silane-modified formulations, engineered wood versus luxury vinyl tile versus laminate applications, and renovation contractor versus construction company versus facility manager procurement archetypes. CAGRs derive from regression against construction spending indices, renovation intensity ratios, and regulatory compliance cost trajectories. Forecast inputs incorporate EU Green Deal building renovation target implementation schedules and ECHA SVHC notification timeline probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to isocyanate feedstock price volatility and cross-regional certification fragmentation between EPA, ECHA, and GB standards. A small set of triggers—ECHA substance of very high concern candidate list expansions, California Air Resources Board rule evolutions, and PLI scheme incentive adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Asia-Pacific Adhesives and Sealants Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
Adhesive Primer Market