
 Glass Reinforced Plastic (GRP) Piping Market | 2026-2036
Glass Reinforced Plastic (GRP) Piping Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Reinforced Plastic (GRP) Piping Market Analysis
The GRP piping industry is pivoting between premium engineered systems for offshore oil platforms and commodity-grade products for municipal drainage. Future Pipe Industries leverages filament-winding automation to sustain cost leadership in Middle Eastern water projects. Saudi Arabian Amiantit Company anchors its position through backward integration into resin formulation. HOBAS differentiates via centrifugal casting expertise for large-diameter pressure pipes.
Glass reinforced plastic piping consists of thermoset polymer matrices reinforced with continuous glass fiber filaments, typically manufactured through filament winding or centrifugal casting to achieve specific pressure ratings up to 32 bar. These composite conduits serve primarily to transport corrosive fluids, seawater, and process chemicals where metallic alternatives suffer galvanic degradation. The oil and gas application segment leads value generation due to offshore platform replacement cycles, while water treatment installations represent the fastest-growing end-use channel driven by desalination capacity additions. Custom product configurations command margin premiums over standardized horizontal and vertical geometries.
API standards for offshore riser systems, ISO 14692 for petroleum and natural gas industries, and NSF/ANSI 61 for drinking water system components collectively define certification barriers and performance benchmarks. The EPA enforces corrosion resistance thresholds that favor composite materials in underground chemical containment. ASTM D2992 provides hydrostatic design basis protocols that manufacturers must validate for market access. Stakeholders should monitor evolving hydrogen infrastructure codes, as GRP compatibility with pressurized hydrogen service remains an unresolved technical frontier requiring material qualification investments.
Market Dynamics
The EPA's Lead and Copper Rule revisions are compressing replacement cycles for municipal water infrastructure, forcing utilities toward corrosion-resistant composite alternatives and reshaping procurement specifications across North American distribution networks.
Growth Catalysts
- Corrosion Resistance Mandates:EPA enforcement of underground chemical containment thresholds favors thermoset composites over metallic alternatives in US industrial applications.
- Desalination Capacity Additions:Seawater intake and brine discharge systems across Saudi Arabia, UAE, and Oman specify GRP for saltwater corrosion immunity.
- Filament-Winding Automation:Continuous glass fiber placement technology reduces unit production costs for standardized pressure-rated pipe configurations.
Market Restraints
- Resin Price Volatility:Unsaturated polyester and vinyl ester feedstock costs fluctuate with crude oil derivatives, compressing margin stability for manufacturers without captive chemical production.
- Specialized Installation Labor:Thermoset jointing techniques require certified technicians, creating bottleneck constraints in regions lacking composite trades training infrastructure.
- Steel Pipe Substitution:Ductile iron and carbon steel maintain cost advantages in low-corrosion environments where chemical resistance specifications remain unenforced.
Strategic Opportunities
- Hydrogen Infrastructure Codes:Pressurized hydrogen service compatibility remains unresolved, creating first-mover advantage for material qualification investments ahead of ISO standard finalization.
- India Industrial Corridor Expansion:Chemical processing clusters in Gujarat and Maharashtra require thermoset composite infrastructure for acid and alkali transport systems.
- Centrifugal Casting Scale-Up:Large-diameter pressure pipe production via centrifugal casting addresses water transmission main specifications previously served by concrete cylinder pipe.
Industry Challenges
- ISO 14692 Certification Timelines:Petroleum and natural gas industry qualification protocols require extensive hydrostatic testing, extending product validation cycles for offshore riser applications.
- Legacy Metallic System Integration:Flange compatibility and cathodic protection isolation create engineering complexity when inserting GRP segments into existing steel pipeline networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Reinforced Plastic (GRP) Piping Market |
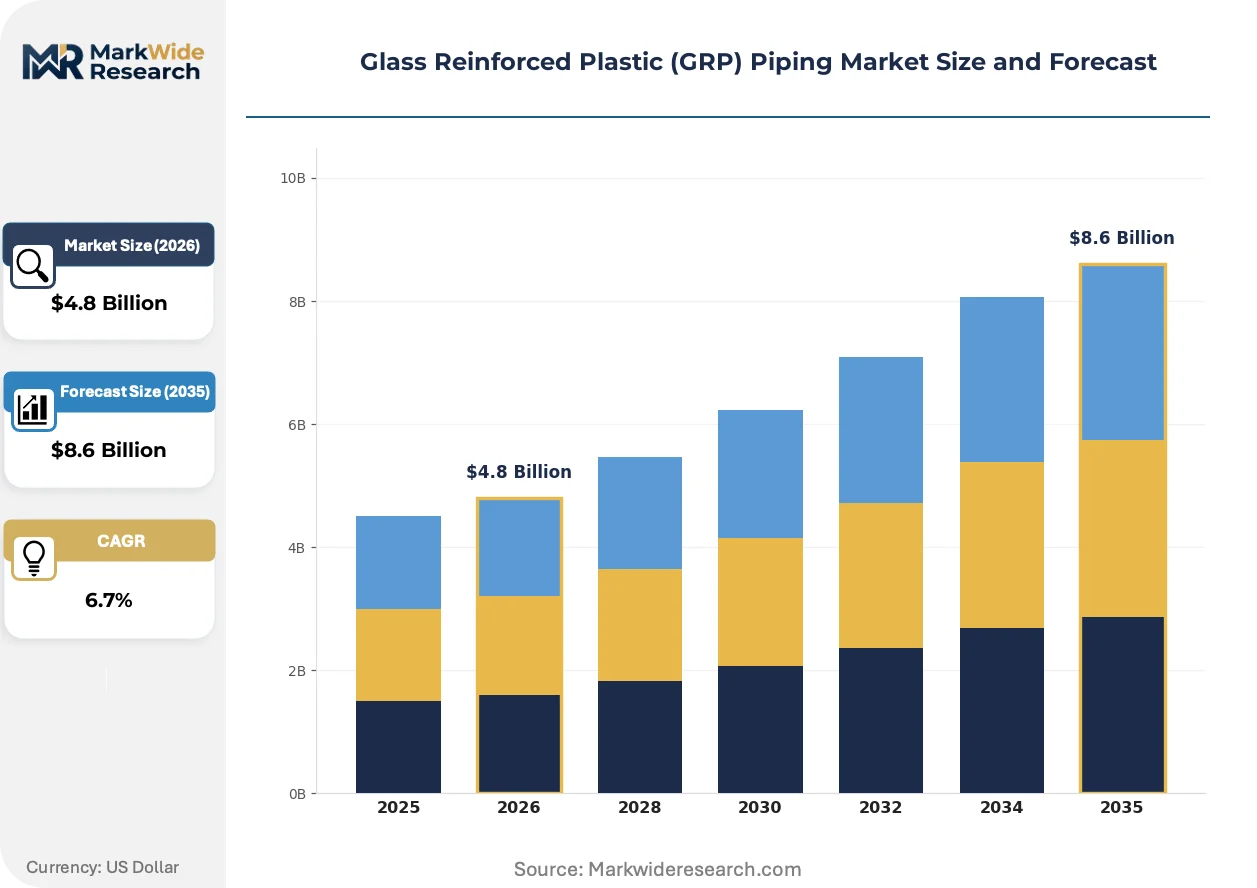
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Modular, Custom End User: Municipal, Industrial, Marine, Chemical Application: Water Treatment, Wastewater Management, Oil & Gas, Hydraulics Installation Method: Above Ground, Below Ground, Buried, Embedded |
| Companies Covered | Future Pipe Industries, Saudi Arabian Amiantit Company, HOBAS, Enduro Composites, Veplas d.d., Plasticon Composites, Dubai Pipes Factory, Hanwei Energy Services Corp., Abu Dhabi Pipe Factory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Reinforced Plastic (GRP) Piping Market Emerging Trajectories
Automation in manufacturing processes and evolving certification requirements are compressing product development cycles while expanding addressable application boundaries for thermoset composite conduits.
Filament-winding robotics is modularizing production workflows for customized pressure-rated configurations. Offshore platform operators in the North Sea and Gulf of Mexico specify automated-wound riser systems for replacement cycles. This manufacturing shift enables batch-size reduction without proportional cost escalation, supporting project-specific engineering demands.
REACH chemical substance restrictions in Europe are tightening resin formulation disclosure requirements for imported GRP products. The regulation forces reformulation of certain vinyl ester grades to eliminate Substances of Very High Concern. German and Dutch water utilities now require full material transparency documentation for municipal procurement compliance.
Asset owners increasingly unbundle after-sales inspection services from initial equipment supply contracts. Third-party drone-based condition monitoring replaces manufacturer-mandated maintenance agreements in Middle Eastern water transmission networks. Saudi Arabia's National Water Company pioneered this separation, with Abu Dhabi and Qatar utilities following the procurement restructuring.
Glass Reinforced Plastic (GRP) Piping Market Segmentation
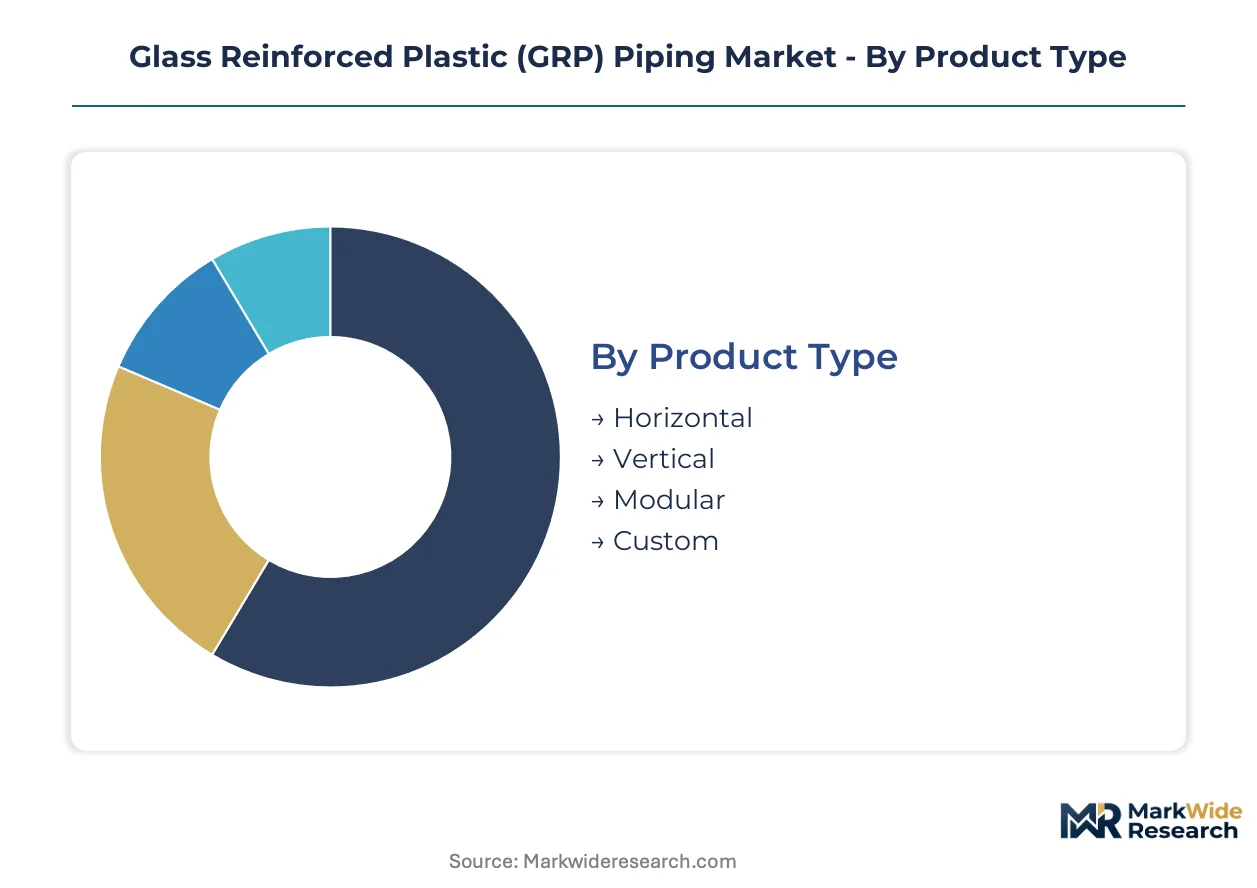
GRP piping configurations diverge sharply between standardized commodity products and engineered-to-order systems. Understanding these segment boundaries clarifies where manufacturers compete on cost versus where they command specification premiums.
Product Type:
Horizontal and vertical geometries dominate volume shipments, while custom configurations capture margin premiums through project-specific engineering.
- Horizontal:Standardized pressure-rated pipe sections manufactured via filament winding for municipal distribution networks. Demand concentrates in Saudi Arabian water transmission projects where corrosion resistance specifications override steel cost advantages.
- Vertical:Columnar configurations engineered for deep-well pump applications and offshore platform riser systems. Procurement from North Sea operators accelerates as API-standard replacement cycles compress.
- Modular:Prefabricated skid-mounted assemblies reduce field installation labor for chemical processing plants.
- Custom:Project-specific geometries with non-standard diameters or pressure ratings command engineering premiums.
Mature deployment sits with horizontal configurations. Newer deployment is concentrated in custom engineered systems.
End User:
Industrial and municipal procurement patterns diverge on certification requirements and replacement cycle timing.
- Municipal:Water and wastewater utilities specify NSF/ANSI 61 certified products for drinking water compliance. EPA Lead and Copper Rule revisions in the United States force accelerated replacement of metallic distribution infrastructure.
- Industrial:Chemical processing plants in Gujarat and Maharashtra require vinyl ester formulations for acid and alkali transport. BIS certification timelines create qualification barriers for imported systems.
- Marine:Desalination intake and brine discharge systems across UAE and Oman specify saltwater-immune GRP alternatives.
- Chemical:Underground chemical containment applications favor thermoset composites over steel where EPA corrosion resistance thresholds apply.
Volume leadership belongs to municipal procurement. Margin expansion concentrates in chemical end-use specifications.
Application:
Water-related applications generate shipment volume, while oil and gas specifications drive value concentration through offshore platform replacement demand.
- Water Treatment:Municipal filtration and distribution systems specify large-diameter pressure pipes. Centrifugal casting technology addresses transmission main requirements previously served by concrete cylinder pipe.
- Wastewater Management:Sewage collection and treatment infrastructure favors corrosion-resistant composites for underground service life extension.
- Oil & Gas:Offshore riser and platform piping systems require ISO 14692 qualification. Replacement cycles in the Gulf of Mexico and North Sea accelerate procurement of automated-wound configurations.
- Hydraulics:Pressurized fluid power systems in industrial automation represent emerging specification territory.
Established demand centers on water treatment. Oil and gas applications are expanding most quickly through offshore infrastructure renewal.
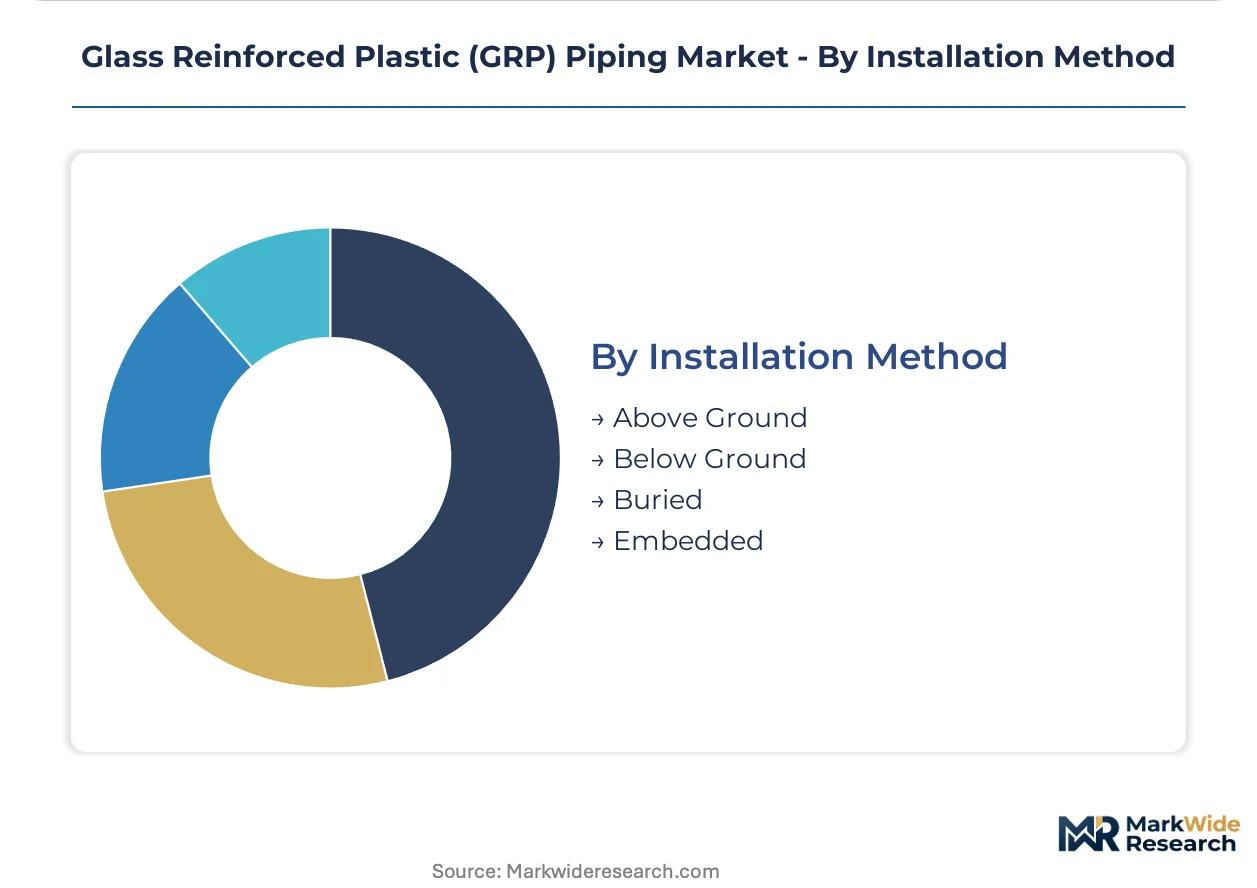
Installation Method:
Above-ground and buried methods split on labor skill requirements and cathodic protection complexity.
- Above Ground:Exposed piping arrays in chemical plants and desalination facilities simplify inspection access. Modular support systems reduce field welding requirements.
- Below Ground:Shallow burial for municipal distribution networks requires joint integrity validation against soil loading.
- Buried:Deep trench installations for water transmission mains demand external load calculations and bedding specification.
- Embedded:Concrete-encased configurations for structural integration in marine and industrial foundations.
Volume concentration sits with below-ground municipal installation. Technical complexity concentrates in embedded applications for marine structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City anchors GRP procurement volume through Saudi Aramco's desalination and petrochemical infrastructure. The city's integrated water-power complexes specify thermoset composite piping for brine handling and process chemical transport. This concentration shapes procurement patterns across the Middle East.
United States
Houston's petrochemical corridor drives demand for offshore platform riser replacements in the Gulf of Mexico. EPA Lead and Copper Rule revisions force municipal utilities in Flint, Michigan and Newark, New Jersey toward corrosion-resistant distribution networks. California's Central Valley water districts specify NSF/ANSI 61 certified products for agricultural drainage conversion.
Saudi Arabia
NEOM's linear city project and Red Sea tourism developments require large-diameter pressure piping for seawater intake systems. The National Water Company unbundled inspection services from supply contracts, restructuring procurement across Riyadh and Jeddah transmission networks. Jubail and Yanbu industrial cities anchor vinyl ester formulation demand for acid transport.
India
Gujarat's Dahej and Hazira chemical clusters specify thermoset composites for sulfuric acid and caustic soda handling. BIS certification timelines create qualification barriers for imported systems in Maharashtra's Mumbai-Pune industrial corridor. The Delhi-Mumbai Industrial Corridor projects accelerate specification of corrosion-resistant drainage infrastructure.
United Arab Emirates
Abu Dhabi's Taweelah reverse osmosis facility and Dubai's Hassyan power complex specify GRP for seawater intake and cooling water circuits. MOHAP's material transparency requirements align with REACH-equivalent disclosure standards for municipal procurement. Jebel Ali's port and free zone concentrates fabrication capacity serving GCC water transmission projects.
Germany
The Rhine-Ruhr chemical processing belt demands vinyl ester piping for chlorine and hydrogen peroxide transport. REACH chemical substance restrictions force reformulation of certain resin grades to eliminate Substances of Very High Concern. Hamburg's port infrastructure and Bavaria's industrial municipalities require full material documentation for underground containment systems.
Glass Reinforced Plastic (GRP) Piping Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification complexity and project engineering intensity. The vendor base organizes into three tiers: integrated resin-to-pipe manufacturers, filament-winding automation specialists, and regional fabrication contractors. Strategic differentiation concentrates on backward integration into resin formulation, centrifugal casting scale for large-diameter pressure ratings, and captive installation service networks. Geographic expansion through port-proximate fabrication and technology licensing to regional partners represent dominant competitive vectors.
Within the integrated manufacturer tier, Saudi Arabian Amiantit Company and Future Pipe Industries exemplify scale-driven positioning across Middle Eastern water infrastructure. HOBAS occupies a specialist position in centrifugal casting expertise for European and North American municipal specifications. Among regional fabricators, Dubai Pipes Factory and Abu Dhabi Pipe Factory anchor Gulf-based procurement proximity. Enduro Composites represents the North American engineering-focused archetype serving industrial chemical containment specifications.
| Leading Market Players |
|---|
| Future Pipe Industries |
| Saudi Arabian Amiantit Company |
| HOBAS |
| Enduro Composites |
| Veplas d.d. |
| Plasticon Composites |
| Dubai Pipes Factory |
| Hanwei Energy Services Corp. |
| Abu Dhabi Pipe Factory |
| Others |
Supply Flow & Price Mechanics
EPA Lead and Copper Rule revisions are compressing municipal procurement timelines and forcing utilities toward corrosion-resistant specifications, compelling manufacturers to absorb certification costs while competing for accelerated replacement contracts. This demand-side pressure concentrates pricing power among resin-integrated producers capable of rapid qualification turnaround.
Pricing Analysis
Project-specific engineering premiums anchor value-based pricing for offshore riser configurations, where ISO 14692 certification tier and filament-winding automation grade determine margin capture. Three-tier pricing structure across premium certified, standard pressure-rated, and commodity drainage levels separates specification-driven procurement from cost-sensitive municipal volume. Pricing pressure stems from unsaturated polyester feedstock volatility linked to crude oil derivatives, squeezing margin stability for non-integrated manufacturers. Municipal utilities exhibit highest price sensitivity due to bond-financed capital constraints, while oil and gas operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Arabia and the UAE for large-diameter centrifugal casting capacity serving Middle Eastern water transmission projects. Glass fiber roving draws from China and the United States, while vinyl ester resin formulation concentrates among German and Dutch chemical producers subject to REACH disclosure mandates. Tariff exposure on imported resin grades threatens margin stability for regional fabricators lacking captive chemical production. Distribution runs through port-proximate fabrication clusters in Jubail, Jebel Ali, and Houston, with third-party logistics handling final-mile installation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GRP piping market is becoming a vertical-integration race where resin formulation control and automated manufacturing scale determine competitive survival. Players are pursuing backward integration into thermoset chemistry to escape feedstock volatility and accelerate certification timelines.
For Market Incumbents: Deploy filament-winding robotics scale-up in Middle Eastern port zones to defend cost leadership against emerging Asian competitors. Capture municipal procurement consolidation by bundling NSF/ANSI 61 certification with drone-based inspection services, separating hardware supply from recurring revenue streams. Resin price volatility and steel pipe substitution in low-corrosion environments remain the primary margin threats requiring captive chemical production as counterweight. For New Entrants and Emerging Players: Launch via technology licensing to Indian regional fabricators, exploiting BIS certification bottlenecks that delay imported system qualification. Target Gujarat and Maharashtra chemical clusters with vinyl ester expertise for acid transport specifications, where incumbent presence remains thin. Hydrogen infrastructure material qualification offers first-mover positioning ahead of ISO standard finalization. For Investors and Strategic Acquirers: The window for entry favors resin-integrated mid-cap specialists with centrifugal casting scale and regional certification depth. Long-term viability rests on exposure to desalination capacity expansion and offshore platform replacement cycles rather than commodity municipal drainage. Watch hydrogen pipeline compatibility test results as the critical inflection signal for material qualification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive vinyl ester production insulates margins from crude-linked feedstock volatility. |
| Filament-Winding Automation Scale-Up | Robotics deployment in Jubail and Jebel Ali reduces per-unit costs for standardized pressure ratings. |
| ISO 14692 Certification Investment | Offshore riser qualification opens Gulf of Mexico and North Sea replacement procurement. |
| Drone-Based Inspection Unbundling | Saudi National Water Company's procurement restructuring creates recurring service revenue streams. |
| Hydrogen Compatibility Qualification | Pressurized hydrogen service testing positions manufacturers for emerging infrastructure codes. |
Methodological Framework
Document review covered customs trade databases, EPA enforcement records, and ISO certification registries, complemented by interviews with plant engineers at chemical processing facilities, procurement managers at Saudi Aramco and National Water Company, technical directors at filament-winding equipment suppliers, and regulatory affairs leads at resin formulation companies. Secondary sources included SEC 10-K filings from integrated manufacturers, BIS notification records, and REACH substance restriction updates. Bottom-up shipment estimates triangulated against top-down infrastructure investment forecasts.
Segment-level projections across product type, end user, application, and installation method combined with regional production cluster analysis produced volume and value estimates over the projection horizon. CAGRs derived from regression against historical infrastructure spending correlations, desalination capacity addition schedules, and offshore platform replacement cycle data. Hydrogen infrastructure code development timelines and REACH chemical disclosure expansion served as scenario inputs.
Resin price volatility, certification timeline delays, and hydrogen compatibility test failures are the dominant revision risks that could compress or extend replacement cycle assumptions. Forecasts reflect documented infrastructure investment commitments and regulatory enforcement trajectories without claiming predictive certainty. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market