
 Industrial Tubes Market | 2026-2036
Industrial Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Tubes Market Intelligence
Consolidation among European specialty steel producers is hardening the supply landscape for high-pressure seamless tubes. Vallourec S.A. leverages its extensive manufacturing footprint to serve the oil and gas sector. Sandvik AB differentiates through its focus on advanced corrosion-resistant alloys for chemical processing applications. Tenaris sustains its market position with a dedicated supply chain for energy-related projects.
Industrial tubes are hollow cylindrical structures engineered from materials like steel, copper, or aluminum for fluid transport or structural applications. They are manufactured to precise dimensional tolerances, often through processes like extrusion or electric resistance welding (ERW), to handle specific pressure and temperature ratings. Seamless tubes command a premium due to their superior strength, making them essential for high-pressure oil & gas applications. Welded tubes, including ERW types, dominate volume in structural components and general piping systems due to lower production costs.
Product specifications are governed by standards from bodies like ISO and the American Society of Mechanical Engineers (ASME), ensuring safety in critical applications. In Europe, compliance with the Pressure Equipment Directive (PED) is mandatory for market access, influencing material selection and testing protocols. Navigating the patchwork of regional certifications and material traceability requirements remains a central challenge for component suppliers.
Market Dynamics
The industrial tubes market is defined by a structural tension between demand for higher performance alloys, driven by stricter environmental regulations, and the concentrated supply base for manufacturing these specialty products, particularly for seamless high-pressure applications.
Growth Catalysts
- Public Infrastructure Investment:Large-scale energy and infrastructure projects, particularly in India, create sustained demand for steel and alloy tubes for power plants, water systems, and transportation networks.
- Power Generation Retrofits:The need to upgrade aging power generation facilities to meet efficiency and emissions standards, such as the EU's Industrial Emissions Directive, requires extensive use of high-performance tubing.
- Advanced Material Development:The creation of new nickel and steel alloys with superior corrosion resistance and high-temperature strength enables tube usage in more demanding chemical processing and energy applications.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of key raw materials like nickel, chromium, and molybdenum directly impact the production cost and pricing stability of high-grade alloy tubes.
- Substitution from Polymers:In lower-pressure and less critical applications, advanced composite and polymer piping systems present a cost-effective alternative to traditional metal tubes, particularly in water and wastewater.
- Manufacturing Consolidation:A concentrated number of European and Japanese mills capable of producing high-specification seamless tubes limits supply options and creates potential bottlenecks for critical projects.
Strategic Opportunities
- Hydrogen Economy Infrastructure:The build-out of hydrogen production, storage, and transport systems requires specialized tubes capable of handling embrittlement and high pressures, creating a new application segment. *
- Desalination Plant Construction:Increasing water scarcity drives investment in desalination facilities, particularly in the Middle East and North Africa, which utilize large volumes of corrosion-resistant tubes.
- Additive Manufacturing:3D printing of complex metal tube assemblies and custom fittings offers a path to producing specialized components for low-volume, high-value sectors like aerospace and medical devices.
Industry Challenges
- Certification and Compliance Complexity:Manufacturers face significant administrative overhead in managing a mosaic of regional and application-specific certifications, such as the Pressure Equipment Directive (PED) and ASME codes.
- Skilled Labor Scarcity:A persistent shortage of certified welders and non-destructive testing technicians qualified to work with advanced alloys constrains installation and maintenance capacity for high-specification projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Tubes Market |
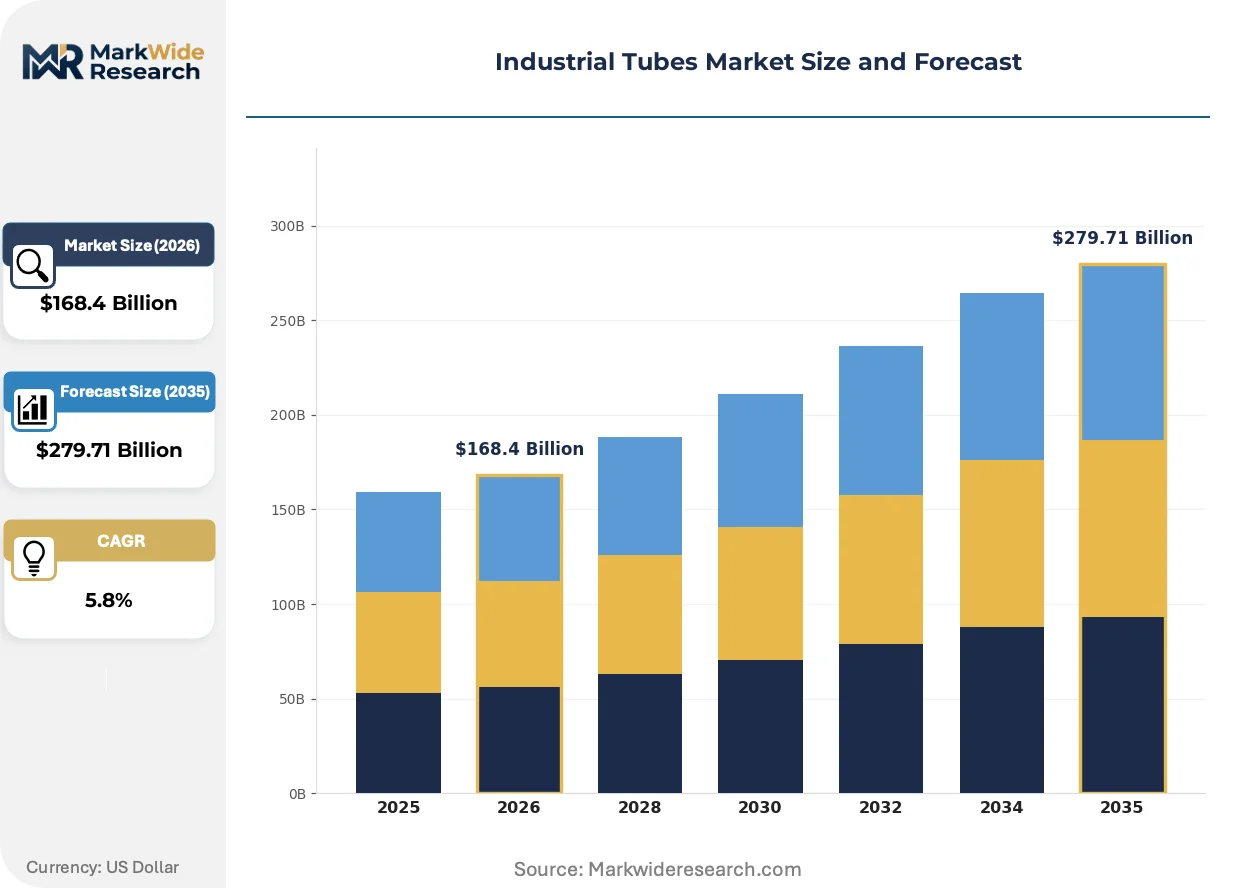
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Aluminum, Copper, PVC, Brass, Fiberglass Product Type: Seamless Tubes, Welded Tubes, Drawn Over Mandrel Tubes, ERW Tubes, Precision Tubes Application: Piping Systems, Structural Components, Hydraulic Cylinders, Heat Exchangers, Mechanical Parts End User Industry: Oil & Gas, Aerospace, Chemical Processing, Power Generation, Shipbuilding |
| Companies Covered | Nippon Steel Corporation, Vallourec S.A., Tenaris, Sandvik AB, Tata Steel, JFE Steel Corporation, ArcelorMittal, U.S. Steel Corporation, Benteler International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Tubes Market Strategic Shifts & Innovations
The competitive landscape for industrial tubes is reshaping around material traceability and manufacturing process automation. These shifts respond directly to end-user demands for greater safety assurance in critical systems and improved operational efficiency from component suppliers.
Advanced Inspection Technologies
Automated non-destructive testing (NDT) systems are gaining traction in manufacturing facilities. Major end-users in the power generation and oil and gas sectors are increasingly specifying advanced inspection methods like phased array ultrasonic testing (PAUT). This technology is automating quality control, replacing manual checks to deliver faster and more reliable defect detection for seamless and welded tubes.
Stricter Emissions Regulations
Legislation like the EU's Industrial Emissions Directive (IED) is a primary influence on material specification. The directive compels industrial operators in sectors like energy and chemicals to adopt Best Available Techniques (BAT) to reduce pollution, which often necessitates upgrading to higher-grade alloy tubes that can withstand more corrosive environments and higher operating temperatures. This trend most directly impacts producers of specialty seamless tubes.
Project-Based Traceability Mandates
A shift toward project-based procurement with stringent material traceability requirements is altering supply chain dynamics. This disrupts the traditional stock-and-sell model of distributors, forcing a move toward documented, heat-traceable supply chains from the mill to the final installation. This behavior is most pronounced in the nuclear, LNG, and offshore oil and gas verticals, where component provenance is a non-negotiable safety requirement.
Industrial Tubes Market Segmentation
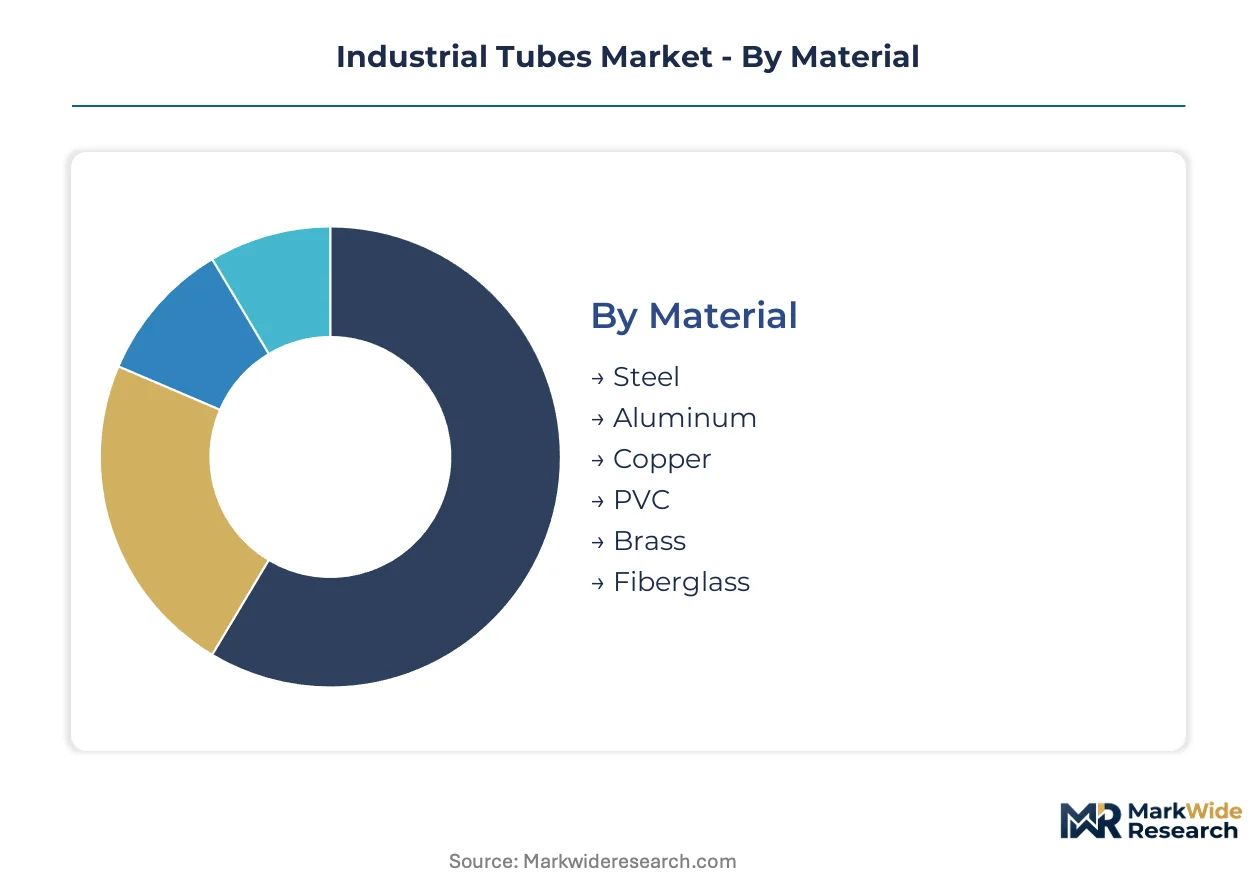
The industrial tubes market is diverse, with segmentation highlighting the critical differences in material properties, manufacturing processes, and end-use requirements. Understanding these distinctions is essential for suppliers to tailor product offerings and for end-users to select components optimized for specific operational demands.
Material:
Material selection in industrial tubes often divides between high-volume, cost-effective options and premium alloys designed for extreme conditions.
- Steel:This material dominates the market due to its strength, versatility, and cost-effectiveness, finding extensive use across structural and fluid transport applications. Demand for steel tubes is sustained by large-scale infrastructure projects in India.
- Aluminum:Known for its lightweight properties and corrosion resistance, aluminum tubes are crucial in applications where weight reduction is paramount, such as aerospace and certain transportation sectors. Its usage expands in applications requiring good thermal conductivity.
- Copper:Copper tubes are widely used for their excellent thermal conductivity and corrosion resistance in water supply systems and HVAC applications.
- PVC:Polyvinyl chloride tubes offer a cost-effective and chemically resistant option for low-pressure fluid transfer, particularly in water and wastewater infrastructure.
- Brass:Brass tubes provide good corrosion resistance and machinability, making them suitable for ornamental applications and specific plumbing fittings.
- Fiberglass:Fiberglass reinforced plastic (FRP) tubes are employed in highly corrosive environments where metal tubes would quickly degrade, often in chemical processing plants.
Today's leader: Steel. Tomorrow's challenger: Fiberglass.
Product Type:
Industrial tube product types are differentiated by their manufacturing methods, which directly influence their structural integrity and suitability for various pressure ratings.
- Seamless Tubes:These tubes are manufactured without a weld seam, offering superior strength and integrity for high-pressure and high-temperature applications in oil and gas. Consolidation among European specialty steel producers affects their supply.
- Welded Tubes:Produced by forming metal strips into a cylindrical shape and welding the edges, welded tubes are more cost-effective and widely used for structural components and general piping systems. ERW types dominate volume in many sectors.
- Drawn Over Mandrel Tubes:DOM tubes are cold-drawn electric resistance welded tubes, offering improved dimensional accuracy and surface finish for applications requiring precise tolerances.
- ERW Tubes:Electric Resistance Welded tubes are a type of welded tube known for their cost-effectiveness and are commonly used in automotive, structural, and general engineering applications.
- Precision Tubes:These tubes are manufactured to extremely tight dimensional tolerances and surface finishes, making them critical for sensitive instruments and hydraulic systems.
The market volume heavily favors welded tubes, while seamless variants command a premium for critical applications.
Application:
Industrial tubes serve a broad spectrum of functions, with demand patterns shaped by the specific performance requirements of each application area.
- Piping Systems:This segment represents the largest application, encompassing the transport of fluids, gases, and slurries across industries from power generation to chemical processing. Stricter emissions regulations necessitate higher-grade alloys in these systems.
- Structural Components:Tubes provide essential support and framework in construction, manufacturing, and general engineering, valued for their strength-to-weight ratio. Welded tubes dominate volume in this segment due to lower production costs.
- Hydraulic Cylinders:Precision tubes are critical for hydraulic systems, where smooth internal surfaces and exact dimensions ensure efficient and reliable operation.
- Heat Exchangers:Tubes in heat exchangers facilitate thermal energy transfer between fluids, requiring materials with good conductivity and corrosion resistance in demanding environments.
- Mechanical Parts:Industrial tubes are often machined or fabricated into various mechanical components, offering versatility for custom engineering solutions.
Demand for piping systems remains foundational, with heat exchangers expanding most quickly.
End User Industry:
The end-user industry segmentation highlights the diverse sectors that rely on industrial tubes, each with unique material and specification requirements.
- Oil & Gas:This sector requires high-performance seamless tubes capable of withstanding extreme pressures, corrosive environments, and high temperatures for exploration, production, and transportation. Vallourec S.A. leverages its manufacturing footprint to serve this sector.
- Power Generation:Demand from this industry is significant for new plant construction and retrofitting aging facilities, driven by efficiency and emissions standards like the EU's Industrial Emissions Directive. High-performance tubing is essential for these upgrades.
- Aerospace:Lightweight, high-strength, and high-precision tubes are critical for aircraft structures, hydraulic systems, and engine components, where material integrity is paramount.
- Chemical Processing:This industry demands corrosion-resistant alloys for tubes that handle aggressive chemicals at varying temperatures and pressures, with Sandvik AB focusing on advanced alloys for these applications.
- Shipbuilding:Tubes are extensively used in shipbuilding for piping systems, structural elements, and hydraulic lines, requiring materials resistant to saltwater corrosion and demanding marine conditions.
The Oil & Gas sector represents a stable core, while power generation retrofits are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While India's extensive public infrastructure and energy projects drive significant demand for steel tubes, Germany's market emphasizes higher performance alloys for industrial upgrades. Both nations exhibit distinct but substantial requirements for industrial tubes. These regional demands influence global supply chain configurations.
India
India's robust public infrastructure investment and energy projects fuel substantial demand for industrial tubes. The PLI scheme supports domestic manufacturing capabilities, including steel and alloy production. Major industrial corridors like the Delhi-Mumbai Industrial Corridor are seeing extensive tube deployment for new power plants and water systems.
Germany
Germany's industrial sector prioritizes advanced alloys for power generation retrofits and chemical processing applications. Compliance with the EU's Industrial Emissions Directive necessitates high-performance tubing in many facilities. The Ruhr region, a traditional industrial heartland, continues to drive demand for specialized tubes in upgraded manufacturing plants.
United States
United States demand for industrial tubes stems from its vast oil and gas sector and ongoing infrastructure modernization. Regulations from the EPA often drive material upgrades in chemical and energy facilities. The Gulf Coast region, with its extensive petrochemical and refining complexes, remains a primary consumer of high-pressure seamless tubes.
Saudi Arabia
Saudi Arabia's ambitious desalination plant construction and oil and gas expansion projects create significant tube requirements. The country's national development plans, like Vision 2030, stimulate investment in advanced materials. NEOM, a flagship giga-project, is expected to generate substantial demand for specialized tubes for its diverse infrastructure needs.
China
China's extensive industrial base and continuous infrastructure development maintain strong demand for various industrial tubes. The dual carbon goals are accelerating upgrades in energy and manufacturing sectors, requiring higher-specification materials. The Yangtze River Delta region, a major manufacturing hub, sees significant tube consumption for its diverse industrial applications.
Industrial Tubes Market Key Industry Players
European producers anchor one tier; Asian specialists hold another within the industrial tubes market. The market structure exhibits a tiered consolidation, with a few large integrated mills dominating high-specification seamless tube production. Strategic archetypes include global diversified manufacturers, regional niche specialists, and cost-effective volume producers. Competitive moves primarily involve capacity expansion in advanced alloys and strategic partnerships for project-based supply chains.
Specialists in high-performance applications include Vallourec S.A., which leverages its extensive manufacturing footprint to serve the demanding oil and gas sector. Sandvik AB exemplifies differentiation through its focus on advanced corrosion-resistant alloys, particularly for chemical processing applications where material integrity is paramount. Tenaris sustains its market position with a dedicated supply chain tailored for energy-related projects, reinforcing its role in critical infrastructure development. These companies operate at the premium end, emphasizing material science, application-specific engineering, and stringent quality control for critical systems.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Vallourec S.A. |
| Tenaris |
| Sandvik AB |
| Tata Steel |
| JFE Steel Corporation |
| ArcelorMittal |
| U.S. Steel Corporation |
| Benteler International |
| Others |
Cost & Logistics Intelligence
Skilled welders in the Ruhr region, with their specialized expertise in high-performance alloys, drive premium pricing for seamless tubes. Labor-cost differentials influence the spread between standard welded and specialized tube offerings.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard steel tubes. The dominant pricing model is project-based, with long-term contracts for major infrastructure. Price differentiation stems from certification levels, such as ASME codes, and customization required for specific applications. Pricing softness for commodity tubes reflects oversupply from Asian mills, while end-users in critical applications like nuclear power exhibit low price sensitivity compared to structural component buyers.
Supply Chain Analysis
Reverse logistics for industrial tubes primarily involve scrap metal recycling, feeding back into primary steel production. Supply concentration centers in European countries like Germany and Asian specialists in China and Japan. Production relies on key raw materials such as nickel, chromium, and molybdenum, which are prone to input cost volatility. Single-source vulnerability for high-specification seamless tubes presents a significant structural risk, with distribution running through specialized industrial distributors and direct-to-project channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial tubes market is a late-cycle quality story, driven by a demand shift towards premium specifications for corrosion-resistant alloys. Stricter environmental regulations, like the EU's Industrial Emissions Directive, necessitate these higher-grade materials.
For Market Incumbents:Anchor R&D investments in advanced alloy development to counter substitution from polymers in less critical applications. Consolidate fragmented manufacturing footprints to achieve economies of scale for high-pressure seamless tubes. Invest in certification expertise, particularly for the Pressure Equipment Directive (PED), to maintain market access. The threat of input cost volatility demands robust supply chain resilience planning.
For New Entrants and Emerging Players:A price-point gap exists between premium corrosion-resistant tubes and standard welded options, offering entry for specialized fabricators. Target the hydrogen economy infrastructure segment with tubes capable of handling embrittlement. Penetrate desalination plant construction in the Middle East and North Africa, focusing on niche material requirements. Partner with engineering, procurement, and construction (EPC) firms for project-based supply.
For Investors and Strategic Acquirers:Integrated steel producers are the most active acquirers in this space, seeking to expand their high-performance alloy capabilities. The market offers long-term viability, driven by essential infrastructure and energy transition projects over the next decade. Target mid-sized specialists with proprietary manufacturing processes for precision tubes. Watch for increasing M&A activity among European specialty steel producers as a consolidation signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Alloys | Expands output for high-performance applications like chemical processing, meeting stricter emissions regulations. |
| Long-term Supply Agreement with OEMs | Secures stable demand for specialized tubes in sectors like power generation and oil & gas. |
| Green Manufacturing Transition | Enhances sustainability credentials, aligning with EU Green Deal objectives for industrial operations. |
| Joint Venture for Hydrogen Infrastructure | Develops specialized tube solutions for the emerging hydrogen economy, addressing unique material challenges. |
| Certification Investment (ASME/PED) | Ensures market access and compliance for critical applications in Europe and North America. |
Research Approach
Direct dialogue with plant managers, procurement leads, R&D directors, and EPC contractors provided qualitative insights. This primary research was triangulated with secondary data from ISO standards, ASME codes, national trade statistics, and company 10-K filings. A bottom-up approach aggregated segment-level data, validated against top-down market sizing estimates, ensuring comprehensive data validation.
A bottom-up analytical framework projected market growth across the analysis window, validated by top-down macroeconomic indicators. Segmentation dimensions modeled include material type, product type, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and expert consensus. Raw material price volatility served as a critical forecast input.
Caveats apply where significant shifts in global trade policies or raw material supply could materially shift the outlook. Forecasts reflect assumptions regarding sustained infrastructure spending and regulatory enforcement. Practitioners should monitor geopolitical stability and additive manufacturing advancements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Europe Pipe Market
Pipes and Tubes
Portugal PVC Pipes Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Global Butt Weld Fittings Market