
 Hose Reinforcement Wire Market | 2026-2036
Hose Reinforcement Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Hose Reinforcement Wire Market Insights
Construction firms and mining operations are redrawing procurement priorities for hose reinforcement wire as oilfield services expand capital deployment into deeper well pressure systems. Bekaert leverages its integrated steel wire drawing capacity across European and Asian production nodes. Hyosung Advanced Material anchors supply relationships with Korean construction equipment OEMs through dedicated metallurgy labs. Gustav Wolf GmbH specializes in precision brass wire coatings for chemical transfer applications where corrosion resistance commands premium positioning.
Hose reinforcement wire consists of high-tensile steel, brass, or stainless steel filaments engineered into woven, spiral, or braided configurations to withstand internal pressures exceeding 6,000 psi in hydraulic and pneumatic assemblies. Manufacturing involves multi-stage cold drawing, patenting heat treatment, and brass or zinc plating to achieve specified tensile strength and adhesion for rubber hose embedding. Steel wire dominates volume due to cost efficiency in construction and mining hose bundles, while stainless steel wire captures margin pools in chemical transfer and offshore oilfield segments where chloride corrosion resistance is non-negotiable. Braided wire technology leads in mobile hydraulic equipment, whereas spiral wire configurations dominate static high-pressure industrial fluid systems.
EPA emissions regulations and OSHA workplace safety standards govern hose assembly certification in the US, while REACH and the EU Machinery Directive enforce material disclosure and pressure equipment conformity across European supply chains. China's GB standards and MIIT industrial policy directives shape domestic content requirements and quality benchmarks for hydraulic components. Stakeholders must monitor divergence between regional pressure testing protocols and alloy composition mandates when configuring multinational supply footprints.
Market Dynamics
Shale extraction operators are driving procurement toward high-pressure hose assemblies rated above 6,000 psi, forcing wire manufacturers to recalibrate tensile strength specifications and brass coating adhesion protocols across their production lines.
Growth Catalysts
- Hydraulic fracturing intensity:Oilfield services operators in the Permian Basin and Bakken formation are expanding capital deployment into deeper well pressure systems, directly lifting demand for spiral-wire-reinforced high-pressure hose bundles.
- REACH material traceability:European ECHA enforcement is tightening alloy composition disclosure requirements, creating competitive advantage for wire producers with certified brass plating and heat treatment documentation systems already in place.
- China infrastructure buildout:Domestic hydraulic equipment manufacturing scale under MIIT industrial policy directives is concentrating demand for steel reinforcement wire within Chinese OEM supply chains.
Market Restraints
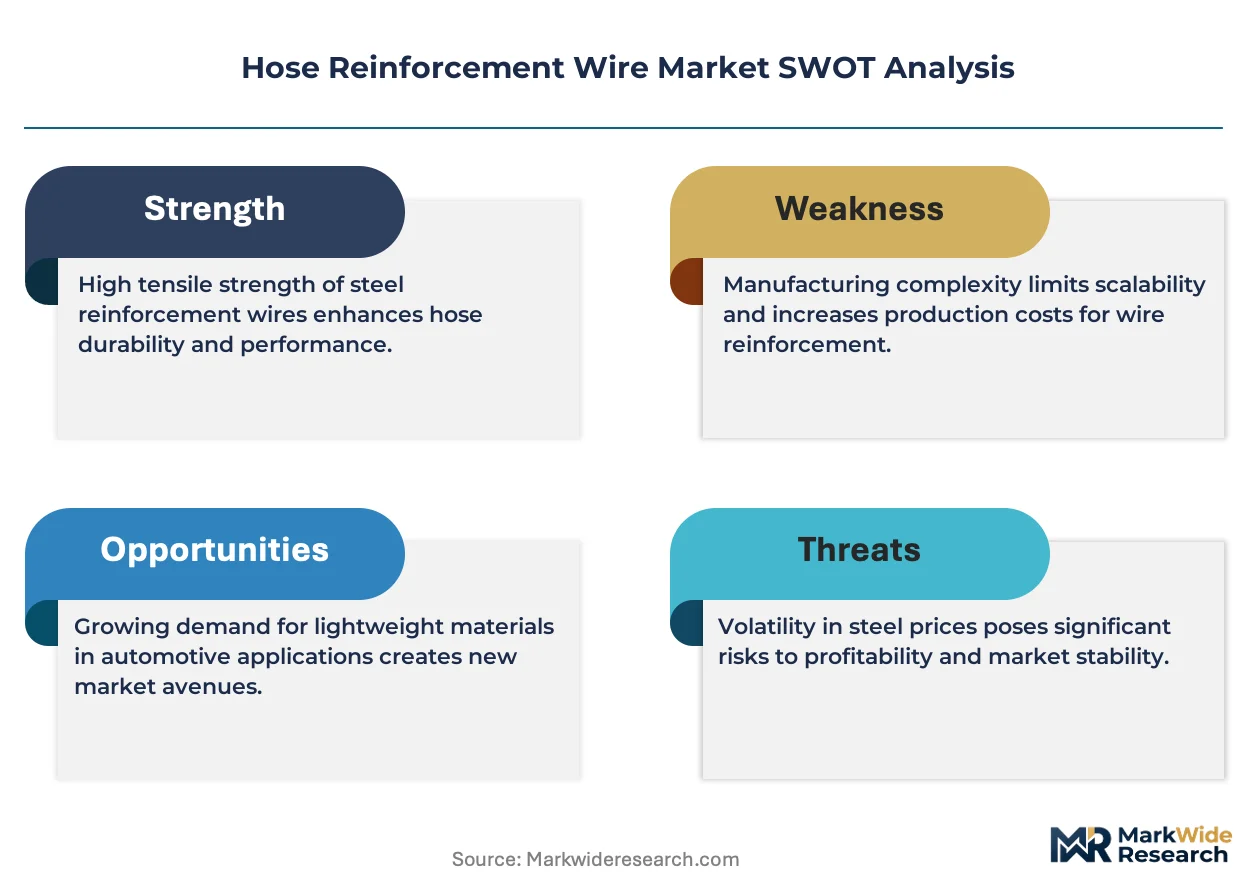
- Steel input cost volatility:Cold-rolled high-carbon steel rod prices fluctuate with scrap metal and energy costs, compressing margin predictability for wire drawing operations without captive steelmaking.
- Supply concentration in East Asian wire drawing:A limited set of integrated producers controls patenting heat treatment capacity, creating bottleneck risk for independent hose manufacturers seeking qualified reinforcement suppliers.
- Stainless steel substitution ceiling:Duplex stainless wire captures premium chemical transfer applications, but cost barriers prevent displacement of brass-coated steel in construction and mining volume segments.
Strategic Opportunities
- India hydraulic equipment localization:PLI scheme incentives for construction machinery manufacturing are creating import-substitution openings for wire producers willing to establish local drawing and plating operations.
- Carbon-neutral steel wire:Electric arc furnace-based production with renewable energy sourcing aligns with EU Green Deal procurement criteria, enabling premium positioning for early adopters in European supply chains.
- Digital pressure monitoring integration:Convergence of embedded fiber optic sensing with traditional wire reinforcement enables real-time hose health diagnostics for offshore oilfield operators seeking predictive maintenance capabilities.
Industry Challenges
- Metallurgical talent scarcity:Cold drawing process engineers with expertise in multi-stage patenting and brass adhesion optimization are concentrated among retiring cohorts at established European and Japanese producers.
- EPA emissions certification timelines:New hose assembly validation under evolving workplace safety standards requires extended pressure cycling tests, stretching product development cycles for wire specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hose Reinforcement Wire Market |
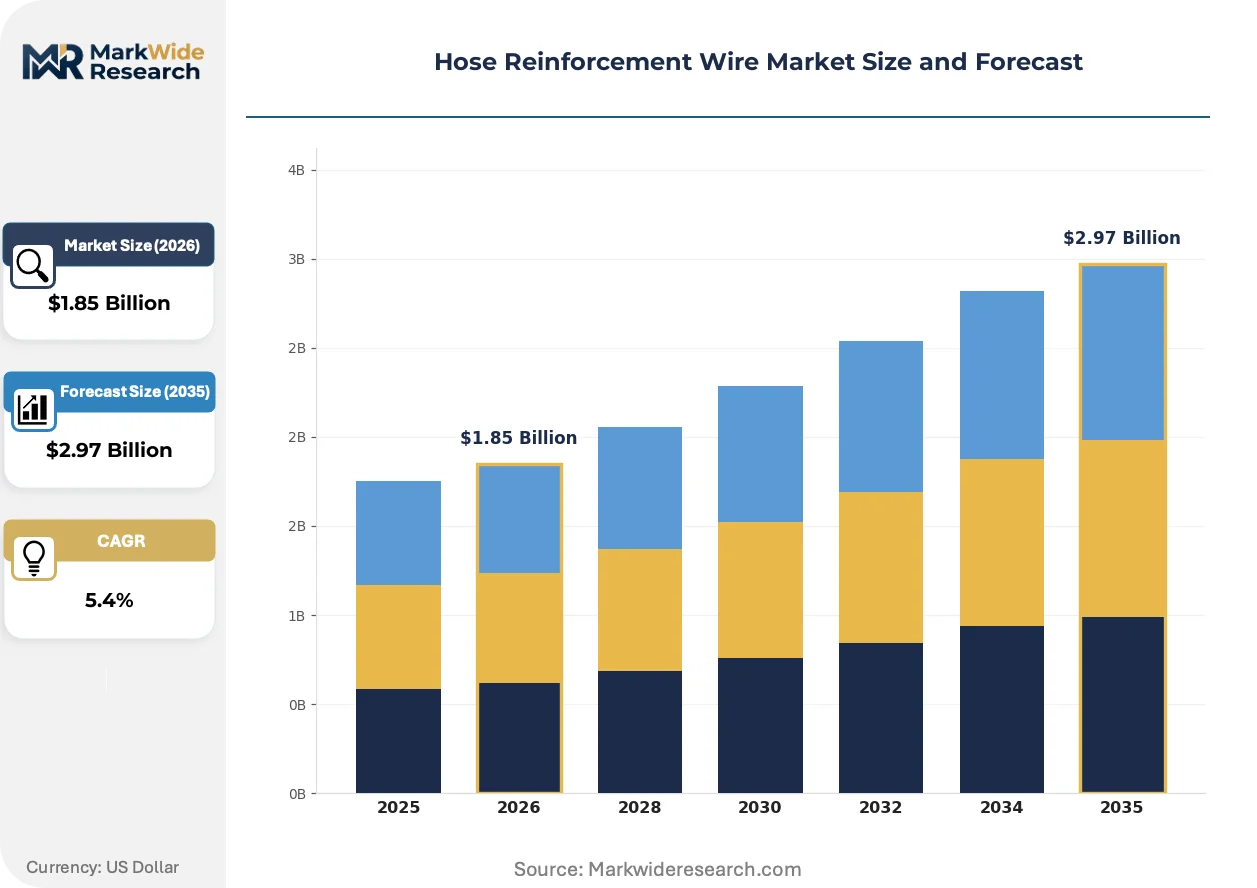
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wire, Brass Wire, Stainless Steel Wire, Copper Wire, Aluminum Wire Technology: Woven Wire, Spiral Wire, Braided Wire, Wrapped Wire, Corrugated Wire Application: Hydraulic Hoses, Industrial Fluids, Chemical Transfer, Pneumatic Systems, Agricultural Equipment End User: Manufacturers, Construction Firms, Mining Operations, Oilfield Services, Transportation Companies |
| Companies Covered | Bekaert, KIS Wire, Shandong Daye, Hyosung Advanced Material, Henan Hengxing, BMZ, Tokyo Rope Mfg, Sumin Metals, Gustav Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hose Reinforcement Wire Market Trends and Innovations
Wire reinforcement technology is splitting along performance-versus-cost axes as end-use verticals diverge in pressure, corrosion, and monitoring requirements. Three developments are restructuring competitive positioning.
High-strength micro-alloyed steel wire is bifurcating the mobile hydraulic equipment segment. Construction OEMs in Germany and Japan are adopting 2,000 MPa tensile strength grades for compact excavator hose bundles, while mining operators in Australia and Canada retain conventional 1,770 MPa specifications for cost-sensitive bulk material handling. This performance tiering is compressing mid-range product margins and forcing wire producers to commit to single-tier specialization.
EPA emissions rules are tightening material certification requirements for hose assemblies used in diesel-powered construction and mining equipment. The industrial consequence is mandatory third-party validation of wire-to-rubber adhesion under thermal cycling, extending qualification timelines by four to six months. North American distributors are responding by consolidating supplier relationships toward wire producers with in-house testing laboratories already accredited to ISO 17025 standards.
Specification consolidation among rental fleet operators is reshaping procurement patterns for replacement hose assemblies. United Rentals and similar multi-regional lessors are standardizing on braided-wire configurations across equipment categories, displacing the fragmented OEM-specific spiral-wire legacy specifications that dominated aftermarket procurement. This concentration is most visible in the US Southeast, where equipment rental density supports direct mill-to-fleet supply contracts bypassing traditional distribution layers.
Hose Reinforcement Wire Market Segmentation
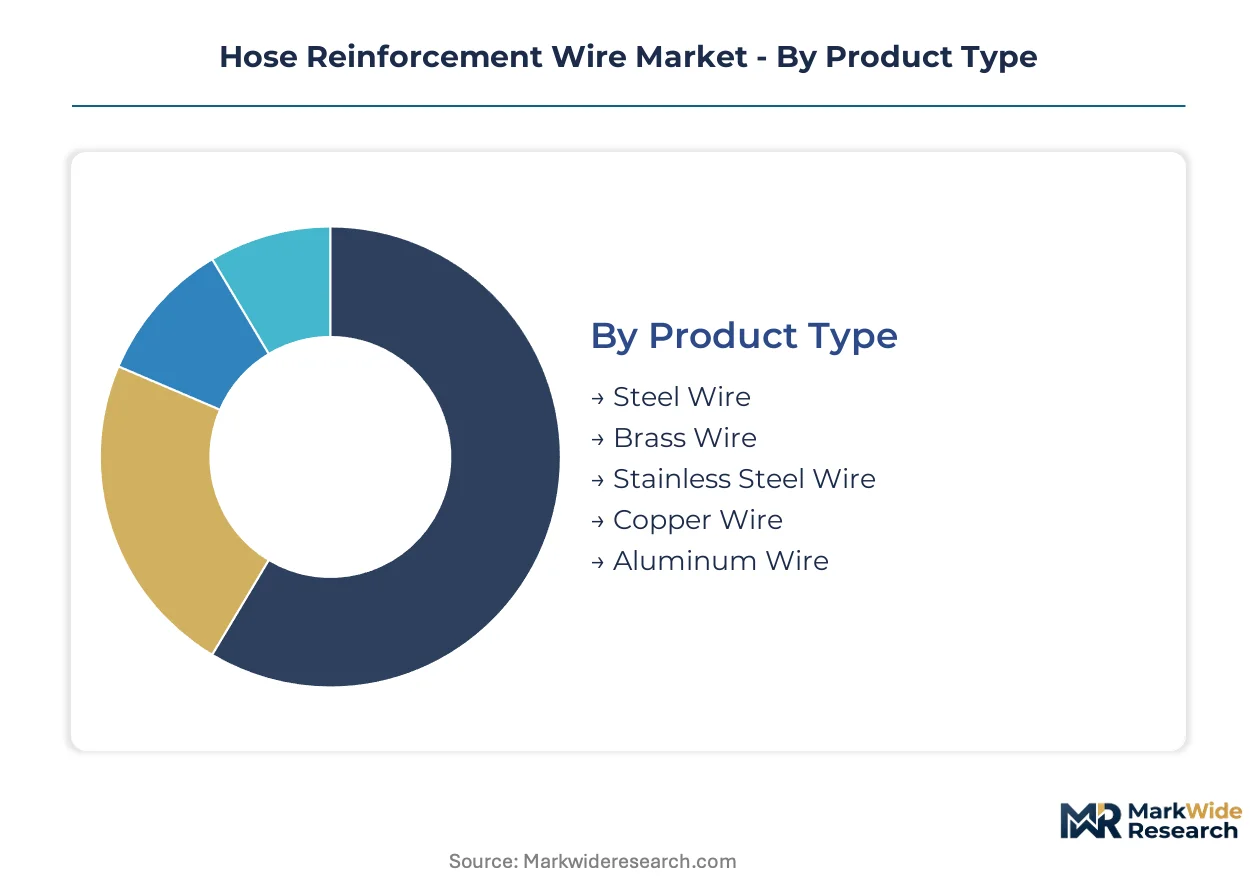
Hose reinforcement wire procurement splits along pressure ratings, corrosion exposure, and regulatory compliance requirements. Specification divergence between mobile hydraulic equipment and static industrial systems creates distinct margin pools across each segment dimension.
Product Type:
REACH and EPA emissions rules differentiate alloy disclosure requirements, with carbon steel facing lighter documentation burdens than specialty metals.
- Steel Wire:Cold-drawn high-carbon grades with brass or zinc plating dominate construction and mining hose bundles due to cost efficiency. Demand concentrates in Chinese OEM supply chains under MIIT industrial policy directives for domestic hydraulic equipment manufacturing.
- Stainless Steel Wire:Austenitic and duplex grades provide chloride corrosion resistance for offshore oilfield and chemical transfer applications where failure costs exceed material premiums. Permian Basin operators specify this grade for subsea hose assemblies despite price multiples over coated carbon steel.
- Brass Wire:Copper-zinc alloys serve specialized chemical transfer applications requiring electrical conductivity and moderate corrosion resistance.
- Copper Wire:Pure copper filaments appear in pneumatic systems and low-pressure fluid handling where flexibility trumps tensile strength.
- Aluminum Wire:Lightweight alloys penetrate aerospace and weight-sensitive mobile equipment segments despite lower fatigue resistance.
Steel wire handles the majority of throughput; stainless steel wire is the fastest mover on share.
Technology:
Cost tiering separates premium spiral configurations from standard braided alternatives, with wrapped and corrugated variants occupying niche positions.
- Braided Wire:Interlaced filament construction dominates mobile hydraulic equipment for excavators and agricultural machinery where flexibility and fatigue resistance matter. United Rentals and similar fleet operators are standardizing on this configuration across equipment categories in the US Southeast.
- Spiral Wire:Multiple layers of helically wound flat wire create rigid high-pressure conduits rated above 6,000 psi for static industrial fluid systems and shale extraction equipment. Bakken formation operators specify spiral-reinforced assemblies for deeper well pressure systems.
- Woven Wire:Plain or twill weave patterns serve medium-pressure pneumatic and low-cycle hydraulic applications.
- Wrapped Wire:Single or double helical wrapping reinforces large-diameter suction and discharge hoses for mining slurry transport.
- Corrugated Wire:Profiled filaments enhance rubber adhesion and kink resistance in specialized agricultural spray equipment.
Braided wire commands the largest installed base; spiral wire is climbing the fastest as oilfield pressure ratings escalate.
Application:
Customer type determines whether procurement prioritizes OEM specification compliance or aftermarket replacement cost minimization.
- Hydraulic Hoses:High-pressure fluid power transmission for construction equipment, mining machinery, and industrial automation represents the core volume application. German and Japanese OEMs are adopting 2,000 MPa tensile strength micro-alloyed wire grades for compact excavator bundles.
- Chemical Transfer:Corrosion-resistant reinforcement for acids, solvents, and petrochemical handling commands premium positioning. EPA emissions certification timelines for hose assembly validation extend product development cycles in this segment.
- Industrial Fluids:General-purpose water, oil, and coolant handling in manufacturing plants and processing facilities.
- Pneumatic Systems:Compressed air delivery for automation and tooling applications with lower pressure requirements.
- Agricultural Equipment:Sprayer, irrigation, and implement hoses subject to UV exposure and seasonal use patterns.
Hydraulic hoses absorb the greatest wire tonnage; chemical transfer is gaining share fastest on corrosion specification tightening.
End User:
Supply concentration among integrated wire producers shapes procurement leverage differently across buyer scale categories.
- Oilfield Services:Shale extraction operators in the Permian Basin and Bakken formation drive demand for spiral-wire-reinforced high-pressure hose bundles rated above 6,000 psi. Capital deployment into deeper well pressure systems directly lifts specification requirements for tensile strength and brass coating adhesion.
- Construction Firms:Equipment rental fleets and contracting operations procure replacement hose assemblies with increasing standardization on braided-wire configurations. Consolidated mill-to-fleet supply contracts are bypassing traditional distribution layers in high-density markets.
- Manufacturers:OEM hydraulic equipment builders specify wire reinforcement during original assembly.
- Mining Operations:Bulk material handling and mineral processing applications favor cost-sensitive 1,770 MPa specifications over premium micro-alloyed grades.
- Transportation Companies:On-highway and off-highway vehicle hydraulic systems for braking, suspension, and power steering.
Construction firms place the largest replacement orders; oilfield services is expanding most quickly on shale intensity recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese wire producers dominate export flows into Southeast Asian hydraulic equipment assembly plants, while European manufacturers supply specialized brass-coated grades to North American oilfield distributors under REACH-certified documentation protocols.
United States
Permian Basin shale operators specify spiral-wire-reinforced hose bundles rated above 6,000 psi for deeper well systems. EPA emissions certification timelines now require third-party validation of wire-to-rubber adhesion under thermal cycling. Houston distributors are consolidating supplier relationships toward producers with ISO 17025-accredited in-house testing laboratories.
Germany
Construction OEMs in Bavaria and Baden-Württemberg adopt 2,000 MPa tensile strength micro-alloyed wire grades for compact excavator hose bundles. ECHA enforcement of REACH alloy composition disclosure requirements favors producers with certified brass plating documentation. Stuttgart-area metallurgy labs anchor heat treatment optimization services for regional wire drawing operations.
China
Domestic hydraulic equipment manufacturing scale under MIIT industrial policy directives concentrates demand for steel reinforcement wire within Jiangsu and Zhejiang OEM supply chains. GB standards shape quality benchmarks for pressure equipment components. Yangtze River Delta wire drawing clusters serve both domestic construction machinery builders and export markets.
India
PLI scheme incentives for construction machinery manufacturing create import-substitution openings for wire producers establishing local drawing and plating capacity. BIS certification requirements govern pressure equipment safety standards. Tamil Nadu and Maharashtra industrial corridors attract capital deployment for hydraulic component localization.
South Korea
Hyosung Advanced Material anchors supply relationships with domestic construction equipment OEMs through dedicated metallurgy labs. MFDS-equivalent industrial safety standards govern hose assembly certification. Busan-Ulsan manufacturing clusters concentrate precision wire coating capacity for chemical transfer applications.
Hose Reinforcement Wire Market Competitive Landscape
Listed leaders compete with private specialists across integrated versus modular production footprints. The vendor base arranges into three tiers: multinational steel wire conglomerates with captive rod supply, regional specialists focused on brass plating and heat treatment, and commodity traders serving aftermarket replacement channels. Strategic moves center on backward integration into steelmaking and geographic expansion into India and Southeast Asia.
Within the integrated multinational tier, Bekaert exemplifies scale-driven positioning through European and Asian production nodes. Hyosung Advanced Material occupies a specialist position anchoring Korean OEM relationships. Gustav Wolf GmbH represents precision-focused positioning in brass wire coatings for corrosion-resistant applications.
| Leading Market Players |
|---|
| Bekaert |
| KIS Wire |
| Shandong Daye |
| Hyosung Advanced Material |
| Henan Hengxing |
| BMZ |
| Tokyo Rope Mfg |
| Sumin Metals |
| Gustav Wolf GmbH |
| Others |
Pricing and Supply Chain Analysis
Stainless steel substitution in Permian Basin subsea assemblies simultaneously redraws supply geography toward Korean and Japanese duplex wire specialists while compressing brass-coated carbon steel margins across Chinese export channels. This input shift forces procurement officers to rebalance inventory exposure between spot-priced austenitic grades and long-term offtake contracts for coated high-carbon alternatives.
Pricing Analysis
Technology-generation pricing gaps separate legacy 1,770 MPa construction grades from emerging 2,000 MPa micro-alloyed specifications and experimental fiber-optic-embedded monitoring wire. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and heat treatment documentation depth. Pricing pressure stems from steel input cost volatility and REACH compliance documentation burdens. Construction fleet operators exhibit highest price sensitivity; offshore oilfield services accept premium multiples for corrosion-resistant specifications.
Supply Chain Analysis
Patenting heat treatment capacity chokepoints in the Yangtze River Delta and Stuttgart industrial corridor concentrate qualified wire supply for high-pressure hose manufacturers. Geographic supply anchors in China, Germany, and South Korea draw from cold-rolled high-carbon rod, brass plating chemistries, and specialized heat treatment furnaces. Single-source vulnerability runs through East Asian wire drawing clusters with captive metallurgy expertise. Distribution runs through OEM direct mill contracts and aftermarket distributor networks serving equipment rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hose reinforcement wire functions as a defensive-moat market where regulatory entrenchment via EPA emissions certification and REACH alloy disclosure creates switching costs that lock in qualified supplier relationships.
For Market Incumbents: Secure backward integration into electric arc furnace-based steelmaking to capture carbon-neutral positioning under EU Green Deal procurement criteria. Anchor heat treatment capacity expansion in Tamil Nadu and Maharashtra industrial corridors to defend against PLI-scheme-enabled Indian localization. Certification investment in ISO 17025-accredited testing laboratories defends against distributor consolidation toward validated suppliers.
For New Entrants and Emerging Players: Lead with carbon-neutral wire production using renewable-sourced electric arc furnace capacity to penetrate European supply chains under tightening CSRD disclosure requirements. Target India's construction machinery localization wave through joint ventures with domestic hydraulic equipment OEMs seeking import substitution. Go-to-market positioning centers on mill-to-fleet direct contracts bypassing layered distribution in high-density US Southeast rental markets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized brass plating and heat treatment assets over commodity wire drawing capacity. Long-term viability hinges on regulatory compliance infrastructure and OEM specification entrenchment across the projection horizon. Acquisition focus targets regional specialists with certified REACH documentation systems and established Korean or German OEM relationships. Watch EPA emissions rule evolution and MIIT industrial policy enforcement as inflection signals for geographic demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steelmaking | Captive rod supply insulates margin volatility from scrap metal price swings. |
| Carbon-Neutral Production Certification | EU Green Deal alignment unlocks premium positioning in European OEM supply chains. |
| ISO 17025 Laboratory Accreditation | Third-party validation capability accelerates EPA emissions certification timelines for distributors. |
| India Localization Partnership | PLI scheme access enables import substitution positioning in Tamil Nadu and Maharashtra corridors. |
| Fiber-Optic Embedded Wire Development | Predictive maintenance integration addresses offshore oilfield operator demand for real-time diagnostics. |
Research Methodology
The analysis maps steel wire, stainless steel wire, brass wire, and aluminum wire sub-sectors, each validated through cold drawing process engineers, hose assembly procurement managers, and OEM specification technologists. Primary interviews with metallurgy lab directors, aftermarket distribution channel heads, and oilfield services equipment planners combined with secondary validation from SEC filings, customs trade data, ECHA REACH registration databases, and MIIT industrial policy directives. Bottom-up volume triangulation against top-down value estimates anchored forecast reliability.
Consistency checks against external benchmarks validated model outputs across the projection horizon. Segmentation dimensions modeled include alloy type, wire configuration technology, pressure rating tier, and end-use vertical. CAGRs derived from elasticity-adjusted demand curves incorporating shale extraction intensity, infrastructure capital deployment, and regulatory compliance cost pass-through. Industry-specific inputs encompass patenting heat treatment capacity utilization rates and brass plating chemistry cost indices.
The analysis sits within stated boundaries; outcomes outside sustained oilfield capital deployment, stable steel input costs, or consistent regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding MIIT policy continuity and EPA emissions rule evolution. Practitioners should keep alternative scenarios live as REACH disclosure requirements and Indian PLI scheme implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Industrial Heaters Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Tooling Board Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Global Machined Seals Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Stainless Steel Cable Ties Market