
 Duplex Stainless Steel Pipe Market | 2026-2036
Duplex Stainless Steel Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Duplex Stainless Steel Pipe Market Analysis
Specialty alloy distribution is narrowing as mill-direct relationships displace traditional stocking distributors in high-specification grades. Outokumpu leverages its integrated melt shop and finishing capabilities in Finland to sustain premium positioning for super-duplex seamless products. Sandvik anchors its competitive stance through precision cold-pilgering technology that dominates nuclear and desalination specifications.
Duplex stainless steel pipe combines austenitic and ferritic microstructures in roughly equal proportions, typically containing chromium, nickel, molybdenum, and nitrogen to achieve yield strengths roughly double those of standard austenitic grades while maintaining superior chloride stress corrosion cracking resistance. Oil and gas applications command the deepest specification requirements and longest qualification cycles, creating entrenched supplier relationships and elevated margin pools. Seamless products retain structural preference in high-pressure hydrocarbon service, while welded pipe competes aggressively in chemical processing and marine exhaust systems where pressure ratings permit.
API 5LC and NORSOK M-DS-001 govern material qualification for offshore and subsea installations, with testing protocols that effectively filter out non-specialist producers. ASTM A790 and ASTM A928 set baseline dimensional and mechanical standards for American project specifications, while EN 10216-5 governs European pressure equipment directives. Stakeholders must monitor evolving hydrogen infrastructure standards, as blending ratios and purity specifications will determine whether existing duplex grades qualify or require alloy modifications.
Market Dynamics
The American Petroleum Institute's updated sour service standards are forcing a qualification bottleneck that favors integrated melt-to-finish producers while marginalizing trading houses in high-specification grades.
Growth Catalysts
- API 5LC sour service mandates:Tightened testing protocols for hydrogen sulfide resistance are filtering out non-specialist producers and consolidating procurement around qualified mills in the US Gulf Coast corridor.
- Subsea tieback expansion:Offshore operators in the Gulf of Mexico are extending field life through subsea infrastructure that demands super-duplex seamless products for chloride-rich environments.
- Hydrogen blending infrastructure:Pipeline operators are pre-qualifying duplex grades for hydrogen service ahead of anticipated purity specifications from FERC and state utility commissions.
Market Restraints
- Nickel-molybdenum cost volatility:Alloy surcharge fluctuations compress margin predictability for distributors holding inventory on 60-90 day cycles.
- Scandinavian mill concentration:Seamless super-duplex supply concentrates among integrated producers in Finland and Sweden, creating geographic single-source risk for nuclear and desalination projects.
- Ferritic-austenitic weldability limits:Heat-affected zone sensitization restricts duplex application in field-fabricated piping systems requiring extensive on-site welding.
Strategic Opportunities
- US hydrogen backbone buildout:Regional pipeline consortia are evaluating existing duplex stock for hydrogen compatibility, potentially unlocking retrofitted infrastructure demand ahead of new alloy development.
- Cold-pilgered precision tubing:Instrumentation and umbilical manufacturers are adopting ultra-tight tolerance seamless products for subsea control systems previously served by mechanically worked austenitic grades.
- Mill-direct procurement platforms:Digital channels are disintermediating traditional alloy distributors for standard duplex grades, capturing margin previously allocated to stocking inventory.
Industry Challenges
- Welding procedure qualification scarcity:Certified welders for duplex root passes command premium rates and extended lead times, constraining fabrication capacity for complex spool projects.
- Multi-standard certification overlap:Projects requiring simultaneous API 5LC, NORSOK M-DS-001, and EN 10216-5 compliance extend qualification timelines and engineering review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duplex Stainless Steel Pipe Market |
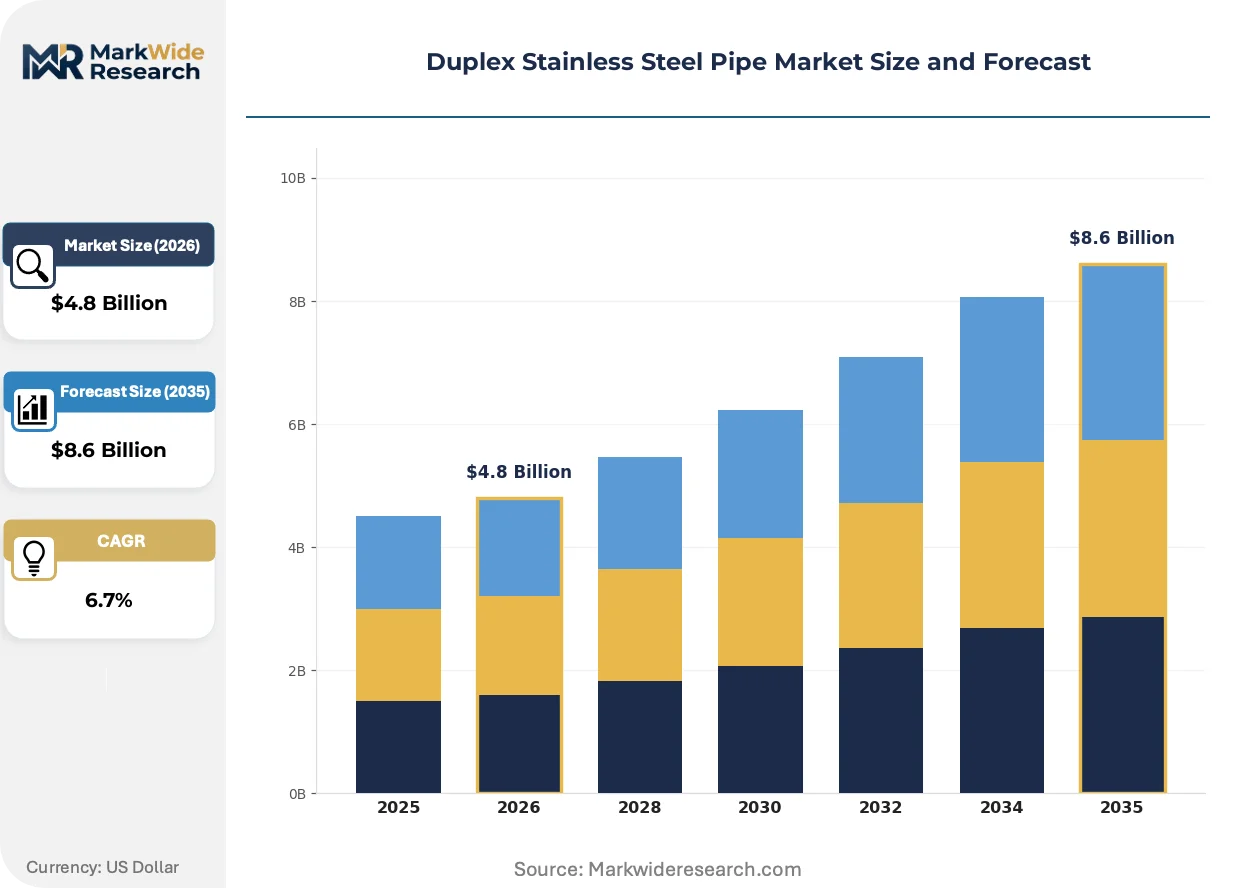
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Electropolished, Duplex Stainless Steel Application: Oil & Gas, Chemical Processing, Marine, Power Generation End User: Construction, Automotive, Aerospace, Pharmaceutical Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size |
| Companies Covered | Outokumpu, Acerinox SA, POSCO, Nippon Steel Corporation, ThyssenKrupp AG, Sandvik, JFE Steel Corporation, Allegheny Technologies Incorporated, Tata Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duplex Stainless Steel Pipe Market Emerging Trajectories
Additive manufacturing of near-net-shape duplex fittings is compressing lead times for complex geometries while cold-pilgering advances are extending seamless length capabilities. These developments are reshaping competitive positioning between welded and seamless product categories.
Hyper-duplex grades with elevated chromium and nitrogen content are hybridizing corrosion resistance thresholds previously requiring nickel-base alloys. Desalination plant operators in the Middle East are specifying these grades for brine heater tubing. The technology is hybridizing the boundary between commodity stainless and premium nickel alloys, compressing the addressable market for Incoloy and Hastelloy products.
REACH authorization requirements for hexavalent chromium surface treatments are forcing conversion to citric acid passivation protocols. European pressure equipment fabricators face reformulation costs for pre-commissioning surface finishing. The directive most affects welded pipe producers serving North Sea projects, where NORSOK compliance intersects with EU chemical regulations.
Long-term service agreements are displacing spot purchasing for offshore projects, bundling inspection, replacement, and metallurgical support into decade-long contracts. Integrated service companies are capturing procurement decisions previously managed by EPC contractors. This consolidation is most visible in Norwegian continental shelf developments, where Equinor and Aker BP have centralized alloy sourcing through framework agreements.
Duplex Stainless Steel Pipe Market Segmentation
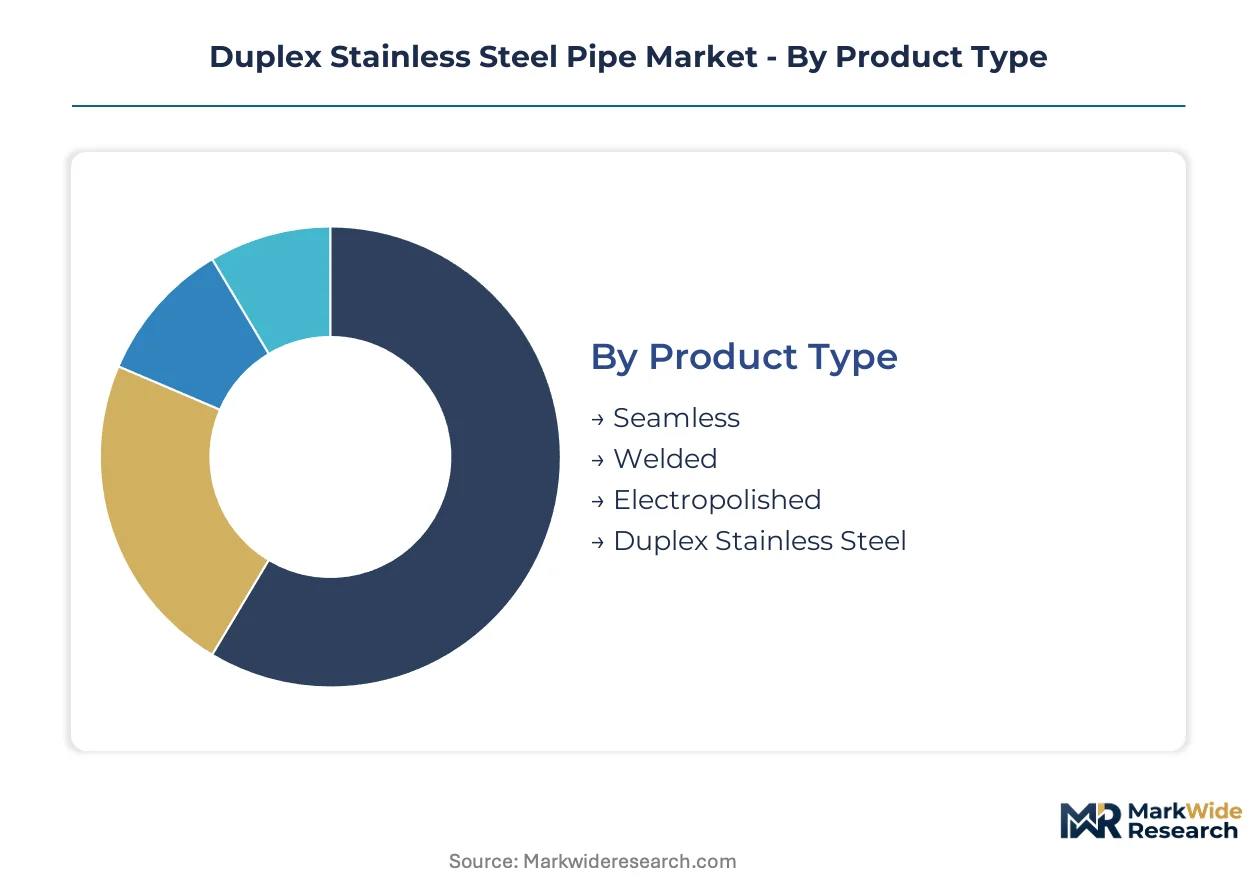
Segmentation in the duplex stainless steel pipe market reflects divergent qualification requirements and margin structures. Product form determines pressure rating eligibility. Application context drives alloy specification complexity.
Product Type:
Cost tier separates commodity welded products from premium seamless grades with metallurgical traceability requirements.
- Seamless:Manufactured through extrusion or piercing without longitudinal weld seams, delivering uniform grain structure for high-pressure hydrocarbon service. Gulf of Mexico subsea tiebacks specify seamless super-duplex for chloride stress corrosion resistance at depth. API 5LC qualification cycles extend 18-24 months, entrenching incumbent mill relationships.
- Welded:Produced from coiled strip or plate through electric resistance welding or submerged arc processes, offering dimensional flexibility at lower unit cost. Chemical processing plants in Texas and Louisiana specify welded pipe for atmospheric pressure vessels where post-weld heat treatment satisfies NACE requirements. Cold-pilgered precision variants are penetrating instrumentation markets.
- Electropolished:Surface-finished through electrochemical dissolution to achieve sub-micron roughness for hygienic applications.
- Duplex Stainless Steel:Base material category encompassing 2205, 2507, and hyper-duplex grades with varying chromium-nickel-molybdenum ratios.
Seamless commands the established base. The steepest expansion runs through electropolished variants for pharmaceutical and desalination specifications.
Application:
Application context determines corrosion severity and drives alloy selection toward standard duplex or super-duplex grades.
- Oil & Gas:Sour service pipelines, subsea manifolds, and topside processing equipment face hydrogen sulfide and chloride exposure simultaneously. US Gulf Coast operators pre-qualify super-duplex seamless products for high-pressure gas injection wells. FERC hydrogen blending rulings may expand addressable infrastructure.
- Chemical Processing:Acid transfer lines, reactor vessels, and heat exchangers in sulfuric and phosphoric acid service. Louisiana petrochemical corridors specify welded duplex for sulfuric acid alkylation units where temperature cycling demands thermal fatigue resistance. Citric acid passivation protocols are displacing hexavalent chromium surface treatments under REACH.
- Marine:Seawater cooling systems, ballast piping, and exhaust scrubbers for IMO compliance.
- Power Generation:Condenser tubing and feedwater heaters in coastal nuclear and combined-cycle plants.
Oil & Gas anchors procurement volume. Chemical Processing is climbing the fastest as US Gulf Coast ethylene expansions commission corrosion-resistant utility piping.
End User:
Customer type segments by project scale, specification authority, and service agreement structure.
- Construction:Infrastructure and commercial building projects specifying duplex for coastal reinforcement and architectural exposed structures. Miami-Dade County building codes mandate corrosion-resistant materials for high-rise seawater cooling systems. General contractors face welder certification scarcity for field-fabricated duplex installations.
- Automotive:Exhaust system manufacturers evaluating duplex for thermal fatigue resistance in heavy-duty catalytic converter housings.
- Aerospace:Hydraulic tubing and fuel system components requiring ultra-tight dimensional tolerances.
- Pharmaceutical:Bioprocessing equipment and clean steam distribution demanding electropolished surfaces with documented material pedigree.
Construction holds the incumbent demand position. Pharmaceutical is gaining share fastest as single-use bioprocessing expansion drives stainless alloy consumption.
Size:
Volume throughput and fabrication complexity vary nonlinearly with diameter specification.
- Small Diameter:Instrumentation tubing, control lines, and umbilical cores below 2 inches nominal bore. Cold-pilgering technology enables 0.5mm wall thickness control for subsea hydraulic systems. Norwegian continental shelf developments specify small-diameter super-duplex for electro-hydraulic multiplex control lines.
- Medium Diameter:Process piping and utility headers between 2 and 12 inches, representing the highest shipment volume category. Texas and Louisiana chemical plants standardize on medium-diameter welded duplex for cooling water and firewater systems. Mill-direct procurement platforms are disintermediating distributors in this range.
- Large Diameter:Transmission pipelines and caisson structures above 12 inches requiring specialized plate-to-pipe rolling capabilities.
- Custom Size:Non-standard dimensions for retrofit projects and proprietary equipment skids.
Medium Diameter represents the volume core. Small Diameter shows the steepest expansion trajectory as subsea electrification multiplies control line density per well.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Mexico pipeline network anchors North American demand for corrosion-resistant subsea infrastructure, while Scandinavian melt shops and Finnish finishing mills supply premium seamless grades to nuclear and desalination projects worldwide.
United States
Gulf Coast petrochemical expansions and subsea tieback projects drive procurement of super-duplex seamless products. FERC hydrogen blending rulings are pre-qualifying existing duplex stock for pipeline retrofits. Houston-Texas City corridor operators centralize sourcing through mill-direct platforms, bypassing traditional distributors for standard grades.
Norway
Equinor and Aker BP framework agreements consolidate alloy procurement for North Sea developments. NORSOK M-DS-001 compliance requirements filter procurement toward qualified integrated producers. Stavanger-Bergen subsea cluster demands small-diameter super-duplex for electro-hydraulic control lines on electrified well installations.
Finland
Integrated melt shop and finishing capabilities sustain premium positioning for super-duplex seamless products. REACH authorization requirements for hexavalent chromium surface treatments force citric acid passivation protocol adoption. Tornio production complex ships nuclear-grade material to Middle East desalination contractors.
Saudi Arabia
Red Sea and Arabian Gulf desalination capacity expansions specify hyper-duplex grades for brine heater tubing. The country's national industrial development program prioritizes localization of specialty alloy fabrication. Jubail industrial city hosts framework negotiations between plant operators and Scandinavian mill representatives.
China
Dual carbon goals accelerate hydrogen pipeline infrastructure planning with duplex grade compatibility assessments. GB standards evolution tracks API sour service protocols for offshore equipment exports. Yangtze River Delta fabricators cold-pilger precision tubing for subsea umbilical manufacturers in Singapore and Norway.
Duplex Stainless Steel Pipe Market Vendor Landscape
On the supply side, the industry is consolidating around integrated melt-to-finish producers capable of multi-standard certification. Trading houses face marginalization in high-specification grades as API qualification bottlenecks favor captive metallurgical capabilities. Two strategic archetypes dominate: Scandinavian seamless specialists with nuclear pedigree and Asian integrated mills with scale-driven welded pipe platforms. Competitive moves center on mill-direct digital procurement channels and long-term service agreement bundling that captures inspection and replacement revenue.
Among Scandinavian seamless specialists, Outokumpu and Sandvik exemplify the premium-tier positioning built on cold-pilgering precision and nuclear-grade traceability. POSCO represents the Asian integrated mill archetype with capacity to supply both standard welded products and qualified seamless grades for regional energy projects. These three entities anchor the competitive structure, with Outokumpu and Sandvik occupying positions in super-duplex specifications while POSCO captures volume-driven chemical processing demand.
| Leading Market Players |
|---|
| Outokumpu |
| Acerinox SA |
| POSCO |
| Nippon Steel Corporation |
| ThyssenKrupp AG |
| Sandvik |
| JFE Steel Corporation |
| Allegheny Technologies Incorporated |
| Tata Steel |
| Others |
Supply Flow & Price Mechanics
Houston-Rotterdam freight corridors transmit alloy surcharge volatility directly into landed cost differentials for super-duplex seamless products. Scandinavian mill concentration amplifies pricing power at the premium tier while Gulf Coast petrochemical buyers exploit volume scale to compress standard-grade welded pipe margins.
Pricing Analysis
Volume-discount tiering separates API 5LC-qualified seamless super-duplex from commodity welded grades. Pricing stratifies across premium certification tiers, standard mill-direct offtake, and economy-grade distributor stock. Cost compression in the standard welded tier is intensifying as digital procurement platforms disintermediate traditional stocking distributors. EPC contractors show highest price sensitivity on atmospheric-pressure chemical processing lines, while offshore operators accept premium positioning for subsea qualification cycles.
Supply Chain Analysis
Tariff exposure between Finland and Saudi Arabia dominates supply chain risk for nuclear-grade desalination contracts. Production gravity centers on Finland, Sweden, and South Korea for seamless super-duplex, with China and India supplying welded pipe for chemical processing. Raw material dependencies rest on nickel from Indonesia, molybdenum from Chile, and ferrochrome from South Africa. Single-source vulnerability concentrates in cold-pilgered precision tubing for subsea umbilicals. Distribution runs through mill-direct platforms for standard grades and long-term framework agreements for offshore projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story where API 5LC and NORSOK M-DS-001 certification entrenchment creates switching costs that lock out non-specialist producers.
For Market Incumbents: Build certification moats by accelerating multi-standard qualification overlap across API 5LC, NORSOK M-DS-001, and anticipated hydrogen infrastructure standards. Expand cold-pilgering capacity in Finland to capture subsea electrification demand for small-diameter super-duplex control lines. Defend against Asian integrated mills by bundling metallurgical support into decade-long service agreements that capture inspection and replacement revenue. For New Entrants and Emerging Players: US hydrogen backbone retrofits offer the most penetrable white-space as regional pipeline consortia evaluate existing duplex stock for hydrogen compatibility. Target citric acid passivation service provision for European pressure equipment fabricators facing REACH hexavalent chromium restrictions. Enter through digital procurement platforms for medium-diameter welded pipe in the Texas-Louisiana chemical corridor. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive alloy distribution units lacking API qualification depth. Long-term viability hinges on hydrogen infrastructure standard-setting and subsea field life extension trends. Watch FERC hydrogen blending rulings as the inflection signal for retrofitted infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Investment | API 5LC and NORSOK M-DS-001 overlap filters procurement toward integrated melt-to-finish producers. |
| Cold-Pilgering Capacity Expansion | Precision seamless length capabilities capture subsea umbilical instrumentation demand from Sandvik-dominated specifications. |
| Mill-Direct Digital Platform Launch | Houston-Texas City corridor operators bypass distributors for standard duplex grades, capturing margin compression. |
| Hydrogen Service Pre-Qualification | FERC and state utility commission rulings will determine existing duplex grade eligibility for pipeline retrofits. |
| Long-Term Service Agreement Bundling | Equinor and Aker BP framework agreements in Norway consolidate alloy sourcing through integrated inspection and replacement contracts. |
Methodological Framework
A spread of perspectives from melt shop operations directors, EPC contractor procurement leads, subsea project metallurgists, and chemical plant maintenance engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from API specification documents, NORSOK standard revisions, SEC filings of listed specialty alloy producers, and customs trade data for nickel-molybdenum alloy imports. Bottom-up shipment analysis triangulated against top-down capacity utilization estimates across Finnish, Swedish, and South Korean production complexes.
Demand-supply-balance modeling anchored volume projections across the analysis window. Segmentation dimensions included product form (seamless versus welded), alloy grade tier (standard duplex, super-duplex, hyper-duplex), application severity (sour service versus atmospheric pressure), and end-user procurement structure (spot purchasing versus framework agreements). CAGRs derived from weighted average of capacity expansion announcements, subsea project sanctioning timelines, and hydrogen infrastructure regulatory pacing. Industry-specific inputs incorporated API 5LC qualification cycle durations and cold-pilgering yield rate improvements.
Practitioners should monitor FERC hydrogen blending rulings, REACH authorization timelines for surface treatments, and nickel-molybdenum alloy surcharge volatility for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Steel Pipes and Tubes Market