
 Lignocaine/ Lidocaine Market | 2026-2036
Lignocaine/ Lidocaine Market Size, Share, and Industry Trends Forecast 2026-2036
Lignocaine/ Lidocaine Market Foresight
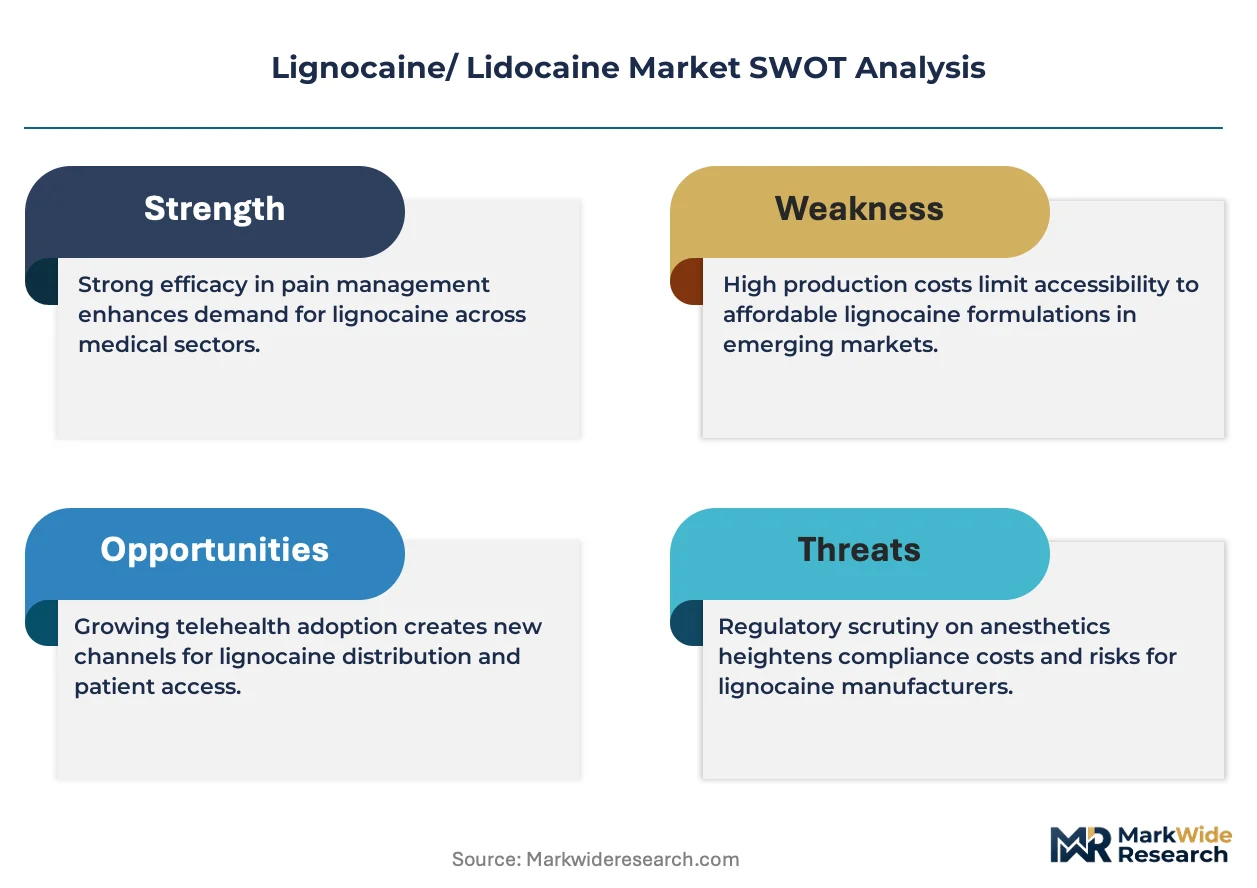
Hospital procurement consolidation is decoupling purchasing decisions from individual clinician preference, forcing suppliers to negotiate with centralized pharmacy committees rather than department heads. Pfizer Inc. leverages its injectable manufacturing scale to secure multi-year hospital contracts. Teva Pharmaceutical Industries competes through vertical integration into active pharmaceutical ingredient production.
Lignocaine, also known as lidocaine, is a synthetic amino amide local anesthetic with a molecular formula of C14H22N2O, functioning by blocking sodium ion channels in neuronal membranes to inhibit nerve signal transmission. Its primary commercial purpose spans surgical anesthesia, acute pain management, and cardiac arrhythmia treatment across inpatient and outpatient settings. Injectable formulations dominate hospital procurement due to higher per-unit pricing and mandatory surgical use, while topical segments gain share in dermatology and minor wound care as outpatient protocols expand. Ambulatory surgical centers represent the fastest-growing end user channel, driven by Medicare reimbursement shifts favoring same-day procedures.
The US FDA maintains stringent purity and sterility requirements for parenteral lidocaine products, directly influencing formulation costs and batch rejection rates. EMA's updated pharmacovigilance guidelines for local anesthetics mandate enhanced cardiac toxicity monitoring across European markets. Stakeholders must monitor evolving reimbursement policies for nerve block procedures and assess whether topical portfolio expansion offsets injectable pricing pressure from group purchasing organizations.
Market Dynamics
Hospital procurement consolidation is dismantling traditional clinician-driven purchasing, replacing it with centralized pharmacy committee authority that demands multi-year volume commitments and standardized formularies across health systems.
Growth Catalysts
- Outpatient Procedure Expansion:Medicare reimbursement shifts favoring same-day surgical interventions are accelerating ambulatory surgical center construction across India and Brazil.
- EMA Pharmacovigilance Guidelines:Enhanced cardiac toxicity monitoring mandates for local anesthetics are driving demand for advanced formulation safety data packages in European markets.
- Topical Formulation Innovation:Transdermal delivery system advances are expanding lidocaine applications into dermatology and chronic pain management protocols.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters heavily in Chinese and Indian chemical manufacturing zones, creating single-source vulnerability.
- FDA Sterility Enforcement:Stringent parenteral purity requirements elevate batch rejection rates and compliance costs for injectable manufacturers.
- Generic Substitution Pressure:Commoditized injectable formulations face price erosion as group purchasing organizations consolidate supplier panels.
Strategic Opportunities
- Brazilian ASC Penetration:Underdeveloped same-day surgery infrastructure in secondary Brazilian cities offers first-mover positioning for formulation suppliers.
- Combination Product Development:Convergence of local anesthetics with sustained-release polymer matrices enables post-operative pain management differentiation.
- Indian PLI Scheme Alignment:Production-linked incentive frameworks for pharmaceutical manufacturing support capital investment in domestic sterile injectable capacity.
Industry Challenges
- Sterile Manufacturing Expertise Scarcity:Qualified personnel for aseptic processing and isolator technology command premium compensation in competitive labor markets.
- Legacy System Integration:Hospital customers require seamless connectivity with existing electronic health record platforms for inventory management and adverse event tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignocaine/ Lidocaine Market |
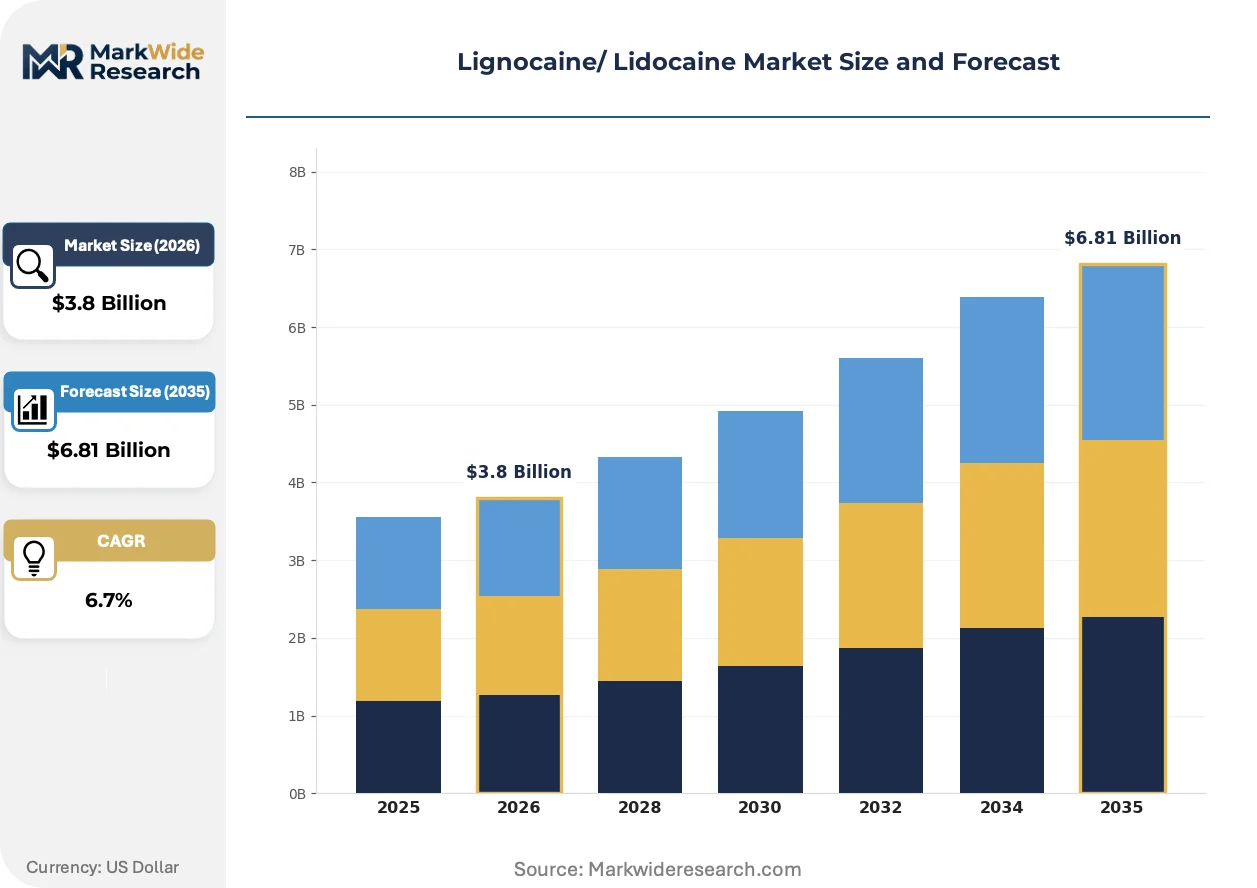
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Topical, Transdermal, Oral Application: Local Anesthesia, Pain Management, Surgical Procedures, Dental Procedures End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Settings Delivery Mode: Intravenous, Infiltration, Epidural, Nerve Block |
| Companies Covered | Pfizer Inc., Merck KGaA, Teva Pharmaceutical Industries, AstraZeneca plc, Amphastar Pharmaceuticals Inc., Hikma Pharmaceuticals, Viatris Inc., Aspen Group Ltd, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignocaine/ Lidocaine Market Shifts & Advancements
Formulation science and delivery mechanism advances are redefining competitive advantage in local anesthetics, with sustained-release technologies and topical applications displacing conventional injectable dominance in select clinical settings.
Polymeric microsphere encapsulation technology is integrating lidocaine into biodegradable matrices that extend analgesic duration from hours to days. Orthopedic surgery units in US academic medical centers are piloting these depot formulations for joint replacement protocols. The technology is integrating post-operative pain management into outpatient discharge pathways, compressing length-of-stay metrics and reducing opioid dependency rates.
EMA's updated pharmacovigilance guidelines for local anesthetics mandate systematic cardiac adverse event collection across all European marketing authorization holders. Pharmaceutical manufacturers must now maintain enhanced signal detection databases and submit periodic safety update reports with expanded cardiovascular endpoints. Injectable formulation suppliers serving EU markets are restructuring quality assurance departments to accommodate real-world evidence collection requirements.
Group purchasing organization consolidation has concentrated hospital buying power into fewer decision-making entities with standardized formularies. Independent ambulatory surgical centers in India and Brazil are responding by forming regional purchasing cooperatives to match negotiating leverage. This behavioral shift is most visible in Maharashtra state and São Paulo province, where multi-facility alliances now tender for lidocaine supply contracts previously negotiated site-by-site.
Lignocaine/ Lidocaine Market Segmentation
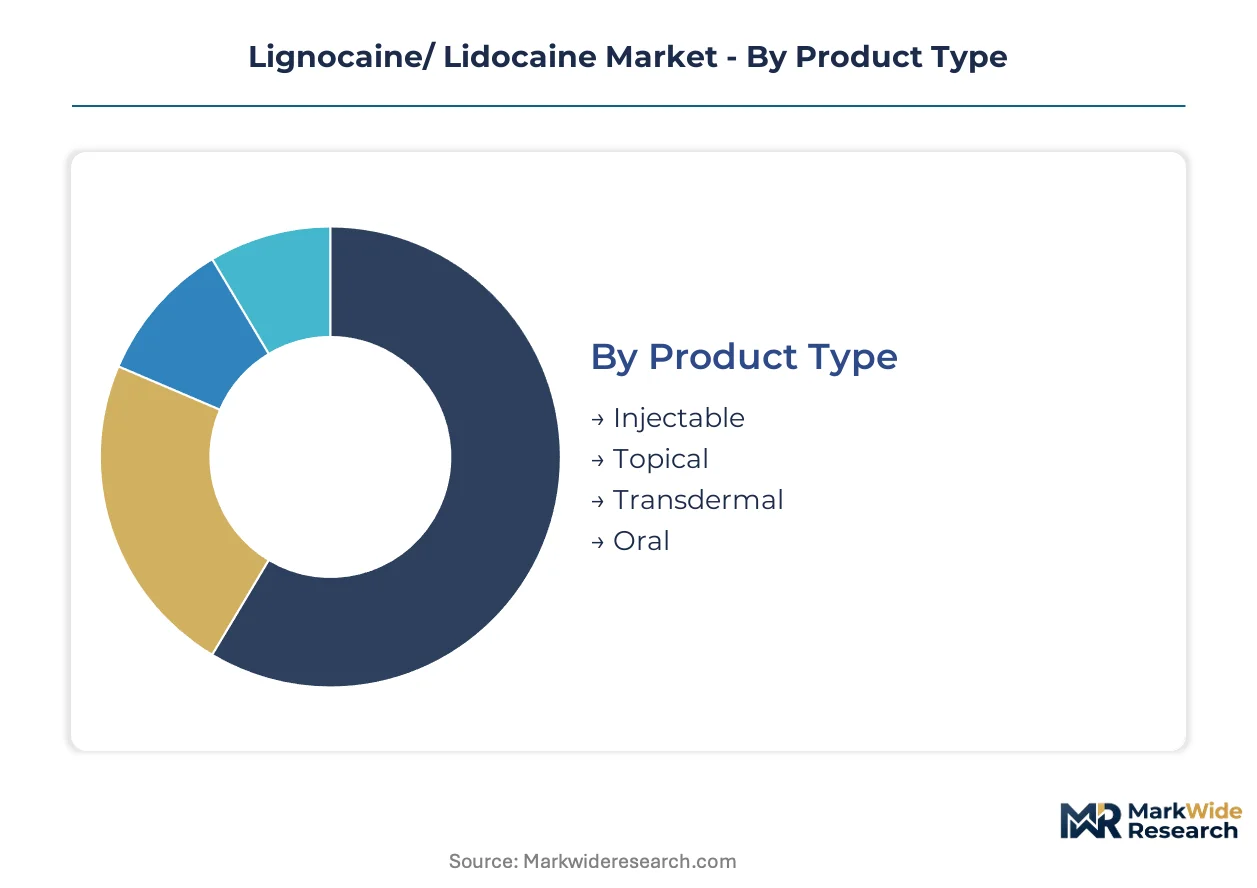
Segmentation in lidocaine markets reveals divergent margin profiles and procurement pathways. Injectable formulations command hospital formulary positions through surgical necessity, while topical and transdermal variants compete on outpatient convenience and chronic pain protocols.
Product Type:
Upgrade cycles in lidocaine delivery systems are shortening as sustained-release technologies mature and hospital formularies refresh their anesthesia portfolios every three to four years.
- Injectable:Sterile parenteral solutions for infiltration, nerve block, and epidural administration dominate hospital procurement volumes. Demand concentrates in US academic medical centers and Indian tertiary hospitals where surgical throughput justifies multi-year supply contracts with mandatory sterility documentation.
- Topical:Creams, gels, and ointments for dermatologic and minor wound applications are gaining formulary inclusion as Medicare reimbursement shifts favor same-day discharge protocols. Brazilian outpatient clinics and US ambulatory surgical centers are expanding topical anesthesia for superficial procedures, reducing systemic exposure risks.
- Transdermal:Patch-based delivery systems enable chronic pain management outside institutional settings. German pain clinics and Japanese long-term care facilities are piloting lidocaine patches for post-herpetic neuralgia protocols.
- Oral:Viscous solutions for mucosal anesthesia serve dental and endoscopic applications with limited volume scale.
Volume placements concentrate in Injectable; the faster expansion belongs to Topical.
Application:
Cost tier differentiation separates commodity anesthesia from premium pain management positioning.
- Local Anesthesia:Standard infiltration and surface anesthesia for minor procedures represents the baseline commercial segment. Indian dental clinics and Brazilian primary care centers drive unit volume through high-frequency, low-margin utilization.
- Pain Management:Chronic neuropathic pain protocols and post-operative analgesia command premium pricing through sustained-release formulations. US Veterans Health Administration facilities and UK National Health Service pain services are expanding lidocaine infusion programs for complex regional pain syndrome.
- Surgical Procedures:Perioperative anesthesia for orthopedic, cardiovascular, and general surgery maintains the largest revenue footprint. German hospital networks and French public hospital groups standardize lidocaine within multimodal anesthesia protocols.
- Dental Procedures:Local infiltration for extractions and endodontic work operates through distinct distribution channels with practitioner-level purchasing authority.
Revenue weight sits with Surgical Procedures; Pain Management is climbing the fastest as chronic disease protocols expand.
End User:
Customer type determines contract structure, with institutional procurement contrasting against individual practitioner purchasing.
- Hospitals:Centralized pharmacy committees in US health systems and Indian corporate hospital chains negotiate multi-year agreements with formulary exclusivity provisions. Group purchasing organization consolidation has reduced supplier counts per network.
- Clinics:Physician-owned outpatient facilities in Germany and France maintain independent purchasing with preference for single-dose packaging and minimal waste.
- Ambulatory Surgical Centers:Same-day surgery facilities in São Paulo and Maharashtra state are forming regional purchasing cooperatives to match hospital negotiating leverage. Medicare reimbursement shifts in the US and parallel policy moves in Brazil are accelerating construction of these facilities.
- Home Care Settings:Transdermal patch utilization for chronic pain enables patient-managed therapy outside institutional oversight, requiring distinct patient education and adverse event monitoring infrastructure.
Contract value aggregates in Hospitals; Ambulatory Surgical Centers are gaining share fastest as procedure migration accelerates.
Delivery Mode:
Supply concentration in sterile manufacturing expertise shapes competitive access to advanced delivery modalities.
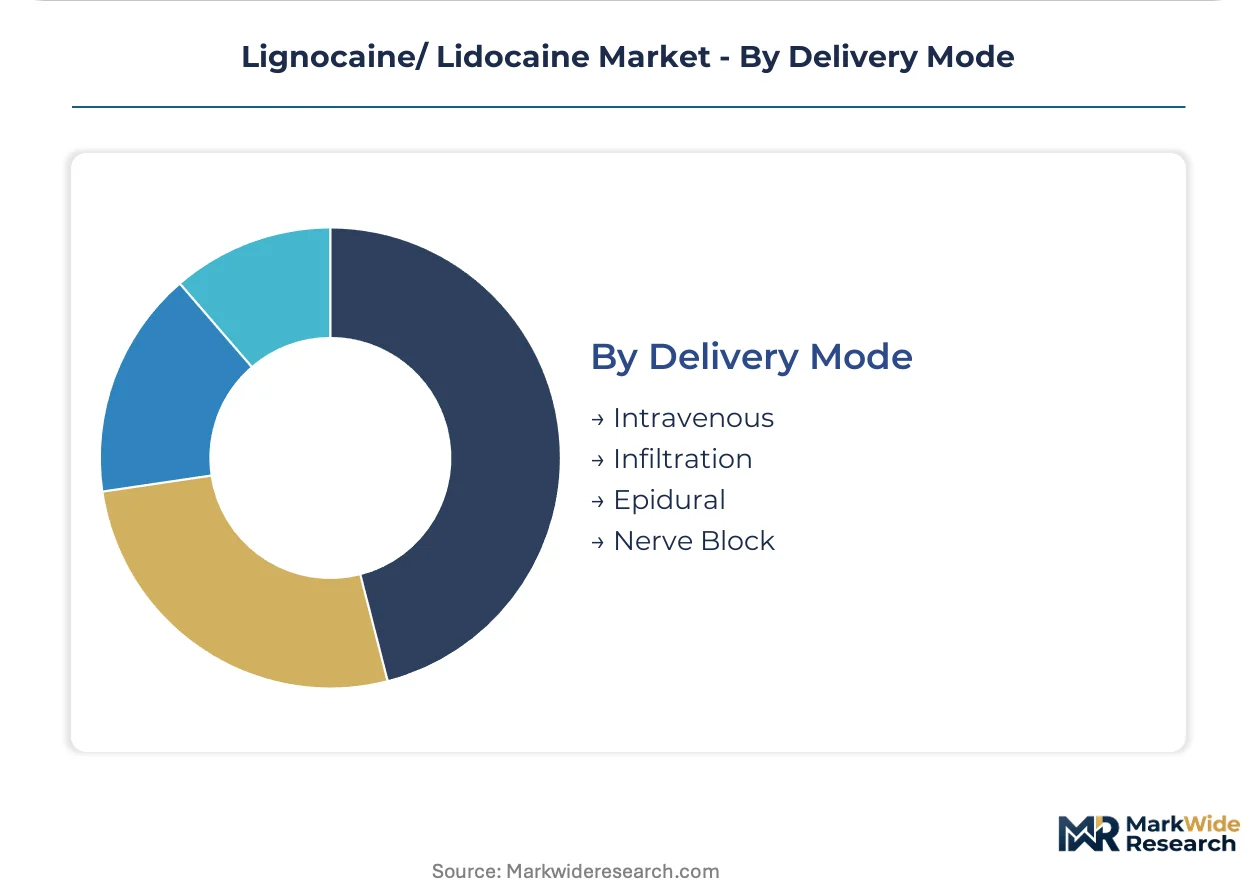
- Intravenous:Systemic administration for cardiac arrhythmia suppression and surgical anesthesia requires precise dosing control and continuous monitoring capability. US emergency departments and Indian cardiac catheterization laboratories maintain standing orders for lidocaine IV protocols.
- Infiltration:Direct tissue injection for wound repair and minor surgery represents the most accessible technique with broad practitioner authorization.
- Epidural:Neuraxial administration for obstetric and major orthopedic anesthesia demands specialized training and sterile compounding infrastructure. UK maternity units and German orthopedic centers maintain dedicated anesthesia teams for these procedures.
- Nerve Block:Ultrasound-guided peripheral nerve blockade is expanding in US ambulatory surgical centers and French same-day surgery facilities as opioid-sparing protocols gain regulatory encouragement.
Procedure frequency peaks with Infiltration; Nerve Block shows the steepest expansion trajectory as ultrasound guidance democratizes regional anesthesia technique.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates purchasing power in the United States, Germany, India, Brazil, and Japan. These five markets generate the majority of lidocaine demand through divergent regulatory pathways and end-user structures.
United States
Medicare reimbursement shifts favoring same-day surgical interventions accelerate ambulatory surgical center construction across Florida and Texas. The FDA maintains stringent purity and sterility requirements for parenteral lidocaine products, elevating batch rejection rates for injectable manufacturers. Academic medical centers in Boston and the Research Triangle pilot sustained-release depot formulations for orthopedic protocols.
Germany
Hospital networks standardize lidocaine within multimodal anesthesia protocols for cardiovascular and general surgery procedures. EMA pharmacovigilance guidelines mandate enhanced cardiac toxicity monitoring, requiring expanded safety databases from European marketing authorization holders. The Rhine-Ruhr metropolitan region concentrates sterile manufacturing infrastructure serving Central European distribution.
India
Corporate hospital chains negotiate multi-year supply agreements with formulary exclusivity provisions for injectable formulations. The CDSCO aligns with production-linked incentive frameworks supporting domestic sterile injectable capacity expansion. Maharashtra state and Delhi-NCR host tertiary hospitals where surgical throughput justifies volume procurement contracts.
Brazil
Same-day surgery facilities in São Paulo and secondary cities form regional purchasing cooperatives to match hospital negotiating leverage. ANVISA regulates local anesthetic safety standards for parenteral and topical products entering the national market. Outpatient procedure volumes rise as private insurance coverage expands for ambulatory interventions.
Japan
Long-term care facilities pilot transdermal lidocaine patches for post-herpetic neuralgia protocols outside institutional settings. The PMDA oversees pharmaceutical manufacturing standards and adverse event reporting requirements for local anesthetics. The Kanto region around Tokyo maintains concentrated demand from aging demographics requiring chronic pain management.
Lignocaine/ Lidocaine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sustained-release formulation differentiation and regional ASC penetration. The market structures around three tiers: multinational injectable manufacturers with hospital GPO relationships, mid-scale API-integrated generic suppliers, and niche topical specialists. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and multi-year contract bidding for health system formularies.
Within the multinational tier, Pfizer Inc. and Teva Pharmaceutical Industries exemplify scale-driven positioning through injectable manufacturing networks. Amphastar Pharmaceuticals Inc. occupies a specialist position in parenteral formulation supply. These three anchors reflect the competitive tension between consolidated hospital procurement power and supplier efforts to secure volume commitments through manufacturing scale and regulatory compliance depth.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck KGaA |
| Teva Pharmaceutical Industries |
| AstraZeneca plc |
| Amphastar Pharmaceuticals Inc. |
| Hikma Pharmaceuticals |
| Viatris Inc. |
| Aspen Group Ltd |
| Fresenius Kabi |
| Others |
Supply & Pricing Matrix
Sterile certification tiers bifurcate the lidocaine market into FDA-validated parenteral suppliers commanding formulary premiums and commodity topical manufacturers competing on unit economics, with each tier sourcing through divergent supply chain configurations shaped by aseptic processing requirements versus standard chemical synthesis.
Pricing Analysis
Volume placements concentrate in injectable formulations with thin margins, while sustained-release depot products capture premium positioning. Price differentiation rests on FDA sterility validation and GPO contract scale, with academic medical centers least sensitive to unit cost and Indian corporate hospital chains most responsive to volume rebates. Cost compression in standard parenteral grades intensifies as Chinese API producers expand sterile finishing capacity.
Supply Chain Analysis
FDA and EMA sterility qualifications gate access to hospital formulary positions, filtering supplier pools to manufacturers with validated aseptic lines. Active pharmaceutical ingredient production clusters in China and India, with final sterile compounding concentrated in the United States, Germany, and India. Supply chain vulnerability centers on single-source API dependencies for specialty grades. Distribution runs through group purchasing organizations in the United States and regional hospital networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is compressing supplier counts per health system, forcing subscale manufacturers toward exit or acquisition as multi-year volume commitments favor incumbents with manufacturing scale.
For Market Incumbents: Deploy backward integration into API production to defend margin structure against Chinese cost competition. Secure GPO formulary exclusivity through multi-year sterile supply contracts with mandatory batch documentation. Counter topical segment entrants by accelerating sustained-release depot formulation pipelines for orthopedic protocols. For New Entrants and Emerging Players: Enter via underdeveloped ambulatory surgical center cooperatives in secondary Brazilian cities where hospital procurement consolidation has not yet penetrated. Target Maharashtra state and São Paulo province purchasing alliances with single-dose packaging formats designed for minimal waste. Build initial volume through regional distributor partnerships before scaling to national tenders. For Investors and Strategic Acquirers: Re-rating potential sits with sterile injectable specialists possessing validated aseptic capacity given EMA pharmacovigilance enforcement tightening quality standards. Long-term viability favors manufacturers with dual-source API arrangements and established hospital GPO relationships. Monitor FDA warning letter issuance rates as an inflection indicator for competitive displacement opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive supply of lidocaine base material insulates margin structure from Chinese export price volatility. |
| Sustained-Release Depot Development | Polymeric microsphere formulations extend analgesic duration and differentiate from commodity injectables in orthopedic protocols. |
| Hospital GPO Contract Expansion | Multi-year formulary agreements with US health systems lock out competing suppliers through volume commitment structures. |
| Brazilian ASC Cooperative Penetration | Regional purchasing alliances in São Paulo offer first-mover positioning before national hospital consolidation reaches outpatient surgery. |
| EMA Pharmacovigilance Compliance Investment | Enhanced cardiac toxicity monitoring databases satisfy European marketing authorization requirements and create regulatory moats. |
Research Methodology
Independent corroboration across hospital pharmacy directors, GPO contracts managers, sterile manufacturing quality leads, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from FDA 483 inspection observations, EMA periodic safety update reports, CDSCO production-linked incentive disclosures, and hospital procurement database extracts. Bottom-up demand modeling triangulates against top-down pharmaceutical market sizing across the analysis window.
Rate-of-change decomposition separates volume growth from price mix effects across product type, application, end user, and delivery mode segmentations. CAGRs derive from logistic diffusion curves fitted to historical procedure volumes and reimbursement policy trajectories. Forecast inputs incorporate Medicare same-day surgery reimbursement shifts, ANVISA regulatory pathway timelines, and Indian PLI scheme capacity expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API export restriction scenarios or abrupt FDA sterility guideline revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Ion Channel Modulators Market