
 Hepatitis C Drug Market | 2026-2036
Hepatitis C Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis C Drug Market Analysis
Hospital-based treatment of hepatitis C is shifting toward outpatient and homecare models as oral direct-acting antivirals eliminate the need for interferon-based infusion protocols. Gilead Sciences Inc. dominates the NS5A inhibitor class through manufacturing scale and patent-protected formulations. AbbVie Inc. competes with combination therapies that simplify dosing schedules for payers and patients. Merck & Co., Inc. anchors its position in polymerase inhibition through sustained R&D investment in resistance-profile optimization.
Hepatitis C drugs comprise small-molecule antivirals targeting specific viral enzymes—NS3/4A protease, NS5A replication complex, and NS5B polymerase—with molecular weights typically below 800 Daltons and oral bioavailability exceeding 30% for approved agents; their primary purpose is sustained virologic response, defined as undetectable HCV RNA 12 weeks post-therapy. Combination therapies generate the deepest margin pools by bundling multiple mechanisms into single-pill regimens that command premium reimbursement. Oral delivery mode leads prescription volume due to 8-12 week treatment durations that displace injectable interferon legacy protocols. NS5A inhibitors represent the fastest-growing molecular class as backbone components in pan-genotypic regimens.
The FDA governs approval pathways through breakthrough therapy and priority review vouchers, while the EMA's centralized procedure shapes access across European Union member states; both frameworks demand rigorous resistance-substitution profiling that elevates development costs and extends pre-market timelines. The WHO prequalification program influences procurement in low-income markets where generic substitution pressures originator pricing. Stakeholders must monitor payer consolidation and value-based contracting evolution as these forces reshape access negotiations beyond traditional list-price dynamics.
Market Dynamics
Medicaid reimbursement compression is forcing manufacturers to abandon list-price contracting in favor of outcomes-based agreements that tie payment to sustained virologic response verification. This structural shift is redistributing margin risk from payers to producers across the entire value chain.
Growth Catalysts
- Prison Health Expansion:State correctional systems in the United States are mandating universal HCV screening and treatment protocols, creating guaranteed volume pools for pan-genotypic regimens.
- Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses Phase III-to-launch timelines for novel NS5B polymerase inhibitors, reducing capital lock-up periods for developers.
- Generic Substitution Waves:Patent cliffs for first-generation direct-acting antivirals are enabling WHO prequalified manufacturers to supply low-income markets at procurement price points below originator tiers.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Over 70 percent of NS5A inhibitor raw material synthesis concentrates in Chinese and Indian contract manufacturers, exposing supply continuity to geopolitical friction.
- Resistance-Substitution Profiling Costs:The FDA and EMA both mandate extensive pre-market resistance testing that adds 18-24 months to development timelines and elevates trial expenditures.
- Curative Therapy Paradox:Sustained virologic response eliminates the recurring revenue streams that characterized interferon-era chronic management, compressing addressable market duration per patient.
Strategic Opportunities
- Micro-Elimination Campaigns:National health ministries in Egypt and Georgia are pursuing country-level HCV elimination through mass screening and treatment blitzes, creating concentrated demand surges.
- Fixed-Dose Combination Innovation:Triple-mechanism single-pill regimens combining NS3/4A protease, NS5A, and NS5B inhibitors are commanding premium formulary placement from integrated delivery networks.
- 340B Program Leverage:US federally qualified health centers are expanding HCV treatment capacity through drug pricing discounts, opening access points in underserved rural and urban corridors.
Industry Challenges
- Virology Specialist Scarcity:The shift from interferon-based infusion centers to oral therapy management has eliminated the training pipeline for hepatology nurses, creating workforce gaps in patient monitoring.
- Reimbursement Documentation Burden:Prior authorization requirements for direct-acting antivirals demand fibrosis staging evidence and treatment history verification that delays therapy initiation by 3-6 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis C Drug Market |
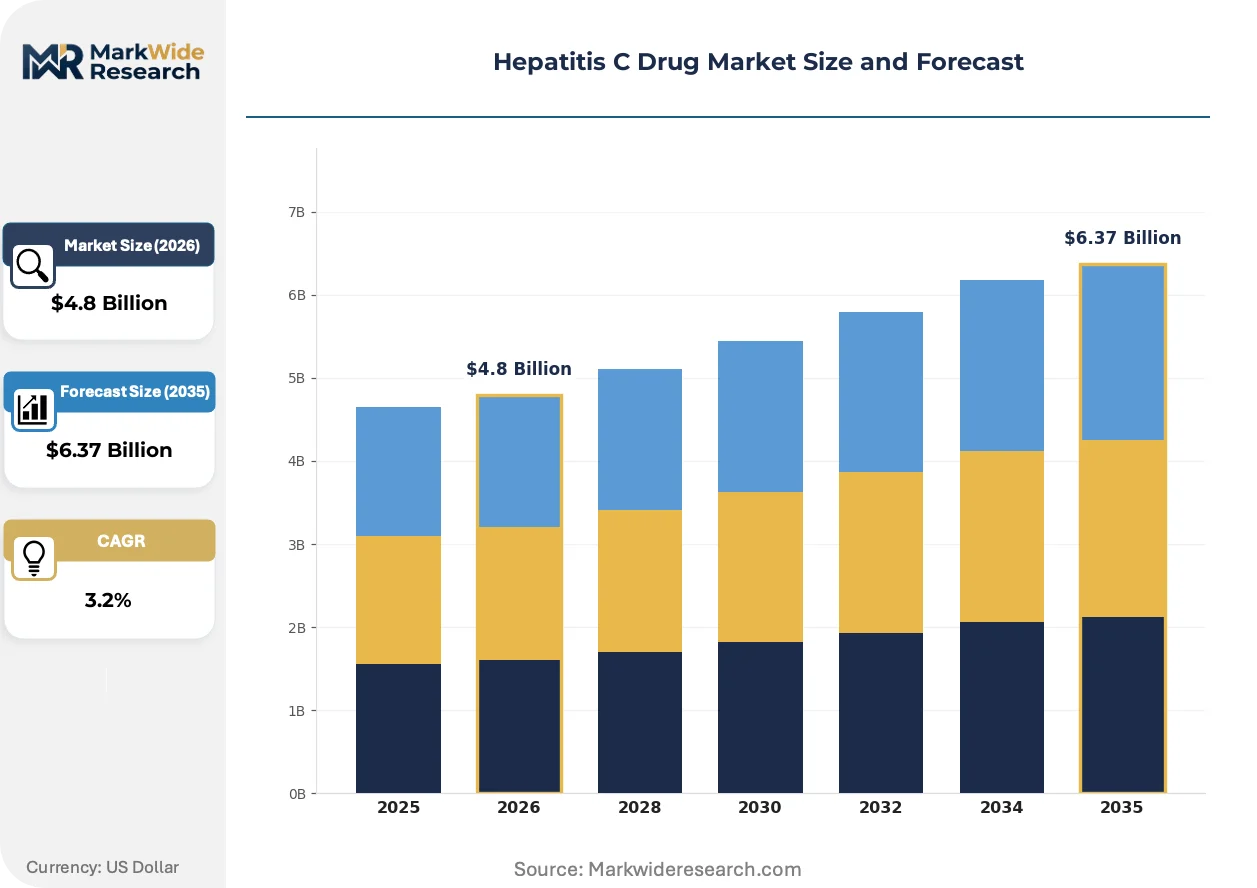
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NS5A Inhibitors, NS3/4A Inhibitors, Polymerase Inhibitors, Combination Therapies Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Research Labs, Homecare Therapy Area: Chronic Infection, Viral Clearance, Liver Health, Secondary Therapies |
| Companies Covered | Gilead Sciences Inc., AbbVie Inc., Merck & Co., Inc., Bristol-Myers Squibb Co., F. Hoffmann-La Roche Ltd, Johnson & Johnson, Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis C Drug Market Emerging Trajectories
Pharmacogenomic integration is reshaping how prescribers match patient IL28B genotype status to optimal regimen selection, compressing trial-and-error protocols that previously extended treatment duration.
Artificial intelligence-driven resistance prediction algorithms are converging with real-world evidence platforms to forecast treatment failure before regimen initiation. Large integrated delivery networks in the United States are deploying these tools at the point of prescribing to optimize formulary positioning. This convergence is enabling risk-sharing contracts that transfer outcome accountability from payer to manufacturer.
The FDA's Real-Time Oncology Review pilot has expanded to include infectious disease applications, allowing rolling submission of HCV clinical data before trial completion. This regulatory innovation compresses pre-market review timelines by 4-6 months for qualifying therapies. Manufacturers with breakthrough-designated assets are restructuring regulatory affairs teams to exploit this pathway.
Hospital pharmacy directors are consolidating antiviral procurement through group purchasing organizations that demand standardized outcome metrics across competing regimens. This buying-pattern shift displaces individual drug-level negotiations in favor of portfolio-level contracts. The phenomenon is most visible in California and Texas, where Medicaid managed care organizations have adopted identical performance frameworks.
Hepatitis C Drug Market Segmentation
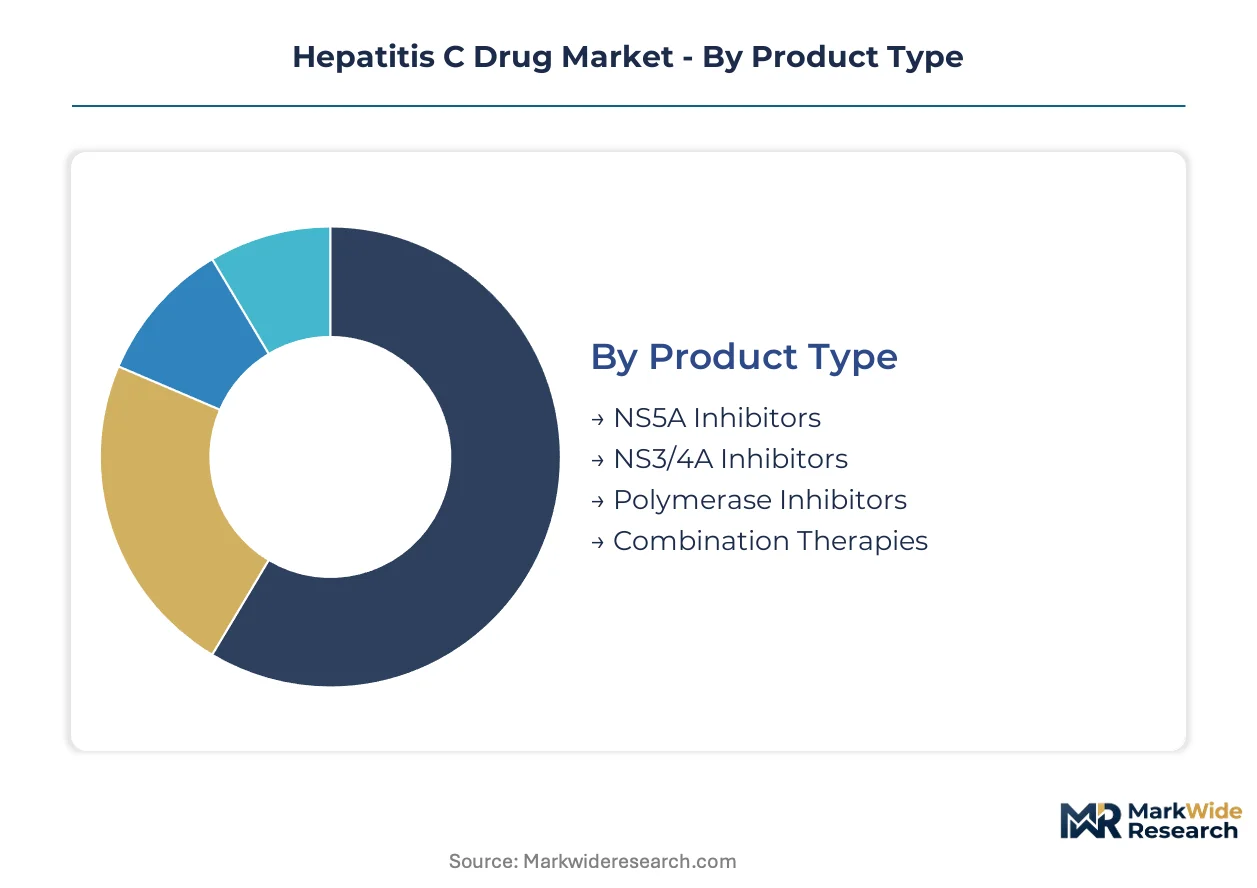
Segmentation in the Hepatitis C drug market reveals how regulatory pathways, reimbursement structures, and patient access routes fragment commercial opportunity. Each dimension carries distinct certification burdens and margin profiles that reshape competitive positioning across the value chain.
Product Type:
FDA breakthrough therapy designation applies differentially across molecular classes, with NS5A inhibitors and combination therapies commanding accelerated review while polymerase inhibitors face extended resistance-substitution profiling requirements.
- NS5A Inhibitors:These replication complex disruptors, exemplified by daclatasvir and ledipasvir, feature molecular weights below 600 Daltons with high hepatic uptake. Demand concentrates in Medicaid expansion states where pan-genotypic coverage simplifies prior authorization. Patent-protected formulations sustain originator pricing power despite generic entry in other classes.
- Combination Therapies:Fixed-dose regimens bundling NS3/4A protease, NS5A, and NS5B mechanisms into single-pill protocols dominate integrated delivery network formularies. Egypt's mass elimination campaign has generated concentrated procurement volumes for these premium-tier products.
- NS3/4A Inhibitors:Protease-targeting agents require genotype-specific prescribing that fragments addressable markets.
- Polymerase Inhibitors:NS5B-targeting nucleoside analogs anchor salvage therapy protocols for treatment-experienced patients.
Leading the category by volume: Combination Therapies. Growing fastest: NS5A Inhibitors.
Delivery Mode:
Cost tier stratification separates oral regimens commanding premium reimbursement from injectable formats relegated to salvage protocols and interferon-refractory populations.
- Oral:Direct-acting antiviral tablets with 8-12 week treatment durations displace legacy infusion centers. The 340B program expansion in US federally qualified health centers has amplified prescription volume for oral agents in underserved corridors.
- Injectable:Pegylated interferon-ribavirin combinations persist only in resource-constrained settings where generic pricing offsets efficacy limitations.
- Intravenous:Hospital-administered formulations serve decompensated cirrhosis populations with acute presentation.
- Subcutaneous:Self-administered interferon legacy products retain marginal share in prison health systems with restricted formulary access.
Oral delivery commands absolute volume dominance. Injectable formats are contracting most rapidly as guidelines exclude interferon from first-line protocols.
End User:
Customer type determines procurement leverage, with hospital systems extracting outcome-based concessions while homecare channels fragment purchasing power across dispersed prescriber networks.
- Hospitals:Academic medical centers and integrated delivery networks consolidate antiviral procurement through group purchasing organizations demanding standardized sustained virologic response metrics. California and Texas Medicaid managed care organizations have adopted identical performance frameworks.
- Clinics:Community-based hepatology practices serve Medicaid and uninsured populations where prior authorization documentation burdens delay therapy initiation.
- Research Labs:Resistance-substitution profiling and pharmacogenomic testing facilities support pre-market development and post-market surveillance.
- Homecare:Oral therapy enablement has expanded pharmacist-managed adherence monitoring for rural and immobile patient cohorts.
Hospitals lead procurement volume through consolidated buying power. Homecare is expanding most quickly as oral regimens eliminate infusion requirements.
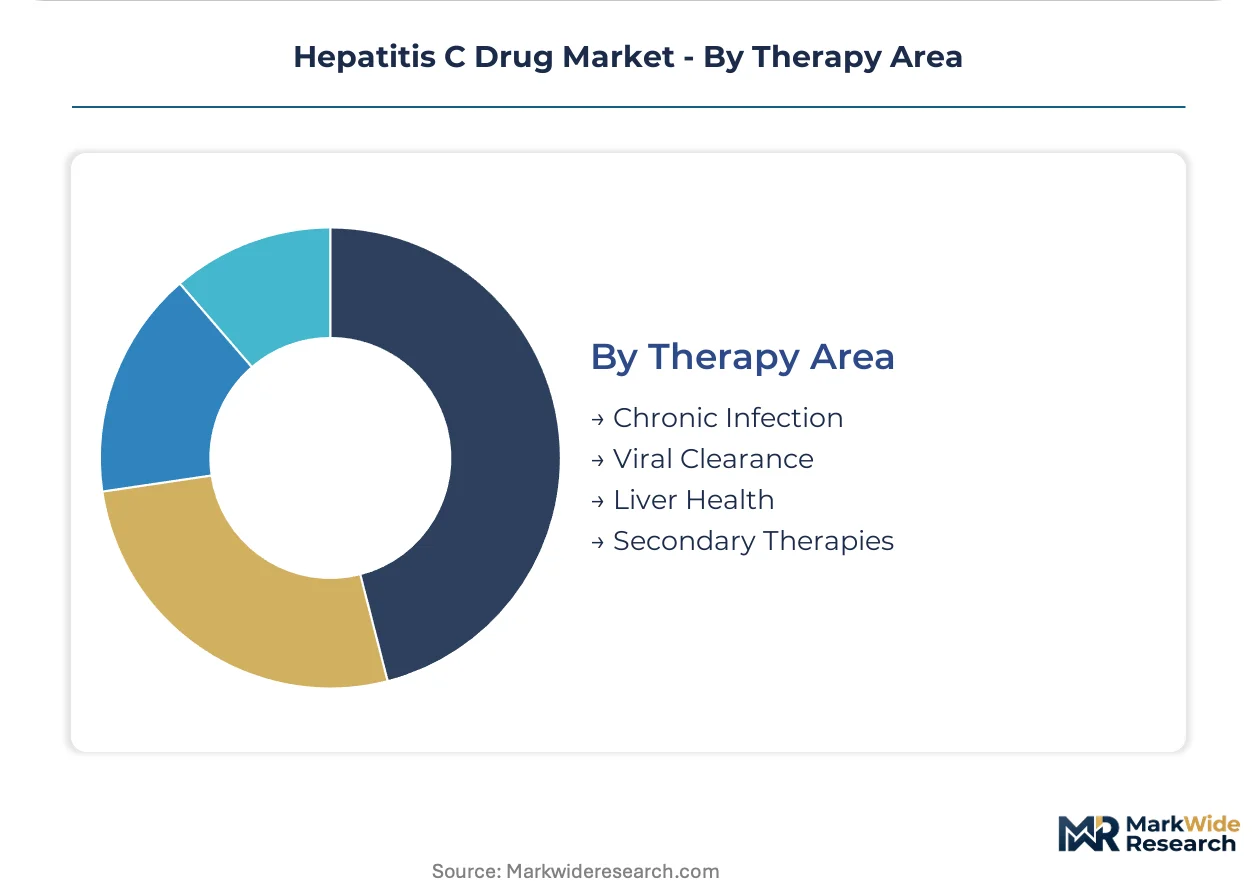
Therapy Area:
Maturity gradients separate established chronic infection management from emerging secondary therapy applications where evidence generation remains incomplete.
- Chronic Infection:Sustained virologic response as primary endpoint drives regulatory approval and reimbursement authorization across all major markets. Georgia's national elimination program has concentrated treatment volume in this segment.
- Viral Clearance:Post-transplant prophylaxis and reinfection prevention protocols represent emerging applications with evolving evidence standards.
- Liver Health:Fibrosis regression and hepatocellular carcinoma risk reduction claims require extended follow-up data that prolongs label expansion timelines.
- Secondary Therapies:Extrahepatic manifestation management and cryoglobulinemia treatment occupy niche positioning with limited payer recognition.
Chronic infection management dominates prescription volume. Viral clearance applications are climbing the fastest as transplant centers expand prophylactic protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis concentrates in Asian contract manufacturing clusters, while treatment demand localizes in North American and European reimbursement systems. This geographic split shapes procurement patterns and regulatory submission strategies across the value chain.
United States
Medicaid expansion and prison health programs sustain high treatment volumes for pan-genotypic regimens. The FDA's breakthrough therapy designation compresses Phase III-to-launch timelines for novel NS5B polymerase inhibitors. California and Texas Medicaid managed care organizations have adopted identical performance frameworks for antiviral procurement.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor European demand for combination therapies with resistance-optimized profiles. The EMA's centralized procedure shapes access across EU member states through rigorous pre-market resistance-substitution profiling. Frankfurt-based procurement consortia negotiate portfolio-level contracts with standardized sustained virologic response metrics.
Egypt
National health ministry mass screening and treatment blitzes have created concentrated demand surges for fixed-dose combination therapies. WHO prequalification program procurement channels enable generic substitution at price points below originator tiers. Cairo and the Nile Delta corridor host the world's largest micro-elimination campaign infrastructure.
India
Contract manufacturers in Gujarat and Maharashtra supply over 70 percent of NS5A inhibitor raw material synthesis, exposing supply continuity to geopolitical friction. CDSCO regulatory pathways support domestic production of direct-acting antivirals for export to low-income markets. Hyderabad's pharmaceutical cluster specializes in resistance-substitution profiling for pre-market development.
Switzerland
Swissmedic approval pathways attract developers seeking parallel EMA submission efficiency for polymerase inhibitor portfolios. Basel and Zurich host concentrated R&D investment in pan-genotypic regimen optimization. The country's reimbursement authorities negotiate outcomes-based agreements that tie payment to sustained virologic response verification.
Hepatitis C Drug Market Vendor Landscape
Top-tier vendors anchor originator drug development, while mid-scale specialists concentrate on generic API synthesis and regional distribution. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with breakthrough-designated assets, regional formulators with WHO prequalification status, and contract research organizations supporting resistance profiling. Competitive moves center on fixed-dose combination patent filing and 340B program contract capture.
Within the originator tier, Gilead Sciences Inc., AbbVie Inc., and Merck & Co., Inc. exemplify divergent strategic positioning. Gilead Sciences Inc. represents manufacturing scale dominance in NS5A inhibitor supply. AbbVie Inc. occupies a position emphasizing simplified dosing schedules for payer and patient compliance. Merck & Co., Inc. anchors polymerase inhibition specialization through sustained R&D commitment. These three entities collectively illustrate how patent-protected formulations, combination therapy bundling, and resistance-profile optimization define competitive differentiation in curative regimen markets.
| Leading Market Players |
|---|
| Gilead Sciences Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Co. |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient synthesis costs for NS5A inhibitors flow from Chinese and Indian contract manufacturers through tiered pricing structures that separate originator formulations from WHO-prequalified generic tiers, with Medicaid reimbursement compression forcing manufacturers toward outcomes-based contracts that redistribute margin risk downstream.
Pricing Analysis
Cost compression in Medicaid-managed segments intensifies as state correctional systems and expansion programs mandate universal HCV screening, pressuring list-price contracting toward value-based agreements. Pricing stratifies across originator premium, authorized generic, and WHO-prequalified economy tiers differentiated by patent status and resistance-profile certification. Price erosion runs through first-generation protease inhibitors facing patent cliffs, while pan-genotypic regimens retain pricing power. Payers in prison health and 340B programs exhibit highest price sensitivity; integrated delivery networks with GPO leverage show lowest.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's dual carbon goals are reshaping active pharmaceutical ingredient sourcing toward localized fermentation and synthesis capabilities. Over seventy percent of NS5A inhibitor raw material production concentrates in Gujarat, Maharashtra, and Zhejiang province clusters, drawing from specialized intermediate chemicals and catalyst inputs. Single-source vulnerability concentrates in geopolitically exposed contract manufacturing organizations. Distribution runs through hospital pharmacy directors consolidating procurement via group purchasing organizations demanding standardized outcome metrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-acting antiviral oral regimens are displacing interferon-based infusion protocols, compressing treatment duration from chronic management to 8-12 week curative courses and eliminating legacy revenue streams.
For Market Incumbents: Deploy resistance-profile optimization R&D to anchor salvage therapy positioning against generic substitution waves threatening first-generation assets. Deepen backward integration into NS5A inhibitor API synthesis to reduce exposure to Chinese and Indian contract manufacturing concentration. Capture 340B program contracts at federally qualified health centers before formulary consolidation hardens. For New Entrants and Emerging Players: Enter via WHO prequalification pathways targeting Egypt and Georgia micro-elimination campaigns where concentrated procurement volumes bypass entrenched integrated delivery network formularies. Prison health systems in Medicaid expansion states represent the most penetrable segment given mandated universal screening protocols. Pursue pharmacist-managed adherence monitoring partnerships for rural homecare channels. For Investors and Strategic Acquirers: FDA breakthrough therapy designation expansion to infectious disease applications is the leading indicator that regulatory timeline compression will reward developers with accelerated review assets. Long-term viability hinges on pan-genotypic regimen portfolios with resistance-optimized profiles. Target acquisition profile centers on mid-scale specialists with CDSCO-approved manufacturing and existing WHO prequalification status. Watch for payer consolidation in California and Texas Medicaid managed care as inflection signal for portfolio-level contracting dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA's infectious disease pilot compresses Phase III-to-launch timelines for NS5B polymerase inhibitors. |
| Fixed-Dose Combination Patent Filing | Triple-mechanism single-pill regimens command premium formulary placement from integrated delivery networks. |
| 340B Program Contract Capture | Federally qualified health centers expand treatment capacity through drug pricing discounts in underserved corridors. |
| Backward Integration into API Synthesis | In-house production of NS5A inhibitor raw materials reduces exposure to geopolitical friction in Asian contract manufacturing. |
| Pharmacogenomic Platform Development | IL28B genotype matching tools enable risk-sharing contracts transferring outcome accountability to manufacturers. |
Methodological Framework
Multi-period observation of Medicaid reimbursement rates, prison health procurement volumes, and formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA breakthrough therapy filings, EMA centralized procedure submissions, ClinicalTrials.gov enrollment data, and WHO prequalification program records. Bottom-up prescription volume modeling and top-down revenue triangulation converged on segment-level estimates.
Input-output matrices mapped patient population flows across treatment lines, dosage forms, administration routes, and regional regulatory clusters to generate volume and value projections over the analysis window. CAGRs derived from regression analysis of historical Medicaid expenditure patterns and patent expiration schedules. Forecast inputs incorporated resistance-substitution profiling timelines, prior authorization approval rates, and micro-elimination campaign procurement announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to API supply chains or abrupt Medicaid reimbursement policy shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Ibuprofen API Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Antimycotics Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Medication Adherence Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Hypertension Drug Market
Pharmacology
Influenza Medication Market
Pharmacology
Propranolol Drug Market
Pharmacology
Olanzapine API Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Alzheimer's Therapeutics Market