
 Gasification Market | 2026-2036
Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Gasification Market Intelligence
The proliferation of modular and small-scale gasification systems is narrowing the economic viability gap for decentralized waste-to-energy and biomass projects. This shift challenges the dominance of large, centralized plants traditionally supported by major engineering firms. General Electric leverages its turbine expertise for integrated gasification combined cycle applications, while Siemens specializes in advanced syngas cooling technologies. Mitsubishi Heavy Industries leads in the high-pressure entrained flow gasifier segment for large-scale chemical production.
Gasification is a thermochemical process that converts carbonaceous materials, such as coal or biomass, into a synthesis gas, or syngas. The process operates at high temperatures, typically above 700°C, with a controlled amount of an oxidizing agent like oxygen or steam. This syngas serves as a versatile intermediate for producing chemicals, hydrogen, synthetic fuels, and electricity. While coal remains a primary feedstock for large-scale chemical production, biomass and municipal solid waste are the fastest-growing feedstock segments, driven by waste-to-value initiatives.
Regulatory frameworks are critical in shaping technology choices and project economics. The US EPA’s emission standards and the EU’s Industrial Emissions Directive push for cleaner gasification systems and lower pollutant outputs. Similarly, China's MEE policies on air quality and carbon intensity favor technologies with integrated carbon capture capabilities. Navigating the complex interplay between feedstock price volatility and evolving carbon pricing mechanisms will determine long-term profitability for operators.
Market Dynamics
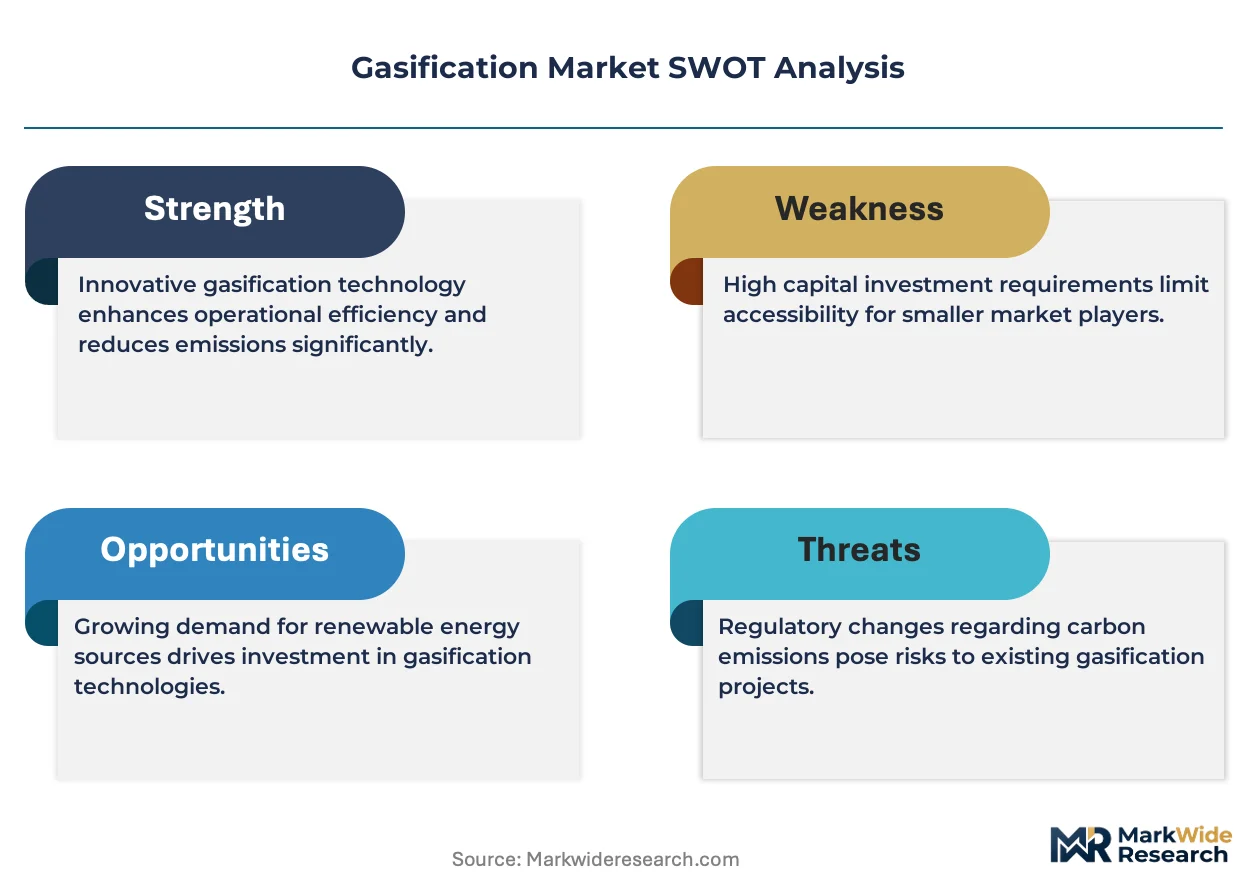
The primary structural force shaping the gasification market is the convergence of stringent environmental mandates, such as the US EPA's emission standards, with the economic imperative to process increasingly diverse and volatile feedstocks like municipal solid waste.
Growth Catalysts
- EU Industrial Emissions Directive:This framework compels operators to adopt best available techniques, accelerating investment in advanced syngas cooling and cleaning systems to meet stricter pollutant limits.
- Chemicals Demand:The persistent need for syngas-derived products, particularly in China's coal-to-chemicals sector, sustains a baseline demand for large-scale, high-pressure gasification technologies.
- Waste-to-Value Initiatives:Government policies promoting circular economy principles are creating new markets for modular gasification systems capable of converting biomass and municipal solid waste into local energy.
Market Restraints
- High Capital Intensity:The substantial upfront investment required for constructing large-scale integrated gasification combined cycle (IGCC) plants remains a significant barrier for new entrants and project developers.
- Feedstock Price Volatility:Unpredictable price swings for primary inputs like coal and natural gas, as well as fluctuating gate fees for municipal solid waste, complicate long-term project financing.
- Technical Complexity:Persistent issues with tar formation and removal in certain biomass gasification processes can reduce operational reliability and increase maintenance costs, hindering wider adoption.
Strategic Opportunities
- Green Hydrogen Production:Gasification of biomass and waste offers a non-fossil pathway to produce hydrogen, aligning with national decarbonization strategies and creating new revenue streams from hydrogen offtake agreements.
- Regulatory Incentives:The US Inflation Reduction Act (IRA) provides tax credits for producing low-carbon hydrogen and capturing carbon, substantially improving the economic case for gasification projects with CCUS.
- Decentralized Energy in Asia:Developing economies in Southeast Asia present a significant opportunity for small-scale gasification units to convert agricultural residues and urban waste into reliable power.
Industry Challenges
- Systems Integration Complexity:Ensuring seamless operation between the gasifier, syngas cleanup units, and downstream power or chemical synthesis blocks requires specialized engineering expertise that is in short supply.
- Operator Skill Gaps:The safe and efficient operation of high-temperature, high-pressure gasification systems demands a highly trained workforce, creating a bottleneck for rapid capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasification Market |
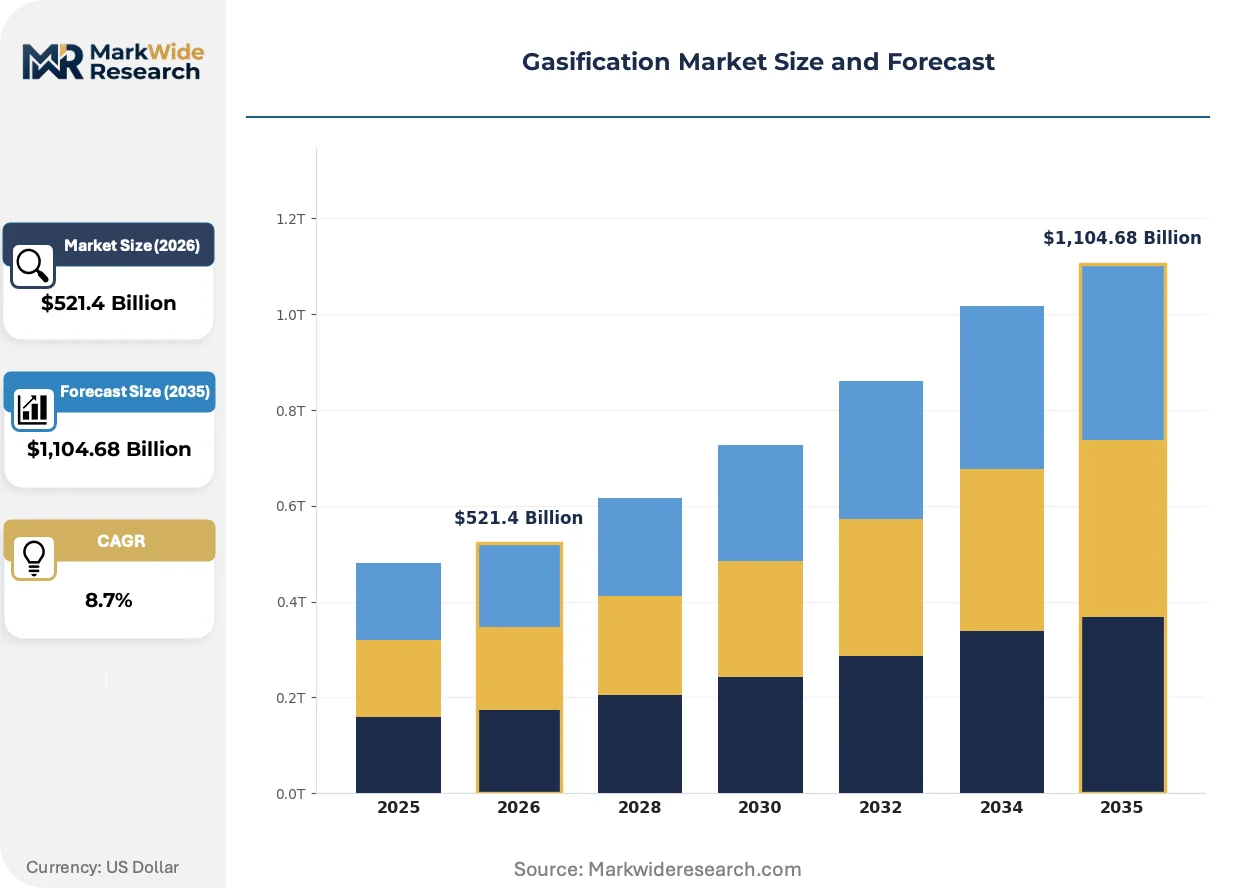
| Market Size in 2026 | $521.4 Billion |
| Market Size in 2035 | $1,104.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed, Fluidized Bed, Entrained Flow, Plasma Gasification, Catalytic Gasification Feedstock Type: Coal, Biomass, Municipal Solid Waste, Petroleum Coke, Agricultural Residues Application: Power Generation, Chemicals Production, Hydrogen Production, Synthetic Fuels, Waste Management End User: Energy Producers, Chemical Manufacturers, Refineries, Waste Treatment Facilities |
| Companies Covered | Royal Dutch Shell, Air Liquide, General Electric, Mitsubishi Heavy Industries, KBR Inc., Siemens, Thyssenkrupp AG, SEDIN Engineering Company Limited, Synthesis Energy Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasification Market Strategic Shifts & Innovations
The market's evolution is defined by a technological pivot toward operational flexibility and process intelligence. This movement enables the use of varied carbonaceous materials beyond traditional coal, optimizing efficiency and environmental performance through advanced digital tools.
Digital twin technology creates a dynamic virtual model of a physical gasification plant. Chemical and power generation operators are adopting these models to simulate feedstock changes and process adjustments without physical risk. This innovation is virtualizing the expensive and time-consuming pilot testing phase, accelerating the path to optimized plant performance.
China’s MEE policies targeting air quality and carbon intensity are directly impacting technology selection for new chemical plants. The regulations incentivize or mandate the inclusion of carbon capture systems with gasification units. Consequently, the domestic coal-to-chemicals sector is pioneering the large-scale integration of gasification with CCUS technologies.
A demand shift toward feedstock optionality is altering supply contracts. Project developers and plant operators are moving away from rigid, long-term agreements for a single feedstock like coal. This trend is most pronounced in Europe, where facilities are being designed to accept a mix of biomass, refuse-derived fuel, and other wastes to mitigate supply risks.
Gasification Market Segmentation
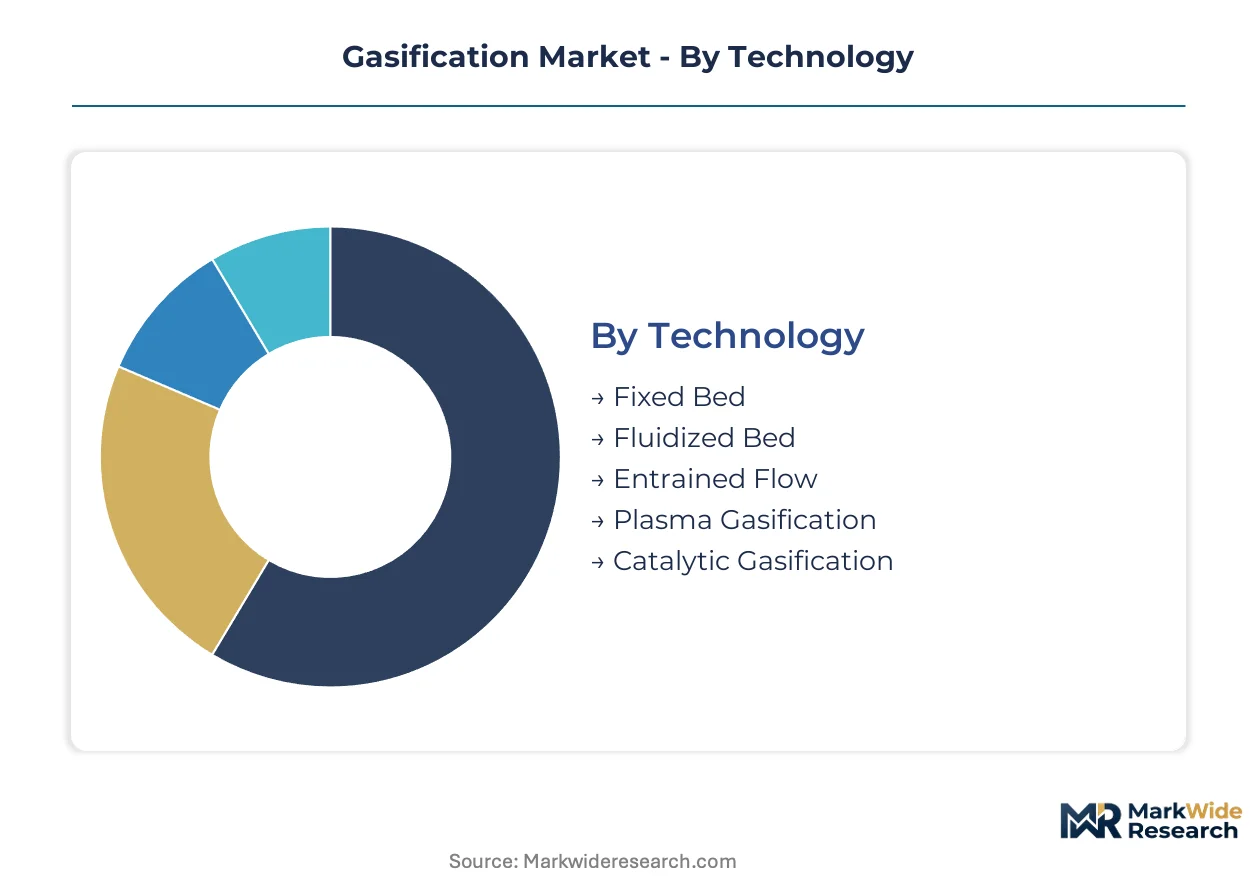
The gasification market's diverse applications and feedstock flexibility necessitate granular segmentation for strategic planning. Understanding these distinct segments reveals where technological advancements and market demand converge. This analysis delineates the core components driving industry expansion and profitability.
Technology:
The various gasification technologies exhibit distinct cycle times from project inception to commercial operation, influencing investment horizons.
- Entrained Flow:This technology operates at high temperatures and pressures, converting fine coal or petroleum coke into syngas. Mitsubishi Heavy Industries leads in its application for large-scale chemical production, where high syngas purity is critical.
- Plasma Gasification:Utilizing extremely high temperatures generated by plasma torches, this advanced method converts municipal solid waste into syngas. Its adoption is accelerating in waste-to-energy initiatives, particularly for difficult-to-treat feedstocks.
- Fixed Bed:This technology processes solid feedstocks in a stationary bed, offering simpler operation for smaller-scale biomass or coal gasification projects.
- Fluidized Bed:Characterized by excellent heat and mass transfer, fluidized bed systems efficiently gasify diverse feedstocks, including biomass and refuse-derived fuels.
- Catalytic Gasification:This process uses catalysts to lower operating temperatures and improve syngas quality, particularly for hydrogen production from biomass.
Entrained flow gasification anchors the volume base while plasma gasification gains share at the steepest rate.
Feedstock Type:
Feedstock selection directly impacts the operational parameters and environmental footprint of gasification projects, dictating specific processing requirements.
- Coal:As a traditional and abundant feedstock, coal remains a primary input for large-scale chemical production, especially in China's industrial sector. Its continued use depends on integrated carbon capture solutions to meet emissions standards.
- Municipal Solid Waste:This diverse feedstock is increasingly processed through gasification for waste-to-value initiatives. Government policies in Europe and Southeast Asia are driving its expansion for localized energy generation.
- Biomass:Agricultural residues, wood waste, and energy crops offer carbon-neutral feedstock options for decentralized power and synthetic fuel production.
- Petroleum Coke:A byproduct of oil refining, petroleum coke provides a high-energy feedstock for syngas production, often used in integrated refineries.
- Agricultural Residues:Crop stalks, husks, and other farm waste represent a sustainable feedstock source, particularly for rural energy projects in developing economies.
Coal provides a stable, high-volume feedstock option, while municipal solid waste processing is climbing the fastest due to waste management mandates.
Application:
The end-use application of syngas determines the required purity and scale of the gasification system, influencing design and operational complexity.
- Chemicals Production:Syngas serves as a foundational building block for methanol, ammonia, and other industrial chemicals. Demand in China's coal-to-chemicals sector represents a significant volume driver for high-purity syngas.
- Power Generation:Integrated Gasification Combined Cycle (IGCC) plants convert syngas into electricity with higher efficiency and lower emissions than traditional coal plants. General Electric leverages its turbine expertise in this segment.
- Hydrogen Production:Gasification offers a non-fossil pathway to produce hydrogen, supporting national decarbonization strategies and creating new revenue streams.
- Synthetic Fuels:Syngas can be converted into liquid fuels like diesel or gasoline through processes such as Fischer-Tropsch synthesis, reducing reliance on crude oil.
- Waste Management:Gasification provides a thermal treatment solution for various waste streams, reducing landfill volumes and recovering energy or materials.
Chemicals production represents the largest current application, with hydrogen production demonstrating the most rapid expansion trajectory.
End User:
End-user segments exhibit varied investment capacities and regulatory compliance needs, which shape their technology adoption patterns.
- Chemical Manufacturers:These industrial players require stable, high-volume syngas supply for their production processes. They often invest in large-scale, integrated gasification facilities to ensure feedstock security and cost control.
- Waste Treatment Facilities:These entities seek gasification solutions to convert diverse waste streams into valuable energy or products. Their focus often lies on modular, decentralized systems to manage local waste volumes efficiently.
- Energy Producers:Utilities and independent power producers use gasification for cleaner electricity generation, especially in regions with abundant coal or biomass resources.
- Refineries:Petroleum refineries integrate gasification to convert heavy residues like petroleum coke into syngas, which can then be used for power or hydrogen production.
Chemical manufacturers drive substantial capital investment, while waste treatment facilities are increasingly adopting gasification solutions for circular economy objectives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration of chemical manufacturers and waste treatment facilities drives regional demand for gasification solutions. These end-users require stable syngas supply for production or efficient waste-to-value conversion. Regulatory mandates and economic incentives further shape technology adoption across different geographies.
China
China's extensive coal-to-chemicals sector sustains significant demand for large-scale gasification technologies. The country's MEE policies on air quality and carbon intensity mandate cleaner production methods. Industrial clusters in the Yangtze River Delta actively integrate gasification with carbon capture systems.
United States
The United States sees growing demand for gasification in green hydrogen production and cleaner power generation. The US Inflation Reduction Act (IRA) provides substantial tax credits for low-carbon hydrogen and carbon capture. Projects in the Gulf Coast region are leveraging these incentives for new gasification facilities.
Germany
Germany focuses on waste-to-energy initiatives and biomass gasification for decentralized power. The EU’s Industrial Emissions Directive compels operators to adopt best available techniques for pollutant reduction. Facilities in the Ruhr area are designed for feedstock optionality, including refuse-derived fuels.
India
India's demand for gasification arises from decentralized energy needs and the processing of agricultural residues. Government policies promote waste-to-value projects and energy security through local resource utilization. Industrial hubs in Gujarat are exploring small-scale gasification for captive power generation.
Japan
Japan prioritizes advanced waste management solutions, especially plasma gasification for municipal solid waste. METI policies support innovative technologies for energy recovery and resource circulation. The Tokyo Bay area features facilities converting difficult-to-treat feedstocks into syngas.
Gasification Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in gasification technologies. The market structure exhibits a tiered landscape, with major engineering, procurement, and construction (EPC) firms alongside specialized technology licensors. Strategic partnerships for integrated solutions and technology licensing represent dominant competitive moves.
Large, integrated solution providers, including Royal Dutch Shell and Mitsubishi Heavy Industries, anchor the high-capital, large-scale project segment. These companies often offer comprehensive packages spanning technology, engineering, and project execution. Siemens, specializing in advanced syngas cooling, exemplifies a technology-focused player whose innovations are critical for meeting stringent environmental standards across various gasification applications.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| Air Liquide |
| General Electric |
| Mitsubishi Heavy Industries |
| KBR Inc. |
| Siemens |
| Thyssenkrupp AG |
| SEDIN Engineering Company Limited |
| Synthesis Energy Systems Inc. |
| Others |
Cost & Logistics Intelligence
Global bulk shipping lanes' cost dynamics influence feedstock supply concentration, directly impacting regional syngas pricing. This volatility shapes downstream chemical and energy product differentiation.
Pricing Analysis
Cost-plus contracts with commodity price indexation define much of the gasification market's pricing. Long-term offtake agreements for syngas or feedstock establish a stable revenue base, with price differentiation stemming from feedstock type, syngas purity, and geographic delivery costs. Pricing softness reflects persistent feedstock price volatility. Energy producers exhibit high price sensitivity, while chemical manufacturers prioritize syngas purity and supply security.
Supply Chain Analysis
Upstream feedstock procurement for gasification projects concentrates in specific regions. China dominates coal supply, while the US sources petroleum coke, and Southeast Asia provides agricultural residues and municipal solid waste. Raw material dependencies include coal, biomass, and diverse waste streams, with commodity price volatility representing a significant structural risk for operators. Syngas distribution involves direct sales via pipelines or long-term contracts to chemical manufacturers and power generators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gasification market presents a fragmentation opportunity as waste-to-value initiatives create specialized niches. Decentralized energy production from diverse feedstocks requires tailored, smaller-scale solutions.
For Market Incumbents: Build proprietary process integration moats to counter emerging modular system threats. Invest in advanced syngas cleanup and integrate carbon capture (CCUS) solutions to meet stringent emission standards. Leverage R&D in catalyst development for improved efficiency and partner with EPC firms to control project execution channels.
For New Entrants and Emerging Players: Decentralized energy markets in Southeast Asia represent significant underpenetration for modular gasification systems. Target municipal solid waste gasification and agricultural residue conversion for localized power. Small-scale biomass gasification in rural India offers a highly penetrable application. Go-to-market strategies should focus on localized waste management partnerships and energy service agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates divesting non-core gasification technology units. Gasification offers long-term viability for diverse feedstocks over the next decade, driven by decarbonization goals. Focus on specialized technology licensors in plasma or catalytic gasification. A key signal to watch is increased public-private partnerships for waste-to-energy projects, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables chemical manufacturers to secure high-volume syngas supply for their operations. |
| Technology Licensing | Accelerates adoption of advanced plasma gasification for municipal solid waste treatment. |
| Joint Venture | Facilitates large-scale integrated gasification combined cycle (IGCC) plant development in new regions. |
| Green Manufacturing Transition | Positions operators to meet stringent EU Industrial Emissions Directive standards for pollutant reduction. |
| Long-term Supply Agreement | Mitigates feedstock price volatility for operators and ensures stable syngas output. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis. Primary interviews with plant managers, R&D directors, EPC contractors, and waste management executives provided qualitative insights. Secondary validation utilized government environmental reports, industry association publications, and company financial filings. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Market size calibration across the analysis window utilized a multi-factor regression model. The analytical framework integrated segmentation dimensions including technology, feedstock type, application, end user, and regional regulatory environment. Compound annual growth rates were derived from historical data and projected growth drivers over the modeling period. Syngas demand projections and waste generation rates served as key industry-specific forecast inputs.
Practitioners should monitor feedstock price shocks and evolving carbon pricing mechanisms for early signals of market shifts. Forecasts reflect assumptions regarding regulatory stability and technological adoption. Cross-checking against IEA energy outlooks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market