
 North America Biomass Gasification Market | 2026-2036
North America Biomass Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biomass Gasification Market Intelligence
Long-term operations and maintenance contracts are consolidating around integrated service platforms that bundle reactor uptime guarantees with remote monitoring analytics. Mitsubishi Power leverages its turbine integration expertise to anchor combined-cycle biomass gasification projects across the U.S. Southeast. Babcock & Wilcox Enterprises sustains engineering dominance through its bubbling fluidized bed reactor designs for industrial-scale installations. Andritz AG differentiates via specialized feedstock preprocessing systems that handle high-moisture agricultural residues.
Biomass gasification converts organic feedstocks into synthesis gas through partial oxidation at temperatures between 700°C and 1,500°C, yielding a hydrogen-carbon monoxide mixture for power generation or chemical synthesis. Fluidized bed technology leads installed capacity due to superior fuel flexibility and scale economics above 50 MW thermal input. Agricultural residues represent the fastest-expanding feedstock category as corn stover and wheat straw collection infrastructure matures in the U.S. Midwest. Electricity generation captures the dominant application share, though biofuel production for renewable diesel and sustainable aviation fuel blendstocks is gaining margin traction.
The EPA enforces emissions thresholds under the Clean Air Act that shape reactor design and syngas cleanup train specifications for new projects. State regulators in California, New York, and Oregon administer renewable portfolio standards that create offtake certainty for biomass gasification developers. USDA conservation programs and the Biorefinery Assistance Program provide loan guarantees that reduce project finance risk. Stakeholders must monitor evolving carbon accounting methodologies and state-level clean hydrogen production tax credits that could reclassify biomass gasification pathways.
Market Dynamics
State-level renewable portfolio standards in California and New York are compressing project development timelines and forcing technology convergence between biomass gasification and carbon capture systems.
Growth Catalysts
- Renewable Fuel Standard:The EPA's mandate for advanced biofuels creates guaranteed offtake volumes for syngas-to-liquid fuel pathways, anchoring project finance.
- Pulp mill residue clustering:Georgia and Mississippi processing hubs concentrate feedstock supply within 50-mile collection radii, slashing logistics costs for new entrants.
- Fluidized bed reactor maturation:Bubbling and circulating designs now achieve 90% carbon conversion efficiency, expanding viable feedstock ranges to high-alkali agricultural residues.
Market Restraints
- Tariff-driven equipment costs:Pressure vessel and gas cleanup train imports face duties that inflate front-end engineering expenses by 15-25% for non-domestic suppliers.
- Syngas conditioning bottlenecks:Tars and particulates in raw producer gas require multi-stage scrubbing systems that consume 8-12% of plant energy output.
- Natural gas price volatility:Henry Hub fluctuations below $3.00/MMBtu erode biomass feedstock cost advantages in baseload power tenders.
Strategic Opportunities
- Clean hydrogen production tax credits:The IRA's 45V credit structure rewards biomass-derived hydrogen with upstream carbon capture, opening chemical synthesis markets.
- Sustainable aviation fuel blendstocks:Fischer-Tropsch synthesis from woody biomass syngas qualifies for California's LCFS credits at 2-3x conventional biofuel rates.
- Remote monitoring convergence:IoT sensor networks paired with machine learning platforms enable predictive maintenance contracts that guarantee 95% reactor availability.
Industry Challenges
- Gasification engineer scarcity:North American universities graduate fewer than 50 specialized process engineers annually, forcing developers to recruit from European and Asian talent pools.
- Interconnection queue delays:ERCOT and CAISO backlogs stretch 18-36 months for biomass gasification projects seeking grid connection above 50 MW.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biomass Gasification Market |
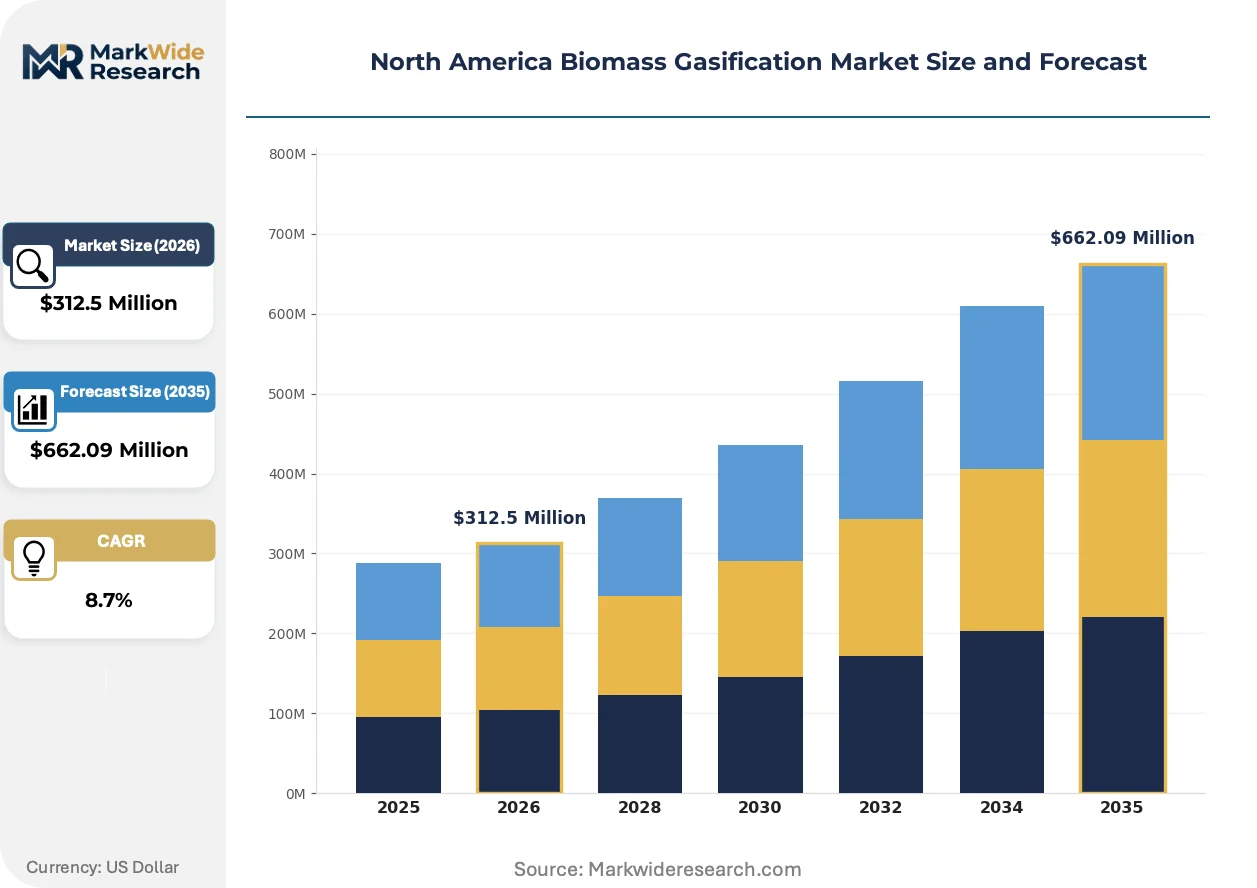
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed, Fluidized Bed, Plasma Arc, Downdraft Feedstock Type: Agricultural Residues, Wood Chips, Energy Crops, Municipal Solid Waste Application: Electricity Generation, Heat Production, Biofuel Production, Chemical Manufacturing End User: Power Plants, Industrial Facilities, Agricultural Sector, Waste Management Companies |
| Companies Covered | Mitsubishi Power, Andritz AG, Siemens Energy, Biomass Engineering & Equipment, EQTEC plc, Babcock & Wilcox Enterprises, Nexterra Systems Corp, Thyssenkrupp AG, Valmet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biomass Gasification Market Strategic Shifts & Innovations
Reactor automation and syngas analytics are compressing operational staffing models while expanding feedstock flexibility beyond traditional woody biomass.
Distributed control systems with embedded AI diagnostics are automating reactor temperature modulation and feedstock blending decisions. Power utilities in the U.S. Southeast are deploying these platforms at 100 MW-scale installations to reduce shift staffing from 12 to 4 operators. The technology is automating real-time adjustments that previously required 15-20 minutes of manual intervention, cutting unplanned shutdown frequency by 40%.
The EPA's pending Maximum Achievable Control Technology standards for hazardous air pollutants will tighten particulate and hydrogen chloride limits for new gasification facilities. Equipment vendors are responding with ceramic hot-gas filtration and catalytic tar cracking trains that add $8-12 million to project capital costs. Industrial-scale installations in Texas and Louisiana face the steepest compliance curves due to existing petrochemical facility density.
Long-term power purchase agreements with fixed escalators are displacing merchant market exposure for project sponsors. Independent power producers in the Pacific Northwest are bundling 20-year contracts with renewable energy certificate streams to attract institutional capital. This structure concentrates development activity in states with mandatory RPS targets rather than voluntary green pricing programs.
North America Biomass Gasification Market Segmentation
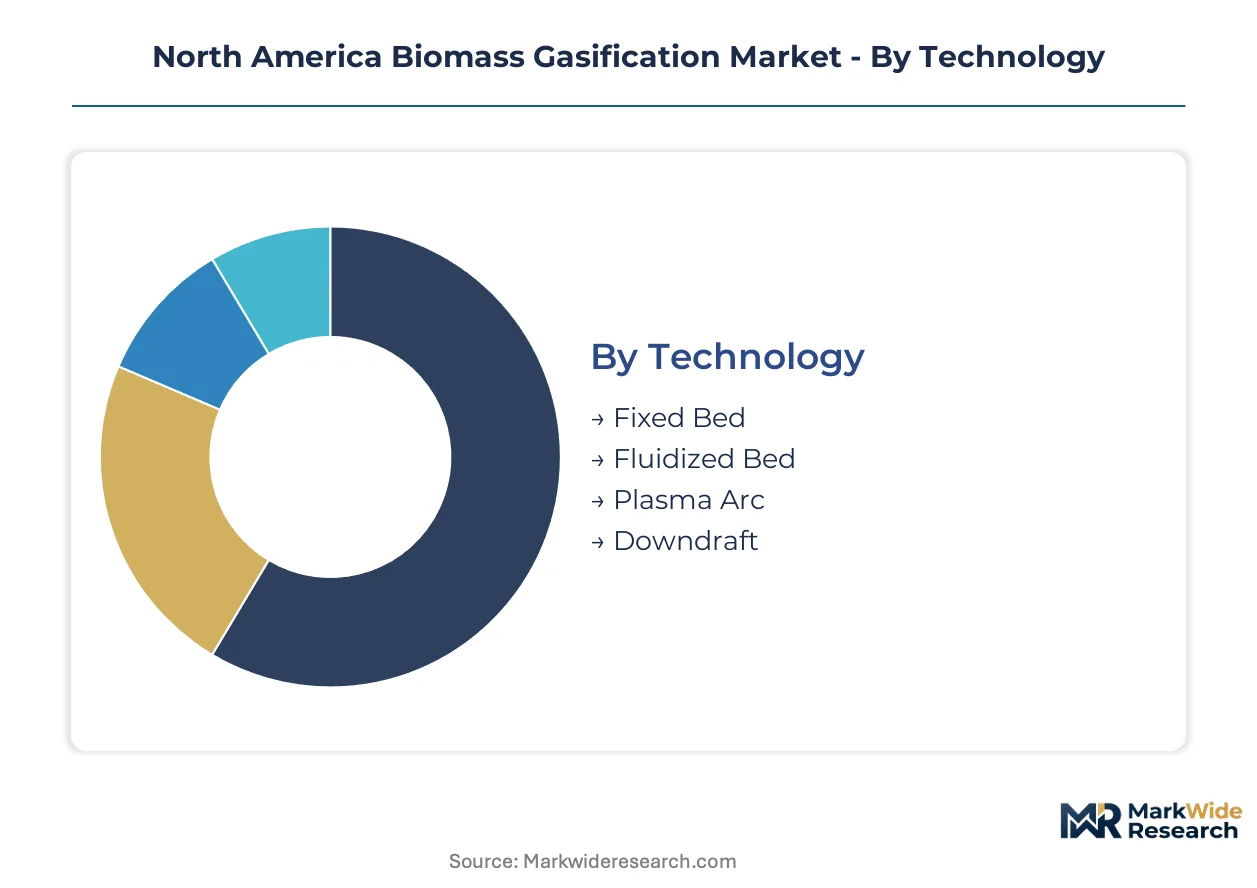
Technology choice dictates reactor capital requirements and feedstock flexibility for North American developers. Feedstock procurement patterns and application economics further stratify project returns across the U.S. Southeast and Midwest supply basins.
Technology:
Capital intensity varies sharply by reactor configuration, with pressurized designs demanding 40-60% higher upfront investment than atmospheric alternatives.
- Fluidized Bed:Bubbling and circulating configurations dominate utility-scale deployment above 50 MW thermal input. Georgia and Mississippi processing hubs favor these systems for pulp mill residue conversion due to superior fuel flexibility and 90% carbon conversion efficiency.
- Fixed Bed:Updraft and downdraft reactors suit distributed applications below 10 MW with lower capital barriers. Rural Midwest installations processing agricultural residues select fixed bed units where grid interconnection queues stretch beyond 24 months.
- Plasma Arc:Electric arc torches achieve temperatures exceeding 3,000°C for complete tar destruction. Texas and Louisiana industrial clusters pilot these systems for hazardous waste co-processing despite 2-3x capital cost premiums.
- Downdraft:Cross-draft gasifiers produce low-tar syngas suited for small-scale engine applications. Agricultural cooperatives in Iowa and Illinois deploy downdraft units for on-farm power where natural gas pipeline access is limited.
Fluidized bed systems absorb the bulk of installed capacity; plasma arc configurations are expanding most quickly in petrochemical corridor demonstrations.
Feedstock Type:
Logistics radius and preprocessing requirements determine delivered cost structures across North American supply sheds.
- Agricultural Residues:Corn stover and wheat straw collection infrastructure matures across the U.S. Midwest. EPA Renewable Fuel Standard compliance drives demand concentration in Iowa, Nebraska, and Kansas where residue density exceeds 5 tons per square mile.
- Wood Chips:Forest thinning and sawmill residuals supply established procurement networks. Pacific Northwest independent power producers secure 20-year power purchase agreements backed by wood chip supply contracts with fixed escalators.
- Energy Crops:Dedicated sorghum and switchgrass cultivation expands on marginal cropland. USDA Biorefinery Assistance Program loan guarantees de-risk project finance for energy crop gasification in Mississippi and Alabama.
- Municipal Solid Waste:RDF and biosolids streams face stringent EPA emissions thresholds under pending Maximum Achievable Control Technology standards. California waste management companies pursue gasification as landfill diversion compliance tightens in Los Angeles and San Francisco metro areas.
Wood chips anchor current installed capacity; agricultural residues are climbing the fastest as Midwest collection infrastructure scales.
Application:
Revenue stability differs markedly between regulated power tariffs and merchant biofuel markets.
- Electricity Generation:Baseload power sales to utilities under long-term contracts dominate project economics. ERCOT and CAISO interconnection backlogs stretch 18-36 months for biomass gasification projects above 50 MW.
- Biofuel Production:Fischer-Tropsch synthesis yields renewable diesel and sustainable aviation fuel blendstocks. California LCFS credits reward woody biomass pathways at 2-3x conventional biofuel rates, concentrating development in the Central Valley.
- Heat Production:Industrial process steam and district heating applications serve pulp mills and chemical facilities. Babcock & Wilcox bubbling fluidized bed designs anchor combined heat and power installations across the U.S. Southeast.
- Chemical Manufacturing:Syngas-to-methanol and ammonia pathways compete with natural gas reforming. IRA Section 45V clean hydrogen production tax credits reclassify biomass gasification economics for Texas and Louisiana chemical corridor projects.
Electricity generation commands the dominant revenue share; biofuel production is gaining margin traction fastest through California credit stacking.
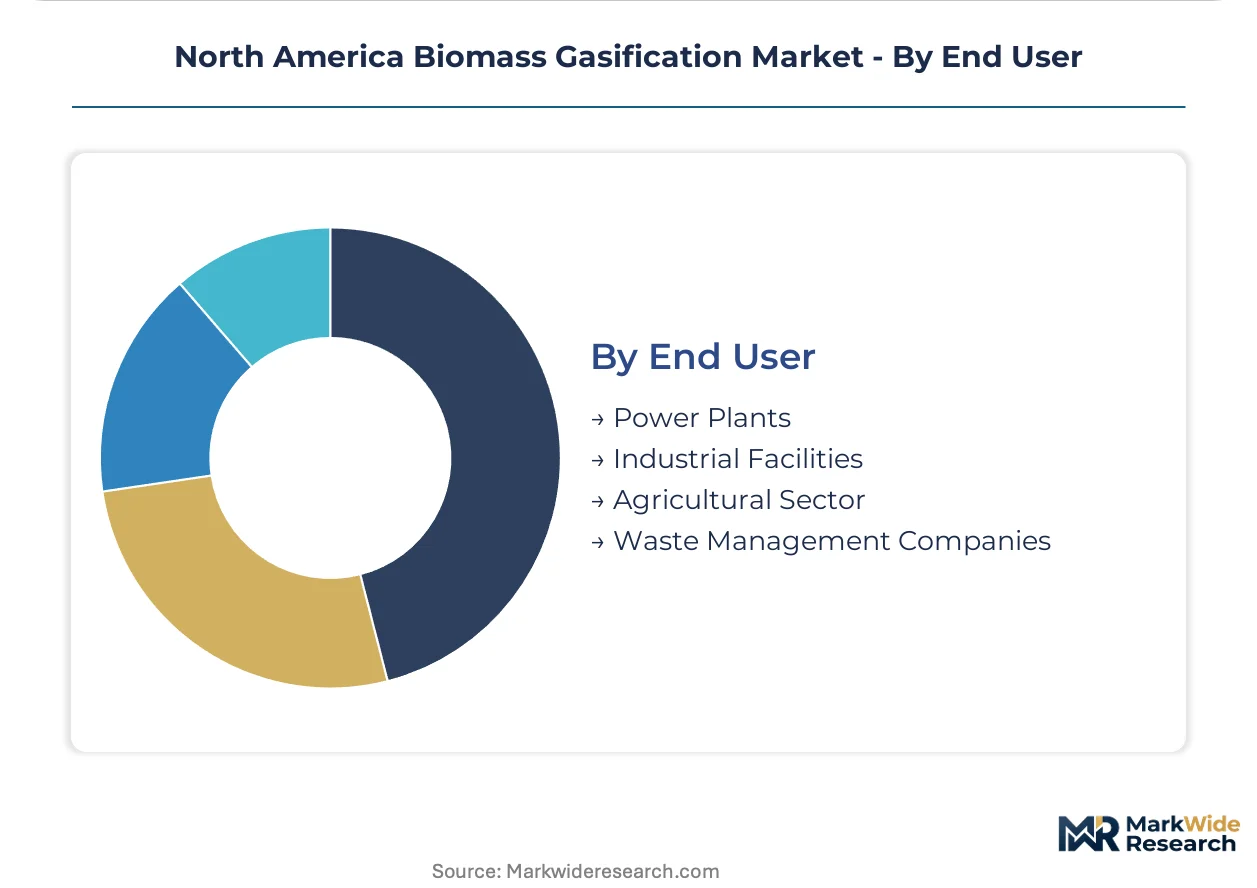
End User:
Customer sophistication and offtake contract duration vary across utility, industrial, and agricultural procurement desks.
- Power Plants:Investor-owned utilities and independent power producers seek baseload renewable capacity. Duke Energy and Southern Company procurement teams evaluate biomass gasification against solar-plus-storage bids in regulated Southeast markets.
- Industrial Facilities:Pulp and paper, cement, and steel producers pursue on-site syngas for process heat. Georgia-Pacific and International Paper mill complexes in Georgia and Mississippi cluster feedstock procurement within 50-mile radii.
- Agricultural Sector:Cooperatives and large integrated operations deploy small-scale systems for energy cost hedging. Iowa and Illinois farm operations select downdraft gasifiers where grid interconnection costs exceed $500 per kW.
- Waste Management Companies:Landfill operators and municipal utilities pursue gasification as diversion compliance tightens. Waste Management Inc. and Republic Services evaluate plasma arc systems for California MSW streams facing export restrictions.
Power plants account for the majority of contracted capacity; waste management companies are expanding their development pipelines fastest as landfill regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in the U.S. Southeast while consumption spreads across utility procurement desks in California and New York. Feedstock supply chains anchor gasification capacity near Georgia and Mississippi pulp mills, yet interconnection queues delay project completion in high-demand coastal markets.
United States
Duke Energy and Southern Company procurement teams evaluate biomass gasification against solar-plus-storage bids in regulated Southeast markets. EPA Renewable Fuel Standard mandates anchor project finance for syngas-to-liquid pathways. Georgia and Mississippi processing hubs concentrate pulp mill residue supply within 50-mile collection radii.
Canada
Provincial utilities in British Columbia and Ontario seek baseload renewable capacity to displace coal-fired generation. Natural Resources Canada administers funding programs that de-risk first-of-a-kind gasification installations. Forest product clusters around Vancouver and Thunder Bay anchor wood chip supply contracts with 20-year escalators.
Mexico
Industrial process heat demand from cement and steel producers drives pilot project interest in Nuevo León and Jalisco. Federal electricity commission interconnection standards shape project scale decisions for independent power producers. Agricultural residue collection networks in Sinaloa and Sonora supply pilot downdraft installations for rural electrification.
North America Biomass Gasification Market Key Industry Players
Top-tier vendors anchor utility-scale reactor supply, while regional fabricators occupy distributed installation niches. The vendor base stratifies across three tiers: integrated power equipment conglomerates, specialized reactor engineering houses, and feedstock preprocessing specialists. Strategic archetypes include turbine-integrated platform providers, bubbling fluidized bed designers, and agricultural residue handling specialists. Competitive moves concentrate on long-term service contracts bundling uptime guarantees with remote monitoring, plus geographic clustering around Southeast feedstock hubs.
Within the turbine-integrated tier, Mitsubishi Power represents combined-cycle biomass gasification anchoring across the U.S. Southeast. Among specialized reactor engineering houses, Babcock & Wilcox Enterprises exemplifies bubbling fluidized bed design dominance for industrial-scale installations. Andritz AG occupies a position within feedstock preprocessing specialization, handling high-moisture agricultural residues.
| Leading Market Players |
|---|
| Mitsubishi Power |
| Andritz AG |
| Siemens Energy |
| Biomass Engineering & Equipment |
| EQTEC plc |
| Babcock & Wilcox Enterprises |
| Nexterra Systems Corp |
| Thyssenkrupp AG |
| Valmet Corporation |
| Others |
Cost & Logistics Intelligence
Fluidized bed reactor maturation across the U.S. Southeast is compressing unit capital costs while concentrating procurement leverage among Georgia and Mississippi engineering hubs. This technology shift simultaneously expands feedstock flexibility and anchors pricing power with integrated service platforms bundling reactor uptime guarantees.
Pricing Analysis
Margin tightening in utility-scale installations reflects tariff-driven pressure vessel import duties and multi-stage syngas conditioning energy losses. Three-tier pricing structure across premium, standard, and economy levels separates turbine-integrated combined-cycle projects from standalone bubbling fluidized bed units and small-scale downdraft agricultural systems. Price differentiation hinges on carbon conversion efficiency guarantees and remote monitoring analytics bundling. Independent power producers exhibit highest price sensitivity due to interconnection queue delays stretching project finance timelines.
Supply Chain Analysis
Domestic-content requirements under the EPA's Renewable Fuel Standard and Buy American provisions are reshaping sourcing patterns for pressure vessels and gas cleanup trains. Manufacturing concentrates in the United States, Germany, and Japan for specialized reactor components and ceramic hot-gas filtration systems. Feedstock procurement draws from pulp mill residue networks in Georgia and Mississippi, corn stover collection infrastructure in Iowa and Nebraska, and wood chip supply contracts across the Pacific Northwest. Tariff exposure on non-dominated equipment imports creates single-source vulnerability for front-end engineering. Distribution runs through integrated service platforms bundling reactor supply with long-term O&M contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized gasification engineer scarcity—fewer than 50 North American university graduates annually—props project development pricing and extends delivery timelines across the U.S. Southeast and Midwest.
For Market Incumbents: To counter emerging plasma arc technology pilots in Texas and Louisiana petrochemical corridors, Babcock & Wilcox Enterprises and Mitsubishi Power should anchor fluidized bed reactor market share through backward integration into feedstock preprocessing systems and captive remote monitoring platform development. Certification investment in EPA Maximum Achievable Control Technology compliance ahead of pending hazardous air pollutant standards will lock out smaller fabricators. For New Entrants and Emerging Players: The IRA's Section 45V clean hydrogen production tax credits in the United States open a window for Fischer-Tropsch synthesis pathway development targeting California LCFS credit stacking. Agricultural residue gasification in Iowa and Illinois presents the most penetrable white space, where grid interconnection costs exceeding $500 per kW strand utility-scale competitors. A cooperative procurement model bundling downdraft units with farm-level energy cost hedging contracts offers direct go-to-market traction. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by power equipment conglomerates seeking turbine integration capabilities and by waste management companies pursuing landfill diversion compliance. Long-term viability favors platforms with demonstrated 95% reactor availability guarantees and established 20-year power purchase agreement track records. The signal to watch is California's LCFS credit price trajectory, which would reclassify biofuel production economics across woody biomass pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor Uptime Guarantee Platform | Mitsubishi Power bundles remote monitoring analytics with 95% availability contracts to anchor Southeast utility procurement. |
| Feedstock Preprocessing Integration | Andritz AG's high-moisture agricultural residue systems reduce delivered cost structures for Midwest corn stover projects. |
| Carbon Capture Co-Development | State-level renewable portfolio standards in California and New York compress timelines for biomass gasification plus CCS convergence. |
| Long-Term Power Purchase Agreement | Pacific Northwest independent power producers bundle 20-year contracts with renewable energy certificate streams to attract institutional capital. |
| Plasma Arc Hazardous Waste Co-Processing | Texas and Louisiana industrial clusters pilot electric arc systems for complete tar destruction despite capital cost premiums. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists across the United States and Canada. EPA Renewable Fuel Standard compliance databases, FERC interconnection queue filings, EIA power generation statistics, and USDA Biorefinery Assistance Program loan guarantee records provided segmentation validation. Bottom-up project pipeline enumeration and top-down utility procurement forecast reconciliation ensured coverage consistency.
Data-stream reconciliation across technology deployment, feedstock procurement, and application revenue models shaped the analytical framework. Segmentation dimensions spanned reactor configuration, feedstock type, end-use application, and regional regulatory framework across the analysis window. CAGRs derived from installed capacity buildout trajectories and power purchase agreement pricing escalators incorporated natural gas price volatility scenarios and interconnection queue delay assumptions.
The model assumes a particular technology adoption path; alternative pathways for plasma arc gasification achieving cost parity with fluidized bed systems would alter the outlook. Forecasts reflect assumptions regarding EPA emissions threshold enforcement timing and state-level renewable portfolio standard target revisions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Biomass Gasification Market