
 Biomass Pellets Market | 2026-2036
Biomass Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Pellets Market Analysis
ENplus A1 certification is reorganizing procurement standards across European industrial buyers. Enviva leverages its port-terminal network to dominate transatlantic supply chains. Drax Group anchors its position through backward integration into sustainable forestry partnerships. Pacific BioEnergy Corporation differentiates via dedicated rail-loading infrastructure on Canada's west coast.
Biomass pellets are compressed cylindrical fuel units, typically six to eight millimeters in diameter and ten to thirty millimeters in length, manufactured through densification of lignocellulosic material under high pressure and temperature. They serve as a direct combustion substitute for coal in power generation and heating systems, offering standardized energy density and reduced particulate emissions relative to raw biomass. Wood feedstock occupies the largest margin pool due to established supply chains and consistent calorific value, while agricultural residues represent the fastest-expanding category as straw and husk collection systems improve. Power generation applications lead volume offtake, though residential heating sustains premium pricing in Nordic and Alpine markets where district heating networks integrate pellet-fired boilers.
The EU Green Deal and F-Gas Regulation shape product standards and carbon accounting methodologies for biomass pellets entering European power stations. The US EPA enforces renewable fuel pathway qualifications under the Renewable Fuel Standard, while Health Canada and the PMRA coordinate sustainable harvesting certifications for export-grade wood pellets. Stakeholders must monitor evolving sustainability certification requirements and carbon border adjustment mechanisms to secure long-term offtake contracts.
Market Dynamics
The EU Green Deal's tightening emission benchmarks are forcing power generation utilities to restructure fuel procurement, with carbon border adjustment mechanisms now determining contract tenures and supplier eligibility across European industrial buyers.
Growth Catalysts
- EU Green Deal benchmarks:The tightening emission standards are mandating coal-to-biomass conversions in continental power stations, creating guaranteed offtake volumes for certified pellet suppliers.
- Straw and husk collection systems:Agricultural residue densification technology is unlocking feedstock pools previously stranded by logistical constraints, expanding addressable raw material supply.
- German district heating networks:Municipal utilities in Bavaria and Baden-Württemberg are retrofitting coal boilers for pellet combustion, anchoring residential heating demand.
Market Restraints
- Wood fiber input volatility:Sawmill residue availability fluctuates with construction cycles, compressing margin predictability for producers without captive forestry assets.
- Transatlantic shipping concentration:Port terminal capacity at Wilmington and Baton Rouge creates bottleneck risk for European buyers dependent on US Atlantic supply.
- Natural gas price normalization:The return of competitive gas pricing in Northwest Europe is reviving fuel-switching arbitrage that erodes pellet burn economics.
Strategic Opportunities
- Japan's feed-in tariff regime:METI's renewable energy procurement auctions are opening long-term power purchase agreements for imported biomass pellets.
- Black pellet torrefaction:The convergence of pyrolysis preprocessing with conventional densification is producing hydrophobic fuel with coal-equivalent grindability.
- Industrial heat applications:Cement and steel producers in Poland and the Czech Republic are piloting pellet-fired calcination as Scope 3 reduction pathways.
Industry Challenges
- ENplus certification timelines:Laboratory testing backlogs and auditor capacity constraints are delaying facility approvals, freezing export eligibility for new market entrants.
- Legacy coal handling infrastructure:European power stations require pneumatic conveying system retrofits to prevent pellet degradation, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Pellets Market |
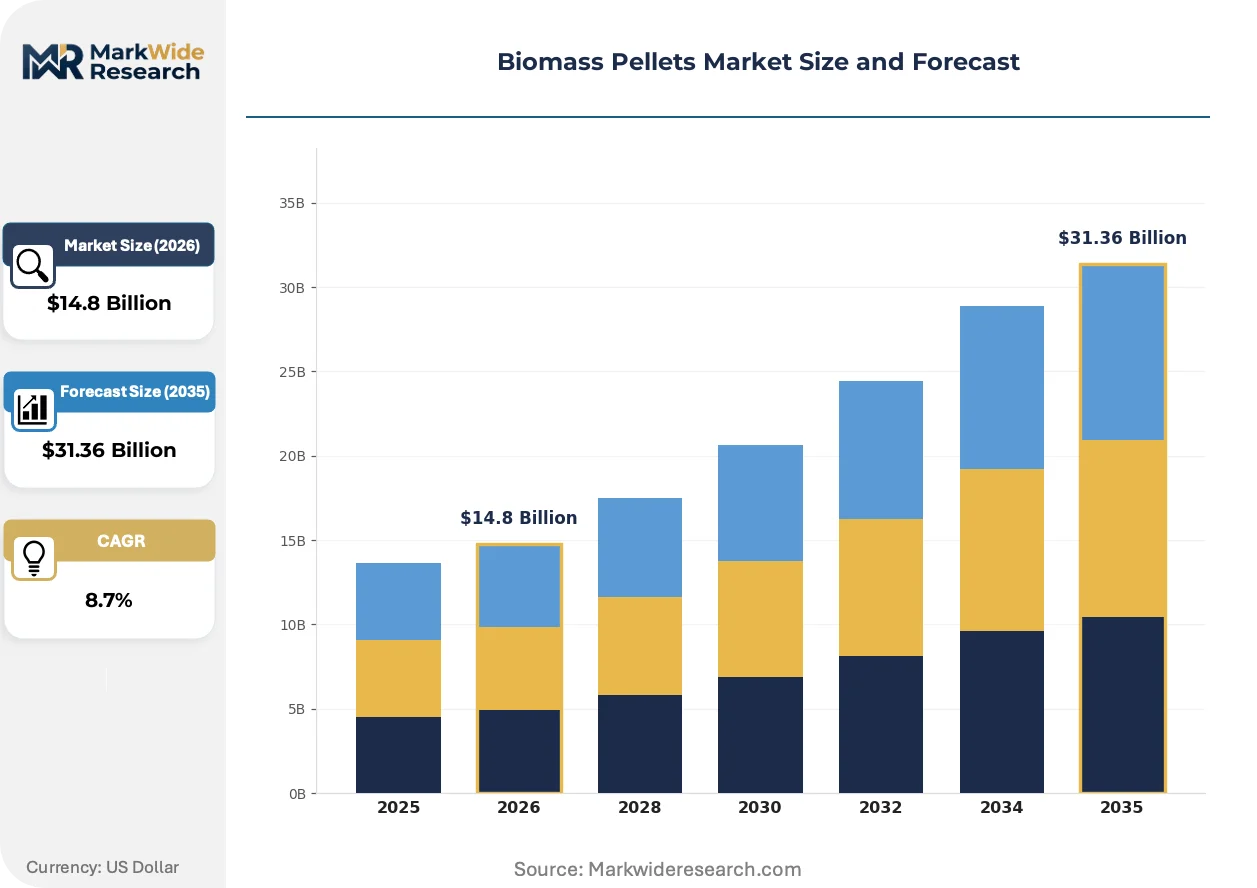
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Wood, Agricultural Residues, Energy Crops, Organic Waste Application: Heating, Power Generation, Industrial Use, Residential Distribution Channel: Direct Sales, Online Retail, Wholesale, Commercial Product Form: Pellets, Briquettes, Chunks, Fine Powder |
| Companies Covered | Premium Pellet Ltd., Biomass Secure Power Inc., Enviva, CPM, Pacific BioEnergy Corporation, Drax Group, BIOMAC Energy Ltd, Yulong Gattuwala Machine, Pinnacle Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Pellets Market Emerging Trajectories
Torrefaction preprocessing and automated pellet sorting are compressing quality variance and enabling new industrial heat applications. Regulatory carbon accounting methodologies are rewriting procurement criteria, while buyer consolidation is restructuring contract negotiation leverage.
Torrefied black pellet production is supplanting conventional white pellets in co-firing applications above twenty percent thermal substitution rates. Drax and European utilities with high coal-retrofit exposure are adopting torrefied material to eliminate on-site storage degradation. The technology is supplanting moisture-sensitive supply chains in Nordic and Baltic markets where outdoor storage dominates.
The EU's F-Gas Regulation and delegated acts under the Renewable Energy Directive are tightening lifecycle carbon intensity thresholds for biomass eligibility. Industrial buyers must now document supply chain emissions through mass-balance certification. Power generators in the Netherlands and Denmark are responding by sourcing exclusively from boreal forests with documented carbon payback periods under twenty years.
Long-term offtake agreements are displacing spot market procurement as utilities seek supply security ahead of carbon border adjustment implementation. Industrial buyers in Germany and Sweden are locking in five-to-ten-year contracts with indexed pricing. This shift is most visible in district heating cooperatives where fuel cost pass-through mechanisms require multi-year budget predictability.
Biomass Pellets Market Segmentation
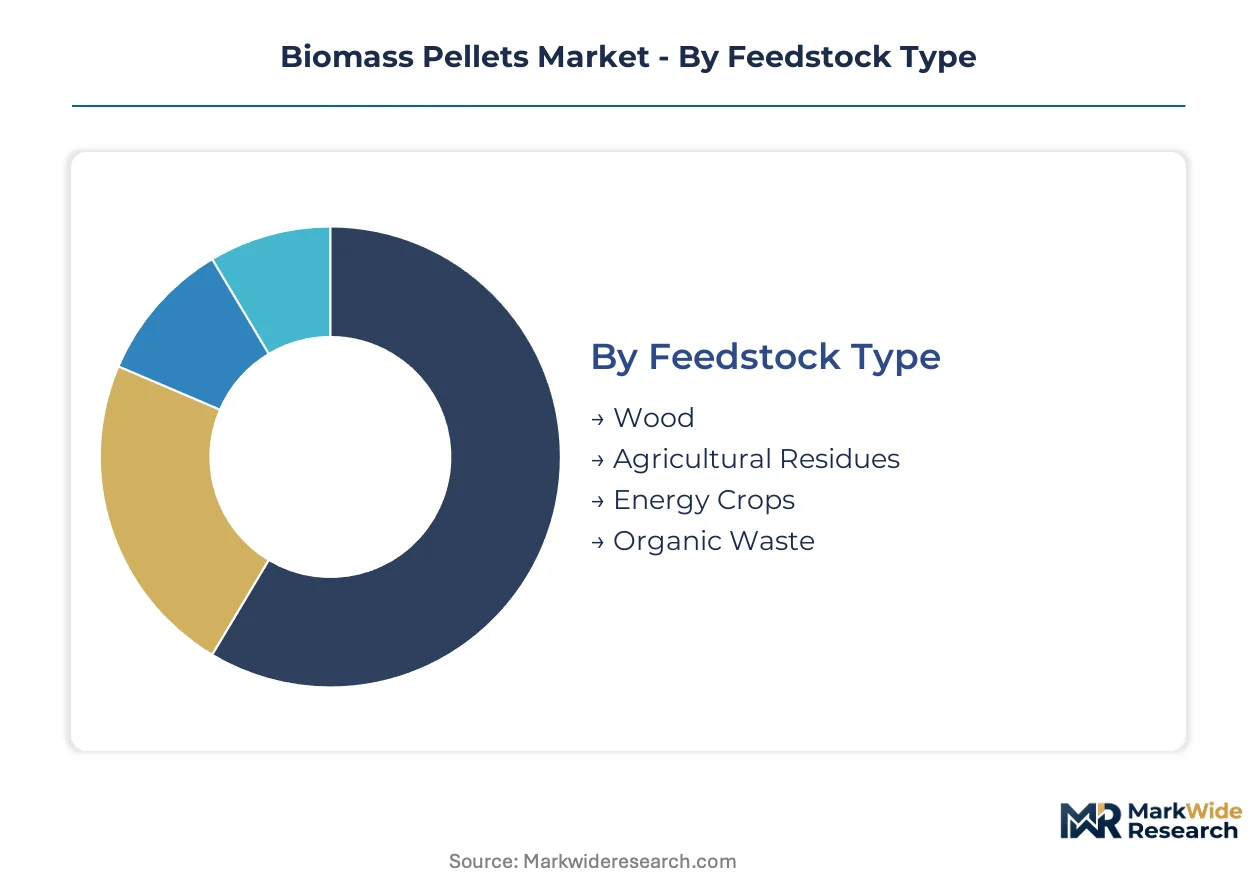
Feedstock chemistry and combustion specifications determine contract eligibility for power utilities. Application requirements drive certification tiers and pricing stratification across procurement channels.
Feedstock Type:
Wood feedstock flows through established port-terminal networks to European utilities, while agricultural residues access district heating cooperatives via regional collection hubs.
- Wood:Softwood and hardwood residues deliver consistent calorific value above 17 MJ/kg with ash content below 0.7 percent. Drax Group and RWE anchor procurement in Germany and the Netherlands, prioritizing ENplus A1 certification for coal retrofit compatibility. Fiber supply volatility from construction cycles compresses margin predictability for non-integrated producers.
- Agricultural Residues:Straw, rice husk, and corn stover require densification preprocessing to achieve combustion-grade density. Bavarian and Baden-Württemberg municipal utilities pilot straw pellet cofiring, though collection system fragmentation constrains scale-up beyond 50,000 tonnes annually.
- Energy Crops:Dedicated miscanthus and switchgrass cultivation in Poland and Ukraine targets industrial heat contracts.
- Organic Waste:Food processing residues and manure digestate serve localized biogas-integrated heating in Nordic cooperatives.
By volume, Wood leads. By growth pace, Agricultural Residues is expanding most quickly.
Application:
Power generation contracts command bulk volume with standardized quality tiers, while residential heating sustains premium pricing through distributor markups.
- Power Generation:Utility-scale cofiring and dedicated biomass plants require grindability matching coal handling systems. Torrefied black pellets penetrate this segment above 20 percent thermal substitution rates, with Drax and Ørsted locking five-to-ten-year offtake agreements ahead of carbon border adjustment implementation.
- Heating:District heating networks in Sweden, Finland, and Austria integrate pellet-fired boilers with seasonal storage. German municipal utilities in Bavaria retrofit coal infrastructure, creating guaranteed demand basins for certified suppliers.
- Industrial Use:Cement and steel calcination pilots in Poland and the Czech Republic test pellet-fired process heat.
- Residential:Bagged pellet retail through agricultural cooperatives dominates Alpine and Nordic markets.
Power Generation captures the largest revenue pool. Residential commands the steepest margin premium.
Distribution Channel:
Direct sales concentrate among utilities with long-term procurement desks, while wholesale intermediaries aggregate fragmented residential demand.
- Direct Sales:Enviva and Pacific BioEnergy contract directly with RWE, Vattenfall, and Tokyo Electric Power through port-terminal offtake agreements. These arrangements bypass intermediary margins but require documented sustainability certification and mass-balance carbon accounting.
- Wholesale:Regional distributors in Germany and France aggregate 15-25 kilogram bagged volumes for heating cooperatives and agricultural retailers. Inventory financing constraints limit wholesaler participation in spot markets.
- Online Retail:E-commerce platforms penetrate consumer heating segments with palletized delivery.
- Commercial:Industrial procurement desks source torrefied grades through specialized traders.
Direct Sales dominates contract value. Wholesale channels are gaining share fastest in residential heating.
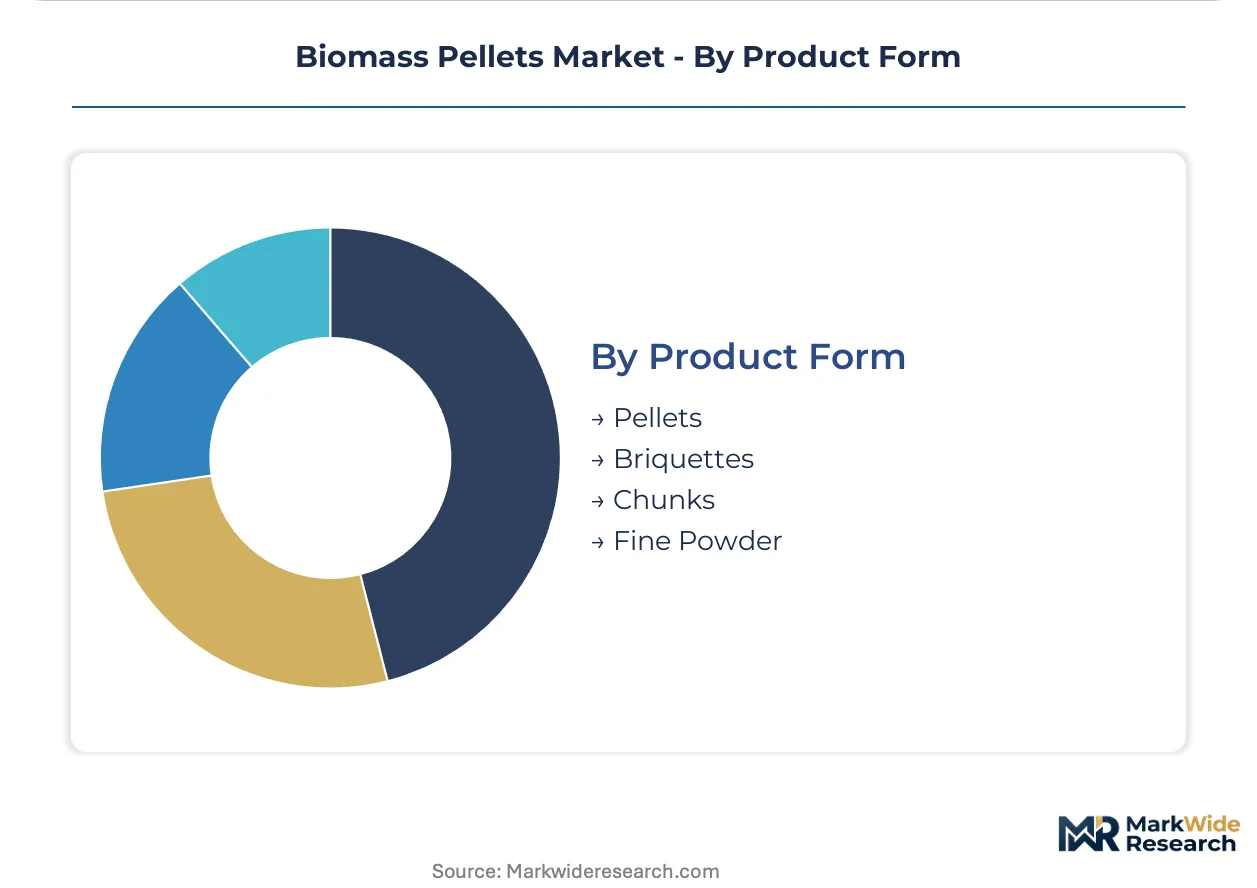
Product Form:
Pellet geometry determines pneumatic conveying compatibility and storage degradation risk in utility infrastructure.
- Pellets:Standardized six-to-eight millimeter diameter cylinders enable direct coal handling system retrofit with minimal pneumatic conveying modification. European utilities specify ENplus or DINplus certification, with durability indices above 97 percent preventing transport attrition.
- Briquettes:Larger fifty-to-one-hundred millimeter blocks serve manual-feed residential boilers and industrial stoker grates. Higher bulk density reduces storage footprint for Nordic outdoor storage installations.
- Chunks:Unprocessed wood chips retain moisture sensitivity, limiting utility uptake.
- Fine Powder:Torrefaction byproducts and pulverized residues target specialized cofiring applications.
Pellets lead by installed base. Briquettes are climbing the fastest in residential retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port-terminal infrastructure clusters along the US Atlantic seaboard and Canada's Pacific coast anchor transatlantic supply chains. European utilities source predominantly from Germany, Sweden, and the Baltic states, while Asian demand concentrates in Japanese power auctions and Korean industrial heat contracts.
Germany
RWE and municipal utilities in Bavaria drive coal-to-biomass retrofit demand through district heating networks. The EU Green Deal's delegated acts under the Renewable Energy Directive mandate mass-balance carbon accounting for imported pellets. The Port of Hamburg anchors North European import logistics, with storage facilities expanding to handle torrefied black pellet volumes.
United States
Southeastern pellet producers supply Drax Group and European utilities via Wilmington and Baton Rouge terminals. EPA renewable fuel pathway qualifications under the Renewable Fuel Standard govern export-grade certification. The Virginia-North Carolina forestry belt concentrates wood fiber processing capacity for transatlantic shipment.
Japan
Tokyo Electric Power and regional utilities procure imported pellets through METI's feed-in tariff renewable energy auctions. The country's national energy regulator enforces sustainability documentation for biomass eligibility in power purchase agreements. The Chubu/Nagoya industrial corridor hosts cofiring pilot programs at cement and steel facilities.
Canada
British Columbia's Pacific BioEnergy and Alberta producers export via Vancouver port terminals to Asian and European buyers. Health Canada and the PMRA coordinate sustainable harvesting certifications for export-grade wood pellets. The Prince George forestry cluster densifies sawmill residues into ENplus-certified supply for Japanese utility contracts.
Sweden
Vattenfall and municipal district heating networks sustain premium pricing for residential and industrial pellet combustion. The EU F-Gas Regulation shapes product standards for Nordic outdoor storage installations. The Stockholm-Mälaren Valley integrates pellet-fired boilers with seasonal thermal storage systems.
Biomass Pellets Market Vendor Landscape
Concentration sits with integrated producers controlling captive forestry assets and port-terminal networks. The supplier base stratifies between large-scale exporters with transatlantic logistics dominance and regional densification specialists serving district heating cooperatives. Two archetypes predominate: vertically integrated energy companies with backward integration into sustainable forestry, and independent pellet producers leveraging dedicated rail-loading infrastructure. Capacity expansion and long-term offtake agreement structuring constitute the dominant competitive moves.
Among North American integrated suppliers, Enviva and Drax Group exemplify the port-terminal network archetype, while Pacific BioEnergy Corporation represents the rail-loading infrastructure specialization. These three entities anchor distinct supply chain configurations for European and Asian utility procurement.
| Leading Market Players |
|---|
| Premium Pellet Ltd. |
| Biomass Secure Power Inc. |
| Enviva |
| CPM |
| Pacific BioEnergy Corporation |
| Drax Group |
| BIOMAC Energy Ltd |
| Yulong Gattuwala Machine |
| Pinnacle Renewable Energy |
| Others |
Supply Flow & Price Mechanics
Coal-to-biomass substitution in European power stations simultaneously redraws supply geography toward Atlantic port terminals and compresses pricing premiums for ENplus-certified material. This dual restructuring rewards producers with captive forestry assets while penalizing spot-market-dependent competitors.
Pricing Analysis
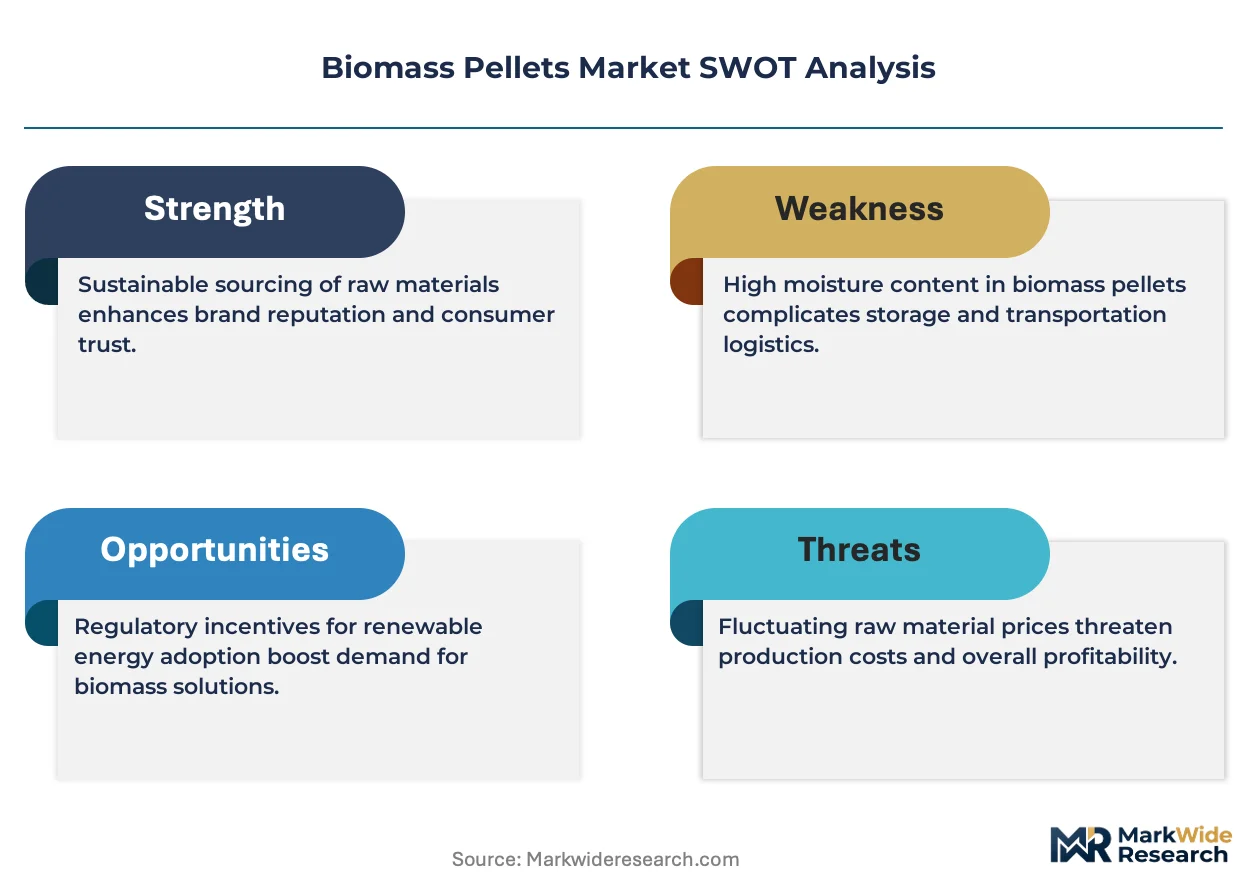
The EU Green Deal dictates the pricing tier structure across European procurement desks, separating ENplus A1-certified supply from uncertified material. Contract-based long-term offtake dominates, with price differentiation driven by certification grade and volume scale. Cost compression in standard-tier pellets is intensifying because natural gas price normalization revives fuel-switching arbitrage. District heating cooperatives exhibit highest price sensitivity due to pass-through mechanism constraints, while Japanese utilities under METI auctions show lowest sensitivity.
Supply Chain Analysis
The United States and Canada anchor wood pellet densification, with British Columbia's rail-loading infrastructure feeding Asian contracts and Southeastern US terminals serving European buyers. Fiber supply draws from sawmill residues, forest thinning, and agricultural straw collection. Single-source vulnerability concentrates at Wilmington and Baton Rouge port terminals. Distribution runs through direct utility contracts and wholesale bagged channels for residential heating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified pellet supply scarcity—particularly torrefied black pellet production capacity—determines competitive positioning across European and Asian procurement desks. Producers with documented carbon accounting and port-terminal access command disproportionate contract flow.
For Market Incumbents: Secure ENplus A1 certification renewals ahead of auditor capacity constraints, and extend backward integration into boreal forestry partnerships to offset sawmill residue volatility. Drax Group's sourcing model demonstrates how captive fiber supply insulates margins against construction-cycle fluctuations. For New Entrants and Emerging Players: ENplus certification fast-track through Baltic laboratory partnerships opens entry into German district heating retrofits. Agricultural residue densification in Poland and Ukraine represents the most penetrable white-space, with straw pellet cofiring pilots creating guaranteed offtake basins for regional collection system operators. For Investors and Strategic Acquirers: Carbon border adjustment implementation reshapes the acquisition landscape toward producers with mass-balance certification infrastructure. Five-to-ten-year viability favors rail-terminal integrated assets over pure-play densification facilities. Watch Japanese feed-in tariff auction participation rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Torrefaction Capacity Buildout | Drax and European utilities adopt black pellets to eliminate storage degradation in Nordic outdoor installations. |
| Backward Integration into Forestry | Enviva's port-terminal network pairs with sustainable harvesting partnerships to secure long-term fiber supply. |
| ENplus Certification Program | Pacific BioEnergy's dedicated rail-loading infrastructure leverages A1 certification for Japanese utility contracts. |
| Long-term Supply Agreement | German municipal utilities lock five-to-ten-year indexed contracts ahead of carbon border adjustment enforcement. |
| Joint Venture in Agricultural Residue | Bavarian cooperatives pilot straw pellet cofiring with regional collection hub aggregation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA pellet export data, EU customs records, IEA bioenergy reports, and FERC infrastructure filings. Utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists provided demand-side validation. Bottom-up densification capacity counts triangulate against top-down utility procurement forecasts.
Segmentation dimensions modeled include feedstock chemistry, application requirements, distribution channel structure, and product form specifications across the projection horizon. CAGRs derive from facility expansion announcements, offtake contract tenures, and regulatory milestone implementation schedules. Torrefaction technology adoption curves and carbon accounting methodology evolution constitute biomass-specific forecast inputs.
Underlying assumptions cover EU Green Deal delegated act enforcement, natural gas price normalization trajectories, and ENplus auditor capacity expansion, with deviation risk concentrated in transatlantic shipping rate volatility and Japanese auction participation shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Gasifier Market