
 Modular Biomass Power Plant Market | 2026-2036
Modular Biomass Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Biomass Power Plant Market Foresight
Finnish engineering clusters is realigning around standardized gasification skids for decentralized heat-and-power networks. Valmet leverages its pulp-and-paper equipment heritage to anchor biomass boiler module production in Northern Europe. Andritz AG competes through hydropower-to-biomass technology transfer, sustaining cross-sector manufacturing scale. Siemens Energy AG specializes in gas turbine integration for hybrid biomass configurations, differentiating on grid-stability services.
A modular biomass power plant comprises prefabricated subsystems—fuel handling, combustion or gasification reactor, emissions control, and power generation—typically rated between 0.5 and 20 MWe, designed for rapid site assembly and feedstock flexibility. The primary purpose is to convert lignocellulosic or organic waste streams into dispatchable electricity and thermal energy for industrial or district heating applications. Combustion Systems dominate current installations due to proven reliability with wood chip and agricultural residue fuels. Gasification Systems represent the fastest-expanding category, as higher electrical efficiency and syngas cleaning advances unlock project finance in utility-scale deployments. Containerized Systems concentrate margin pools through factory acceptance testing and reduced site labor costs.
The EU Green Deal and F-Gas Regulation shape equipment standards and carbon accounting methodologies for biomass-to-energy assets across member states. EPA renewable fuel standards and state-level renewable portfolio obligations in the US mandate emission verification protocols that influence modular plant design choices. Stakeholders must monitor feedstock certification schemes and evolving carbon border adjustments that will determine project bankability and cross-border equipment procurement strategies.
Market Dynamics
Containerized gasification skids are compressing project development timelines from years to months, forcing incumbent combustion-system suppliers to retool manufacturing lines for factory-integrated reactor modules that ship with pre-validated emissions profiles.
Growth Catalysts
- EU Green Deal renewable energy directives:Germany's forestry residue processors face binding carbon-intensity targets that favor dispatchable biomass over intermittent wind and solar, accelerating procurement of 5-20 MWe modular units.
- District heating network feedstock flexibility mandates:Nordic municipal utilities require multi-fuel capability to hedge against wood chip price volatility, pulling containerized systems with automated fuel-switching controls.
- F-Gas Regulation phase-down schedules:Industrial heat users across EU member states must replace fluorinated refrigerants in thermal systems, redirecting capital toward biomass-powered absorption chilling and trigeneration configurations.
Market Restraints
- Stainless steel alloy cost volatility:Reactor vessel fabrication depends on nickel and chromium supply concentrated in Indonesian and South African mining operations, exposing project economics to commodity swings.
- Syngas tar cracking technical limitations:Gasification systems below 10 MWe struggle to achieve the residence times and temperature uniformity needed for complete hydrocarbon conversion, elevating maintenance frequency.
- EPA renewable fuel standard verification friction:US developers face multi-year pathway approval timelines for novel feedstocks, delaying project finance close on agricultural residue proposals.
Strategic Opportunities
- Polish district heating privatization wave:Municipal heat asset divestitures create greenfield sites for 2-10 MWe biomass CHP without legacy coal retrofit constraints.
- Hybrid biomass-battery configurations:Grid operators in frequency-constrained networks value synchronous inertia from biomass turbines paired with lithium-ion smoothing, opening utility-scale tenders.
- Outcome-based thermal service contracts:Industrial off-takers in pulp-and-paper verticals shift from equipment purchase to heat-rate-guaranteed operating agreements, transferring fuel risk to plant operators.
Industry Challenges
- Gasification control systems integration complexity:Project developers struggle to synchronize plasma torch ignitors, ceramic filter banks, and gas engine governors within single SCADA architectures.
- Feedstock certification timeline compression:ISCC and SBP scheme auditors face backlogs for forest residue chain-of-custody validation, stalling construction starts on sustainability-linked debt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Biomass Power Plant Market |
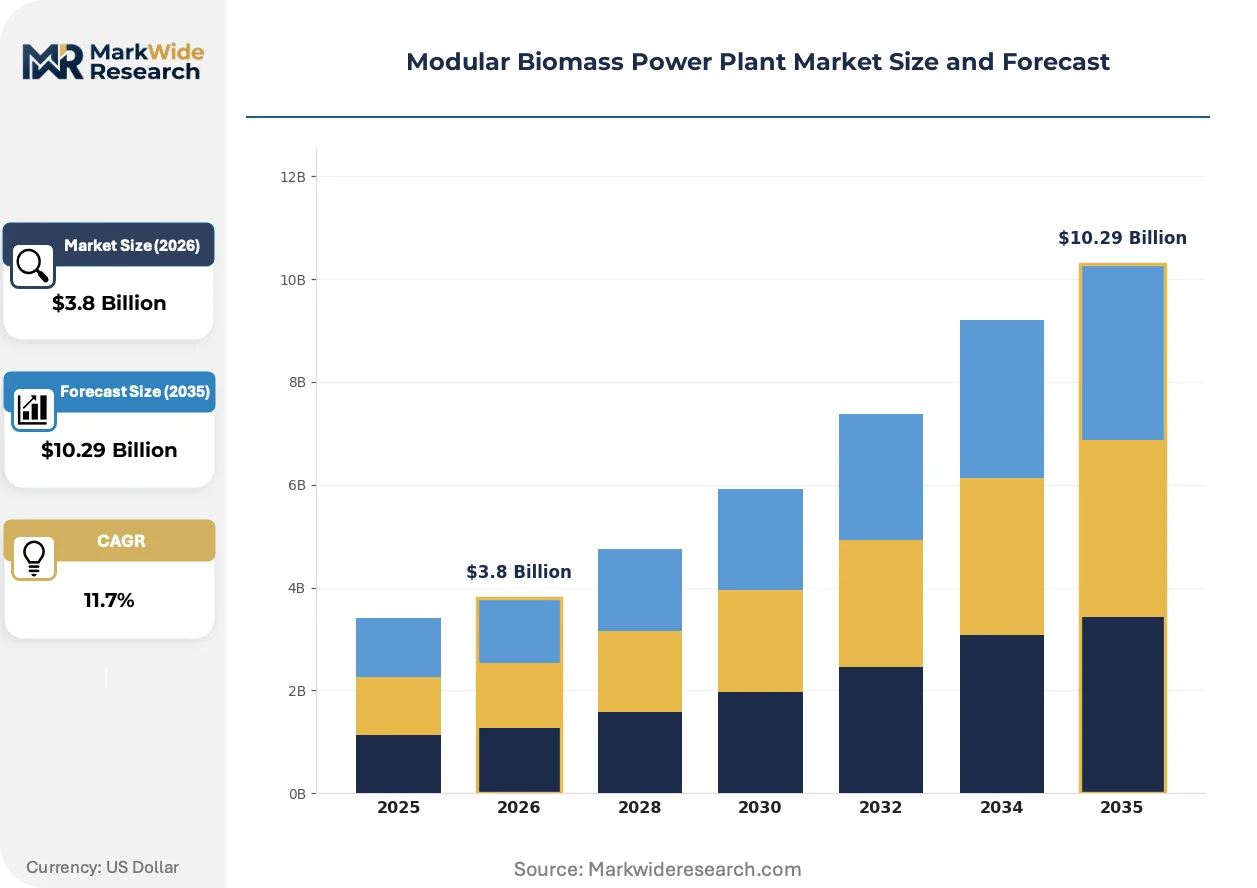
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasification Systems, Combustion Systems, Anaerobic Digesters, Co-Firing Systems Technology: Biochemical Conversion, Thermal Conversion, Mechanical Conversion, Hybrid Systems End User: Utility Companies, Industrial Users, Commercial Users, Agriculture Sector Installation: Onsite Installations, Offsite Installations, Containerized Systems, Custom Installations |
| Companies Covered | Jamestown Energy, Valmet, bp Archaea Energy, Siemens Energy AG, Andritz AG, Greenleaf Power, EWP Renewable Corporation, Engie SA, GRU Deerhaven Renewable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Biomass Power Plant Market Shifts & Advancements
Standardization pressures are forcing reactor designers to sacrifice customization for interchangeability, while digital twins and remote monitoring compress commissioning curves and reshape after-sales revenue models.
Fluidized bed gasification is unifying the thermal treatment of herbaceous residues, demolition wood, and sewage sludge within single reactor platforms. German district heating cooperatives are adopting these multi-feed systems to secure supply continuity. The technology is unifying what were previously separate fuel-preprocessing supply chains into centralized fuel hub operations.
The EU F-Gas Regulation's stepped phase-down of hydrofluorocarbons is accelerating biomass absorption chiller deployments in industrial process cooling. Food processing facilities in the Netherlands and Denmark face retrofit deadlines that favor thermal-driven refrigeration over electric compression. Containerized biomass trigeneration packages are capturing share in sites with simultaneous heating, cooling, and power requirements.
Industrial off-takers are consolidating procurement authority for thermal assets under centralized energy management functions, displacing site-level engineering autonomy. Pulp mills and chemical processors in Finland and Sweden now specify modular biomass units through group-level framework agreements rather than individual plant tenders. This concentration is visible most acutely in the Nordic cluster, where district heating network operators pool equipment specifications to achieve volume pricing on standardized skid packages.
Modular Biomass Power Plant Market Segmentation
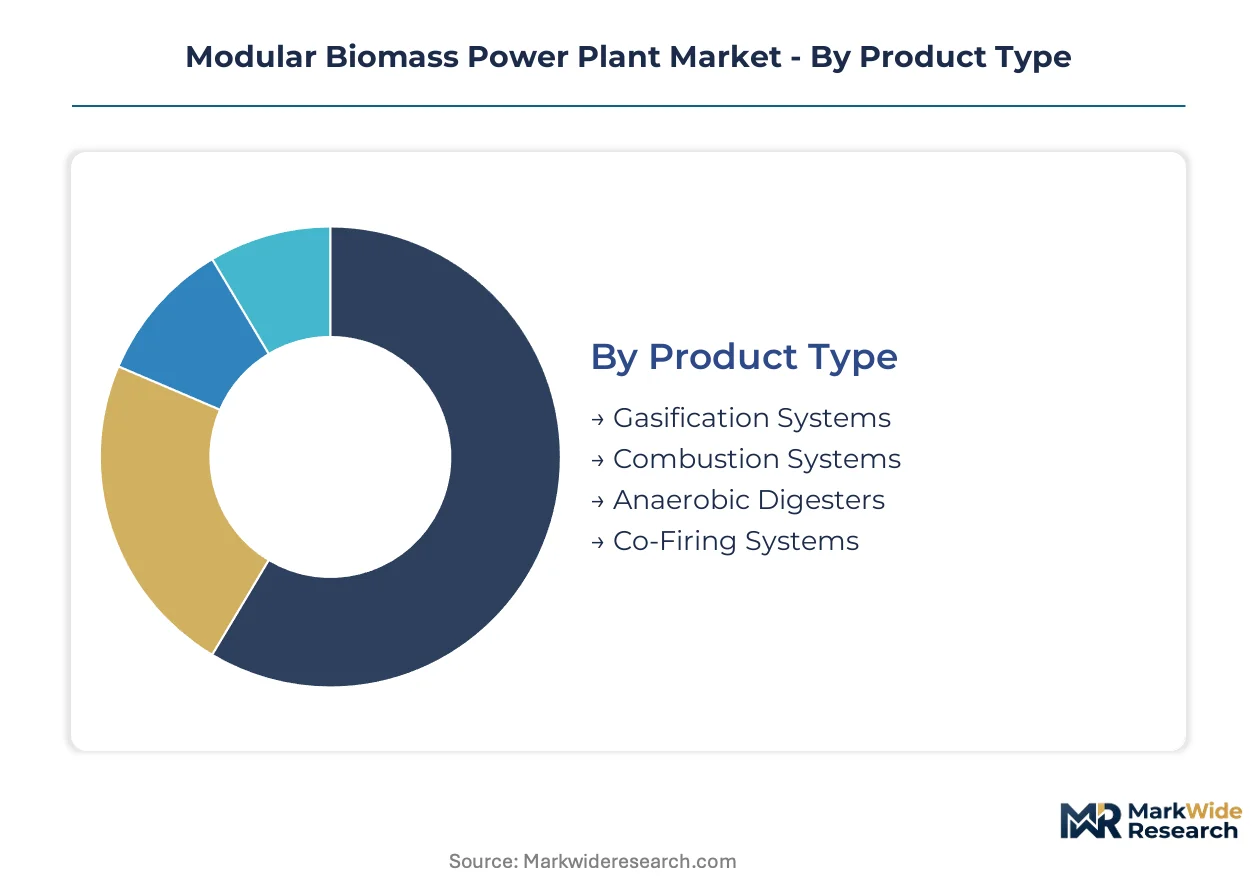
Technology selection in modular biomass plants hinges on feedstock chemistry, scale requirements, and local grid integration mandates. Procurement committees weigh thermal efficiency against fuel flexibility when specifying reactor configurations for district heating or industrial CHP applications.
Product Type:
Buyers prioritize electrical efficiency targets and syngas quality specifications when selecting reactor platforms for utility-scale deployment.
- Gasification Systems:Partial oxidation reactors convert lignocellulosic feedstocks into syngas for gas engines or turbine integration, achieving higher electrical efficiency than direct combustion. Finnish district heating cooperatives specify fluidized bed gasifiers to process mixed wood chips and agricultural residues under EU Green Deal carbon-intensity benchmarks.
- Combustion Systems:Grate-fired and fluidized bed boilers burn solid biomass directly to generate steam for turbines or thermal distribution. German forestry residue processors favor combustion for proven reliability in 5-20 MWe baseload configurations where grid stability services command premium tariffs.
- Anaerobic Digesters:Biological breakdown of wet organic wastes produces biogas for combined heat and power generation.
- Co-Firing Systems:Biomass injection retrofits existing coal plants to reduce carbon emissions intensity.
Volume sits with Combustion Systems; growth tilts toward Gasification Systems.
Technology:
Conversion pathway selection tracks feedstock moisture content, ash chemistry, and the target energy carrier—electricity, heat, or transport fuel.
- Thermal Conversion:High-temperature processes including pyrolysis, gasification, and direct combustion dominate woody biomass applications. Nordic municipal utilities deploy thermal routes for district heating networks requiring dispatchable output regardless of weather conditions.
- Biochemical Conversion:Enzymatic and microbial processes break down cellulosic feedstocks into fermentable sugars or biogas. Agricultural operations in the Netherlands specify anaerobic digestion for manure and food waste streams where moisture content exceeds thermal process thresholds.
- Mechanical Conversion:Physical densification through pelletization or briquetting upgrades low-density biomass for transport and storage.
- Hybrid Systems:Sequential thermal and biological stages maximize energy extraction from heterogeneous waste streams.
Deployment concentrates in Thermal Conversion; Biochemical Conversion climbs fastest where wet waste valorization incentives strengthen.
End User:
Off-taker risk profiles and offtake contract structures determine plant scale, automation level, and financing instrument selection.
- Utility Companies:Grid-connected operators procure 10-20 MWe units with synchronous inertia capabilities for frequency regulation services. Polish district heating privatization tenders specify biomass CHP to replace coal assets without network infrastructure overhaul.
- Industrial Users:Pulp mills and chemical processors seek captive thermal supply with fuel cost predictability. Finnish engineering clusters negotiate heat-rate-guaranteed operating agreements that transfer feedstock risk to plant operators.
- Commercial Users:Hotels, hospitals, and retail complexes install sub-5 MWe units for behind-the-meter supply.
- Agriculture Sector:Farm cooperatives deploy small-scale digesters and combustion units for self-consumption and grid export.
Procurement authority concentrates under Utility Companies; Industrial Users are expanding fastest through centralized energy management frameworks.
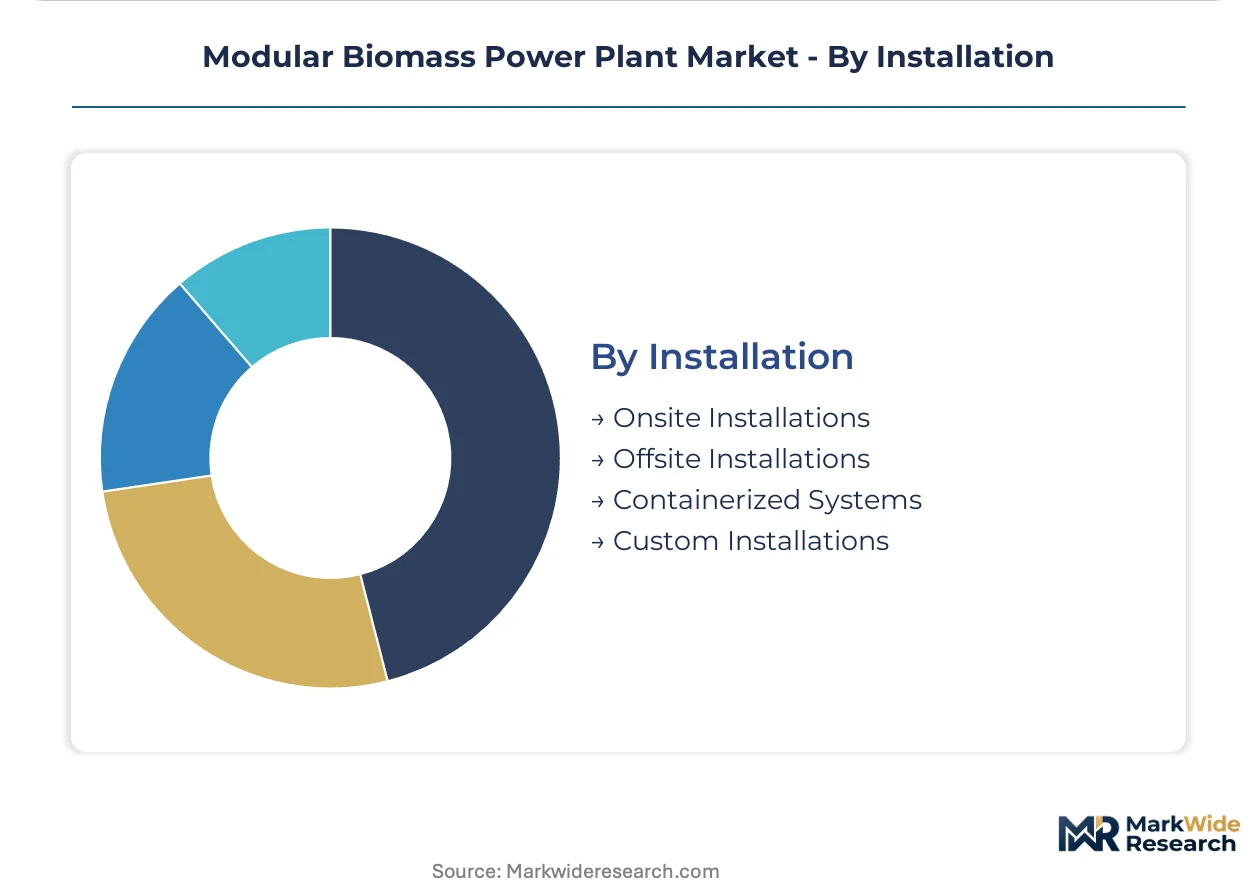
Installation:
Site constraints and labor cost differentials drive the shift toward factory-integrated delivery models.
- Containerized Systems:Pre-engineered skids with factory-accepted emissions profiles compress commissioning timelines from years to months. German district heating networks specify containerized gasification units to accelerate EU Green Deal compliance deadlines.
- Onsite Installations:Stick-built construction persists for large custom configurations where local content requirements or unusual site geometry prevent modular delivery.
- Offsite Installations:Remote fuel processing hubs pretreat biomass for transport to centralized generation facilities.
- Custom Installations:Bespoke engineering addresses unique feedstock blends or integration with legacy industrial heat systems.
Margin pools concentrate in Containerized Systems; Custom Installations retain share where retrofit complexity demands site-specific engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forestry residue deposits in the Nordic-Baltic corridor anchor procurement patterns for containerized gasification units. German agricultural clusters and Polish district heating networks pull equipment specifications toward multi-feed reactor platforms.
Germany
Baden-Württemberg engineering clusters source containerized systems for forestry residue processing under binding EU Green Deal carbon-intensity deadlines. The F-Gas Regulation's stepped phase-down redirects industrial heat capital toward biomass-powered absorption chilling configurations. Stuttgart-based fabricators concentrate procurement of 5-20 MWe modular units for district heating cooperatives.
Finland
Pulp mill energy managers in the Kymenlaakso region negotiate heat-rate-guaranteed operating agreements that transfer feedstock risk to plant operators. Finnish engineering clusters realign manufacturing around standardized gasification skids for decentralized heat-and-power networks. Tampere metropolitan utilities specify fluidized bed gasifiers to process mixed wood chips and agricultural residues.
Poland
Municipal heat asset divestitures in the Silesian and Lesser Poland voivodeships create greenfield sites for 2-10 MWe biomass CHP without legacy coal retrofit constraints. Polish district heating privatization tenders specify biomass CHP to replace coal assets without network infrastructure overhaul. Krakow-area operators pool equipment specifications to achieve volume pricing on standardized skid packages.
Sweden
Chemical processors in the Stenungsund industrial cluster shift thermal asset procurement authority under centralized energy management functions. Swedish district heating networks prioritize biomass feedstock flexibility mandates that hedge against wood chip price volatility. Gothenburg municipal utilities pull containerized systems with automated fuel-switching controls for multi-fuel capability.
United States
Agricultural residue processors in the Upper Midwest face multi-year EPA renewable fuel standard pathway approval timelines that delay project finance close. California industrial heat users navigate state-level renewable portfolio obligations that mandate emission verification protocols influencing modular plant design choices. Pacific Northwest forestry cooperatives evaluate hybrid biomass-battery configurations for frequency-constrained grid networks.
Modular Biomass Power Plant Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue containerized delivery models and hybrid system integration. The vendor base spans pulp-and-paper equipment heritage firms, hydropower-to-biomass technology transfer specialists, and gas turbine integrators. Three archetypes dominate: engineering conglomerates with cross-sector manufacturing scale, specialized reactor fabricators with factory-integrated delivery capabilities, and energy majors diversifying through renewable platform acquisitions. Competitive moves concentrate on strategic partnerships for feedstock hub development and technology licensing for rapid geographic expansion.
Within the engineering conglomerate tier, Valmet leverages Nordic pulp-and-paper equipment heritage to anchor biomass boiler module production, while Andritz AG competes through hydropower-to-biomass technology transfer sustaining cross-sector manufacturing scale. Siemens Energy AG represents the gas turbine integration archetype for hybrid biomass configurations. Among energy majors diversifying into renewable platforms, bp Archaea Energy occupies a position exemplifying the shift toward captive biogas and biomass assets. Engie SA anchors the utility-scale developer archetype with centralized procurement frameworks for industrial off-takers.
| Leading Market Players |
|---|
| Jamestown Energy |
| Valmet |
| bp Archaea Energy |
| Siemens Energy AG |
| Andritz AG |
| Greenleaf Power |
| EWP Renewable Corporation |
| Engie SA |
| GRU Deerhaven Renewable |
| Others |
Supply & Pricing Matrix
Nickel and chromium price indices on the London Metal Exchange cascade through reactor vessel fabrication costs, compressing margins for stainless steel-dependent gasification skids and forcing tiered pricing stratification between factory-integrated containerized systems and site-built custom configurations.
Pricing Analysis
Extended warranty and remote monitoring bundles separate premium-tier offerings from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels tracks factory acceptance testing rigor and feedstock flexibility guarantees. Cost compression in standard-tier combustion systems intensifies because Indonesian nickel supply volatility elevates alloy surcharges. Municipal utilities in Poland exhibit highest price sensitivity due to constrained privatization budgets, while Finnish pulp mills prioritize heat-rate guarantees over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Germany, Finland, and Poland maintain hub-and-spoke patterns for containerized skid delivery, with Stuttgart and Tampere anchoring Nordic-Baltic logistics networks. Reactor vessel fabrication draws from Indonesian nickel and South African chromium mining operations, while ceramic filter banks and plasma torch ignitors source from specialized German and Austrian component suppliers. Single-source vulnerability concentrates in nickel alloy supply chains subject to export restriction risk. Distribution runs through engineering conglomerate direct-sales channels and specialized EPC contractor networks for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around factory-integrated delivery capabilities as containerized gasification timelines compress from years to months, marginalizing stick-built combustion specialists lacking modular manufacturing scale.
For Market Incumbents: Deploy factory-integrated skid production in Northern European engineering clusters to match Valmet's pulp-and-paper heritage advantage. Incumbents must anchor standardized gasification platform output in Tampere or Stuttgart metropolitan zones to defend against Andritz AG's hydropower-to-biomass technology transfer. Backward integration into nickel alloy procurement hedges stainless steel cost volatility threatening project economics. For New Entrants and Emerging Players: Agricultural residue processors in the Upper Midwest face multi-year EPA pathway approval delays that strand conventional project finance. New entrants should target this verification-friction segment with novel feedstock pre-certification services bundled with modular plant deployment. Containerized trigeneration packages for Dutch food processing facilities facing F-Gas Regulation retrofit deadlines offer the most penetrable white-space entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized reactor fabricators with factory-integrated delivery capabilities in Polish district heating privatization zones. Long-term viability over the coming decade rests on feedstock hub development and technology licensing scale rather than equipment-only manufacturing. Watch ISCC and SBP certification auditor backlog resolution as the inflection signal for sustainability-linked debt availability.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Integrated Skid Manufacturing | Compresses commissioning timelines from years to months for German district heating cooperatives. |
| Hybrid Biomass-Battery Configuration Development | Captures utility-scale tenders from frequency-constrained grid operators in the Pacific Northwest. |
| Feedstock Hub Joint Ventures | Secures supply continuity for Nordic municipal utilities hedging wood chip price volatility. |
| Outcome-Based Thermal Service Contracts | Transfers feedstock risk to operators for Finnish pulp mill energy managers. |
| Plasma Torch Ignitor Technology Licensing | Accelerates geographic expansion for gasification control system specialists. |
Research Methodology
Independent corroboration across EIA biomass generation statistics, IEA renewable heat deployment databases, and FERC interconnection queue filings underwrites the qualitative findings. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists combined with secondary validation from EU Green Deal implementation reports, EPA renewable fuel standard pathway databases, and customs trade data. Bottom-up installation capacity modeling and top-down policy-driven demand triangulation anchor the analytical framework.
Rate-of-change decomposition across the analysis window segments volume and value by technology type, installation format, end-user category, and regional regulatory framework. Modeled dimensions include gasification versus combustion system share, containerized versus custom installation split, and utility versus industrial offtake concentration. CAGRs derive from feedstock availability projections and carbon-intensity target enforcement trajectories, with EU F-Gas Regulation phase-down schedules and state-level renewable portfolio obligations as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel alloy commodity volatility and ISCC certification auditor capacity constraints. Outputs reflect documented assumptions around EU Green Deal enforcement continuity and EPA pathway approval timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Energy Harvesting Trees Market