
 Energy Harvesting Trees Market | 2026-2036
Energy Harvesting Trees Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Harvesting Trees Market Analysis
The EU Green Deal is expanding eligibility for urban renewable micro-generation within municipal procurement frameworks. Sologic Ltd. leverages its integrated design-manufacture model to control project margins across European deployments. Solar Botanic specializes in biomimetic leaf architectures that optimize photovoltaic surface area within constrained urban footprints. Treelectric anchors its position through direct relationships with Scandinavian municipal energy cooperatives.
Energy harvesting trees combine photovoltaic, piezoelectric, and thermoelectric transduction elements within structural forms mimicking natural arboreal geometries, typically achieving rated outputs between 2.5 kW and 5 kW per unit depending on canopy span and insolation profile. Solar Trees currently lead installed capacity due to mature supply chains in crystalline silicon module production, while Hybrid Models represent the fastest-expanding category as developers integrate battery storage and IoT Integration to enable grid-independent operation. Piezoelectric Systems occupy a narrower niche serving vibration-rich environments such as transit corridors and industrial perimeters.
EMA efficiency standards and EU Green Deal implementation timelines shape product certification requirements for grid-interactive urban generation assets in Europe. REACH compliance governs material selection for piezoelectric ceramics and thermal substrates, while CE marking mandates govern electrical safety and electromagnetic compatibility for public-space installations. Stakeholders must monitor evolving national building codes that classify energy harvesting trees as either infrastructure or electrical equipment, since this determination dictates permitting pathways and interconnection tariffs.
Market Dynamics
The EU Green Deal's renewable energy directives are forcing municipalities to reclassify urban micro-generation assets as critical infrastructure, compressing permitting timelines while expanding interconnection eligibility for solar and hybrid tree installations.
Growth Catalysts
- Net-Zero Building Mandates:Western European cities now require on-site renewable generation for new commercial construction, creating captive demand for canopy-integrated photovoltaic systems that satisfy aesthetic and output requirements simultaneously.
- EMA Efficiency Standards:Grid-interactive certification pathways for urban generation assets have streamlined, reducing compliance friction for hybrid tree deployments that combine photovoltaic, piezoelectric, and battery storage elements.
- Transit Corridor Vibration Harvesting:Piezoelectric leaf arrays in high-traffic urban corridors capture mechanical energy from pedestrian and vehicle movement, opening revenue streams from transportation infrastructure operators seeking auxiliary power.
Market Restraints
- Crystalline Silicon Supply Concentration:Module production bottlenecks in East Asian manufacturing clusters create input cost volatility for solar tree assemblers dependent on standardized photovoltaic cells.
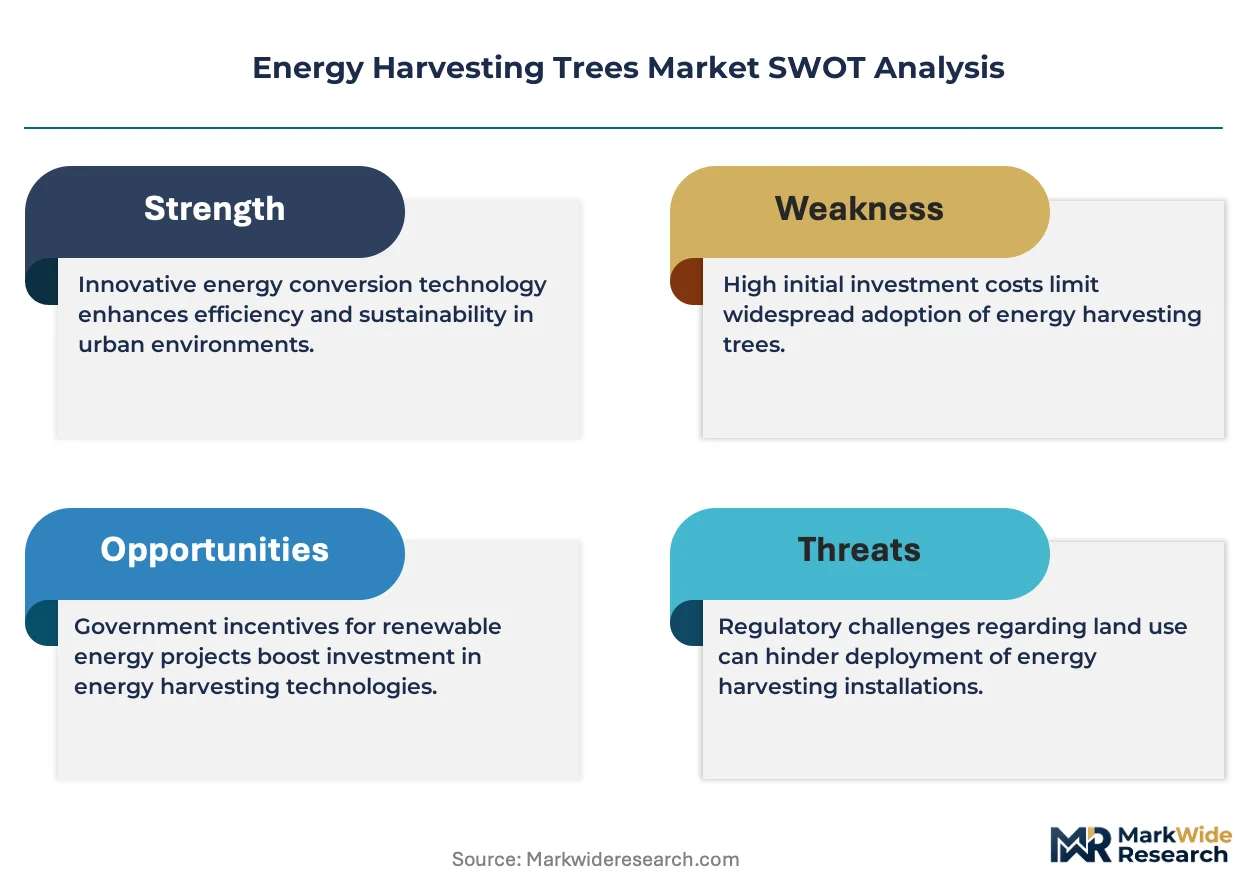
- REACH Compliance Burden:Piezoelectric ceramic formulations containing lead zirconate titanate face material substitution pressures, forcing reformulation of transduction elements before commercial deployment.
- Grid Interconnection Tariff Uncertainty:National building code classifications that treat energy harvesting trees as either infrastructure or electrical equipment generate permitting pathway fragmentation across municipal jurisdictions.
Strategic Opportunities
- Scandinavian Municipal Energy Cooperatives:Direct procurement relationships with city-owned utilities in Denmark, Sweden, and Norway offer long-term offtake agreements for grid-independent hybrid installations with integrated IoT monitoring.
- Biomimetic Architecture Convergence:Integration of photovoltaic surface optimization with thermoelectric substrate cooling is electrifying design possibilities for constrained urban footprints where traditional solar arrays prove dimensionally incompatible.
- CSRD-Linked Corporate Procurement:Scope 3 emissions reporting requirements under the EU Corporate Sustainability Reporting Directive are electrifying demand from commercial real estate developers seeking verifiable on-site generation assets for ESG disclosure.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Design optimization across photovoltaic, piezoelectric, and thermoelectric transduction domains requires specialized computational modeling expertise that remains concentrated within aerospace and automotive sectors.
- CE Marking Timeline Compression:Electromagnetic compatibility and electrical safety certification for public-space installations demands extended validation cycles that delay revenue recognition for project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Harvesting Trees Market |
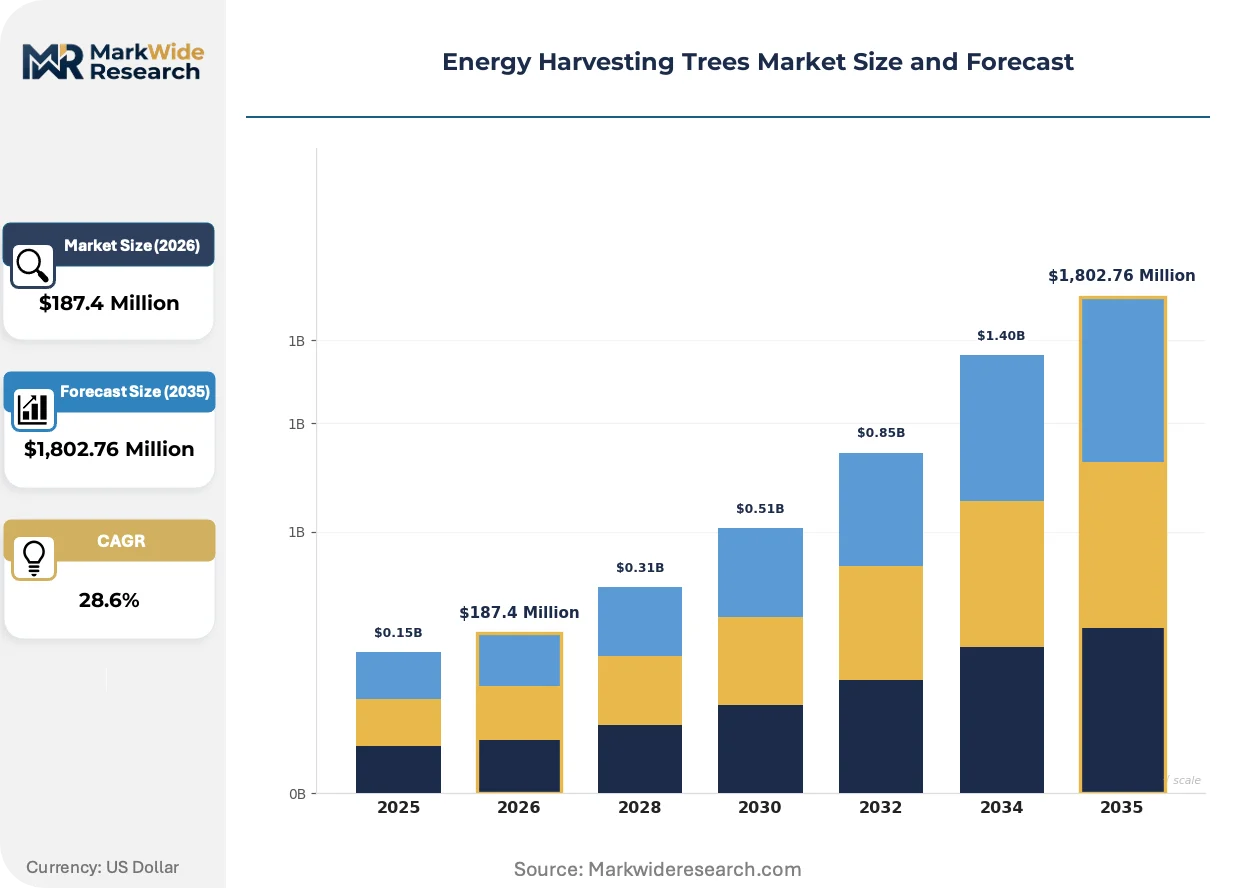
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piezoelectric Systems, Thermoelectric Generators, Solar Trees, Hybrid Models Application: Urban Infrastructure, Agricultural Areas, Remote Sensing, Disaster Management Technology: Solar Technology, Energy Conversion, Storage Solutions, IoT Integration End User: Municipalities, Agricultural Businesses, Research Institutions, Environmental Agencies |
| Companies Covered | Sologic Ltd., Treelectric, Solar Botanic, Smartflower, Solar Tree SL, Spotlight Solar, Treepower Australia, PowerTree India, Envision Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Harvesting Trees Market Emerging Trajectories
Product development is electrifying around hybrid architectures that collapse multiple transduction modes into single structural forms, while regulatory frameworks and procurement patterns are simultaneously adapting to accommodate distributed urban generation.
Hybrid energy harvesting trees are electrifying competitive positioning by integrating battery storage and edge computing into canopy structures. Municipalities in Germany and the Netherlands are specifying these configurations for smart city corridors where grid independence and sensor hosting prove decisive. The convergence is compressing procurement cycles that previously required separate vendor qualification for generation and storage assets.
REACH compliance timelines are electrifying material selection protocols for piezoelectric ceramics and thermal substrates across European supply chains. Manufacturers must document substitution assessments for restricted substances while maintaining transduction efficiency, creating compliance cost concentration among smaller design-manufacture integrators. The regulatory pressure is accelerating partnerships with specialty chemical suppliers capable of certifying lead-free formulations.
Corporate sustainability officers are electrifying procurement criteria toward assets with embedded life-cycle carbon accounting. Commercial developers in Dutch and German urban cores now require embodied carbon disclosures and end-of-life material recovery guarantees before specifying canopy installations. This behavioral shift is favoring integrated design-manufacture models that control upstream material provenance and downstream decommissioning pathways.
Energy Harvesting Trees Market Segmentation
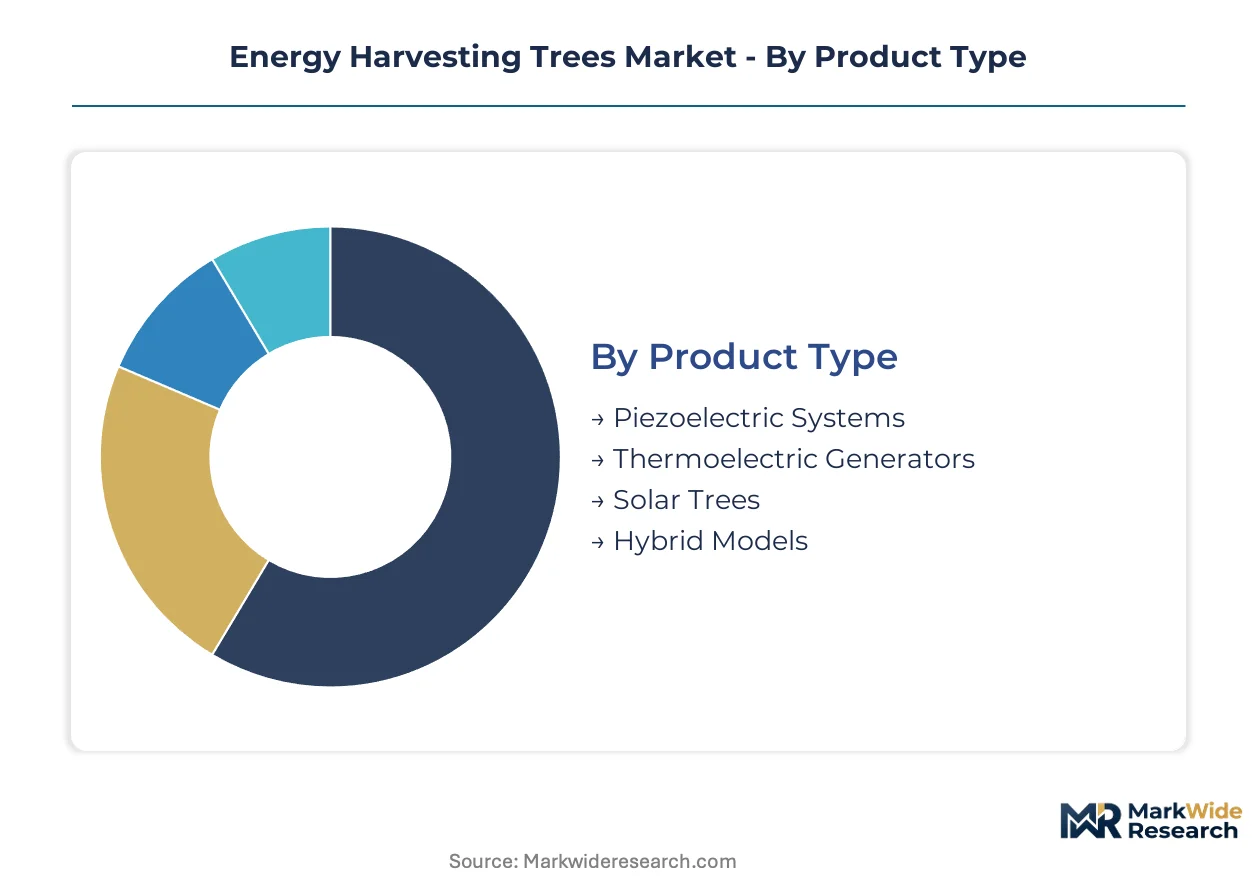
Segmentation reveals how energy harvesting trees compete across distinct value propositions. Product architecture determines unit economics, while application context dictates regulatory pathways and procurement authority.
Product Type:
Solar Trees dominate installed volume through crystalline silicon supply chain maturity. Hybrid Models command premium positioning via integrated storage and grid independence.
- Solar Trees:Photovoltaic canopy structures leveraging standardized silicon modules achieve rated outputs of 2.5 kW to 5 kW per unit. Municipalities in Germany and the Netherlands specify these for public park installations where aesthetic integration and proven reliability outweigh cutting-edge performance requirements.
- Hybrid Models:Multi-transduction architectures combining photovoltaic, piezoelectric, and thermoelectric elements with battery storage and edge computing enable grid-independent operation. Demand concentrates in Scandinavian smart city corridors where IoT sensor hosting and energy autonomy justify procurement premiums.
- Piezoelectric Systems:Vibration-harvesting leaf arrays capture mechanical energy from pedestrian and vehicle movement in high-traffic transit corridors.
- Thermoelectric Generators:Substrate-integrated thermal differential harvesters serve industrial perimeter applications with consistent waste heat profiles.
Mature deployment sits with Solar Trees. Newer deployment is concentrated in Hybrid Models.
Application:
Urban Infrastructure absorbs the majority of procurement volume through municipal sustainability mandates. Remote Sensing applications drive specialized specifications for off-grid durability.
- Urban Infrastructure:Street lighting, EV charging stations, and public WiFi hubs integrate energy harvesting canopies into transit corridors and civic plazas. Western European cities with net-zero building mandates specify these installations for new commercial construction where on-site renewable generation satisfies compliance requirements.
- Remote Sensing:Environmental monitoring stations and agricultural sensor networks require autonomous power in grid-inaccessible locations. Research institutions in Denmark and Sweden deploy hybrid configurations for long-duration data collection where maintenance access is constrained.
- Agricultural Areas:Irrigation monitoring and livestock tracking systems utilize canopy structures for distributed field power.
- Disaster Management:Emergency communication relays and temporary shelter power prioritize rapid deployment and weather resilience.
Procurement scale favors Urban Infrastructure. Technical complexity peaks in Remote Sensing.
Technology:
Energy Conversion capabilities differentiate vendor competitiveness. IoT Integration is climbing fastest as smart city specifications mature.
- Solar Technology:Crystalline silicon and thin-film photovoltaic arrays constitute the foundational generation layer. Supply concentration in East Asian manufacturing clusters creates input cost volatility for European assemblers.
- Storage Solutions:Lithium-ion and emerging solid-state battery integration enables diurnal load shifting and grid-independent operation. CE marking mandates for electrical safety extend validation timelines for public-space installations.
- Energy Conversion:Power electronics and maximum power point tracking optimize harvest efficiency across variable insolation and thermal conditions.
- IoT Integration:Edge computing nodes and wireless sensor hosting transform canopy structures into distributed data infrastructure.
Revenue concentration rests with Solar Technology. Steepest expansion trajectory belongs to IoT Integration.
End User:
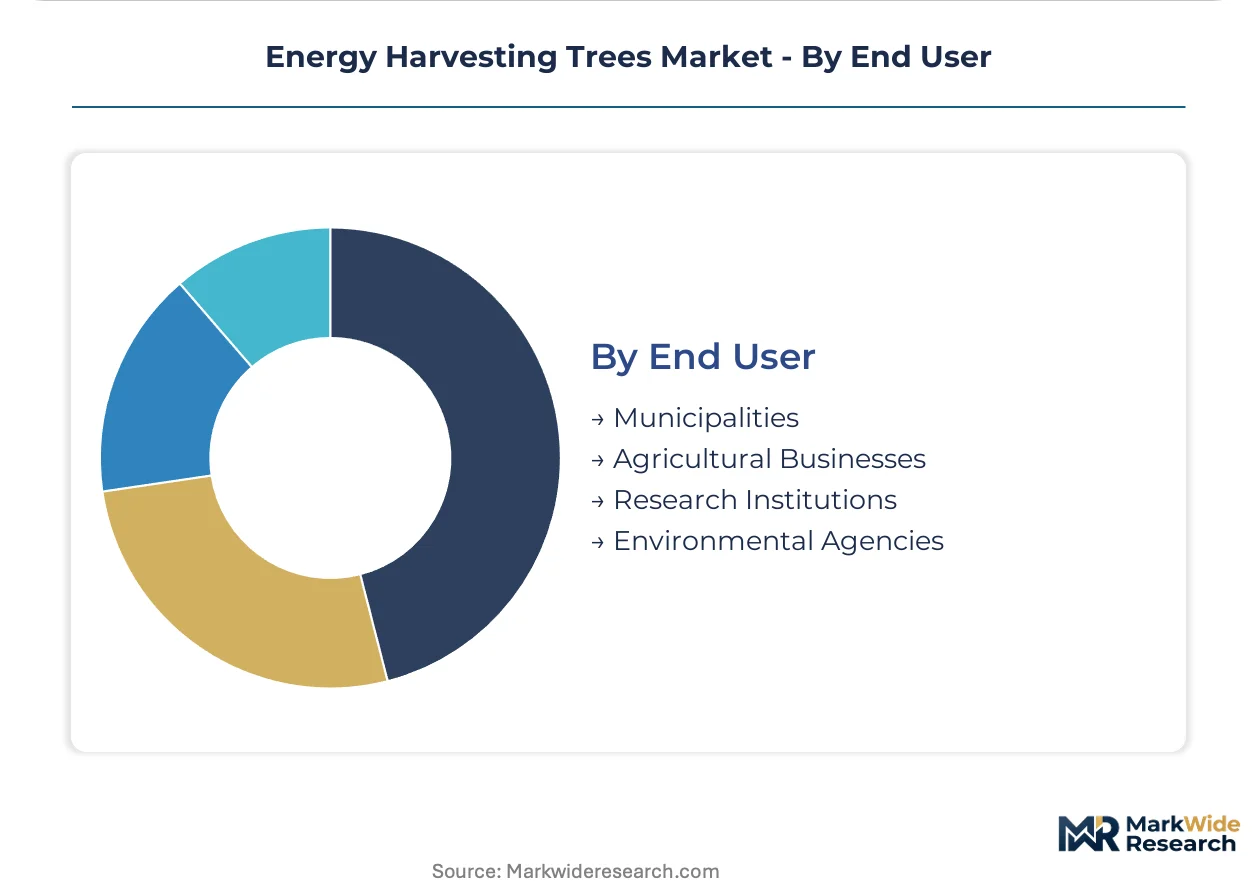
Municipalities control procurement volume through centralized sustainability budgets. Research Institutions drive specification innovation for extreme environment performance.
- Municipalities:City-owned utilities and public works departments specify energy harvesting trees for parks, transit corridors, and civic buildings. The EU Green Deal's renewable energy directives compress permitting timelines for these deployments in Germany, the Netherlands, and Scandinavian markets.
- Environmental Agencies:National and regional conservation authorities require autonomous monitoring power for protected area networks. REACH compliance governs material selection for installations in sensitive ecological zones.
- Agricultural Businesses:Farm operators and cooperative associations seek distributed power for precision agriculture sensor networks.
- Research Institutions:Universities and national laboratories validate novel transduction materials and hybrid architectures under field conditions.
Budget authority concentrates with Municipalities. Technical specification leadership sits with Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amsterdam anchors European deployment momentum through its smart city corridor program, where hybrid canopy installations power transit infrastructure and municipal sensor networks. Municipal procurement across Western Europe is compressing vendor qualification timelines as net-zero mandates harden into enforceable building codes.
Germany
Munich and Hamburg drive municipal adoption through integrated street lighting and EV charging specifications. The EU Green Deal's renewable energy directives accelerate permitting for urban micro-generation assets in public parks and transit corridors. Bavarian engineering clusters supply power electronics and IoT integration modules for canopy-integrated systems.
Netherlands
Rotterdam's port authority and Amsterdam's metropolitan transit authority specify solar tree arrays for auxiliary power in high-traffic corridors. REACH compliance governs material selection for piezoelectric ceramics deployed in vibration-rich environments. Eindhoven's design-manufacture integrators control project margins through captive supply chain relationships.
Sweden
Stockholm and Malmö anchor Scandinavian demand through city-owned energy cooperatives pursuing long-term offtake agreements. EMA efficiency standards streamline grid-interactive certification for hybrid installations with battery storage and edge computing. Lund's research institutions validate novel transduction materials under field conditions.
Denmark
Copenhagen's municipal utility mandates on-site renewable generation for new commercial construction in the Ørestad district. CE marking mandates for electrical safety and electromagnetic compatibility extend validation cycles for public-space installations. Aarhus deploys autonomous canopy systems for environmental monitoring in grid-inaccessible coastal zones.
United Kingdom
London's Greater London Authority embeds urban micro-generation requirements within commercial planning permissions for Canary Wharf and King's Cross developments. The CSRD electrifies procurement criteria from real estate developers seeking verifiable on-site generation assets for Scope 3 emissions disclosure. Manchester's transit authority pilots piezoelectric leaf arrays in high-footfall corridors.
Energy Harvesting Trees Market Vendor Landscape
Premium-margin players sit above commodity-margin players across integration depth and certification control. Design-manufacture integrators capture value through captive supply chains and direct municipal relationships, while module assemblers compete on crystalline silicon input costs. Three archetypes dominate: integrated design-manufacture specialists, biomimetic architecture innovators, and regional fabrication contractors. Competitive moves concentrate on strategic partnerships with specialty chemical suppliers for REACH-compliant materials and geographic expansion into Scandinavian municipal cooperative networks.
Within the integrated design-manufacture tier, Sologic Ltd. exemplifies margin control through European deployment footprints. Treelectric anchors positioning through direct relationships with Scandinavian municipal energy cooperatives. Solar Botanic occupies a specialization node in biomimetic leaf architectures that optimize photovoltaic surface area within constrained urban footprints.
| Leading Market Players |
|---|
| Sologic Ltd. |
| Treelectric |
| Solar Botanic |
| Smartflower |
| Solar Tree SL |
| Spotlight Solar |
| Treepower Australia |
| PowerTree India |
| Envision Solar |
| Others |
Supply Flow & Price Mechanics
EU Green Deal procurement mandates for urban micro-generation assets are compressing vendor qualification timelines and forcing crystalline silicon module assemblers to absorb margin pressure or surrender municipal contracts to integrated design-manufacture specialists with captive supply chains.
Pricing Analysis
Outcome-based pricing anchored to guaranteed uptime and verified energy yield per canopy unit dominates municipal procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels separates hybrid installations with battery storage and IoT integration from basic photovoltaic canopy configurations. Cost compression in standard-tier solar tree assemblies is intensifying because East Asian module supply bottlenecks create input volatility. Municipal energy cooperatives in Scandinavian markets exhibit lowest price sensitivity due to long-term offtake security priorities, while commercial real estate developers in Dutch urban cores show highest sensitivity to upfront capital outlay.
Supply Chain Analysis
End-of-life material recovery flows and refurbishment pathways for piezoelectric ceramics and lithium-ion battery modules are emerging as compliance cost centers under REACH and extended producer responsibility frameworks. Crystalline silicon module production concentrates in China, South Korea, and Vietnam, while power electronics and IoT integration modules source from Bavarian engineering clusters in Germany. European assemblers draw from East Asian photovoltaic inputs, REACH-compliant specialty chemical suppliers for lead-free piezoelectric formulations, and regional fabricators for structural canopy components. Single-source vulnerability in crystalline silicon wafer supply creates tariff exposure and logistics chokepoint risk. Distribution runs through direct municipal procurement channels and city-owned utility relationships rather than traditional equipment wholesaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance timelines and CE marking validation cycles are functioning as consolidation mechanisms, eliminating smaller design-manufacture integrators unable to sustain extended certification costs or secure specialty chemical partnerships for lead-free material formulations.
For Market Incumbents: To counter margin erosion from East Asian module price volatility, deepen backward integration into power electronics and IoT integration module production within European engineering clusters, and secure exclusive offtake agreements with REACH-certified specialty chemical suppliers for piezoelectric ceramic formulations. For New Entrants and Emerging Players: Launch via direct relationships with Scandinavian municipal energy cooperatives pursuing grid-independent hybrid installations, targeting the vibration-harvesting piezoelectric niche in German and Dutch transit corridors where incumbent coverage remains thin and procurement specifications favor novel transduction architectures. For Investors and Strategic Acquirers: The window for entry favors integrated design-manufacture specialists with captive municipal relationships and certified material provenance control over the next decade, with acquisition priority on firms holding validated CE marking pathways and documented end-of-life material recovery protocols. Monitor EMA efficiency standard implementation timelines and national building code reclassifications as inflection signals for interconnection tariff shifts.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Partnership | Specialty chemical supplier alliances secure lead-free piezoelectric formulations ahead of regulatory deadlines. |
| Scandinavian Cooperative Network Expansion | Direct municipal utility relationships in Denmark, Sweden, and Norway lock in long-term offtake visibility. |
| Hybrid Architecture R&D Investment | Multi-transduction integration with battery storage commands procurement premiums in smart city corridors. |
| CE Marking Pathway Acceleration | Compressed electromagnetic compatibility validation reduces revenue recognition delays for public-space deployments. |
| End-of-Life Recovery Infrastructure | Documented decommissioning protocols satisfy CSRD-linked corporate procurement criteria for embodied carbon disclosure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with municipal procurement officers, smart city infrastructure planners, EPC contractors specializing in urban micro-generation, and regulatory affairs leads at canopy-integrated system developers. Primary fieldwork covered deployment sites across German public parks, Dutch transit corridors, and Scandinavian municipal energy cooperative installations. Secondary sources included EU Green Deal implementation documents, EMA efficiency standard drafts, REACH substitution assessment databases, and municipal sustainability budget disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from crystalline silicon module trade flows and municipal procurement aggregation.
Granularity-level modeling addressed product architecture (solar trees, hybrid models, piezoelectric systems, thermoelectric generators), application context (urban infrastructure, remote sensing, agricultural areas, disaster management), technology layer (solar technology, storage solutions, energy conversion, IoT integration), and end-user procurement authority (municipalities, environmental agencies, agricultural businesses, research institutions). CAGRs were derived from segment-level demand elasticity analysis and regulatory implementation timeline assumptions. Forecast inputs incorporated EU Green Deal permitting acceleration schedules, REACH compliance cost trajectories, and crystalline silicon supply concentration risk premiums.
Regulatory implementation delays, material substitution failures in piezoelectric ceramics, and crystalline silicon supply disruption are the dominant revision risks to deployment velocity assumptions. Forecasts reflect documented stakeholder input and validated secondary data rather than speculative scenario construction. Practitioners should monitor EMA efficiency standard finalization, REACH substance restriction amendments, and East Asian module production capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
North America Biomass Gasification Market