
 Biomass Gasification Market | 2026-2036
Biomass Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Gasification Market Intelligence
Fluidized bed reactor designs is tilting capital deployment toward higher throughput configurations with lower tar yields. Valmet Corporation leverages its pulp-and-paper equipment heritage to dominate Nordic retrofit installations. Mitsubishi Heavy Industries, Ltd. anchors Asian utility-scale projects through integrated gas turbine combined-cycle offerings. ANDRITZ AG specializes in entrained flow systems for woody biomass with high ash content.
Biomass gasification converts organic feedstock into combustible syngas through partial oxidation at temperatures typically ranging from 700°C to 1,500°C, yielding a hydrogen-carbon monoxide mixture suitable for power generation or chemical synthesis. Fluidized bed technology occupies the largest installed base due to operational flexibility across wood chips and agricultural residues. Plasma gasification differentiates through near-zero tar output and tolerance for municipal solid waste streams. Supercritical water gasification leads in wet feedstock applications where conventional drying costs erode project economics.
EPA emission standards under the Clean Air Act constrain syngas flaring protocols in US installations, while EU Green Deal carbon accounting rules shape feedstock eligibility for certificate trading. India's MNRE biomass power policies and BIS equipment certification create dual compliance thresholds for imported reactor vessels. Stakeholders must monitor how tightening hydrogen purity specifications from ISO 14687 affect syngas-to-fuel upgrading investments.
Market Dynamics
Fluidized bed reactor designs are consolidating capital deployment toward higher-throughput configurations that slash tar yields while accommodating heterogeneous feedstock streams. This technical pivot is compressing project timelines for utility-scale installations and reshaping vendor qualification criteria.
Growth Catalysts
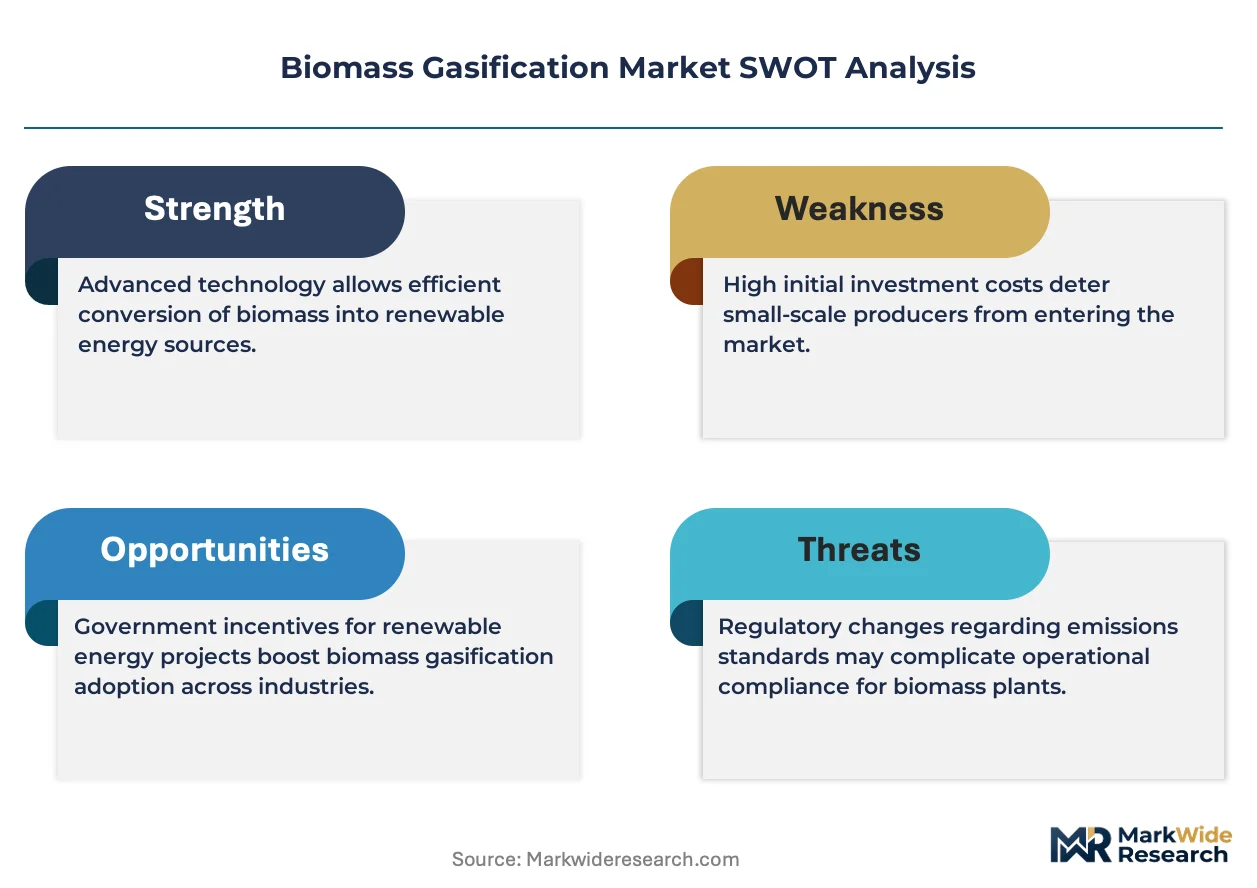
- EU Green Deal carbon accounting:Renewable energy directives tighten emission thresholds for fossil alternatives, accelerating syngas-to-power substitution in continental industrial clusters.
- Indonesia's rural electrification programs:State-backed procurement mandates for off-grid biomass generation create dedicated offtake channels for distributed reactor deployments.
- Plasma gasification tolerance:Near-zero tar output enables municipal solid waste streams previously excluded from thermal conversion economics.
Market Restraints
- Feedstock cost volatility:Agricultural residue prices fluctuate with seasonal harvest cycles and competing industrial demand from pellet manufacturers.
- Reactor vessel supply concentration:Specialized alloy fabrication capacity clusters in Nordic and German metallurgical centers, extending delivery lead times.
- Tar cracking limitations:Conventional catalytic systems degrade rapidly when processing high-alkali agricultural residues, forcing costly downstream cleanup.
Strategic Opportunities
- Vietnam's industrial zone expansion:Manufacturing hub electrification creates captive demand for syngas-to-steam applications without grid interconnection delays.
- Supercritical water integration:Wet feedstock applications bypass conventional drying costs, unlocking palm oil mill effluent and sewage sludge value chains.
- India's MNRE biomass power policies:Central financial assistance and accelerated depreciation allowances improve project IRRs for domestic technology providers.
Industry Challenges
- High-temperature materials engineering:Refractory degradation in entrained flow systems demands specialized welding expertise scarce outside pulp-and-paper maintenance networks.
- ISO 14687 hydrogen purity compliance:Syngas-to-fuel upgrading investments face certification timeline uncertainty as specifications tighten for mobility applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Gasification Market |
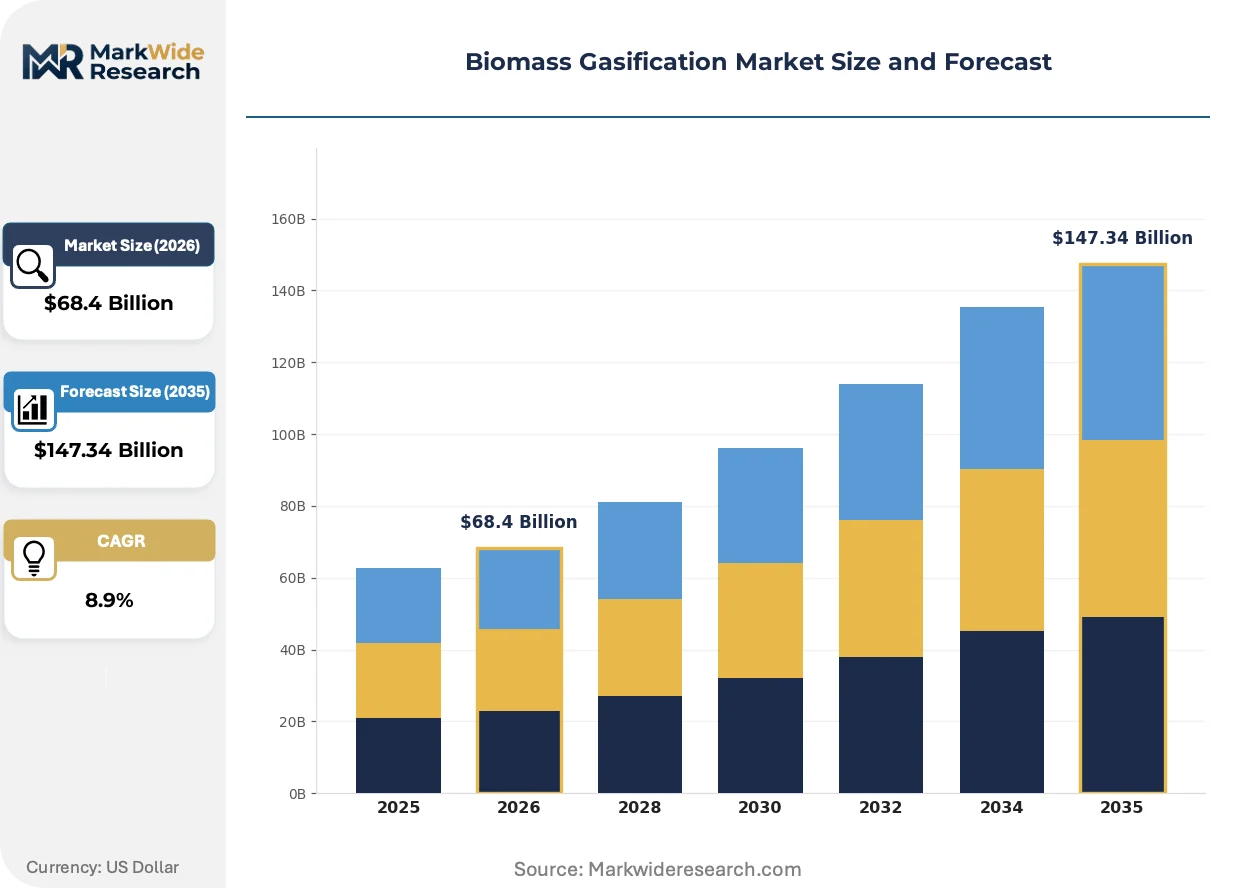
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $147.34 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed, Fluidized Bed, Entrained Flow, Plasma Gasification, Supercritical Water Gasification Feedstock Type: Wood Chips, Agricultural Residues, Energy Crops, Municipal Solid Waste, Animal Waste End User Industry: Power Generation, Chemical Manufacturing, Biofuel Production, Food Processing, Textile Manufacturing Application: Electricity Generation, Heat Production, Syngas for Chemical Synthesis, Hydrogen Production, Biochar Production |
| Companies Covered | EQTEC plc, Chanderpur Works Private Limited, Valmet Corporation, KASAG Swiss AG, Beltran Technologies, Inc., Mitsubishi Heavy Industries, Ltd., Ankur Scientific Energy Technologies Pvt. Ltd., ANDRITZ AG, Thyssenkrupp AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Gasification Market Strategic Shifts & Innovations
Reactor engineering is pivoting from fixed-bed legacy designs toward continuous-feed systems that match syngas quality to downstream application requirements. This evolution is compressing the viable technology set and elevating process control software to competitive differentiation.
Entrained flow gasification is migrating from pilot demonstrations to commercial woody biomass installations. Nordic pulp mills retrofit existing bark boilers with oxygen-blown systems to supply lime kiln fuel. The technology is migrating from premium chemical synthesis feedstock production toward baseload power generation as turbine manufacturers relax fuel specifications.
EPA emission standards under the Clean Air Act now constrain syngas flaring protocols in US installations, forcing real-time composition monitoring and automated diversion systems. Industrial consequence includes mandatory continuous emissions monitoring system upgrades for existing facilities. Chemical synthesis operators in Texas and Louisiana face the steepest compliance costs, driving consolidation toward integrated petrochemical sites with shared abatement infrastructure.
Power utilities in Southeast Asia now specify performance-guaranteed availability contracts rather than equipment purchase agreements. Engineering-procurement-construction firms absorb operational risk for five-to-seven-year terms. This shift concentrates vendor selection criteria on demonstrated run-hour records rather than capital cost minimization, favoring established fluidized bed suppliers with regional service networks.
Biomass Gasification Market Segmentation
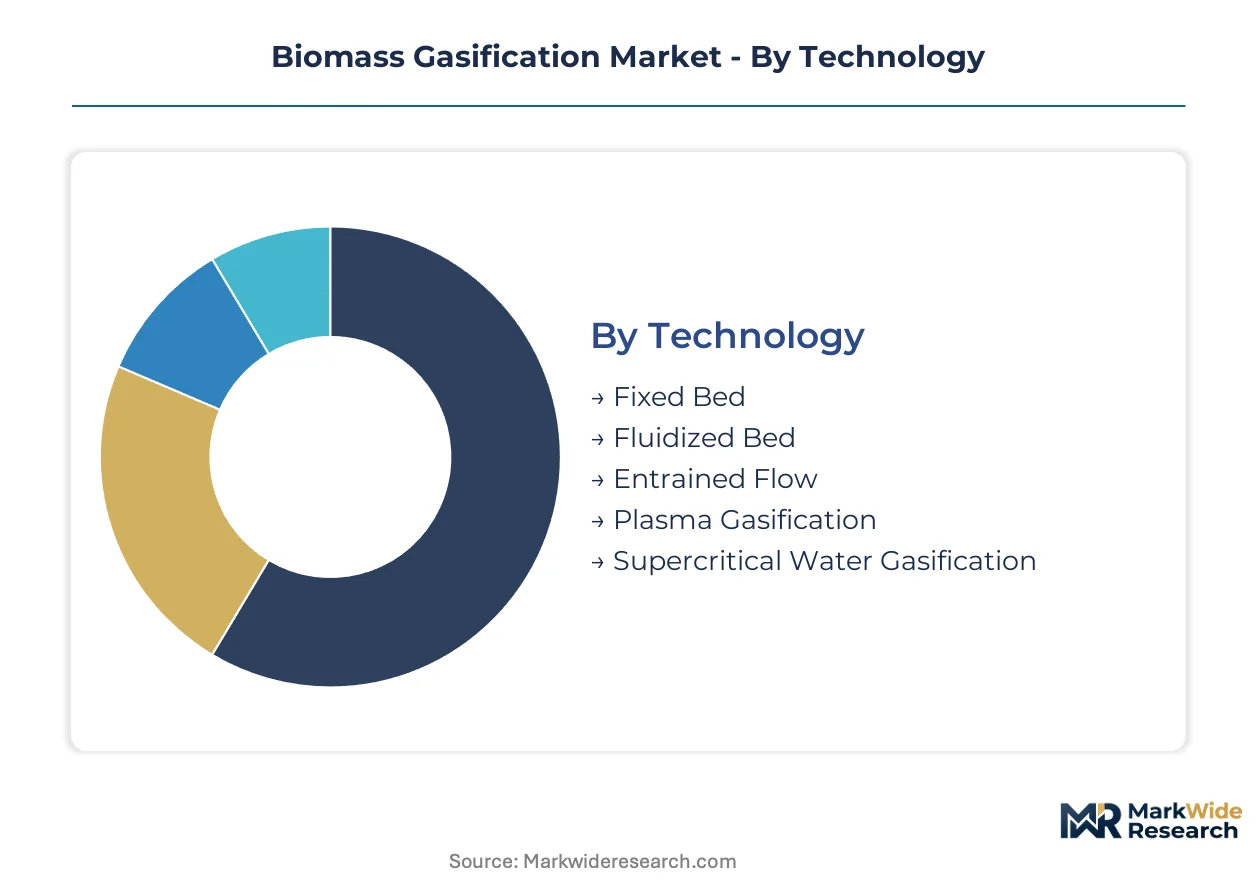
Technology selection dictates capital intensity, feedstock flexibility, and syngas quality specifications across project configurations. End-use requirements for hydrogen purity or chemical synthesis feedstock drive divergent reactor specifications and vendor qualification criteria.
Technology:
Reactor designs span a use-case spectrum from small-scale rural electrification to utility-grade chemical synthesis, with throughput capacity and tar tolerance determining commercial viability.
- Fluidized Bed:Circulating and bubbling bed configurations dominate installed capacity due to operational flexibility across heterogeneous biomass streams. Power utilities in Indonesia specify fluidized bed systems for rural electrification programs requiring 90% availability guarantees.
- Entrained Flow:Oxygen-blown systems operating above 1,200°C produce tar-free syngas suitable for Fischer-Tropsch synthesis. Nordic pulp mills retrofit bark boilers with entrained flow reactors to supply lime kiln fuel, bypassing fossil natural gas.
- Fixed Bed:Downdraft configurations serve distributed village-scale installations with simple mechanical operation and minimal operator training requirements.
- Plasma Gasification:Electric arc heating enables municipal solid waste conversion with near-zero tar output, unlocking feedstock streams excluded from thermal economics.
- Supercritical Water Gasification:Wet biomass processing above 374°C and 22.1 MPa eliminates drying energy penalties for palm oil mill effluent and sewage sludge applications.
The dominant share belongs to Fluidized Bed, while Entrained Flow is closing the gap fastest.
Feedstock Type:
Feedstock economics hinge on collection radius, moisture content, and competing industrial demand from pellet or animal feed markets.
- Wood Chips:Forest residues and sawmill waste provide consistent calorific value with low alkali content. EU Green Deal carbon accounting rules certify sustainably harvested wood chips for renewable energy certificate trading.
- Agricultural Residues:Rice husk, wheat straw, and corn stover face seasonal price volatility and competing demand from pellet manufacturers. High potassium content accelerates catalytic tar cracker degradation, forcing costly downstream cleanup.
- Energy Crops:Dedicated cultivation of miscanthus and switchgrass offers supply security but requires long-term land lease commitments.
- Municipal Solid Waste:Gate fee revenue streams improve project IRRs where landfill diversion mandates exist.
- Animal Waste:Dairy and poultry manure applications concentrate in regions with concentrated animal feeding operations and nutrient runoff regulations.
Wood Chips commands the largest procurement volumes, though Agricultural Residues is expanding most quickly in South and Southeast Asian installations.
End User Industry:
Downstream value capture varies from commodity electricity tariffs to premium chemical synthesis margins.
- Power Generation:Grid-connected and off-grid installations absorb the majority of syngas output. Engineering-procurement-construction firms in Vietnam absorb operational risk through availability contracts spanning five-to-seven years.
- Chemical Manufacturing:Methanol and ammonia producers require ISO 14687-compliant hydrogen specifications, driving investments in water-gas shift and pressure swing adsorption units.
- Biofuel Production:Fischer-Tropsch synthesis and synthetic natural gas upgrading target transport fuel markets with carbon intensity regulations.
- Food Processing:Steam and heat applications for drying and sterilization favor simple gas burner configurations over power generation.
- Textile Manufacturing:Boiler fuel substitution in dyeing and finishing operations concentrates in industrial zones with captive demand.
Power Generation retains the dominant position, while Chemical Manufacturing is climbing the fastest as hydrogen purity specifications tighten for mobility applications.
Application:
Application selection determines syngas conditioning requirements and downstream equipment specifications.
- Electricity Generation:Gas engines and gas turbines accept moderate syngas quality with minimal cleanup. Southeast Asian utilities specify performance-guaranteed availability contracts favoring established fluidized bed suppliers.
- Syngas for Chemical Synthesis:Methanol, ammonia, and Fischer-Tropsch processes demand precise H2/CO ratios and ppb-level contaminant removal.
- Hydrogen Production:Water-gas shift and pressure swing adsorption upgrades face certification timeline uncertainty as ISO 14687 specifications evolve.
- Heat Production:Direct combustion in kilns and boilers bypasses power generation efficiency losses.
- Biochar Production:Slow pyrolysis integration captures carbon in solid form for soil amendment and carbon credit markets.
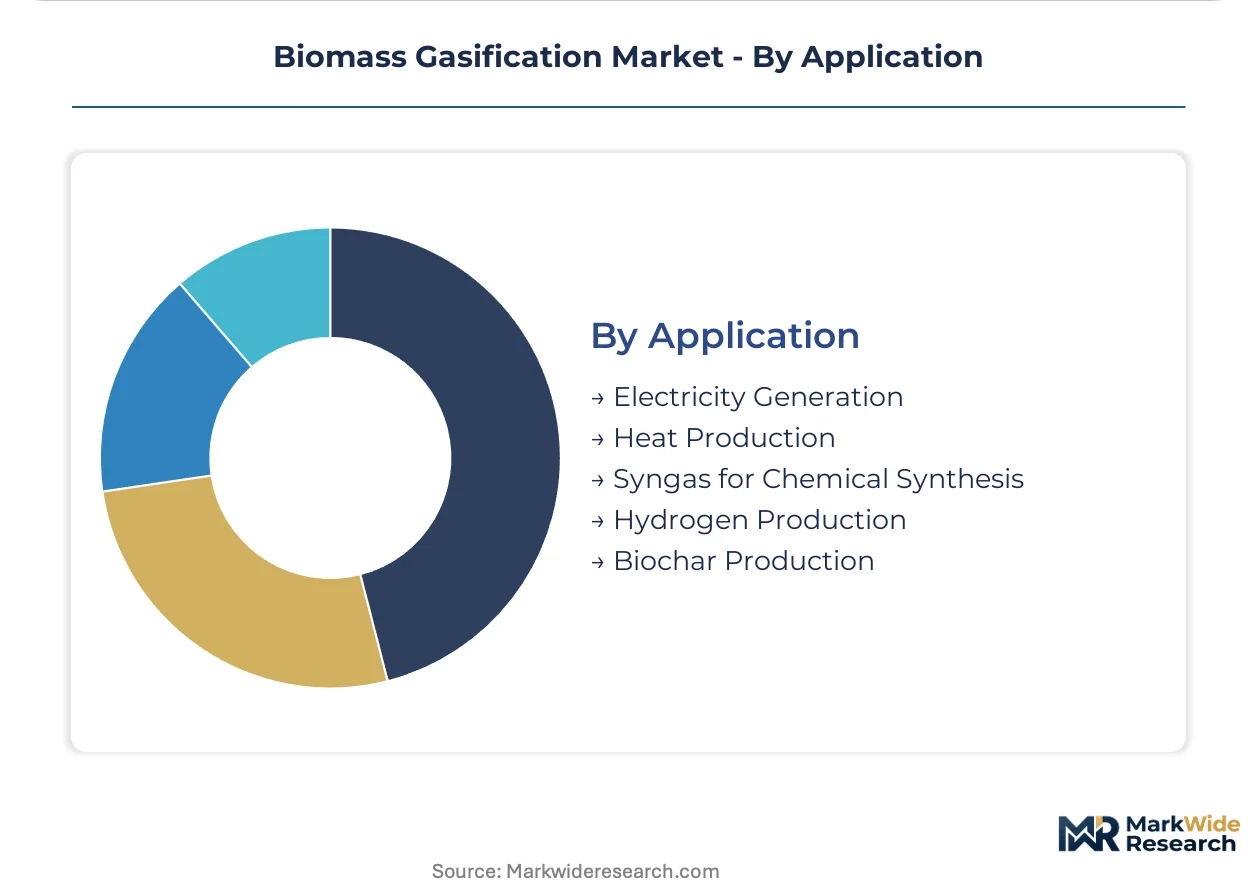
Electricity Generation holds the dominant share, though Hydrogen Production is gaining share fastest as mobility fuel specifications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reactor fabricators export specialized alloy vessels to Indonesian utility projects, while Nordic engineering groups supply entrained flow retrofits to pulp mills across the Baltic Rim.
United States
Texas and Louisiana chemical synthesis operators drive demand for syngas-to-methanol upgrading. EPA Clean Air Act emission standards constrain flaring protocols and mandate continuous emissions monitoring upgrades. Houston-area petrochemical clusters consolidate toward shared abatement infrastructure to distribute compliance costs.
Germany
Industrial clusters in North Rhine-Westphalia and Bavaria substitute syngas for fossil natural gas in lime kiln and chemical feedstock applications. EU Green Deal carbon accounting rules certify woody biomass for renewable energy certificate trading. Ruhr Valley engineering fabricators concentrate specialized alloy reactor vessel production, extending delivery lead times for Asian buyers.
Indonesia
State-backed rural electrification programs create dedicated offtake channels for distributed fluidized bed deployments across Java and Sumatra. National procurement mandates prioritize 90% availability guarantees for off-grid biomass generation. Surabaya-area industrial zones absorb engineering-procurement-construction contracts with five-to-seven-year operational risk terms.
India
Punjab and Haryana agricultural residue collection networks supply rice husk and wheat straw to distributed power projects. MNRE central financial assistance and accelerated depreciation allowances improve project IRRs for domestic technology providers. Gujarat chemical zones pilot syngas-to-hydrogen upgrading for refinery integration.
Vietnam
Manufacturing hub electrification in Binh Duong and Dong Nai provinces creates captive demand for syngas-to-steam applications. Industrial zone expansion bypasses grid interconnection delays through captive generation models. Ho Chi Minh City-area engineering firms absorb operational risk through performance-guaranteed availability contracts.
Biomass Gasification Market Key Industry Players
On the supply side, the industry is consolidating around reactor fabricators with demonstrated run-hour records and regional service networks. The vendor base spans three distinct tiers: pulp-and-paper heritage engineering groups, diversified heavy industrial conglomerates, and specialized fluidized bed technology providers. Dominant competitive moves include strategic partnerships with engineering-procurement-construction firms and technology licensing agreements for regional market entry.
Among Nordic engineering specialists, Valmet Corporation and ANDRITZ AG exemplify the pulp-and-paper heritage archetype, leveraging existing maintenance networks and bark boiler retrofit expertise. Mitsubishi Heavy Industries, Ltd. anchors the diversified industrial tier through integrated gas turbine combined-cycle offerings for Asian utility-scale deployments.
| Leading Market Players |
|---|
| EQTEC plc |
| Chanderpur Works Private Limited |
| Valmet Corporation |
| KASAG Swiss AG |
| Beltran Technologies, Inc. |
| Mitsubishi Heavy Industries, Ltd. |
| Ankur Scientific Energy Technologies Pvt. Ltd. |
| ANDRITZ AG |
| Thyssenkrupp AG |
| Others |
Cost & Logistics Intelligence
Specialized alloy fabrication concentration in Nordic and German metallurgical centers determines both reactor vessel delivery premiums and procurement network topology for Asian utility developers. This single-source dependency for high-temperature vessel manufacturing compresses pricing spreads between fluidized bed configurations while extending engineering-procurement-construction contract timelines.
Pricing Analysis
Current-generation entrained flow systems command substantial premiums over fixed-bed legacy installations due to oxygen-blown operational complexity and tar-free output specifications. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed availability contracts from basic equipment procurement. Cost compression in standard fluidized bed configurations is intensifying because engineering-procurement-construction firms absorb operational risk for five-to-seven-year terms. State-backed rural electrification programs in Indonesia exhibit highest price sensitivity, while EU chemical synthesis operators demonstrate lowest sensitivity due to carbon accounting certificate premiums.
Supply Chain Analysis
Export control regimes for advanced welding technologies and high-nickel alloy specifications constrain reactor vessel flows from German fabricators to Southeast Asian project sites. Supply concentration centers on Germany, Finland, and Japan for specialized metallurgical fabrication, with China and India developing domestic capacity for standard fluidized bed configurations. Raw material dependencies rest on nickel-chromium alloys, refractory ceramics, and precision control instrumentation. Single-source vulnerability persists for entrained flow oxygen injection systems. Distribution runs through engineering-procurement-construction consortia that bundle vessel fabrication with regional installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Southeast Asian utilities specifying performance-guaranteed availability contracts rather than equipment purchase agreements, compressing vendor margins and elevating service network requirements as qualification criteria.
For Market Incumbents: Harden regional service infrastructure through captive maintenance partnerships in Indonesia and Vietnam to defend against emerging fluidized bed technology providers from China. Anchor entrained flow retrofit expertise in Nordic pulp mill networks before oxygen-blown system specifications commoditize. Prioritize welding certification investments that exceed ISO 3834 requirements for high-temperature vessel repairs. For New Entrants and Emerging Players: Build out supercritical water gasification capabilities for palm oil mill effluent applications in Malaysia and Indonesia, where wet feedstock processing bypasses drying cost disadvantages that erode conventional project economics. Target Vietnam's industrial zone expansion for syngas-to-steam captive generation models that bypass grid interconnection delays. Lead with availability-based contracting to match incumbent risk-absorption terms. For Investors and Strategic Acquirers: The market sits at a technology-consolidation phase that favors engineering-procumbment-construction integrators with demonstrated run-hour records over pure equipment manufacturers. Long-term viability across the analysis window hinges on hydrogen purity upgrade positioning as ISO 14687 specifications mature for mobility applications. Acquire fluidized bed technology providers with Indonesian service networks. Monitor BIS equipment certification timeline announcements as inflection indicators for import substitution opportunities in India.| Strategic Initiative | Industry Significance |
|---|---|
| Availability-Based Contracting | Engineering-procurement-construction firms absorb five-to-seven-year operational risk, favoring established fluidized bed suppliers. |
| Entrained Flow Retrofit | Nordic pulp mills retrofit bark boilers with oxygen-blown systems to supply lime kiln fuel, bypassing fossil natural gas. |
| Supercritical Water Integration | Wet feedstock processing eliminates drying energy penalties for palm oil mill effluent and sewage sludge value chains. |
| Regional Service Network Expansion | Indonesian procurement mandates prioritize 90% availability guarantees requiring localized maintenance capabilities. |
| Hydrogen Purity Upgrade Investment | Water-gas shift and pressure swing adsorption systems face certification timeline uncertainty as ISO 14687 specifications tighten. |
Research Approach
A spread of perspectives from utility planning officers, EPC contractors, reactor vessel fabricators, and feedstock procurement specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs data, EU ETS carbon accounting disclosures, MNRE policy circulars, and SEC filings from heavy industrial conglomerates. Bottom-up capacity installation tracking triangulated with top-down energy demand projections across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling reactor deployment trajectories against feedstock availability constraints and regulatory certificate issuance rates. Segmentation dimensions spanned technology type, feedstock moisture content tier, end-use application, and regional grid interconnection status. CAGRs were derived from installed base growth rates and replacement cycle analysis. Industry-specific inputs included EU Green Deal carbon price trajectories and Indonesian rural electrification procurement schedules.
Practitioners should monitor alloy price volatility, BIS certification timeline shifts, and EPA Clean Air Act enforcement intensity for early signals requiring forecast reassessment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market