
 Global Biomass Power Market | 2026-2036
Global Biomass Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomass Power Market Analysis
Market Context
Modular co-firing configurations is broadening buyer choice by letting utilities blend biomass with coal without full plant rebuilds. Drax Group leverages its pellet supply chain to anchor converted coal units across the United Kingdom. Mitsubishi Heavy Industries sustains technology leadership through advanced boiler designs that handle varied feedstock moisture content. Babcock & Wilcox Enterprises competes on engineering services for retrofits in North American installations.
Technical Definition and Segments
Biomass power denotes electricity and thermal energy derived from organic matter—typically lignocellulosic material with moisture content between 10% and 50%—processed through combustion, gasification, or anaerobic digestion to drive turbines or generate biogas. The technology segment splits across combustion, gasification, anaerobic digestion, and pyrolysis, with combustion occupying the dominant share due to proven operational economics at utility scale. Wood chips lead feedstock consumption because established forestry residue collection networks in Scandinavia and the southeastern United States deliver predictable supply economics. The application dimension shows electricity generation commanding the largest revenue pool while co-firing attracts capital for its lower retrofit barrier and faster permitting timelines.
Regulatory Frame and Outlook
The EU Green Deal and its Renewable Energy Directive, alongside EPA renewable fuel standards in the United States and Japan's FIT regime administered by METI, collectively mandate carbon accounting and sustainability certification for feedstock sourcing. These frameworks shape demand by restricting eligible material to certified low-indirect-land-use sources and by setting escalating renewable generation quotas that utilities must meet. Stakeholders must monitor feedstock traceability system costs and policy durability across jurisdictions where political support for biomass classification as carbon-neutral remains contested.
Market Dynamics
Co-firing retrofits are compressing capital deployment timelines for utilities seeking baseload renewable output without full plant rebuilds. This configuration shift is redrawing competitive boundaries between dedicated biomass operators and legacy coal generators.
Growth Catalysts
- EU Green Deal mandates:Escalating renewable portfolio standards across member states require utilities to source certified low-carbon baseload power, directing capital toward converted thermal assets.
- Japan's FIT regime:METI-administered feed-in tariffs guarantee long-term offtake prices for biomass electricity, attracting independent power producers to project development.
- Forestry residue networks:Established collection infrastructure in Scandinavia and the southeastern United States delivers predictable feedstock economics at scale.
Market Restraints
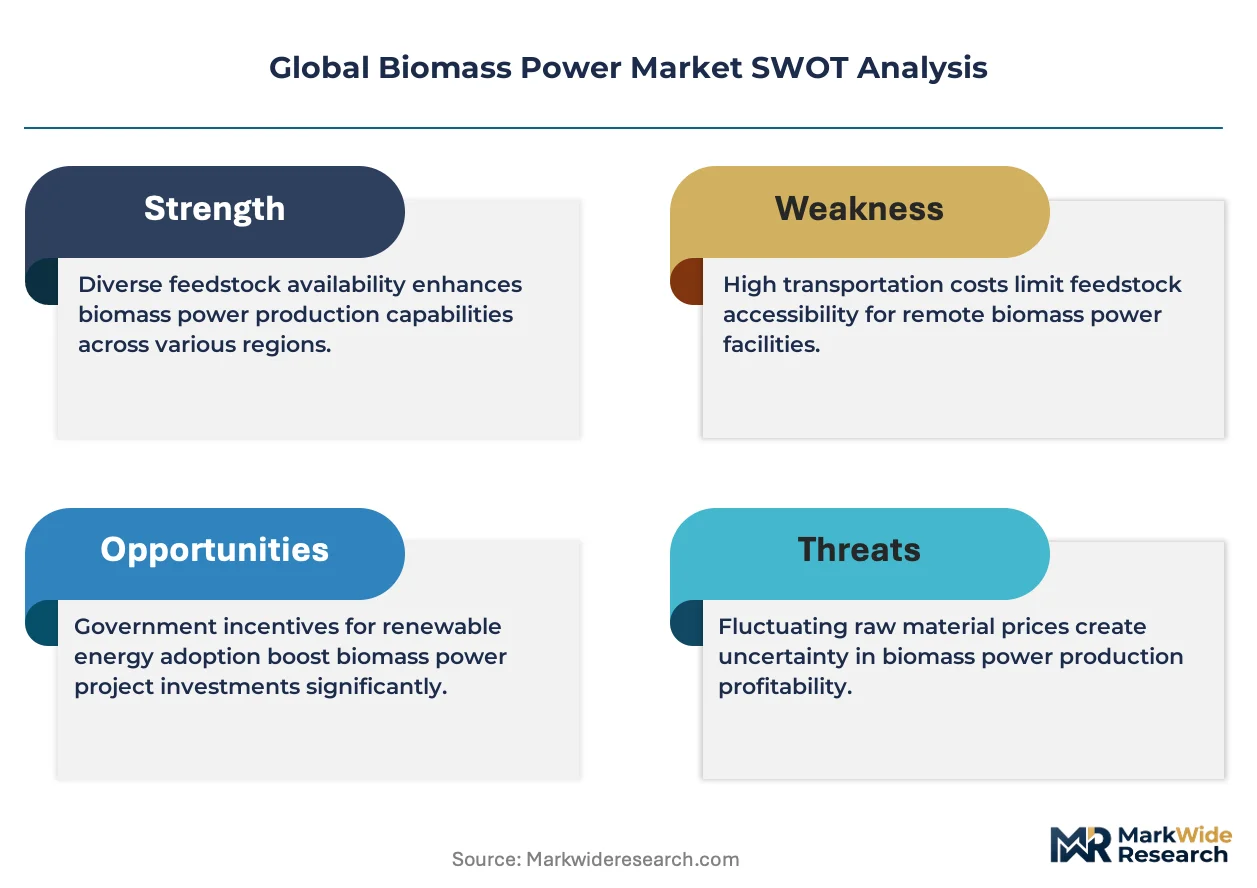
- Pellet supply concentration:Bulk pellet production clusters in the US Southeast and British Columbia, creating single-source vulnerability for European and Asian offtakers.
- Moisture content variability:Lignocellulosic feedstocks ranging from 10% to 50% moisture require customized boiler configurations, limiting equipment interchangeability.
- Carbon accounting disputes:contested biomass neutrality classifications in multiple jurisdictions threaten policy durability and investor confidence.
Strategic Opportunities
- Agricultural residue valorization:Brazil's sugarcane bagasse and rice husk streams remain underutilized for grid-scale power generation.
- Biogas-to-power clusters:Anaerobic digestion installations at German and Danish agricultural cooperatives can feed localized district heating networks.
- Waste-to-energy integration:Municipal solid waste gasification projects in Japan align with landfill reduction targets while generating baseload capacity.
Industry Challenges
- Feedstock certification timelines:Sustainability traceability systems for EU Renewable Energy Directive compliance add 12-18 months to project commissioning.
- Boiler engineering specialization:Scarce technical expertise in high-alkali fuel combustion limits retrofit execution speed for aging coal units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomass Power Market |
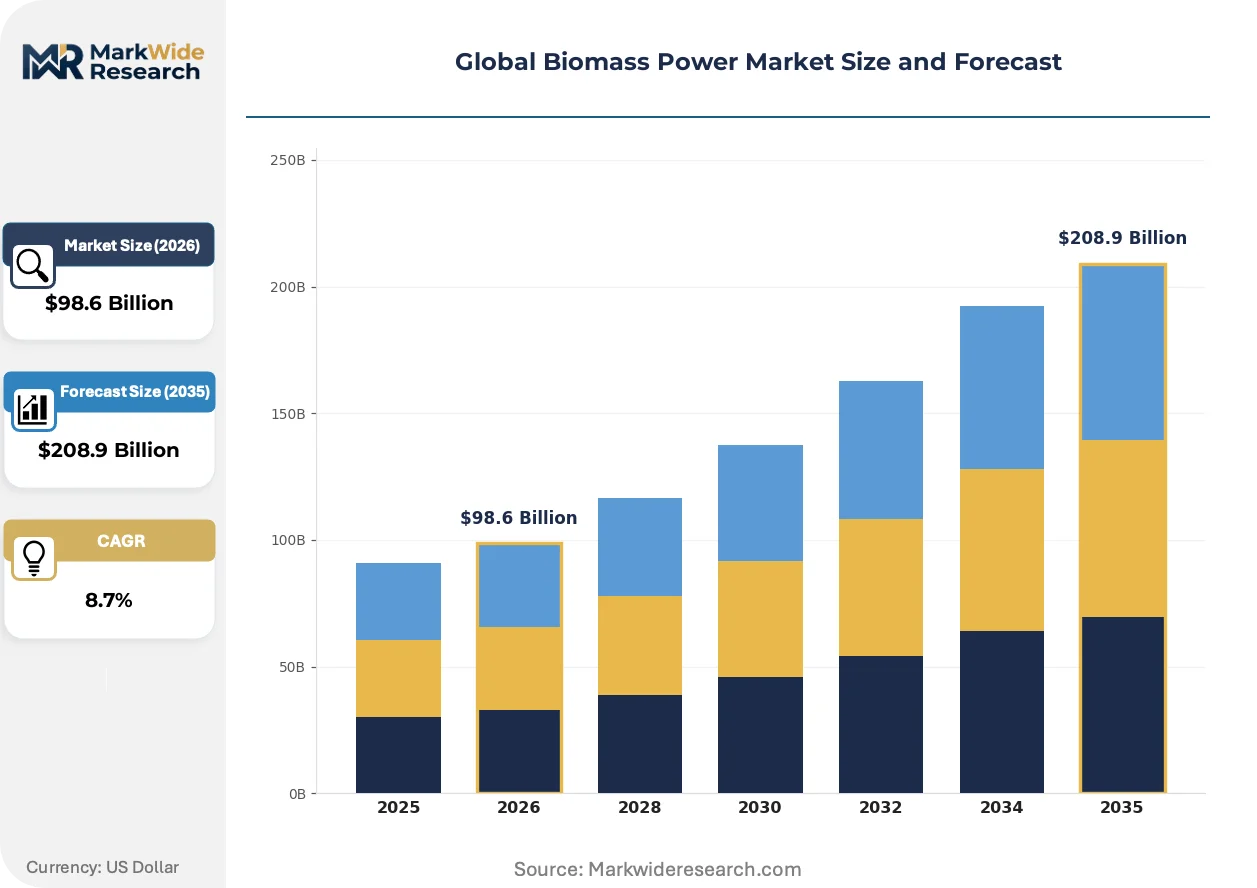
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
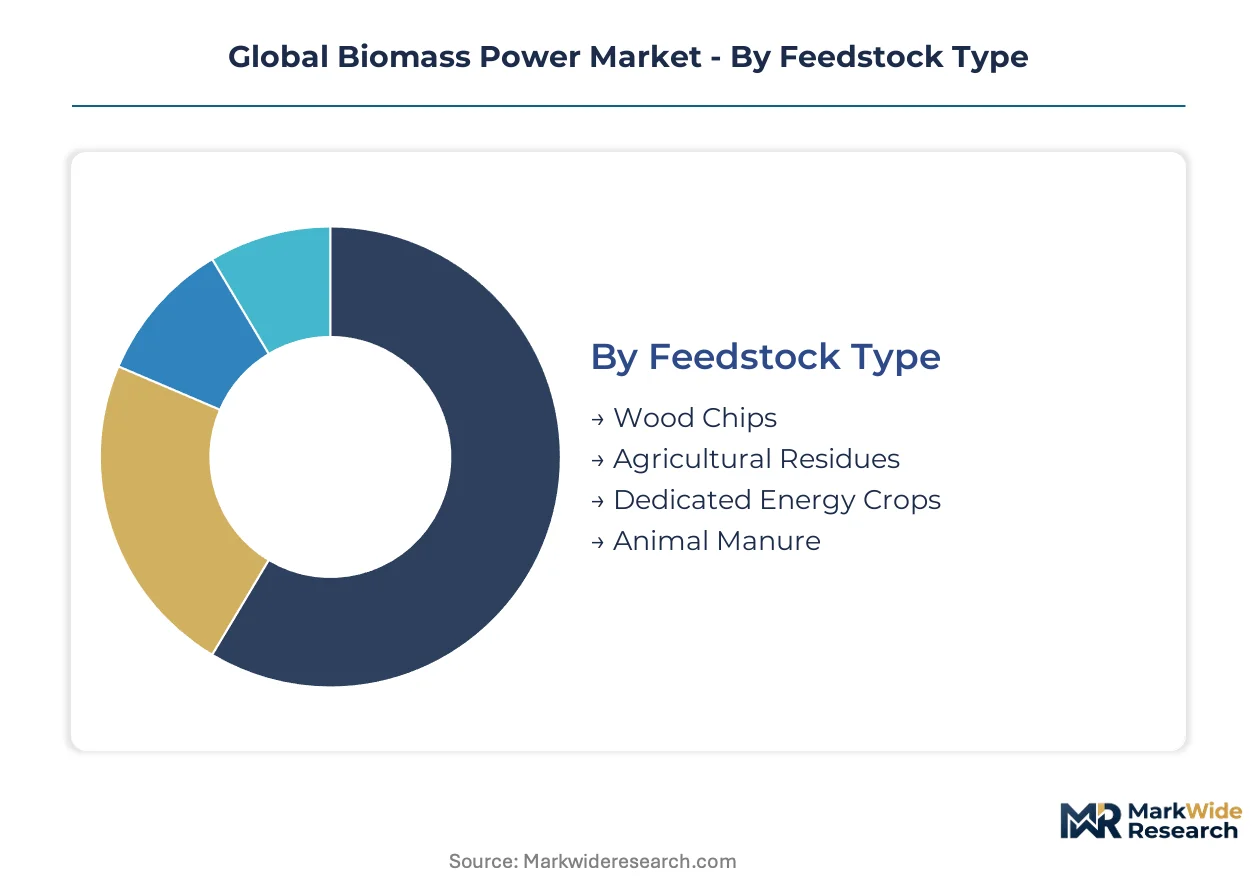
| Segmentation | Feedstock Type: Wood Chips, Agricultural Residues, Dedicated Energy Crops, Animal Manure Technology: Combustion, Gasification, Anaerobic Digestion, Pyrolysis End User: Utilities, Industrial, Commercial, Residential Application: Electricity Generation, Heating, Biofuels, Co-firing |
| Companies Covered | Drax Group, Mitsubishi Heavy Industries, General Electric Company, Xcel Energy Inc, ENGIE, Babcock & Wilcox Enterprises, Ørsted A/S, EDF, Vattenfall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomass Power Market Emerging Trajectories
Technology developers are compressing deployment risk through standardized subsystem designs that reduce site-specific engineering. This standardization wave is enabling faster replication across geographies with heterogeneous feedstock profiles.
Small-scale modular gasification is modularizing distributed power architectures for industrial campuses and municipal utilities. Pulp and paper mills in Finland and Sweden are adopting these units to process onsite bark and sludge residues. The approach is modularizing captive power economics by eliminating long-distance feedstock transport and grid interconnection costs.
The EU's Renewable Energy Directive sustainability criteria are tightening feedstock eligibility to exclude high-indirect-land-use materials. Industrial heat offtakers in Germany and the Netherlands now require mass-balance certification through the entire supply chain. Biomass traders are responding by integrating chain-of-custody software and third-party verification into procurement workflows.
Long-term power purchase agreements are displacing merchant exposure for new project finance. Utility buyers in Japan and the United Kingdom now structure 15-20 year contracts with escalation clauses tied to carbon credit markets. This contracting evolution is most visible in offshore markets where feedstock import dependence requires revenue certainty to secure debt coverage ratios.
Global Biomass Power Market Segmentation
Feedstock heterogeneity and technology maturity create divergent investment profiles across the biomass power value chain. Segment selection determines capital intensity, regulatory exposure, and offtake contract structures for project developers.
Feedstock Type:
Standardization potential varies sharply across this category, from commoditized forestry residues to site-specific agricultural streams requiring customized handling systems.
- Wood Chips:Processed lignocellulosic material with moisture content typically ranging 10-30% enables direct combustion in grate-fired or fluidized bed boilers. Demand concentrates in Scandinavian district heating networks and southeastern United States utility conversions where established harvesting infrastructure delivers predictable supply economics.
- Agricultural Residues:Seasonal biomass streams including wheat straw, corn stover, and rice husk present higher ash and alkali content requiring specialized boiler metallurgy. Brazil's sugarcane bagasse and India's rice husk clusters drive procurement, though collection radius limitations constrain plant scale economics.
- Dedicated Energy Crops:Purpose-grown miscanthus and switchgrass offer supply security through long-term cultivation contracts.
- Animal Manure:Wet organic material with 80-90% moisture content suits anaerobic digestion rather than direct combustion pathways.
Most installed capacity flows through Wood Chips. Expansion is steepest in Agricultural Residues where rural electrification programs incentivize decentralized generation.
Technology:
Cost tiers separate proven combustion systems from emerging thermochemical conversion platforms still seeking scale validation.
- Combustion:Direct firing of solid biomass in stoker, grate, or fluidized bed configurations represents the dominant technology pathway with decades of operational track record. German utilities and Japanese independent power producers favor this approach for baseload renewable output under feed-in tariff regimes.
- Gasification:Partial oxidation of biomass to synthetic gas enables higher efficiency combined cycle operation and chemical synthesis feedstock production. Finnish pulp and paper mills deploy small-scale modular units for captive power from bark and sludge residues.
- Anaerobic Digestion:Microbial decomposition of wet organic matter produces biogas for electricity or biomethane upgrading.
- Pyrolysis:Thermal decomposition in oxygen-limited environments yields bio-oil, syngas, and biochar fractions.
Combustion commands the largest operating fleet. Gasification is climbing the fastest as efficiency advantages attract industrial heat and power integration projects.
End User:
Customer type determines project scale, financing structure, and regulatory compliance burden across the market.
- Utilities:Grid-scale power generators operating assets above 50 MW capacity procure feedstock through long-term supply agreements and structured power purchase contracts. United Kingdom and Japan utility buyers dominate procurement volumes under renewable portfolio standards and feed-in tariff regimes.
- Industrial:Pulp and paper, food processing, and chemical manufacturers deploy captive biomass units to hedge thermal energy costs and meet Scope 1 emissions targets. Swedish and Finnish forest products companies anchor this segment through integrated residue-to-energy systems.
- Commercial:Hospitals, universities, and district heating operators deploy medium-scale systems.
- Residential:Single-home pellet stoves and small boilers represent a fragmented equipment market.
Utilities channel the majority of capital deployment. Industrial self-generation is gaining share fastest as carbon pricing tightens manufacturing cost structures.
Application:
Volume concentration and margin profiles diverge between electricity-focused and thermal-energy applications.
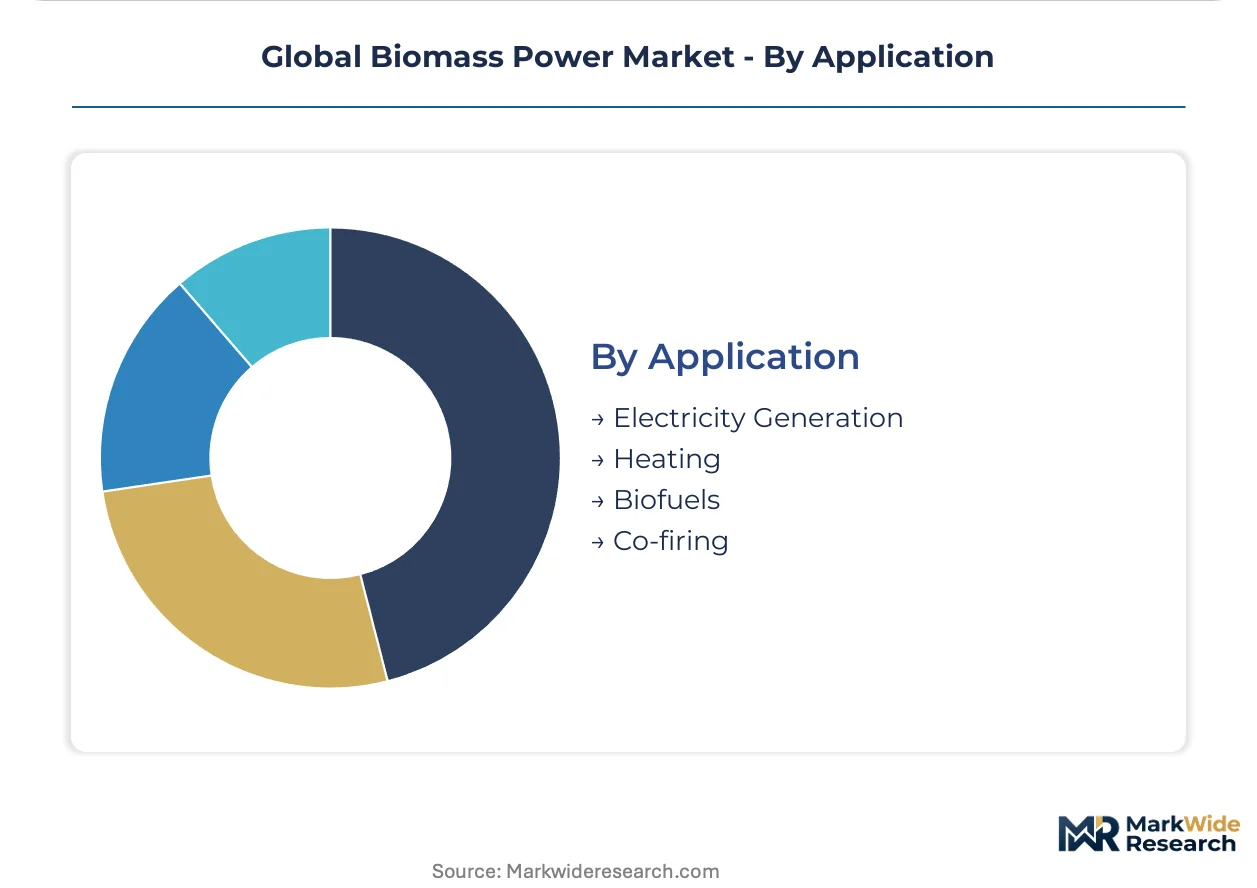
- Electricity Generation:Dedicated biomass power plants and converted coal units feed grid baseload capacity under renewable energy certificates and carbon credit frameworks. Germany, Brazil, and Japan concentrate demand where policy mechanisms reward dispatchable renewable output.
- Co-firing:Blending biomass with coal in existing thermal units reduces carbon intensity without full plant reconstruction. Drax Group's United Kingdom conversions demonstrate this pathway's capital efficiency for legacy generator fleet decarbonization.
- Heating:District heating networks and industrial process heat applications leverage biomass thermal output directly.
- Biofuels:Biomass-to-liquid pathways produce renewable diesel and aviation fuel feedstocks.
Electricity Generation absorbs the largest share of feedstock throughput. Co-firing shows the steepest expansion trajectory as coal plant operators seek compliance pathways with minimal capital outlay.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern biomass power emerged from Scandinavian district heating networks in the 1970s oil crisis, then scaled through German feed-in tariffs and Japanese energy security programs. Today's deployment clusters reflect these historical foundations while expanding into agricultural residue belts and converted coal corridors.
Germany
Industrial heat offtakers in the Rhineland and Bavaria drive demand for certified biomass under the EU Green Deal's Renewable Energy Directive. The Bundesnetzagentur administers auction mechanisms that favor dispatchable renewable capacity. Hamburg and Berlin anchor project development for converted municipal heating plants serving dense urban load centers.
Japan
Energy security imperatives and post-Fukushima baseload replacement needs concentrate procurement in Kanto and Kansai industrial zones. METI's feed-in tariff regime guarantees 20-year offtake prices for imported wood pellet and palm kernel shell projects. The Port of Yokohama and Nagoya Harbor host dedicated biomass import terminals serving converted coal units.
Brazil
Sugarcane bagasse and eucalyptus residue streams in São Paulo and Minas Gerais states enable captive power at mill complexes and grid-scale independent generation. ANEEL regulates distributed generation frameworks that reward rural electrification through agricultural residue valorization. The Ribeirão Preto cluster exemplifies integrated sugar-energy processing at industrial scale.
United States
Southeastern timberland ownership patterns and pulp mill infrastructure in Georgia, Alabama, and Mississippi deliver pellet supply economics for export markets and domestic co-firing. EPA renewable fuel standards and state renewable portfolio standards in California and the Northeast shape compliance demand. The Port of Savannah anchors Atlantic pellet export logistics to European and Asian offtakers.
United Kingdom
Converted coal unit economics under Contracts for Difference mechanisms concentrate activity in Yorkshire and Lincolnshire former mining regions. Ofgem administers sustainability criteria that restrict eligible feedstock to low-indirect-land-use sources. Drax Power Station in North Yorkshire represents the largest single-site biomass conversion delivering baseload renewable output.
Global Biomass Power Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology specialization and feedstock integration depth. The market structures around three tiers: integrated utilities with captive supply chains, engineering contractors with retrofit expertise, and independent power producers relying on merchant feedstock procurement. Strategic moves concentrate on co-firing retrofit partnerships and long-term pellet supply contracting to secure debt financing for project development.
Among engineering and utility conglomerates, Mitsubishi Heavy Industries, General Electric Company, and Drax Group exemplify divergent archetypes. Mitsubishi Heavy Industries occupies a position anchored in advanced boiler manufacturing for varied feedstock profiles. General Electric Company represents the diversified industrial technology tier with power generation equipment spanning multiple fuel pathways. Drax Group sits within the integrated utility archetype, having executed coal-to-biomass conversions that demonstrate capital efficiency for legacy thermal asset decarbonization.
| Leading Market Players |
|---|
| Drax Group |
| Mitsubishi Heavy Industries |
| General Electric Company |
| Xcel Energy Inc |
| ENGIE |
| Babcock & Wilcox Enterprises |
| Ørsted A/S |
| EDF |
| Vattenfall |
| Others |
Supply Flow & Price Mechanics
Wood pellet procurement costs cascade through three distinct pricing tiers shaped by certification grade and volume scale, with EU Renewable Energy Directive compliance premiums separating premium-sustainability feedstock from standard-grade material. Long-term offtake contracts at Japanese utilities under METI feed-in tariffs anchor the premium tier, while merchant procurement in Southeast Asian biomass markets occupies the economy tier with higher price volatility.
Pricing Analysis
Contract-based long-term offtake dominates utility-scale procurement, with price differentiation resting on sustainability certification tier and geographic delivery cost. Premium-tier feedstock commands higher rates where EU mass-balance certification is mandatory. Cost compression in the standard tier is intensifying because pellet supply concentration in the US Southeast and British Columbia creates buyer competition for limited volumes. Industrial self-generators in Scandinavia show least price sensitivity due to captive forestry residue supply, while independent power producers in emerging markets exhibit highest sensitivity to feedstock cost swings.
Supply Chain Analysis
Direct-to-utility long-term contracting handles baseload power demand, with geographic supply concentration in the United States, Canada, and Brazil. Raw material flows draw from southeastern US timberlands, British Columbia sawmill residues, and São Paulo sugarcane bagasse streams. Single-source vulnerability for European and Asian offtakers creates structural risk where Atlantic shipping lanes or Panama Canal congestion disrupt pellet delivery schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Biomass Power Market functions as a geographic-arbitrage play where EU carbon pricing differentials against Japanese energy security premiums create margin capture opportunities for feedstock traders with multi-jurisdictional sourcing networks.
For Market Incumbents: Hedge policy durability risk by diversifying offtake contract jurisdictions beyond single regulatory frameworks. Secure backward integration into pellet production or forestry residue collection networks to defend margins against feedstock cost inflation. Invest in boiler metallurgy R&D for high-alkali agricultural residue combustion as coal plant retrofit demand accelerates. For New Entrants and Emerging Players: Launch via agricultural residue valorization partnerships in Brazil's Ribeirão Preto cluster or India's rice husk belts where collection infrastructure gaps create white-space entry. Target distributed biogas-to-power installations at German and Danish agricultural cooperatives where anaerobic digestion technology remains underdeployed for district heating integration. For Investors and Strategic Acquirers: Consolidation pressure builds where project developers lack captive feedstock supply and face margin compression from certification cost inflation. Frame long-term viability around regulatory durability in jurisdictions with entrenched renewable portfolio standards. Watch for feedstock traceability system cost spikes as EU sustainability criteria tighten as the inflection signal for distressed asset acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Drax Group's pellet contracting model secures debt financing for converted coal units. |
| Backward Integration | Captive forestry residue collection in Scandinavia eliminates merchant feedstock price exposure. |
| Green Certification Program | EU Renewable Energy Directive compliance unlocks premium pricing in German and Dutch markets. |
| Technology Licensing | Mitsubishi Heavy Industries boiler designs transfer high-moisture feedstock handling capability. |
| Joint Venture | Finnish pulp mill gasification partnerships demonstrate modular captive power economics. |
Methodological Framework
Bottom-up utility procurement modeling reconciled against top-down feedstock production tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists were cross-validated against EIA data, IEA reports, FERC filings, and project development databases. Secondary sources include EU Renewable Energy Directive implementation documents, METI feed-in tariff administration records, and ANEEL distributed generation frameworks.
Historical trendline analysis of installed capacity additions and feedstock trade flows established baseline growth patterns across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, regulatory framework, and regional grid type dimensions. CAGRs were derived from capacity deployment trajectories and feedstock cost evolution assumptions, with carbon credit market pricing and policy durability scenarios as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon accounting disputes or feedstock certification timeline extensions. Periodic stress-testing of base assumptions is recommended given contested biomass neutrality classifications and potential regulatory framework revisions in major demand jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Energy Harvesting Trees Market