
 Solar Bio-Gas Hybrid Power System Market | 2026-2036
Solar Bio-Gas Hybrid Power System Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Bio-Gas Hybrid Power System Market Analytics
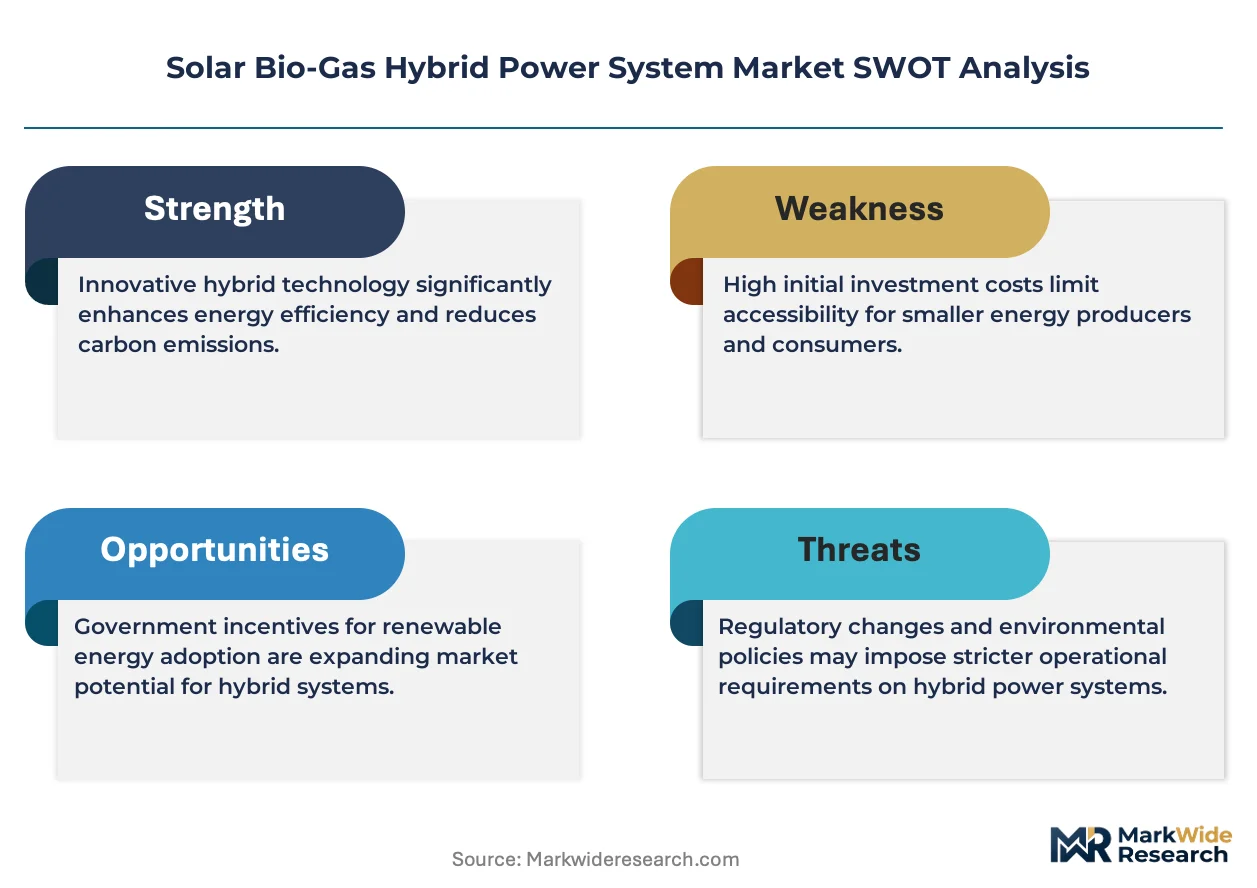
The capital-intensity divergence between integrated energy conglomerates and specialized hybrid developers is unwinding competitive dynamics across the sector. Schneider Electric leverages its power-electronics heritage to dominate inverter and grid-integration architecture for multi-megawatt installations. Husk Power Systems anchors its model with decentralized mini-grid deployment across rural agricultural clusters, competing on deployment speed rather than scale. Siemens Gamesa sustains technology leadership through its wind-solar-biogas hybrid expertise, extending capabilities into combined heat-and-power configurations.
A solar bio-gas hybrid power system integrates photovoltaic arrays with anaerobic-digestion-derived biogas generators, synchronized through common inverters and battery buffers to deliver dispatchable baseload from intermittent solar irradiance. Typical configurations pair 50-500 kW solar capacity with equivalent biogas generation, achieving capacity factors above 65% versus sub-25% for standalone solar. Grid-tied technology leads installed capacity given favorable feed-in mechanisms, though off-grid hybrid systems represent the fastest-expanding segment as island communities and remote processing facilities seek fuel independence. Energy storage systems command disproportionate margin pools due to lithium-ion supply constraints and the technical complexity of managing dual-source charge cycling protocols.
The EU Green Deal and F-Gas Regulation shape equipment standards across European deployment corridors, while India's CEA mandates grid-code compliance for hybrid interconnections above 250 kW. The US EPA and state-level renewable portfolio standards in California and Texas create divergent compliance pathways that fragment procurement specifications. Stakeholders must monitor regulatory alignment between agricultural methane-capture incentives and power-sector decarbonization mandates to anticipate subsidy stacking opportunities.
Market Dynamics
The EU Green Deal's methane-emission caps are compressing deployment timelines for agricultural hybrid installations as dairy and poultry operators race to capture biogas value before penalty regimes activate. This regulatory pressure is synchronizing capital flows across power-electronics, anaerobic-digestion engineering, and rural grid infrastructure.
Growth Catalysts
- EU Green Deal methane penalties:Germany and Denmark are accelerating farm-level digester installations to preempt agricultural emission fines. Dairy cooperatives now treat biogas capture as compliance infrastructure.
- India's national bioenergy mission:State-level rural electrification programs are consolidating procurement for village-scale hybrid mini-grids. The CEA's grid-code mandate above 250 kW is standardizing interconnection protocols.
- Lithium-ion supply constraints:Battery-buffer shortages are elevating margins for system integrators with captive energy storage partnerships. Dual-source charge cycling expertise is becoming a scarce technical asset.
Market Restraints
- Capital intensity for anaerobic digesters:Farm-scale digester construction requires 18-24 month payback horizons that strain agricultural balance sheets. Debt financing remains concentrated among integrated energy conglomerates.
- F-Gas Regulation equipment standards:European heat-and-power configurations face refrigerant-phaseout compliance costs that inflate inverter and cooling system specifications.
- Biogas supply intermittency:Seasonal feedstock variation limits capacity factor guarantees for standalone biogas generators, compressing project finance terms.
Strategic Opportunities
- Island community fuel independence:Off-grid hybrid systems represent deployment white space as remote processing facilities seek insulation from diesel price volatility. Mediterranean and Caribbean archipelagos lack incumbent mini-grid operators.
- Combined heat-and-power convergence:Integration of absorption chilling and district heating is opening industrial food-processing applications beyond power sales.
- California renewable portfolio standards:The state's dairy methane reduction targets are creating subsidy-stacking potential between agricultural capture incentives and power-sector decarbonization mandates.
Industry Challenges
- Grid-code certification timelines:CEA compliance documentation for hybrid interconnections above 250 kW extends project commissioning by 4-6 months, compressing developer working capital cycles.
- Dual-source control engineering scarcity:Technicians capable of synchronizing photovoltaic ramp rates with biogas generator dispatch curves command premium compensation that inflates OPEX budgets.
- Legacy diesel backup integration:Remote installations must maintain redundant fossil capacity for biogas digester downtime, complicating carbon-accounting claims and green financing eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Bio-Gas Hybrid Power System Market |
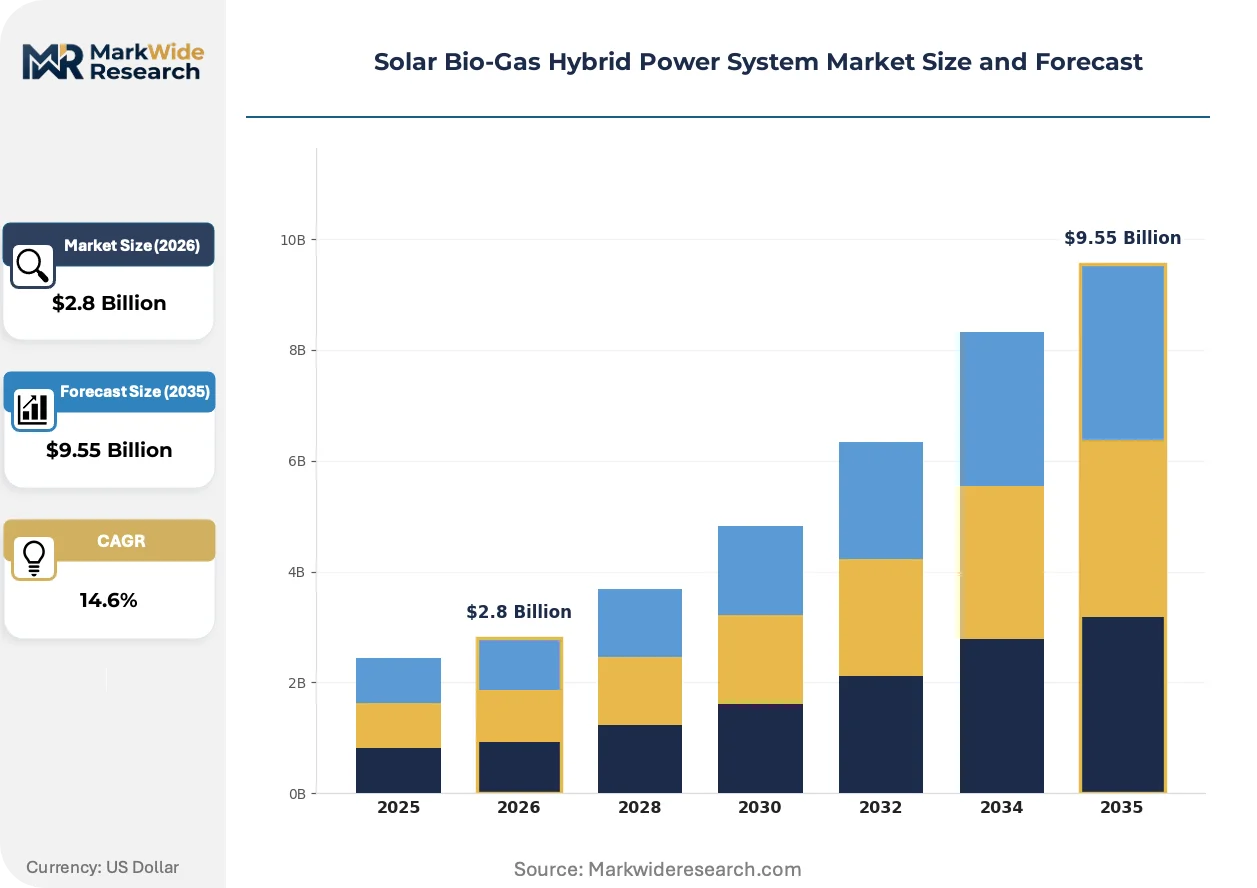
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Biogas Generators, Inverters, Energy Storage Systems Application: Agriculture, Residential, Commercial, Industrial End User: Farmers, Energy Providers, Manufacturing Units, Households Technology: Grid-Tied, Off-Grid, Smart Meters, Hybrid Systems |
| Companies Covered | SMA Solar Technology, Eaton Corporation, Schneider Electric, Siemens Gamesa, General Electric Company, GE Renewable Energy, Husk Power Systems, Iberdrola, Kestrel Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Bio-Gas Hybrid Power System Market Evolving Landscape
Solid-state inverters with silicon-carbide switching architectures are compressing power-conversion losses and enabling tighter synchronization between photovoltaic and biogas generator output. This hardware evolution is reshaping competitive positioning among grid-integration specialists.
Silicon-carbide inverter modules are supplanting conventional IGBT architectures in multi-megawatt hybrid installations. German and Danish agricultural energy cooperatives are adopting these units at 40% annual replacement rates for retrofit projects. The technology is enabling capacity factor improvements above 70% while compressing thermal management footprints by half.
The EU F-Gas Regulation's refrigerant-phaseout schedule is forcing heat-and-power system redesigns across European deployment corridors. Equipment manufacturers must substitute hydrofluorocarbon cooling loops with ammonia or CO2-based alternatives, inflating engineering validation cycles by 8-12 months. Combined heat-and-power configurations for Nordic district heating networks are absorbing the highest compliance costs.
Agricultural cooperatives are consolidating procurement through equipment-leasing structures that unbundle energy storage ownership from generation assets. Danish dairy associations pioneered this model; Indian state-level rural electrification programs are now replicating it. The shift transfers battery degradation risk to financial lessors while accelerating farmer adoption timelines.
Solar Bio-Gas Hybrid Power System Market Segmentation
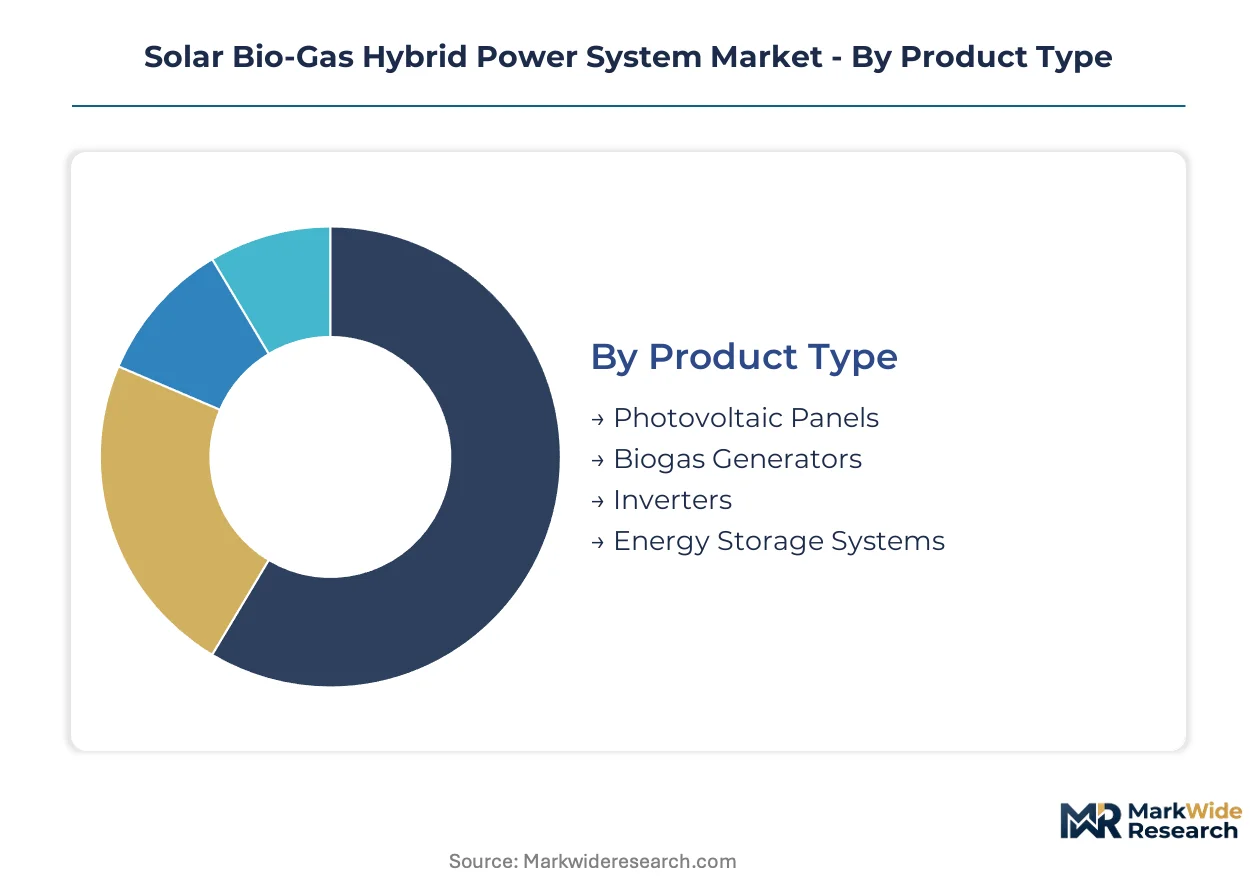
Technology configuration and end-use application determine capital deployment patterns across the solar bio-gas hybrid power system market. Procurement specifications diverge sharply between grid-tied agricultural installations and off-grid rural electrification programs.
Product Type:
Photovoltaic panels and biogas generators anchor domestic production clusters in Germany and India, while inverters and energy storage systems rely on concentrated Asian manufacturing for power electronics.
- Photovoltaic Panels:Crystalline silicon arrays rated 50-500 kW form the solar generation backbone. Dairy cooperatives in Denmark specify these for farm-level hybrid installations under EU Green Deal compliance timelines.
- Biogas Generators:Anaerobic-digestion-fed reciprocating engines synchronize with solar output through common inverters. German agricultural energy cooperatives deploy these to capture methane value before penalty regimes activate.
- Inverters:Silicon-carbide switching architectures are supplanting conventional IGBT modules in multi-megawatt installations.
- Energy Storage Systems:Lithium-ion battery buffers manage dual-source charge cycling protocols for dispatchable baseload delivery.
Photovoltaic panels and biogas generators command the established base. The steepest expansion runs through energy storage systems.
Application:
Cost tier stratification separates subsidy-dependent agricultural deployments from premium commercial installations seeking carbon accounting validation.
- Agriculture:Farm-scale digesters paired with solar arrays achieve capacity factors above 65% versus sub-25% for standalone solar. India's national bioenergy mission concentrates procurement for village-scale hybrid mini-grids in this segment.
- Industrial:Combined heat-and-power configurations integrate absorption chilling and district heating for food-processing applications beyond power sales.
- Commercial:Grid-tied installations serve processing facilities seeking insulation from diesel price volatility.
- Residential:Off-grid hybrid systems address rural electrification gaps in agricultural clusters.
Agriculture commands the established base. The steepest expansion runs through industrial combined heat-and-power convergence.
End User:
Customer type determines financing structure, with energy providers leveraging equipment-leasing models that unbundled battery ownership from generation assets.
- Farmers:Dairy and poultry operators across Germany and Denmark treat biogas capture as compliance infrastructure. Danish dairy associations pioneered equipment-leasing structures now replicated by Indian state-level rural electrification programs.
- Energy Providers:Integrated conglomerates dominate multi-megawatt installations through captive project finance capacity. Schneider Electric leverages power-electronics heritage for grid-integration architecture in this customer tier.
- Manufacturing Units:Remote processing facilities seek fuel independence through off-grid hybrid configurations.
- Households:Rural agricultural clusters access village-scale mini-grids through consolidated procurement programs.
Energy providers command the established base. The steepest expansion runs through farmers facing tightening methane-emission caps.
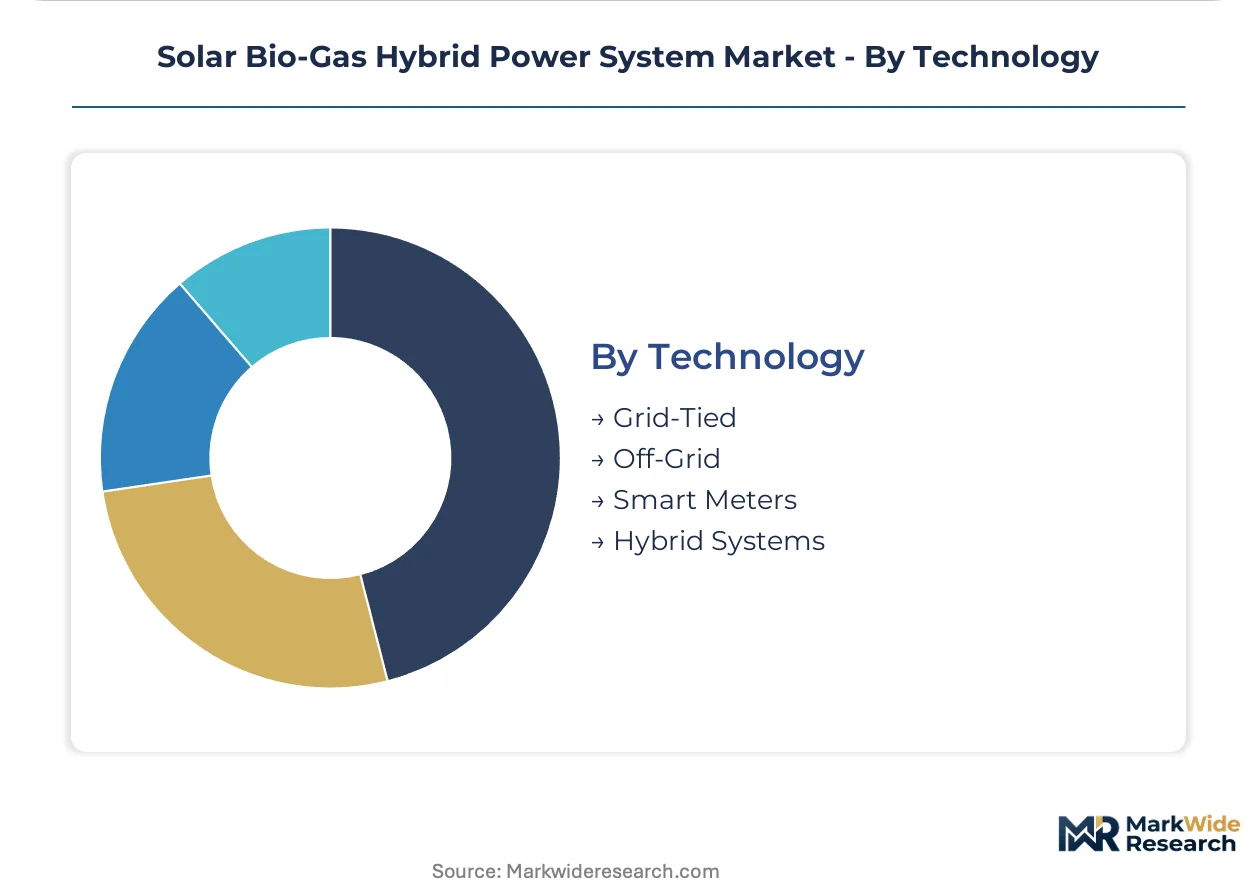
Technology:
Maturity stage separates proven grid-tied architectures from emerging smart metering and advanced hybrid control systems.
- Grid-Tied:Synchronized photovoltaic and biogas output feeds distribution networks under feed-in mechanisms. India's CEA mandates grid-code compliance for hybrid interconnections above 250 kW in this configuration.
- Off-Grid:Island communities and remote processing facilities deploy standalone systems with battery buffers for fuel independence. Mediterranean and Caribbean archipelagos lack incumbent mini-grid operators in this segment.
- Smart Meters:Dual-source monitoring systems track photovoltaic ramp rates and biogas generator dispatch curves for optimized charge cycling.
- Hybrid Systems:Integrated control platforms synchronize variable solar irradiance with biogas dispatchability through common inverters.
Grid-tied technology commands the established base. The steepest expansion runs through off-grid systems addressing diesel price volatility in remote installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys solar bio-gas hybrid systems primarily for agricultural methane compliance, whereas India channels identical technology toward village-scale rural electrification with fundamentally different financing structures.
Germany
Dairy cooperatives in Lower Saxony and Bavaria accelerate digester installations to capture biogas value before EU Green Deal penalty regimes activate. The F-Gas Regulation forces refrigerant-phaseout redesigns across heat-and-power configurations. Agricultural energy clusters around Oldenburg and Münster pioneer silicon-carbide inverter retrofits at 40% annual replacement rates.
Denmark
Poultry and dairy operators treat biogas capture as compliance infrastructure under tightening agricultural emission caps. Danish dairy associations pioneered equipment-leasing structures that unbundle battery ownership from generation assets. Farm-scale hybrid deployments concentrate on Jutland Peninsula agricultural cooperatives.
India
The national bioenergy mission consolidates procurement for village-scale hybrid mini-grids across rural agricultural clusters. CEA grid-code mandates above 250 kW standardize interconnection protocols for state-level rural electrification programs. Maharashtra and Gujarat state programs replicate Danish equipment-leasing models to accelerate farmer adoption timelines.
United States
California's dairy methane reduction targets create subsidy-stacking potential between agricultural capture incentives and power-sector decarbonization mandates. EPA oversight intersects with state-level renewable portfolio standards to fragment procurement specifications. Central Valley dairy operations deploy hybrid configurations to preempt regulatory penalties.
United Kingdom
Farm-scale anaerobic digestion receives support through the country's environmental land management schemes. Grid integration standards from the national energy regulator shape equipment specifications for agricultural hybrid installations. East Anglia and Yorkshire dairy clusters expand digester capacity to capture methane value.
Solar Bio-Gas Hybrid Power System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the solar bio-gas hybrid power system market. Integrated energy conglomerates leverage captive project finance capacity for multi-megawatt installations, while specialized hybrid developers compete on deployment speed across decentralized agricultural clusters. Strategic archetypes separate power-electronics heritage players from mini-grid deployment specialists and wind-solar-biogas hybrid integrators. Dominant competitive moves include strategic partnerships for lithium-ion supply security and geographic expansion into island community off-grid segments.
Among power-electronics specialists, SMA Solar Technology and Eaton Corporation exemplify the inverter and grid-integration architecture tier. Schneider Electric occupies a position representing integrated conglomerate leverage across multi-megawatt installations. Siemens Gamesa anchors the wind-solar-biogas hybrid expertise segment, while Husk Power Systems exemplifies decentralized mini-grid deployment specialists competing on rural deployment velocity rather than scale.
| Leading Market Players |
|---|
| SMA Solar Technology |
| Eaton Corporation |
| Schneider Electric |
| Siemens Gamesa |
| General Electric Company |
| GE Renewable Energy |
| Husk Power Systems |
| Iberdrola |
| Kestrel Renewable Energy |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German dairy cooperatives and inverter manufacturers lock in silicon-carbide module supply while fixing energy storage pricing across 18-24 month deployment cycles. These arrangements transfer lithium-ion volatility risk to project financiers and stabilize farmer balance sheets under EU Green Deal compliance timelines.
Pricing Analysis
After-sales service contracts for dual-source control engineering drive lifetime value for system integrators. Three-tier pricing structure across premium, standard, and economy levels separates CEA-certified grid-tied installations from off-grid village mini-grids. Cost compression in battery buffers intensifies because lithium-ion supply constraints elevate raw material pass-throughs. Agricultural cooperatives in Denmark exhibit highest price sensitivity due to equipment-leasing structures, while industrial food processors absorb premium tiers for combined heat-and-power configurations.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for silicon-carbide inverter modules manufactured in China and South Korea. Crystalline silicon wafers draw from Malaysian and Vietnamese processing clusters, while anaerobic-digestion engineering equipment sources from German fabrication hubs. Single-source vulnerability concentrates in lithium-ion cell production. Distribution runs through state-level rural electrification procurement programs in India and agricultural energy cooperative networks across Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar bio-gas hybrid power systems occupy an early-cycle expansion phase, with EU Green Deal methane penalties accelerating farm-level adoption ahead of penalty regime activation.
For Market Incumbents: Fortify captive energy storage partnerships against lithium-ion supply fragmentation. Deepen backward integration into silicon-carbide switching architectures to defend margin position from Asian power-electronics specialists. Expand CEA grid-code certification capacity to compress 4-6 month commissioning delays that strain developer working capital. For New Entrants and Emerging Players: Lead with off-grid deployment velocity across Mediterranean and Caribbean archipelagos lacking incumbent mini-grid operators. Target island community fuel independence segments where diesel price volatility creates immediate payback visibility. Pursue equipment-leasing structures that unbundle battery ownership to accelerate farmer adoption timelines. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid control engineering specialists with dual-source synchronization capabilities. Over the projection horizon, acquisition targets cluster around technicians commanding premium compensation for photovoltaic-biogas dispatch curve management. Watch silicon-carbide inverter retrofit penetration rates in German agricultural energy cooperatives as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Inverter Retrofit Program | German dairy cooperatives achieve 40% annual replacement rates for thermal management compression. |
| Equipment-Leasing Structure Replication | Indian state programs adopt Danish dairy association models to accelerate rural electrification procurement. |
| CEA Grid-Code Certification Expansion | Standardized interconnection protocols above 250 kW compress project commissioning timelines. |
| Lithium-Ion Supply Partnership | Captive battery buffer agreements stabilize margins against raw material pass-through volatility. |
| Island Community Mini-Grid Deployment | Mediterranean and Caribbean archipelagos offer white-space expansion without incumbent competition. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and agricultural cooperative managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EIA data, IEA renewable energy reports, FERC interconnection filings, and EU Green Deal implementation trackers. Bottom-up installation databases triangulated against top-down regulatory mandate analysis.
Consistency checks against external benchmarks validated capacity deployment trajectories across the analysis window. The analytical framework modeled segmentation by generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derived from compound growth logic applied to verified base-year installations and policy-mandated deployment floors. Biogas feedstock availability curves and solar irradiance patterns informed capacity factor assumptions.
Forecasts assume regulatory continuity in EU Green Deal methane penalty regimes and India's CEA grid-code mandates; material policy shifts would require re-modeling. Specific risks include F-Gas Regulation refrigerant-phaseout delays, lithium-ion supply disruption, and agricultural commodity price volatility affecting digester economics. Recalibration cycles align with material shifts in subsidy stacking opportunities and silicon-carbide inverter adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Biomass Power Generation Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market