
 Biomass Power Generation Market | 2026-2036
Biomass Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Power Generation Market Analysis
Plant operator expertise in combined heat and power systems is bifurcating the competitive landscape between legacy utilities and specialized bioenergy developers. Drax Group plc leverages its port and storage infrastructure to control Atlantic basin wood pellet flows. Enviva Partners, LP anchors industrial procurement contracts with Japanese and European power buyers. Ørsted A/S competes through integrated biomass-heat networks serving Danish district heating cooperatives.
Biomass power generation converts organic feedstock into thermal energy for electricity or combined heat and power output, typically operating at 20-40% electrical efficiency in modern grate-fired or fluidized bed combustion systems. Wood pellets dominate international trade flows due to standardized moisture content below 10% and bulk handling compatibility. Combustion technology occupies the mature baseline, while gasification and pyrolysis represent higher-margin growth vectors for distributed and chemical-production applications. Agricultural residues and dedicated energy crops concentrate supply development in regions with established forestry or farming infrastructure.
The EU Green Deal and F-Gas Regulation shape feedstock sustainability certification requirements across European offtake markets. EPA renewable fuel standards and state-level renewable portfolio standards in the US govern eligibility for biomass power in compliance markets. Japan's METI feed-in-tariff framework and South Korea's renewable portfolio standard drive procurement volume in Northeast Asia. Stakeholders must monitor evolving carbon accounting methodologies that could recategorize certain biomass pathways in national emissions inventories.
Market Dynamics
Wood pellet supply chains are consolidating around Atlantic basin port infrastructure, concentrating procurement leverage among vertically integrated terminal operators and compressing margins for independent biomass traders.
Growth Catalysts
- EU Green Deal sustainability mandates:Tightening feedstock certification requirements under the Renewable Energy Directive are redirecting European utility procurement toward verified low-carbon supply chains.
- Japan METI feed-in-tariff framework:Guaranteed 20-year power purchase agreements for biomass conversions are accelerating coal-to-biomass retrofits among Japanese regional utilities.
- Fluidized bed combustion technology:Higher-efficiency thermal conversion systems are expanding viable feedstock acceptance to lower-grade agricultural residues and herbaceous crops.
Market Restraints
- Feedstock cost volatility:Weather-driven forestry harvest cycles and competing pulp mill demand create input price instability for wood pellet producers.
- Atlantic basin supply concentration:US Southeast and Canadian British Columbia forestry regions dominate export pellet production, creating geographic single-source risk.
- Carbon accounting uncertainty:Evolving lifecycle assessment methodologies under the IPCC may recategorize certain biomass combustion pathways in national emissions inventories.
Strategic Opportunities
- South Korea RPS compliance demand:Renewable portfolio standard penalties for non-compliance are forcing KEPCO and independent generators toward long-term biomass offtake contracts.
- Pyrolysis-oil co-firing applications:Bio-oil derived from fast pyrolysis of forest residues offers drop-in compatibility with existing heavy fuel oil infrastructure.
- District heating network expansion:Scandinavian municipal energy cooperatives are retrofitting natural gas boilers to accept wood chip and pellet feedstocks for baseload thermal supply.
Industry Challenges
- Sustainability certification complexity:Multi-standard compliance across FSC, PEFC, and SBP schemes extends procurement timelines and raises audit costs for biomass traders.
- Combined heat and power engineering talent scarcity:Specialized expertise in thermal integration design for industrial-scale bioenergy plants concentrates among legacy Nordic and German engineering consultancies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Power Generation Market |
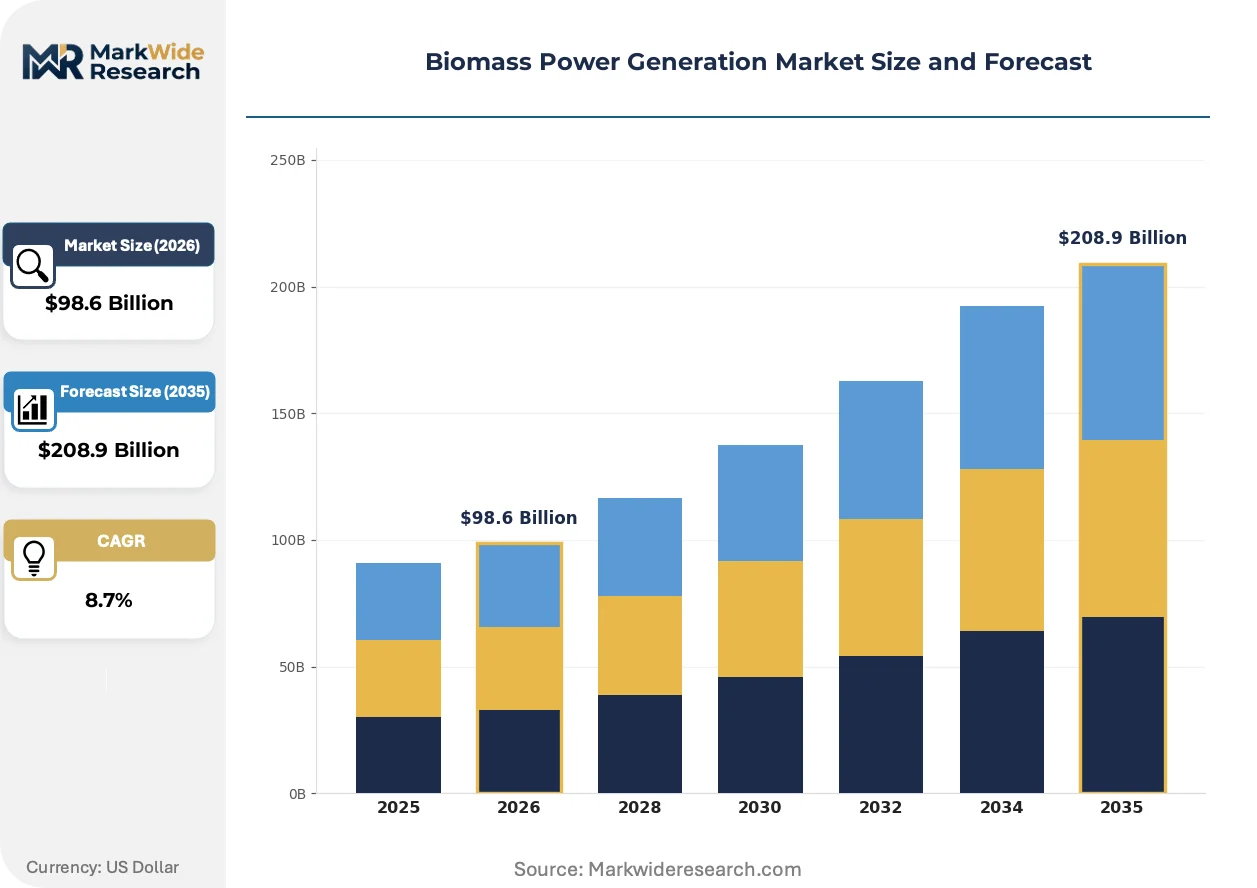
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Wood Pellets, Agricultural Residues, Dedicated Energy Crops, Industrial Waste Technology: Combustion, Gasification, Anaerobic Digestion, Pyrolysis End User: Utilities, Industrial Sector, Commercial Sector, Bioenergy Producers Application: Electricity Generation, Heat Generation, Combined Heat and Power, Biofuels Production |
| Companies Covered | Drax Group plc, Ørsted A/S, Enviva Partners, LP, Babcock & Wilcox Enterprises, Inc., ENGIE, Xcel Energy Inc., Ameresco Inc., Vattenfall AB, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Power Generation Market Emerging Trajectories
Biomass power technology trajectories are diverging between mature combustion baseload systems and higher-margin thermochemical conversion platforms targeting chemical production and distributed generation niches.
Gasification reactor designs are fragmenting across multiple commercial pathways. Dual-fluidized bed systems from Austrian and German engineering firms achieve higher syngas quality for methanol and hydrogen synthesis. Japanese industrial consortia are piloting oxygen-blown entrained flow gasifiers for ammonia co-production. This technology divergence is fragmenting equipment vendor market share and complicating utility technology selection processes.
The EU F-Gas Regulation is tightening emissions monitoring requirements for biomass power stations using synthetic refrigerants in cooling cycles. Industrial operators must retrofit or replace fluorinated gas systems with natural refrigerant alternatives. Scandinavian district heating networks are responding fastest, driven by overlapping national carbon tax and EU compliance obligations.
Japanese power utilities are consolidating procurement through multi-year offtake agreements with dedicated biomass trading houses, displacing spot-market purchasing. Trading houses are responding by acquiring pellet production assets and terminal infrastructure. This buyer concentration is most visible in the Kyushu and Chubu regional power markets, where coal retirement schedules are most aggressive.
Biomass Power Generation Market Segmentation
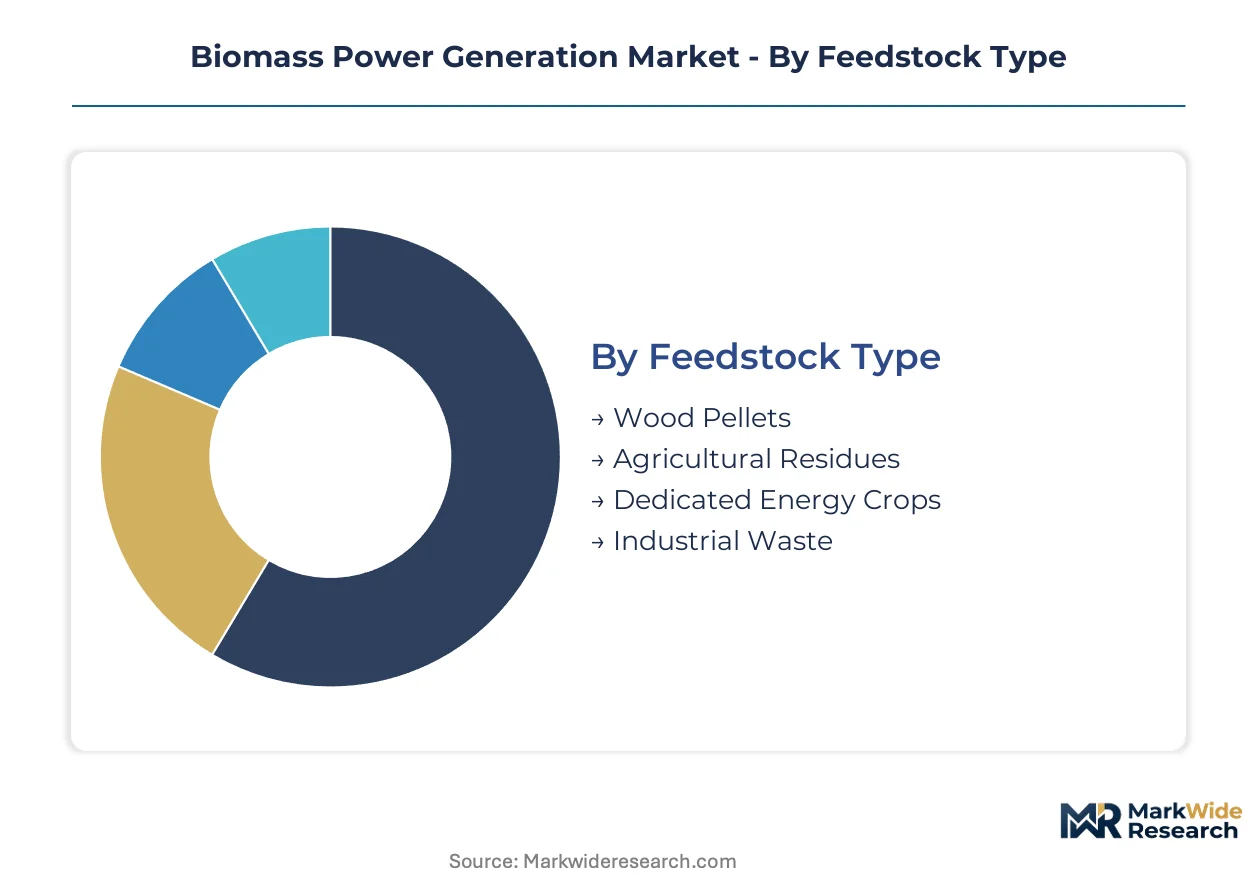
Feedstock quality, conversion efficiency, and end-use thermal requirements fragment procurement economics across the biomass power value chain. Technology selection and application pairing determine project returns more than scale alone.
Feedstock Type:
Margin pools concentrate in low-moisture, high-density feedstocks that minimize transport cost per unit energy and satisfy sustainability certification thresholds for premium offtake markets.
- Wood Pellets:Densified woody biomass with standardized moisture content below 10% enables bulk handling compatibility and long-distance ocean freight. Demand concentrates in Japanese and South Korean coal-to-biomass conversion projects where METI feed-in-tariffs and RPS compliance penalties guarantee offtake pricing. Drax Group and Enviva Partners control Atlantic basin terminal infrastructure, compressing trader margins.
- Agricultural Residues:Field residues including straw, corn stover, and rice husks offer lower feedstock cost but higher handling complexity and variable ash content. Fluidized bed combustion systems in Denmark and agricultural processing clusters in India expand viable acceptance, though supply seasonality constrains year-round operations.
- Dedicated Energy Crops:Short-rotation coppice and perennial grasses deliver purpose-grown supply security. Miscanthus and switchgrass development concentrates on marginal farmland in the UK and Poland where EU Common Agricultural Policy supports cultivation.
- Industrial Waste:Food processing residues, paper mill sludge, and forestry processing byproducts provide negative-cost feedstock streams. Pulp mill integration in Sweden and palm oil processing in Malaysia anchor captive supply networks.
Wood Pellets holds installed capacity. Agricultural Residues is rotating up the share rankings.
Technology:
Technology selection tracks application requirements — baseload electricity favors mature combustion, while chemical production and distributed generation reward thermochemical conversion premiums.
- Combustion:Grate-fired and fluidized bed systems dominate utility-scale deployment with 20-40% electrical efficiency. Scandinavian district heating networks and Japanese regional utilities anchor equipment demand, though technology vendors fragment across Austrian, German, and Nordic engineering consultancies.
- Gasification:Partial oxidation produces syngas for methanol, hydrogen, or ammonia synthesis. Dual-fluidized bed designs from Austrian firms and oxygen-blown entrained flow pilots by Japanese industrial consortia fragment commercial pathways, complicating utility technology selection.
- Anaerobic Digestion:Microbial decomposition of wet organic waste yields biogas for electricity or pipeline injection. Agricultural clusters in Germany and wastewater treatment facilities in Denmark concentrate deployment, constrained by feedstock moisture requirements.
- Pyrolysis:Fast pyrolysis of forest residues produces bio-oil for drop-in heavy fuel oil co-firing. Refinery compatibility trials in the Netherlands and power station retrofits in Japan expand addressable market, though upgrading costs limit scale.
Combustion retains the largest installed base. Gasification is climbing the fastest on chemical production co-location.
End User:
Customer type determines project scale, financing structure, and regulatory compliance pathway — utilities prioritize baseload substitution, while industrial users value thermal integration.
- Utilities:Regional power companies in Japan and South Korea execute coal-to-biomass retrofits under guaranteed tariff structures. Long-term offtake concentration through dedicated trading houses displaces spot procurement in Kyushu and Chubu markets.
- Industrial Sector:Pulp and paper, food processing, and chemical manufacturers deploy captive CHP for process steam and power. Danish industrial clusters and Swedish forestry complexes lead thermal integration engineering.
- Commercial Sector:Hospitals, universities, and district heating cooperatives operate sub-10MW installations. Scandinavian municipal energy cooperatives retrofit natural gas boilers for wood chip acceptance.
- Bioenergy Producers:Independent power producers and biogas upgrading facilities sell into compliance markets. UK renewable obligation certificates and German EEG tariffs anchor revenue visibility.
Utilities dominate capacity additions. Industrial Sector is gaining share fastest on captive thermal demand.
Application:
Application pairing with feedstock and technology determines project economics — electricity-only plants compete on grid parity, while CHP captures thermal value streams.
- Electricity Generation:Standalone power plants feed grid baseload or peak shaving. Japanese coal retrofits and UK Drax conversion anchor large-scale deployment, exposed to carbon accounting methodology revisions under IPCC lifecycle assessments.
- Heat Generation:Dedicated thermal supply serves district heating networks and industrial process heat. Scandinavian municipal cooperatives and Estonian district heating systems lead wood chip boiler deployment.
- Combined Heat and Power:Cogeneration captures 80-90% total energy efficiency through thermal integration. Danish engineering expertise concentrates in legacy Nordic consultancies, creating talent scarcity for project development.
- Biofuels Production:Biogas upgrading to biomethane and bio-oil refining for transport fuel expand beyond power markets. Dutch bio-LNG terminals and German biomethane injection networks anchor infrastructure.
Electricity Generation holds installed capacity. Combined Heat and Power is expanding most quickly on efficiency premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes biomass feedstock primarily for coal-to-biomass power retrofits, while Scandinavian markets prioritize district heating thermal integration, and South Korean procurement concentrates on renewable portfolio standard compliance.
Japan
Kyushu Electric Power and Chubu Electric Power accelerate coal plant conversions under METI's 20-year feed-in-tariff guarantees. The Ministry of Economy, Trade and Industry (METI) mandates biomass sustainability certification for tariff eligibility. Industrial trading houses in Tokyo and Osaka are acquiring pellet production assets to secure long-term supply.
United Kingdom
Drax Power Station anchors Atlantic basin wood pellet demand for baseload electricity substitution. The UK Renewable Obligation Certificate scheme and EU Green Deal sustainability criteria govern feedstock eligibility. Yorkshire and Humberside host the country's largest biomass conversion infrastructure.
Denmark
Municipal energy cooperatives retrofit natural gas boilers for wood chip and pellet acceptance in district heating networks. The Danish Energy Agency enforces strict sustainability standards under EU renewable energy directives. Aarhus and Copenhagen lead thermal infrastructure deployment.
South Korea
KEPCO and independent generators face renewable portfolio standard penalties that force long-term biomass offtake contracting. The Ministry of Trade, Industry and Energy (MOTIE) administers RPS compliance mechanisms. Busan and Ulsan concentrate coal-to-biomass retrofit activity.
Sweden
Pulp mill integration and forestry processing byproducts anchor captive biomass supply networks. The Swedish Energy Agency implements EU F-Gas Regulation emissions monitoring for biomass cooling systems. Stockholm and Gothenburg district heating cooperatives lead wood chip boiler deployment.
Biomass Power Generation Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in biomass power generation. Vertically integrated terminal operators control Atlantic basin wood pellet flows, while specialized bioenergy developers concentrate engineering expertise in combined heat and power systems. Equipment vendors fragment across Austrian, German, and Nordic engineering consultancies. Competitive moves center on port infrastructure acquisition and long-term offtake contracting with Asian utilities.
Within the integrated infrastructure tier, Drax Group plc and Enviva Partners, LP represent Atlantic basin supply chain control through terminal and storage assets. Ørsted A/S occupies a position exemplifying district heating network integration. These three entities anchor distinct competitive vectors: transoceanic feedstock logistics, industrial procurement contracting, and municipal thermal utility partnerships.
| Leading Market Players |
|---|
| Drax Group plc |
| Ørsted A/S |
| Enviva Partners, LP |
| Babcock & Wilcox Enterprises, Inc. |
| ENGIE |
| Xcel Energy Inc. |
| Ameresco Inc. |
| Vattenfall AB |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Scale economies at Atlantic basin pellet terminals compress unit logistics costs while simultaneously concentrating procurement leverage among integrated operators who then dictate price floors for independent traders serving Japanese and South Korean utilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between Japanese trading houses and Atlantic basin pellet producers, displacing spot-market purchasing and stabilizing revenue visibility for terminal operators. Price differentiation hinges on sustainability certification tier under SBP or FSC schemes and guaranteed delivery windows to Northeast Asian ports. Cost compression in standard-grade pellets is intensifying because Drax and Enviva's terminal control limits third-party access to premium logistics slots. Industrial utilities with METI-backed purchase agreements exhibit lowest price sensitivity, while independent biomass traders without captive production face margin erosion.
Supply Chain Analysis
Strategic stockpiling of wood pellets at Rotterdam, Amsterdam, and Chesapeake Bay terminals buffers seasonal harvest fluctuations and ocean freight scheduling constraints. Geographic supply concentrates in the US Southeast, Canadian British Columbia, and the Baltic states where forestry infrastructure feeds densification plants. Raw material dependencies include sawmill residues, pulp-grade roundwood, and drying energy for moisture reduction. Single-source vulnerability runs through the US Southeast where hurricane disruption can idle multiple export terminals simultaneously. Distribution runs through vertically integrated terminal operators who control both inbound rail logistics and outbound vessel chartering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
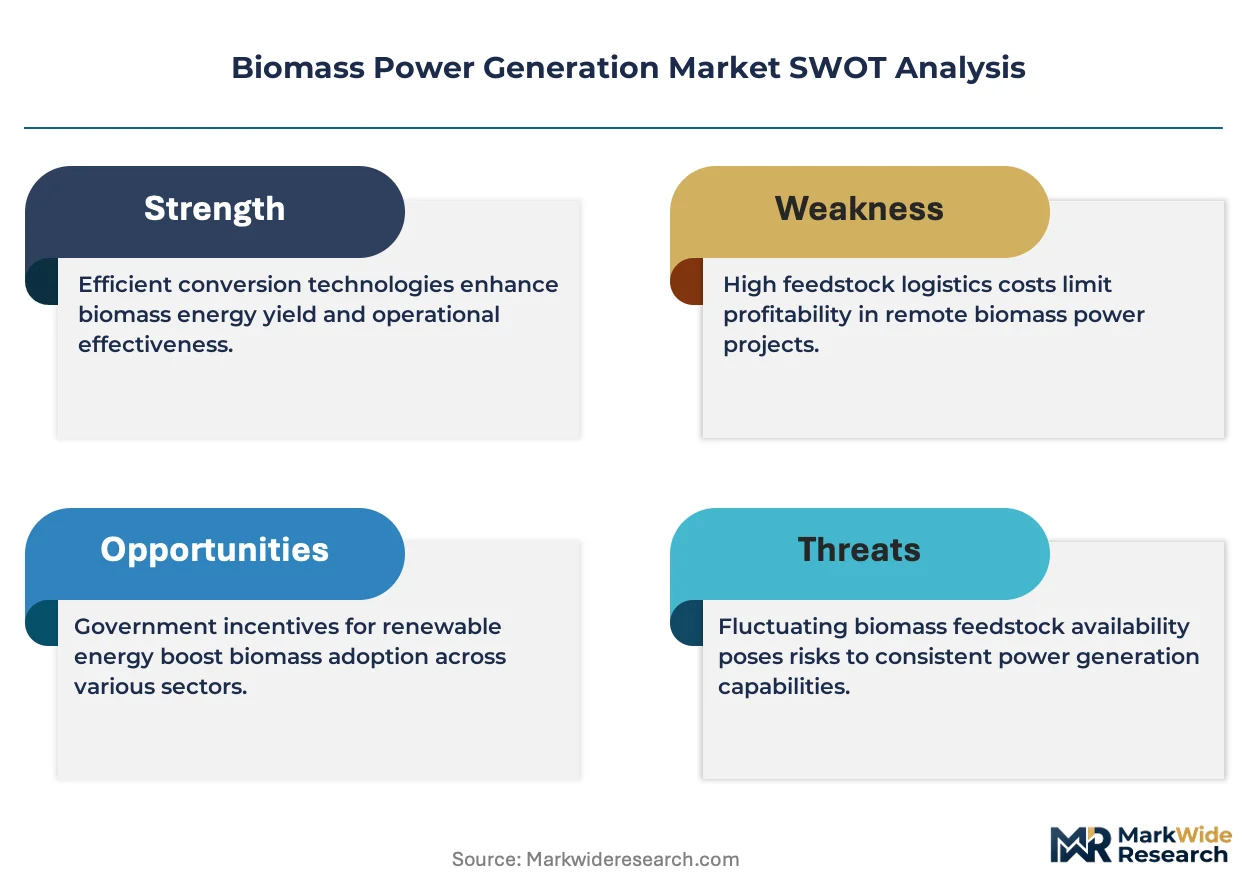
Biomass power generation rewards operators who capture recurring revenue from sustainability certification auditing and long-term fuel supply management, both expanding faster than pure equipment sales as Asian utilities outsource compliance complexity.
For Market Incumbents: Consolidate terminal infrastructure positions in the US Southeast and Baltic region to defend against emerging pellet producers in South America and Southeast Asia. Backward integration into forestry harvesting operations secures feedstock cost stability when competing pulp mill demand spikes. Lock in 15-20 year offtake extensions with Japanese trading houses before South Korean RPS compliance deadlines peak procurement competition.
For New Entrants and Emerging Players: Anchor in pyrolysis-oil upgrading and bio-LNG production where technology fragmentation complicates incumbent scale advantages and specialized engineering commands premium margins. Agricultural residue supply chains in Poland, Romania, and Ukraine offer underdeveloped procurement networks with limited Drax or Enviva presence. Partner with district heating cooperatives in Denmark and Sweden for demonstration projects that generate referenceable thermal integration performance data.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dual-fluidized bed gasification specialists with proven methanol or hydrogen co-production pilots over pure combustion equipment vendors facing carbon accounting headwinds. Five-to-ten year viability hinges on whether IPCC lifecycle methodologies recategorize biomass combustion pathways in national emissions inventories. Watch for EU Green Deal delegated acts tightening sustainability criteria that would strand non-certified supply chain assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Acquisition | Drax and Enviva's port control demonstrates how storage assets dictate Atlantic basin feedstock pricing power. |
| Long-term Offtake Contracting | Japanese trading houses securing 20-year METI-backed agreements lock in revenue visibility against spot market volatility. |
| Sustainability Certification Investment | SBP and FSC compliance investments open tariff-eligible procurement channels under EU Green Deal directives. |
| Pyrolysis Technology Licensing | Fast pyrolysis bio-oil trials in the Netherlands and Japan expand addressable market beyond combustion baseload. |
| District Heating Network Partnership | Danish municipal cooperatives retrofitting natural gas boilers create captive thermal demand for wood chip suppliers. |
Methodological Framework
Cross-validation between utility procurement officer interviews and EIA pellet export data anchors the qualitative findings on Atlantic basin supply concentration. Primary discussions with plant operators at Drax, Danish district heating cooperatives, and Japanese trading house fuel desks combined with secondary validation through IEA biomass reports, FERC infrastructure filings, and EU RED implementation tracking. Bottom-up project pipeline analysis triangulates against top-down national renewable energy target aggregation.
Sensitivity analysis around feedstock cost assumptions and carbon accounting methodology revisions shapes the forecast envelope across the projection horizon. Segmentation dimensions modeled include feedstock type, conversion technology, end-user category, and regional regulatory framework. CAGRs derive from installed capacity buildout trajectories, coal retirement schedules in Japan and South Korea, and district heating network expansion rates in Scandinavia. Key inputs include METI feed-in-tariff adjustment notifications and South Korean RPS penalty rate evolution.
Material uncertainties — IPCC lifecycle assessment recategorizations, EU sustainability criteria tightening, and Atlantic hurricane disruption frequency — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding continued tariff support in Northeast Asia and stable forestry harvest economics. Revision becomes warranted when carbon accounting methodology shifts cross thresholds that reclassify biomass combustion emissions in national inventories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Gasifier Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Modular Biomass Power Plant Market