
 Gasifier Market | 2026-2036
Gasifier Market Size, Share, and Industry Trends Forecast 2026-2036
Gasifier Market Analysis
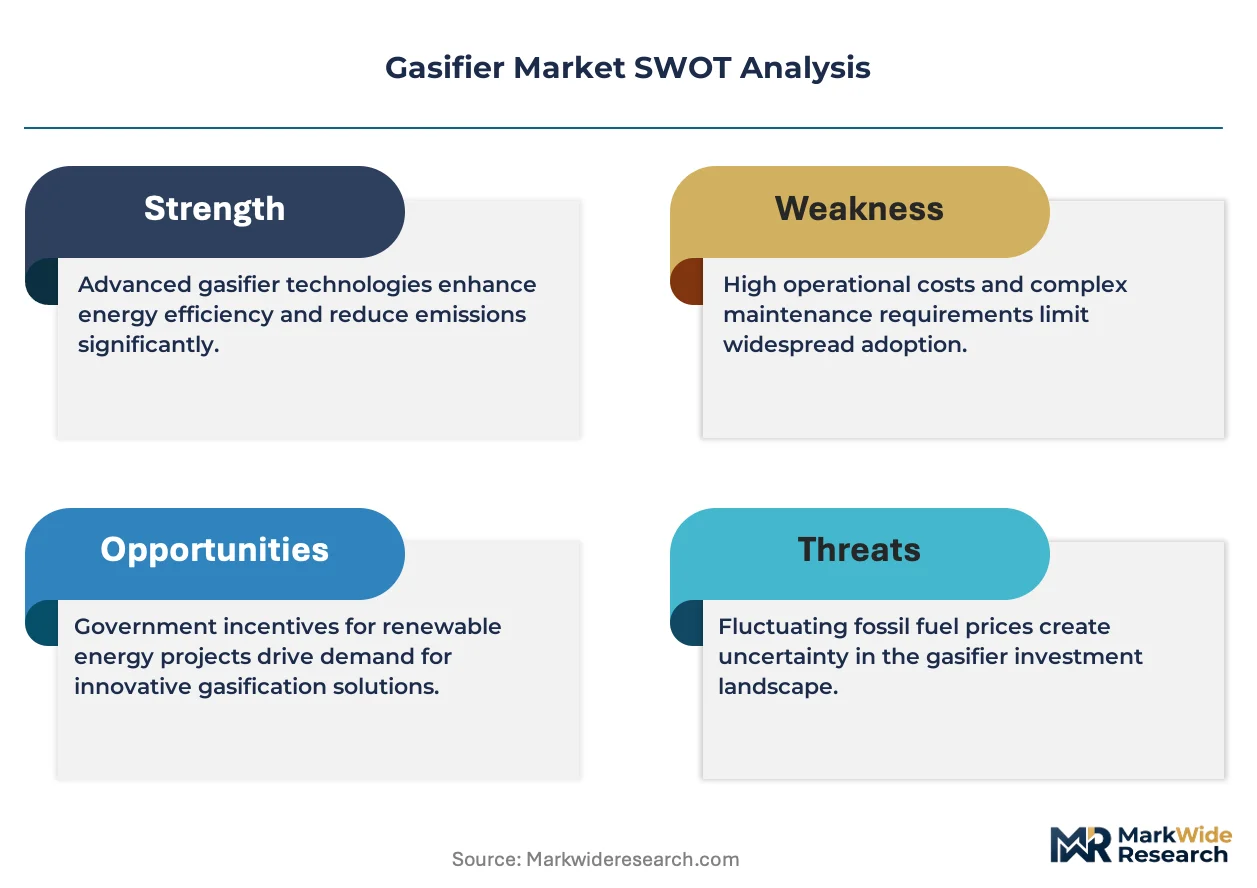
The EU ETS carbon pricing framework is shifting the cost-of-entry calculus for new gasification capacity across Europe. Siemens Energy AG leverages its entrained flow technology leadership to anchor large-scale hydrogen production projects in industrial clusters. Mitsubishi Heavy Industries competes through integrated gasification combined cycle systems that dominate Asian utility procurement. Thyssenkrupp AG specializes in moving bed reactors for chemical production feedstocks, sustaining its position in European refinery retrofits.
A gasifier converts carbonaceous materials into synthesis gas through partial oxidation at temperatures exceeding 700°C, producing a mixture of hydrogen, carbon monoxide, and methane for downstream fuel or chemical synthesis. Entrained flow systems achieve the highest carbon conversion rates above 99%, making them preferred for synthetic fuels and hydrogen production where purity requirements are stringent. Fixed bed technology occupies the biomass and agricultural residue segments where feedstock variability demands simpler reactor geometry and lower capital thresholds. Fluidized bed designs are expanding fastest in waste-to-energy applications across European industrial zones, capturing margin pools from landfill diversion mandates.
The EPA enforces emissions standards under the Clean Air Act that constrain coal-fed gasifier permitting in the United States, while the EU Green Deal and REACH chemical safety protocols shape feedstock eligibility and syngas cleanup specifications across European installations. India's BIS certification requirements and the Bureau of Energy Efficiency's performance standards are accelerating technology transfers into domestic biomass gasification programs. Stakeholders must monitor how carbon border adjustment mechanisms and evolving hydrogen certification schemes will reconfigure project economics and equipment sourcing decisions.
Market Dynamics
The EU ETS carbon pricing framework is compressing project economics for coal-fed installations while entrained flow technology captures margin pools from hydrogen production mandates across industrial clusters in Germany and the Netherlands.
Growth Catalysts
- Renewable Portfolio Standards:India's Bureau of Energy Efficiency performance standards and tightening national renewable mandates are accelerating biomass-to-energy procurement by state power utilities.
- Entrained Flow Technology:Synthetic fuels producers in Germany and the United States are scaling entrained flow systems to meet industrial hydrogen roadmap specifications for carbon conversion rates above 99%.
- Landfill Diversion Mandates:European waste-to-energy regulations are driving fluidized bed gasifier deployments across industrial zones in Belgium and Italy seeking syngas from refuse-derived feedstocks.
Market Restraints
- Feedstock Cost Volatility:Agricultural residue and woody biomass prices fluctuate with seasonal harvest cycles and competing demand from pellet heating markets in Nordic countries.
- EPA Permitting Friction:The Clean Air Act emissions standards constrain greenfield coal gasifier approvals in the United States, extending development timelines by 18-36 months.
- Syngas Cleanup Complexity:Tars and particulate removal systems add 15-25% to capital expenditure for fixed bed biomass installations, limiting deployment in price-sensitive segments.
Strategic Opportunities
- Carbon Border Adjustment Mechanisms:The EU CBAM is creating premium pricing for certified low-carbon hydrogen, enabling gasification-derived syngas to capture margin from steam methane reforming imports.
- Waste Plastic Gasification:Chemical recycling mandates in France and Germany are opening feedstock pools for fluidized bed systems processing mixed polymer streams.
- Power-to-X Convergence:Integration of electrolytic hydrogen with biomass gasification is electrifying synthetic fuels production in Rotterdam and Antwerp industrial corridors.
Industry Challenges
- High-Temperature Materials Engineering:Refractory degradation in entrained flow reactors at temperatures exceeding 1,400°C demands specialized alloy procurement and extended maintenance windows.
- Syngas Certification Timelines:Evolving hydrogen certification schemes under CertifHy and TÜV standards are creating qualification backlogs for project developers seeking offtake agreements.
- Legacy Refinery Integration:Retrofitting moving bed gasifiers into existing European refinery infrastructure requires custom reactor geometry and extended shutdown coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasifier Market |
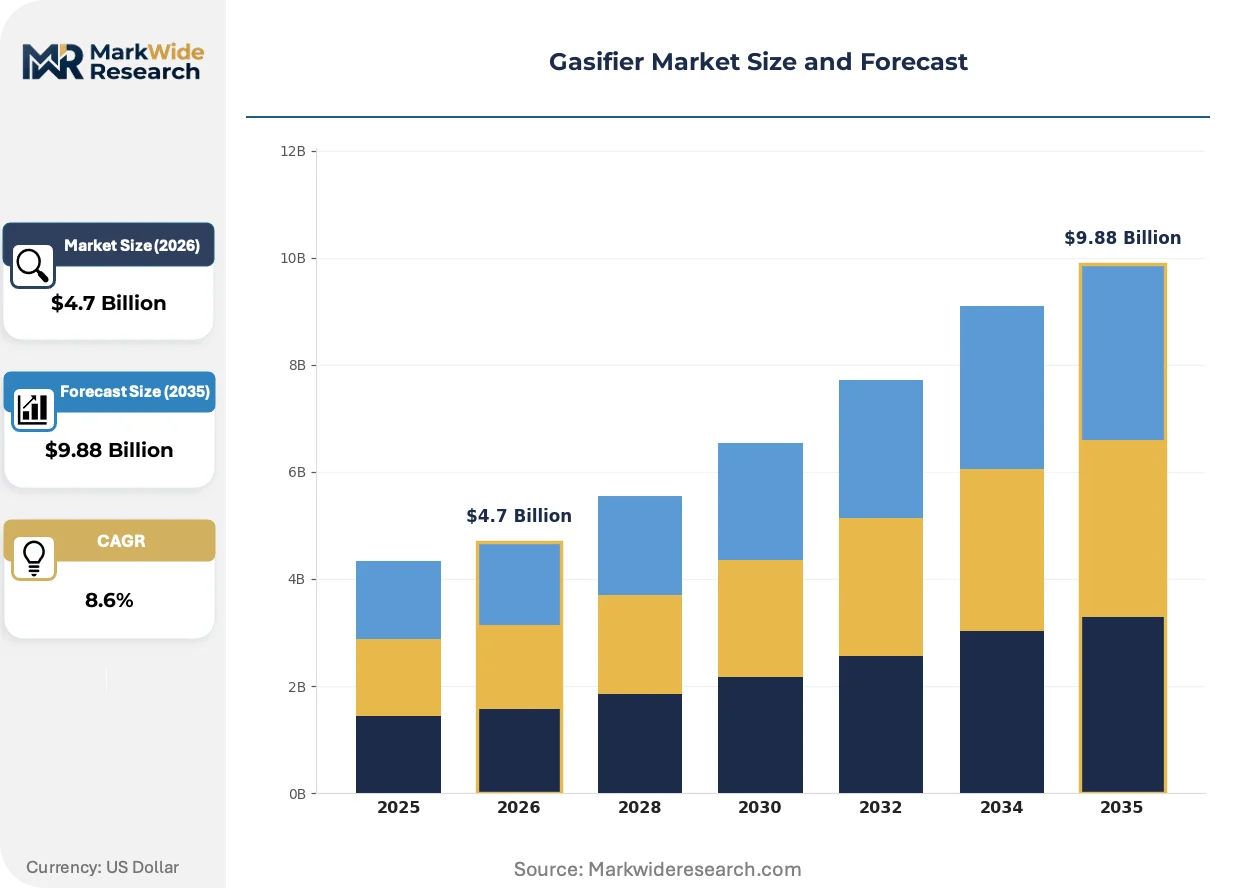
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed, Fluidized Bed, Entrained Flow, Moving Bed Feedstock: Biomass, Coal, Agricultural Residues, Waste Application: Power Generation, Chemical Production, Synthetic Fuels, Hydrogen Production End User: Utilities, Industrial, Agricultural, Commercial |
| Companies Covered | Air Liquide, Andritz AG, Siemens Energy AG, Valmet, Babcock & Wilcox, Mitsubishi Heavy Industries, Thyssenkrupp AG, Hitachi Zosen Inova, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasifier Market Emerging Trajectories
Technology convergence between gasification and carbon capture is reshaping project architectures, while regulatory pressure on scope 3 emissions accelerates feedstock traceability requirements across chemical and fuel value chains.
Plasma gasification is electrifying hazardous waste processing by achieving temperatures above 3,000°C without fossil fuel combustion. Japanese industrial waste handlers in Osaka and Nagoya are piloting systems for medical residue and industrial sludge destruction. The technology is compressing landfill dependency for toxic feedstocks while producing vitrified slag for construction aggregate recovery.
The EU Green Deal's 55% emissions reduction target by 2030 is tightening feedstock eligibility criteria under REACH chemical safety protocols. Gasification operators must now document biomass origin and processing chain integrity to qualify for renewable fuel status. German chemical producers are responding by backward integrating into agricultural residue collection cooperatives to secure certified supply.
Power utilities in China are consolidating procurement around integrated gasification combined cycle systems that co-produce electricity, hydrogen, and captured CO2 for enhanced oil recovery. State Grid Corporation's provincial subsidiaries in Shandong and Jiangsu are specifying dual-output configurations that improve project-level returns. This procurement pattern is displacing standalone power-only gasifier tenders in favor of polygeneration assets.
Gasifier Market Segmentation
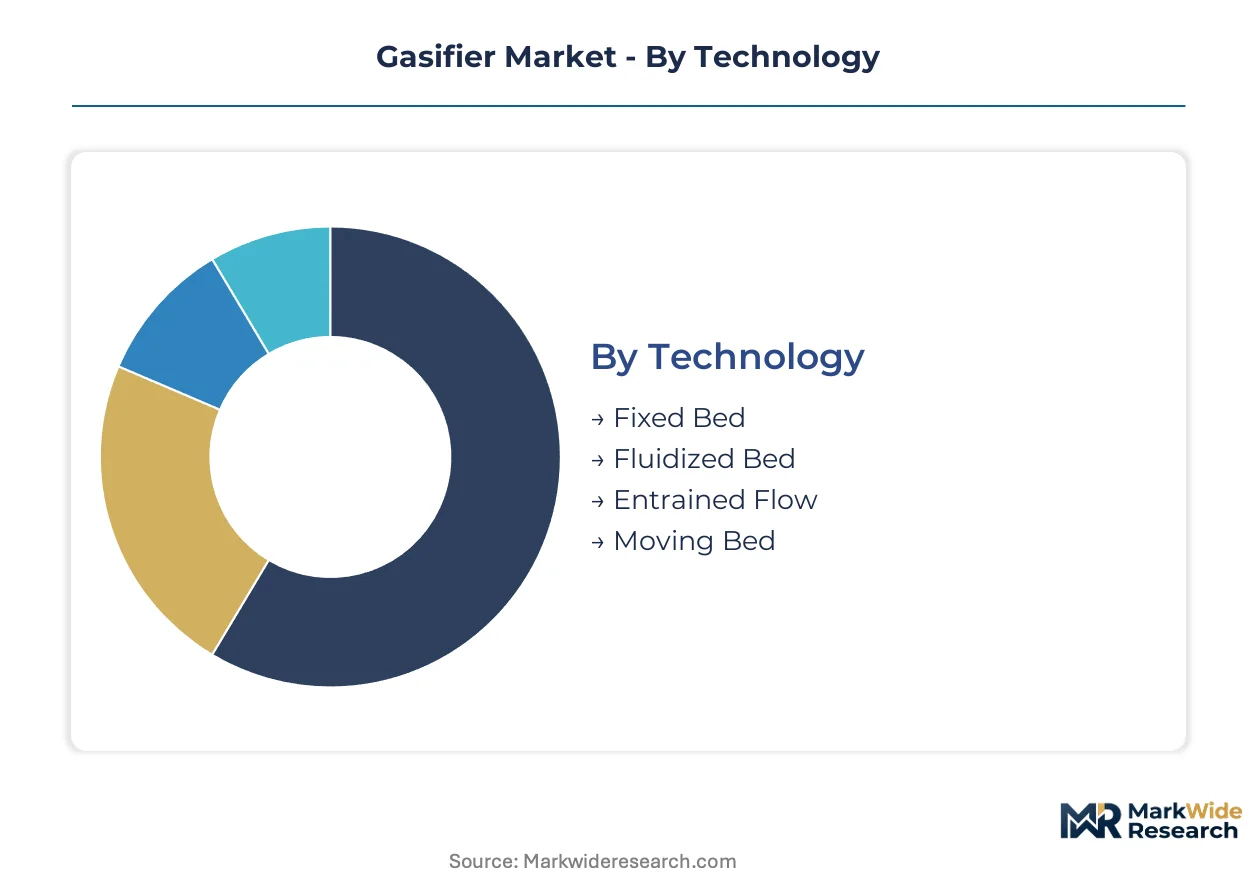
Gasifier technology selection locks in feedstock flexibility, carbon conversion efficiency, and downstream product slate for decades. Technology and feedstock pairings determine capital intensity, while application focus shapes project returns and regulatory risk exposure.
Technology:
Supply concentration in entrained flow systems reflects their dominance in synthetic fuels and hydrogen projects where 99%-plus carbon conversion is non-negotiable.
- Entrained Flow:Fine feedstock particles suspend in oxygen streams at temperatures exceeding 1,400°C, achieving near-complete carbon conversion. Demand clusters in Germany's industrial hydrogen clusters and Rotterdam-Antwerp chemical corridors where purity specifications are stringent. The EU Green Deal's hydrogen certification schemes favor this technology for renewable fuel offtake agreements.
- Fixed Bed:Counter-current gasification in packed-bed reactors handles variable biomass feedstocks with simpler mechanical design. India's state power utilities specify fixed bed systems for agricultural residue programs under Bureau of Energy Efficiency performance standards, accepting lower throughput in exchange for feedstock adaptability.
- Fluidized Bed:Sand or alumina media suspend feedstock particles for uniform temperature distribution, enabling waste-to-energy applications.
- Moving Bed:Slow-moving grates process larger feedstock chunks, sustaining refinery retrofit demand in European chemical production.
Today's leader: Entrained Flow. Tomorrow's challenger: Fluidized Bed.
Feedstock:
Cost tier differentiation separates premium-certified biomass from commodity coal and emerging waste streams.
- Biomass:Woody and herbaceous materials qualify for renewable fuel credits under EU and Indian certification frameworks. Nordic pellet heating markets compete for supply, creating price volatility that project developers hedge through long-term agricultural residue contracts.
- Waste:Refuse-derived feedstocks and industrial residues unlock landfill diversion revenues. Belgian and Italian industrial zones deploy fluidized bed systems to capture margin from circular economy mandates, though tars and chlorine content demand upgraded syngas cleanup.
- Coal:High energy density and supply security sustain demand in China and India, though EPA permitting friction and EU ETS carbon pricing compress project economics in Western markets.
- Agricultural Residues:Rice husks, straw, and bagasse provide seasonal supply pools for distributed power generation in rural India and Southeast Asia.
Biomass commands premium pricing. Waste feedstocks are climbing the fastest.
Application:
Volume concentration in power generation is yielding to margin-rich hydrogen and synthetic fuels as carbon pricing reshapes project economics.
- Hydrogen Production:Gasification-derived syngas feeds water-gas shift reactors for blue hydrogen with carbon capture. Germany's industrial hydrogen roadmaps and the EU CBAM are creating premium pricing opportunities against steam methane reforming imports.
- Synthetic Fuels:Fischer-Tropsch synthesis converts cleaned syngas into diesel and jet fuel substitutes. Entrained flow systems in the United States and Germany scale to meet aviation sector offtake agreements.
- Power Generation:Integrated gasification combined cycle plants co-produce electricity and hydrogen. China's State Grid Corporation specifications favor dual-output configurations in Shandong and Jiangsu provinces.
- Chemical Production:Ammonia, methanol, and olefin feedstocks drive moving bed reactor demand for European refinery retrofits.
Hydrogen Production captures tomorrow's margin. Power Generation defends today's volume.
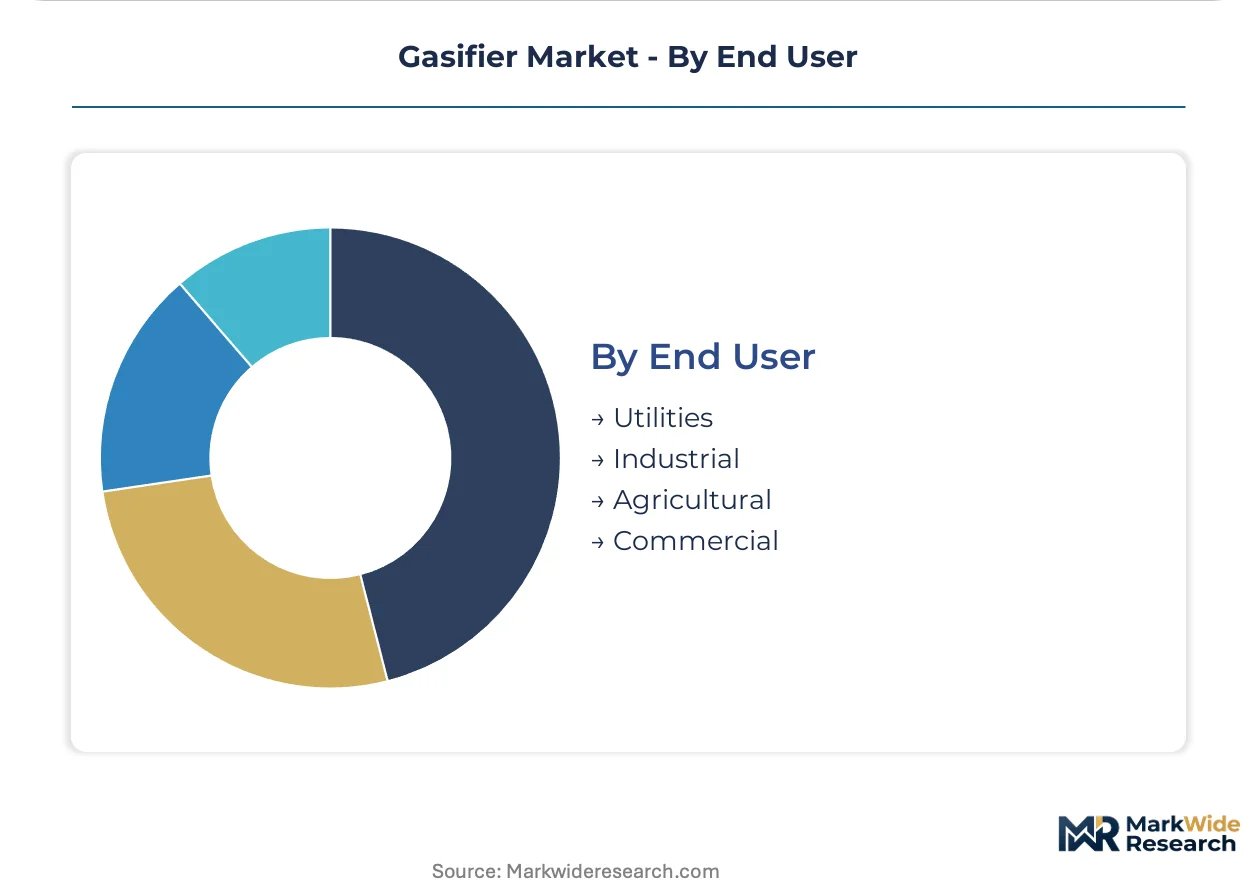
End User:
Customer type determines procurement scale, technology sophistication, and regulatory compliance burden.
- Industrial:Chemical producers and refineries specify entrained flow and moving bed systems for captive syngas supply. German chemical producers backward integrate into agricultural residue collection to secure certified feedstock under REACH protocols.
- Utilities:State power companies in India and China consolidate procurement around integrated gasification combined cycle systems, displacing standalone power-only tenders.
- Agricultural:Rural cooperatives and agro-processors deploy small-scale fixed bed units for on-site power and thermal applications.
- Commercial:Waste management operators and district heating utilities pilot fluidized bed and plasma gasification for landfill diversion.
Industrial buyers set technology standards. Utilities provide volume anchor demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The gasifier industry traces its modern commercial roots to German chemical engineering in the early twentieth century, where entrained flow systems first achieved industrial scale for synthetic fuel production during resource-constrained periods.
Germany
Industrial hydrogen clusters in the Rhine-Ruhr and Leuna chemical corridors anchor European entrained flow demand. The EU ETS carbon pricing framework and national hydrogen roadmaps compress coal-fed project economics while elevating biomass-to-hydrogen pathways. BASF and thyssenkrupp anchor large-scale syngas production in Ludwigshafen and Duisburg industrial zones.
United States
Synthetic fuels producers in the Gulf Coast and Midwest scale entrained flow capacity for aviation sector offtake agreements. EPA Clean Air Act emissions standards constrain greenfield coal gasifier permitting, extending development timelines significantly. Houston and Lake Charles industrial clusters concentrate hydrogen production infrastructure with carbon capture integration.
China
State Grid Corporation subsidiaries in Shandong and Jiangsu provinces consolidate procurement around integrated gasification combined cycle systems. Dual carbon goals and provincial renewable mandates accelerate biomass-to-energy installations alongside coal-based polygeneration assets. The Yangtze River Delta chemical corridor anchors captive syngas demand for methanol and olefin production.
India
State power utilities in Maharashtra and Tamil Nadu scale agricultural residue gasification under Bureau of Energy Efficiency performance standards. BIS certification requirements accelerate technology transfers into domestic biomass programs. Rural cooperatives in Punjab and Haryana deploy fixed bed units for rice husk and straw processing.
Netherlands
Rotterdam-Antwerp port industrial zones integrate biomass gasification with electrolytic hydrogen for Power-to-X synthetic fuels production. EU Green Deal hydrogen certification schemes and CBAM implementation create premium pricing for certified low-carbon syngas. Shell and Air Products anchor large-scale blue hydrogen projects in the port complex.
Gasifier Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive energy technology portfolios. Market concentration remains moderate, with technology leadership distributed across German engineering groups, Japanese heavy industrials, and European process equipment specialists. Two archetypes dominate: integrated engineering-procurement-construction contractors and specialized reactor technology licensors. Competitive moves center on strategic partnerships for hydrogen cluster development and technology licensing agreements for emerging market entry.
Among German-based industrial groups, Siemens Energy AG and thyssenkrupp AG exemplify the engineering-procurement-contractor archetype with entrained flow and moving bed reactor expertise respectively. Mitsubishi Heavy Industries represents the Japanese heavy industrial model with integrated gasification combined cycle system integration. These three anchors illustrate how geographic engineering traditions shape technology specialization across synthetic fuels, hydrogen production, and power generation applications.
| Leading Market Players |
|---|
| Air Liquide |
| Andritz AG |
| Siemens Energy AG |
| Valmet |
| Babcock & Wilcox |
| Mitsubishi Heavy Industries |
| Thyssenkrupp AG |
| Hitachi Zosen Inova |
| Air Products and Chemicals |
| Others |
Supply Flow & Price Mechanics
Specialized refractory materials engineers in Germany's Ruhr industrial basin command wage premiums that compress margins on entrained flow reactor fabrication, widening the spread between premium-certified hydrogen-grade systems and standard biomass gasifier units.
Pricing Analysis
Project-based long-term offtake contracting dominates capital equipment procurement, with pricing stratifying across premium, standard, and economy tiers based on carbon conversion efficiency guarantees and EU CertifHy certification status. Price differentiation rests on feedstock flexibility clauses and after-sales service bundling. Cost compression in the standard tier is intensifying because Chinese EPC contractors are capturing fixed-bed biomass utility contracts. Agricultural cooperatives in rural India exhibit the highest price sensitivity, while German chemical producers in hydrogen clusters demonstrate the lowest.
Supply Chain Analysis
Direct-to-industrial-plant channels handle hyperscale entrained flow reactor demand, while regional EPC partnerships serve distributed biomass installations. Manufacturing concentrates in Germany, Japan, and China for pressure vessel fabrication and high-temperature alloy components. Raw material procurement draws from nickel-chromium superalloy foundries, ceramic refractory suppliers, and precision gas control valve specialists. Single-source vulnerability in specialized alloy supply creates exposure to aerospace sector demand spikes. Distribution runs through engineering-procurement-construction contractors for large projects and authorized regional integrators for smaller-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gasifier market compounds returns through regulatory layering, with the EU Carbon Border Adjustment Mechanism creating durable margin pools for certified low-carbon hydrogen production that gasification-derived syngas can capture.
For Market Incumbents: Lock in entrained flow technology leadership through captive refractory alloy supply agreements that insulate against aerospace sector demand competition. Secure long-term agricultural residue collection contracts in India's Punjab and Haryana belts before domestic engineering firms consolidate feedstock access. Position against fluidized bed technology encroachment in European waste-to-energy segments by embedding carbon capture integration into standard hydrogen project offerings.
For New Entrants and Emerging Players: Digital-channel equipment financing platforms open access to capital-constrained agricultural cooperatives in Southeast Asia seeking sub-megawatt fixed bed units. Target India's state power utility biomass procurement programs where BIS certification requirements have slowed foreign equipment adoption. Pursue technology licensing arrangements with established refractory suppliers rather than greenfield manufacturing investments.
For Investors and Strategic Acquirers: Industrial hydrogen project developers are the most active acquirer in this space, seeking entrained flow reactor technology to anchor cluster developments. The five-to-ten year viability window favors integrated engineering-procurement-construction capabilities over pure technology licensors. Acquisition target archetypes include specialized refractory materials firms and regional biomass feedstock aggregators. Monitor EU hydrogen certification scheme backlog resolution rates as the inflection indicator for project development velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | German chemical producers secure certified agricultural residue streams under REACH origin documentation requirements. |
| Carbon Capture Integration Partnership | Rotterdam port hydrogen clusters combine entrained flow syngas with electrolytic hydrogen for Power-to-X synthetic fuels. |
| Technology Licensing to Domestic EPC Firms | Foreign licensors accelerate market entry in India where BIS certification barriers constrain direct equipment sales. |
| Refractory Alloy Supply Agreement | Gasifier fabricators lock in nickel-chromium superalloy access against aerospace and nuclear sector demand competition. |
| Waste Plastic Gasification Pilot Scale-Up | Belgian and Italian operators capture chemical recycling mandate revenues through fluidized bed mixed polymer processing. |
Methodological Framework
Bottom-up utility procurement modeling reconciled against top-down EPC contractor order tracking forms the analytical core of this study. Primary interviews with plant engineers at State Grid Corporation subsidiaries, procurement leads at German chemical producers, EPC project managers in India, and refractory materials suppliers provided demand-side validation. Secondary sources include EIA power plant databases, IEA hydrogen project tracking, EU ETS carbon price registries, and SEC filings from industrial conglomerates with gasifier technology portfolios.
The input-output matrix framing connects feedstock cost assumptions through technology-specific conversion efficiencies to end-product revenue streams across hydrogen, synthetic fuels, and power generation applications. Segmentation dimensions modeled include reactor technology type, feedstock category, application focus, and regional regulatory cluster. CAGRs were derived through regression analysis of historical capacity additions against policy milestone timing. Forecast inputs incorporate EU CBAM phase-in schedules and national hydrogen roadmap implementation pace.
Feedstock price volatility, permitting timeline extensions under EPA Clean Air Act enforcement, and hydrogen certification scheme qualification backlogs are the dominant revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomass Energy Systems
Energy Harvesting Trees Market
Biomass Energy Systems
Biomass Pellets Market
Biomass Energy Systems
Solar Bio-Gas Hybrid Power System Market
Biomass Energy Systems
Global Wood Fuel Pellets Market
Biomass Energy Systems
Global Biomass Power Market
Biomass Energy Systems
Europe Biomass Gasification Market
Biomass Energy Systems
Gasification Market
Biomass Energy Systems
Europe Wood Pellet Heating Systems Market
Biomass Energy Systems
North America Biomass Gasification Market
Biomass Energy Systems
Biomass Gasification Market
Biomass Energy Systems
Global Biomass Market
Biomass Energy Systems
Modular Biomass Power Plant Market
Biomass Energy Systems
Biomass Power Generation Market