
 Global Gas Treatment Market | 2026-2036
Global Gas Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Treatment Market Foresight
EPA cross-state air rules is broadening the cost-of-entry calculus for sulfur dioxide and nitrogen oxide control systems across North American power and refining complexes. BASF SE leverages its catalyst and adsorbent portfolio to anchor positions in hydrogen sulfide removal and tail gas treatment units. Dow Inc. sustains manufacturing scale across integrated petrochemical sites where amine-based absorption systems process high-volume sour gas streams. Linde competes through cryogenic and membrane separation technologies that serve LNG pretreatment and helium recovery applications.
Gas treatment encompasses the chemical and physical processing of industrial gas streams to remove contaminants including hydrogen sulfide, carbon dioxide, mercury, and particulate matter through absorption, adsorption, membrane separation, or catalytic conversion at operating pressures ranging from atmospheric to 100 bar. The primary purpose centers on meeting pipeline specifications for natural gas transport, protecting downstream catalysts in chemical synthesis, and ensuring compliance with atmospheric emission limits for sulfur compounds and acid gases. Absorption technology occupies the dominant share of installed capacity due to mature amine solvent systems and retrofittable column designs, while membrane separation represents the fastest-expanding segment driven by modular skid-mounted units for remote gas fields and biogas upgrading facilities where operational simplicity outweighs marginal recovery efficiency. Carbon dioxide scrubbers concentrate margin pools in post-combustion carbon capture deployments linked to power generation and hydrogen production facilities.
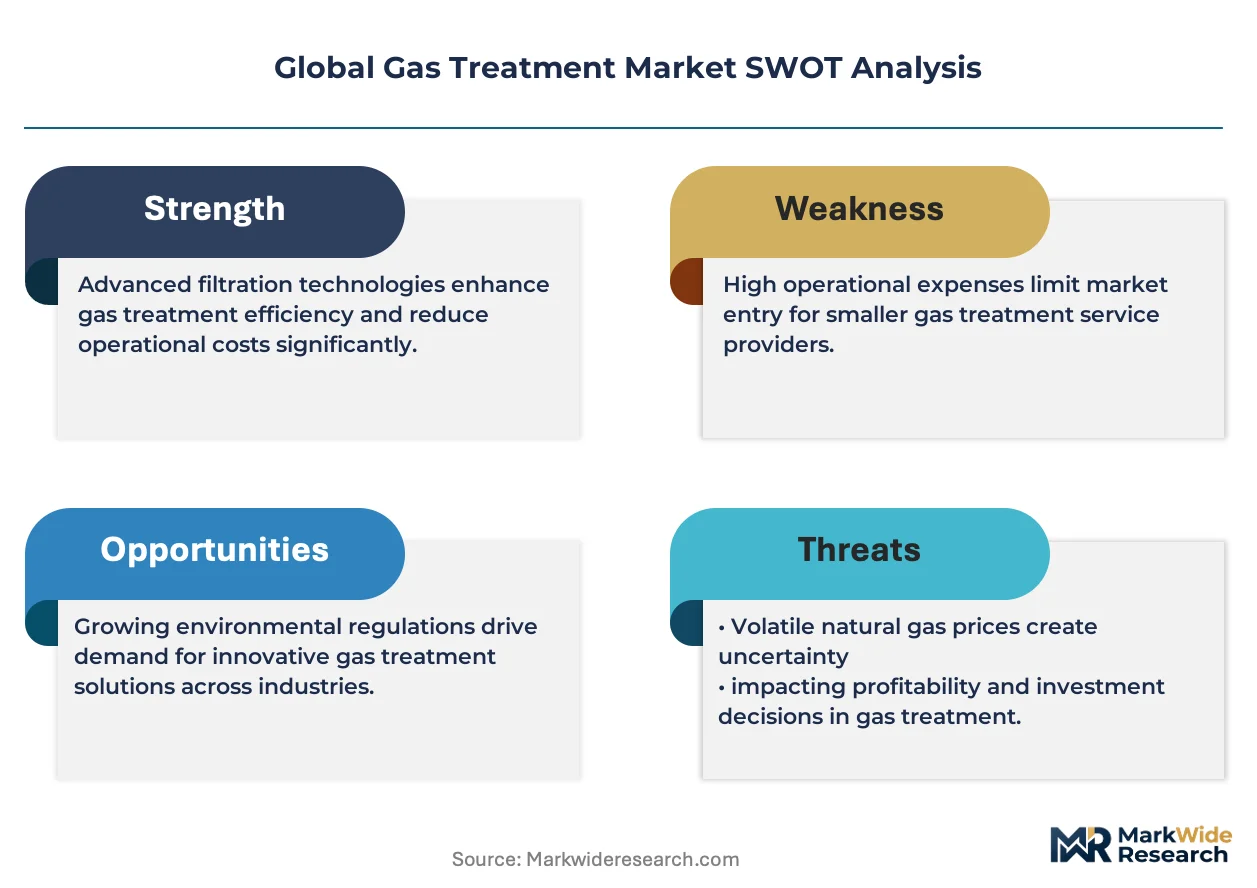
FERC interstate pipeline safety standards, EPA National Ambient Air Quality Standards, and EU F-Gas Regulation collectively shape equipment specifications, solvent selection, and leak detection mandates across gas treatment installations. These frameworks drive replacement demand for lower-emission amine formulations and accelerate qualification of non-amine absorbents in European and North American jurisdictions. Stakeholders must monitor evolving carbon border adjustment mechanisms and hydrogen blending specifications that will redefine contaminant thresholds and treatment intensity for pipeline-injected gases.
Market Dynamics
Amine solvent degradation and regeneration energy costs are compressing operating margins across sour gas processing facilities, forcing operators toward hybrid separation trains and non-amine absorbent qualification programs.
Growth Catalysts
- LNG export terminal construction:Cryogenic pretreatment trains at United States Gulf Coast liquefaction facilities are expanding acid gas removal capacity to meet pipeline-quality specifications and international offtake contracts.
- EU F-Gas Regulation phase-down:Fluorinated solvent restrictions are accelerating methyl diethanolamine replacement with lower-global-warming-potential formulations in European carbon capture and natural gas processing installations.
- Biogas upgrading mandates:Membrane separation skids are capturing landfill and agricultural digester streams to inject renewable natural gas into German and French distribution networks under national biomethane quotas.
Market Restraints
- Specialty solvent supply concentration:Piperazine and sterically-hindered amine production concentrates among German and Dutch chemical manufacturers, exposing processors to freight cost volatility and allocation risk.
- High-purity alumina shortage:Claus catalyst substrate availability tightens as smelter energy costs in China and Australia constrain activated alumina output for sulfur recovery units.
- Membrane material performance ceilings:Polyimide hollow-fiber modules face hydrogen sulfide plasticization limits above 20 bar partial pressure, restricting deployment in high-pressure sour gas reservoirs.
Strategic Opportunities
- Blue hydrogen production clusters:Autothermal reforming and gasification facilities in the Netherlands and United Kingdom are embedding carbon capture trains that double acid gas treatment intensity per unit of hydrogen output.
- Modular offshore platform retrofits:Compact amine reclamation and solid-bed scavenger systems are penetrating aging North Sea and Gulf of Mexico infrastructure where deck space constraints previously blocked capacity expansion.
- India City Gas Distribution expansion:Localized biogas and compressed natural gas treatment skids are qualifying under Petroleum and Natural Gas Regulatory Board specifications to serve residential and transport demand in tier-2 cities.
Industry Challenges
- Corrosion metallurgy expertise gap:Rich amine service alloy specification and stress-corrosion-cracking prediction require specialized materials engineering talent scarce in mid-sized EPC firms.
- Cross-border solvent certification delays:REACH registration and EPA TSCA premanufacture notification timelines extend 18-24 months for novel amine formulations, slowing formulation substitution programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Treatment Market |
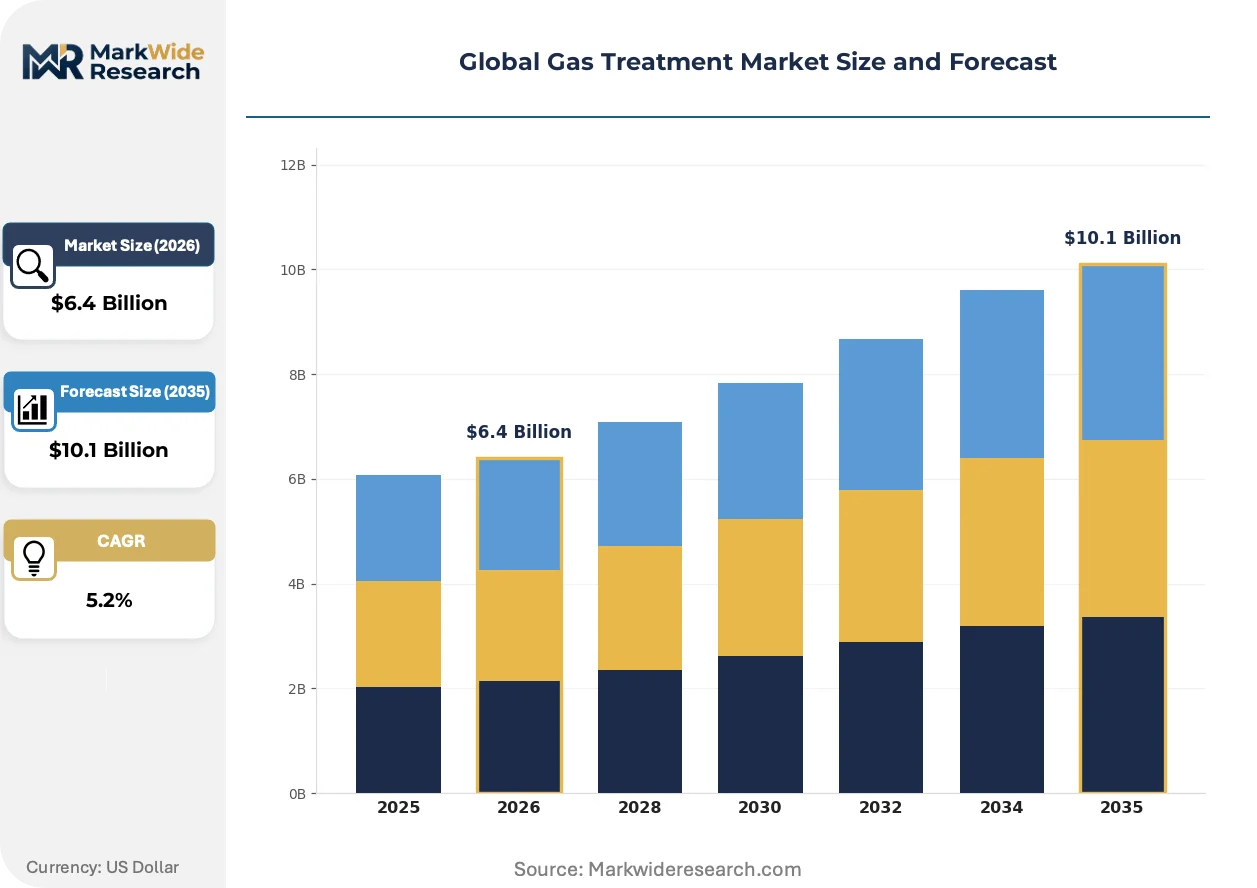
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.1 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Absorption, Adsorption, Membrane Separation, Cryogenic Distillation, Catalytic Conversion Application: Natural Gas Processing, Syngas Purification, Biogas Upgrading, Flue Gas Treatment, Acid Gas Removal End User: Refineries, Petrochemical Plants, Power Generation Facilities, Landfill Operations, Chemical Manufacturers Product Type: Sulfur Removal Units, Carbon Dioxide Scrubbers, Mercury Removal Systems, Hydrogen Sulfide Filters, Particulate Scrubbers |
| Companies Covered | BASF SE, Air Products and Chemicals, Linde, Honeywell, Huntsman Corporation, Dow Inc., ExxonMobil, Baker Hughes Company, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Treatment Market Shifts & Advancements
Process intensification through hybrid separation sequences and digital twin deployment is compressing energy intensity and unplanned downtime in gas treatment facilities. Equipment vendors and chemical suppliers are converging on integrated performance guarantees.
Membrane-cryogenic hybrid pretreatment is integrating polymer separation stages with turboexpander chilling to handle high-CO2 feedstocks previously uneconomic for LNG liquefaction. Qatari and Australian train operators are piloting these configurations to process leaner reservoir gas without amine solvent loops. The technology is integrating once-discrete unit operations into single-l skid packages that reduce plot space and refrigeration load.
EPA National Ambient Air Quality Standards revision and state implementation plan deadlines are tightening sulfur dioxide emission budgets for existing Claus tail gas treatment units. Refineries in Texas and California are retrofitting selective catalytic reduction and caustic scrubber stages to meet 1 ppm sulfur outlet specifications. The power generation segment faces parallel pressure as cross-state air pollution rules extend to hydrogen co-firing in combined-cycle turbines.
Long-term service agreements are displacing unit-based equipment sales as integrated operators seek guaranteed availability and solvent management from technology licensors. BASF and Dow are restructuring commercial models around throughput fees and regeneration chemical supply at United States and Middle Eastern petrochemical complexes. This shift concentrates procurement decision authority with central engineering functions and extends contract durations beyond traditional 5-year catalyst replacement cycles.
Global Gas Treatment Market Segmentation
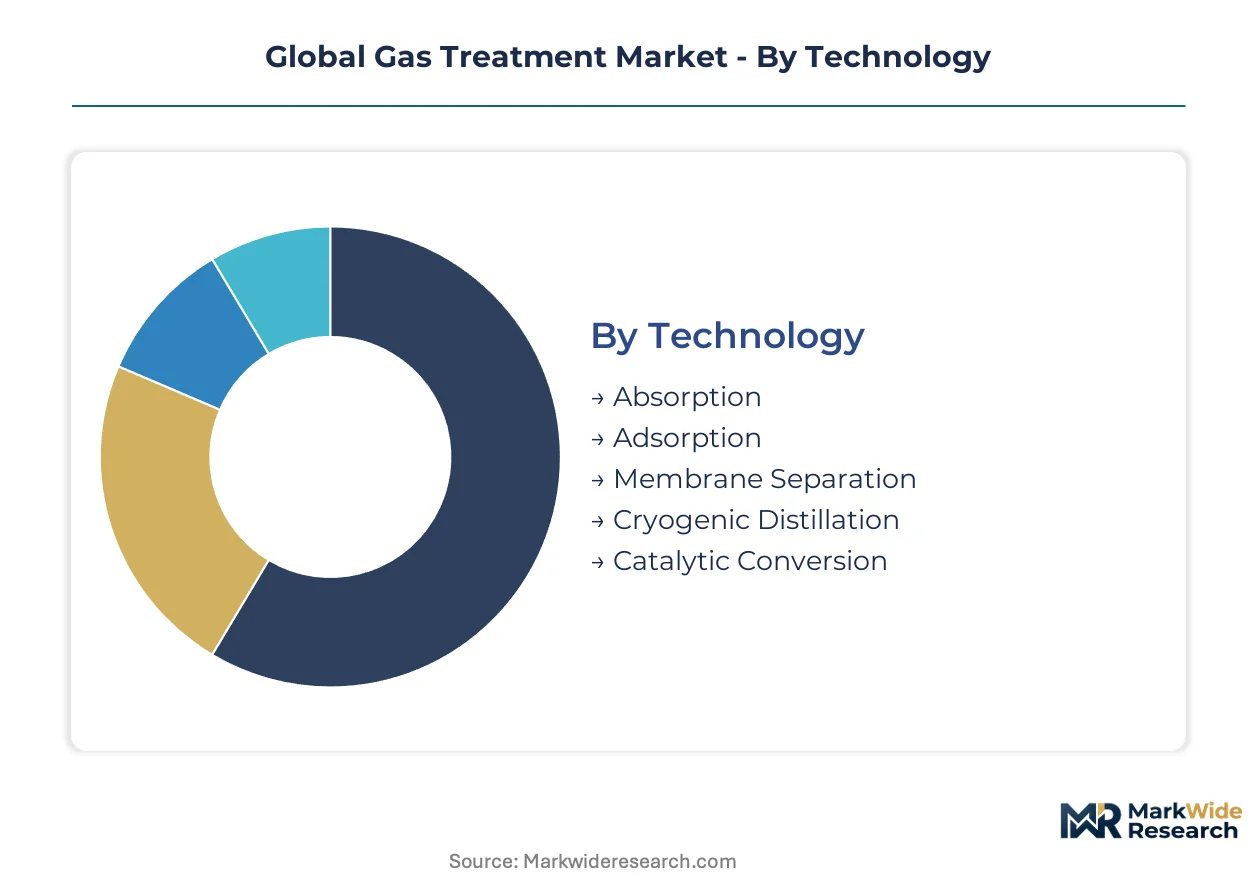
Technology selection in gas treatment hinges on contaminant profile, pressure conditions, and energy integration requirements. Each segment carries distinct capital intensity and operating cost structures that determine retrofit feasibility versus greenfield deployment.
Technology:
Replacement cycles for solvent-based systems are shortening as regeneration energy costs erode operating margins, pushing operators toward hybrid configurations and modular alternatives.
- Absorption:Amine solvent systems process high-volume sour gas streams through regenerable aqueous solutions at pressures up to 100 bar. Gulf Coast LNG terminals and Dutch hydrogen clusters anchor demand as operators retrofit existing columns with lower-energy formulations.
- Membrane Separation:Polymer hollow-fiber modules separate acid gases based on differential permeability without thermal regeneration. Remote gas fields in Australia and biogas upgrading facilities in Germany favor skid-mounted units where operational simplicity outweighs recovery efficiency trade-offs.
- Adsorption:Solid-bed systems using activated alumina or molecular sieves target mercury and trace sulfur removal.
- Cryogenic Distillation:Turboexpander-based chilling separates acid gases through partial condensation at sub-zero temperatures.
- Catalytic Conversion:Claus and tail gas treatment units oxidize hydrogen sulfide to elemental sulfur.
Absorption sits at the top of the volume ranking, with Membrane Separation climbing the fastest.
Application:
Application selection correlates with feedstock contaminant loading and product specification stringency, driving divergent technology bundling strategies.
- Natural Gas Processing:Pipeline specification compliance requires bulk CO2 and H2S removal through amine absorption or membrane pretreatment. United States Permian Basin gathering systems and Qatari liquefaction trains represent concentrated demand nodes.
- Biogas Upgrading:Membrane and pressure-swing adsorption systems purify landfill and agricultural digester streams to biomethane quality. German and French injection quotas accelerate deployment at distributed agricultural facilities.
- Syngas Purification:Acid gas removal protects downstream catalysts in ammonia and methanol synthesis loops.
- Flue Gas Treatment:Post-combustion CO2 capture and desulfurization address power generation and industrial boiler emissions.
- Acid Gas Removal:Integrated treatment trains handle combined H2S and CO2 streams in high-sour reservoir developments.
Natural Gas Processing commands the largest installed base, while Biogas Upgrading shows the steepest expansion trajectory.
End User:
End user procurement authority is centralizing as integrated operators seek performance guarantees and solvent management from technology licensors.
- Refineries:Sulfur recovery units and tail gas treatment systems meet EPA National Ambient Air Quality Standards and EU Industrial Emissions Directive limits. Texas and California complexes are retrofitting selective catalytic reduction stages to achieve 1 ppm sulfur outlet specifications.
- Petrochemical Plants:Ethylene and ammonia producers deploy hydrogen sulfide removal to protect downstream catalysts. United States Gulf Coast and Netherlands clusters embed carbon capture trains that double acid gas treatment intensity per unit of output.
- Power Generation Facilities:Combined-cycle turbines require flue gas desulfurization and emerging hydrogen co-firing emission controls.
- Landfill Operations:Biogas collection and upgrading systems convert methane emissions to renewable natural gas.
- Chemical Manufacturers:Syngas and specialty gas purification supports methanol, hydrogen, and carbon black production.
Refineries maintain the dominant share of capital deployment, with Petrochemical Plants gaining share fastest.
Product Type:
Product configuration varies with contaminant chemistry, with sulfur and carbon dioxide systems representing mature categories and mercury removal gaining regulatory traction.
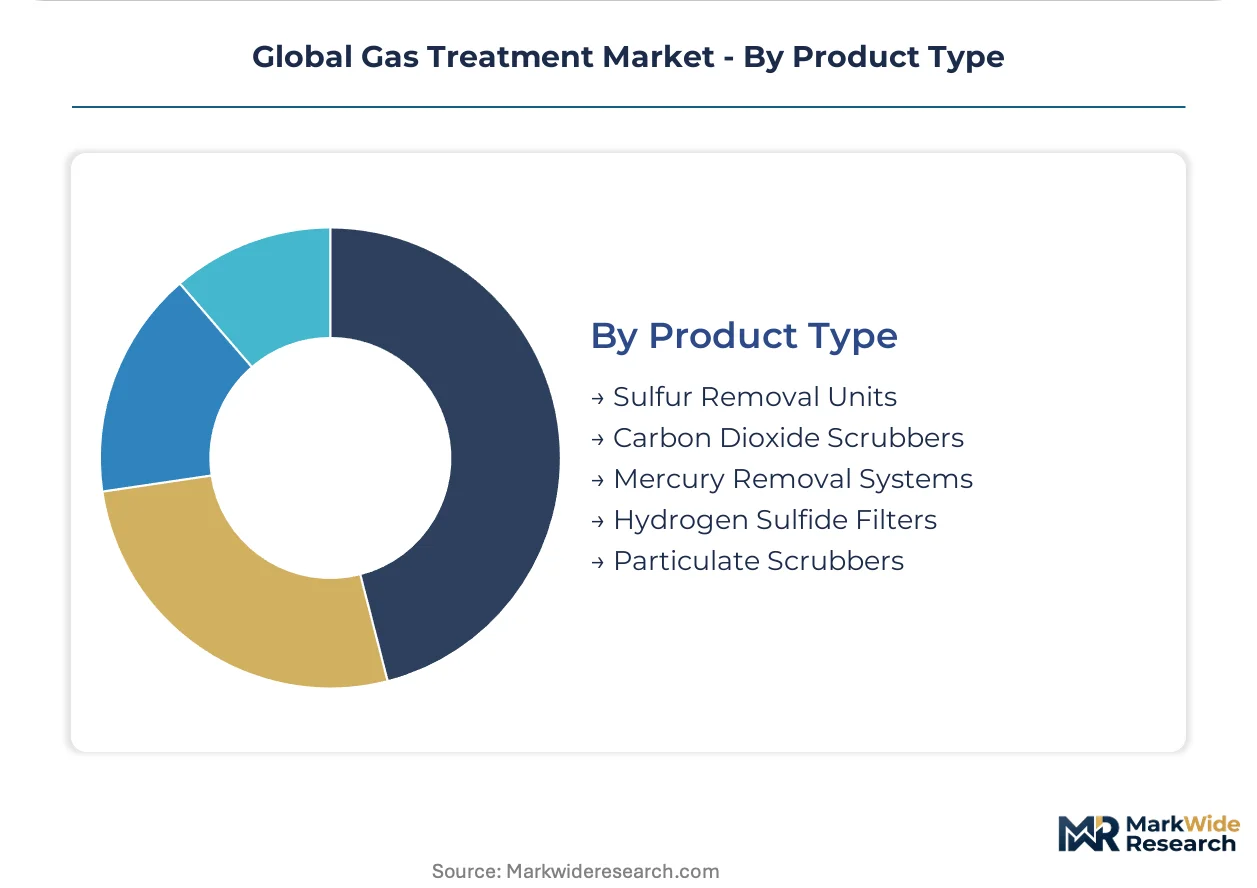
- Sulfur Removal Units:Amine absorption trains and Claus sulfur recovery systems process high-H2S feedstocks to elemental sulfur or sulfuric acid. Middle Eastern sour gas developments and United States shale gas processing anchor replacement demand.
- Carbon Dioxide Scrubbers:Post-combustion capture and natural gas pretreatment systems concentrate margin pools at United Kingdom and Netherlands blue hydrogen facilities.
- Mercury Removal Systems:Activated carbon and metal sulfide beds protect aluminum heat exchangers in LNG liquefaction.
- Hydrogen Sulfide Filters:Solid-bed scavengers and liquid redox systems treat low-concentration streams.
- Particulate Scrubbers:Wet and dry scrubbing removes dust and aerosols from process gas streams.
Sulfur Removal Units lead by installed value, with Carbon Dioxide Scrubbers expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized corrosion metallurgists and amine process engineers concentrate along the United States Gulf Coast, the Netherlands, and Qatar, anchoring project execution capacity for high-pressure sour gas developments.
United States
LNG export terminal construction at Corpus Christi and Sabine Pass drives acid gas removal capacity additions. EPA National Ambient Air Quality Standards revisions tighten sulfur dioxide emission budgets for Texas and California refineries. Houston-area engineering firms deploy modular amine reclamation systems for offshore platform retrofits in the Gulf of Mexico.
Qatar
North Field expansion projects require cryogenic pretreatment trains for lean reservoir gas processing. The national petroleum regulator mandates pipeline-quality specifications for international offtake contracts. Ras Laffan Industrial City hosts membrane-cryogenic hybrid pilot configurations that integrate polymer separation with turboexpander chilling.
Germany
Biogas upgrading mandates under national biomethane quotas accelerate membrane separation skid deployment at agricultural digesters. EU F-Gas Regulation phase-down restrictions force methyl diethanolamine replacement with lower-global-warming-potential formulations. Chemical manufacturers in Ludwigshafen and Marl concentrate piperazine and sterically-hindered amine production.
Netherlands
Blue hydrogen production clusters at Rotterdam and Eemshaven embed carbon capture trains that double acid gas treatment intensity per unit of hydrogen output. REACH registration timelines extend 18-24 months for novel amine formulations. Port of Rotterdam infrastructure supports integrated solvent management and regeneration chemical supply for petrochemical complexes.
India
City Gas Distribution expansion under Petroleum and Natural Gas Regulatory Board specifications drives localized biogas and compressed natural gas treatment skid qualification. Central Electricity Authority emission norms tighten for power generation facilities. Tier-2 cities in Gujarat and Maharashtra deploy compact treatment units for residential and transport demand.
Global Gas Treatment Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive catalyst and adsorbent portfolios. Technology licensors and equipment fabricators occupy distinct tiers based on solvent formulation depth and modular system capabilities. Two strategic archetypes dominate: diversified chemical majors leveraging manufacturing scale across integrated petrochemical sites, and specialized gas technology providers competing through cryogenic and membrane separation expertise. Capacity expansion and long-term service agreement restructuring represent the dominant competitive moves, displacing traditional unit-based equipment sales.
Among diversified chemical conglomerates, BASF SE and Dow Inc. occupy positions exemplifying the integrated performance guarantee model, while Linde sits within the specialized gas technology tier. These three anchors demonstrate how procurement decision authority centralizes with central engineering functions as operators seek guaranteed availability and solvent management. The shift extends contract durations beyond traditional catalyst replacement cycles and concentrates commercial relationships around throughput fees rather than discrete equipment transactions.
| Leading Market Players |
|---|
| BASF SE |
| Air Products and Chemicals |
| Linde |
| Honeywell |
| Huntsman Corporation |
| Dow Inc. |
| ExxonMobil |
| Baker Hughes Company |
| Clariant AG |
| Others |
Supply & Pricing Matrix
Regeneration energy costs cascade through amine solvent pricing tiers, with high-purity formulations commanding premiums from United States Gulf Coast LNG operators while standard grades serve mid-sized biogas upgraders in Germany and France.
Pricing Analysis
Bundled long-term service agreements now dominate over unbundled unit sales, with throughput fees and solvent management packages anchoring commercial relationships at United States and Middle Eastern petrochemical complexes. Price differentiation rests on certification grade for EPA and EU F-Gas compliance, alongside geographic delivery cost to remote gas fields. Cost compression in standard amine formulations is intensifying because regeneration energy penalties erode operating margins. Mid-sized EPC firms show highest price sensitivity due to scarce corrosion metallurgy expertise, while integrated majors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's Petroleum and Natural Gas Regulatory Board specifications and Qatar's North Field expansion requirements are reshaping sourcing toward localized skid fabrication and in-country alloy specification expertise. Piperazine and sterically-hindered amine production concentrates in Germany and the Netherlands, while activated alumina for Claus catalyst substrates draws from China and Australia. Single-source vulnerability runs through specialty solvent manufacturers exposed to freight cost volatility. Distribution feeds from Rotterdam and Houston chemical hubs through EPC contractors to end-user installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in solvent formulation premiumization and hybrid technology integration, as regeneration energy penalties push operators toward higher-value bundled service models.
For Market Incumbents: Anchor positions through captive catalyst and adsorbent portfolios that lock in replacement cycles at United States Gulf Coast refineries facing EPA National Ambient Air Quality Standards tightening. Deepen backward integration into piperazine production to offset Dutch and German supply concentration risk. Prioritize certification investment for lower-global-warming-potential amine formulations ahead of EU F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: Membrane-cryogenic hybrid pretreatment systems offer a technology-first wedge into Qatari and Australian LNG train retrofits where lean reservoir gas processing demands modular alternatives to amine loops. Target India's tier-2 City Gas Distribution expansion under Petroleum and Natural Gas Regulatory Board specifications, where compact skid-mounted units address residential and transport demand gaps. Pursue joint development agreements with national oil companies to bypass incumbent EPC relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where corrosion metallurgy expertise scarcity fragments mid-sized EPC execution capacity for high-pressure sour gas developments. Long-term viability favors targets with integrated solvent regeneration and reclamation capabilities serving blue hydrogen clusters in the Netherlands and United Kingdom. Watch membrane material breakthroughs above 20 bar hydrogen sulfide partial pressure as inflection indicators for displacement potential in high-pressure reservoir applications.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast LNG terminal construction at Corpus Christi and Sabine Pass drives acid gas removal additions. |
| Backward Integration | Captive piperazine production insulates processors from Dutch chemical manufacturer allocation risk. |
| Long-term Supply Agreement | Throughput fee restructuring with BASF and Dow extends contract duration beyond catalyst replacement cycles. |
| Technology Licensing | Membrane-cryogenic hybrid configurations penetrate Qatari lean gas processing without amine solvent loops. |
| Joint Venture | Rotterdam and Eemshaven blue hydrogen clusters embed carbon capture trains doubling treatment intensity. |
Research Methodology
Direct dialogue with plant managers at United States Gulf Coast refineries, procurement leads at Qatari LNG operators, EPC contractors specializing in sour gas projects, and technical R&D directors at German chemical manufacturers grounded qualitative assessments. Secondary validation drew from EPA enforcement data, EU ETS transaction records, FERC pipeline safety filings, and customs trade data for activated alumina and specialty amine imports. Bottom-up installation counts across technology segments triangulated against top-down energy demand projections.
Segment-level outputs across the projection horizon reflect technology, application, end user, and product type dimensions, with regional production hub clustering for supply-side calibration. CAGRs derived from regression against historical capacity additions and regulatory mandate timelines incorporated hydrogen blending specifications and carbon border adjustment mechanisms as emerging demand drivers.
The model holds under stable regulatory enforcement and continued LNG offtake contract structures; deviation in EU F-Gas Regulation phase-down acceleration or membrane material performance breakthroughs would shift technology substitution trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Wood Pellet Market
Fuels
Diesel As Fuel Market
Fuels
Fuel Quality Testing Market
Fuels
Aviation Fuel Market
Fuels
LPG Vaporizer Market
Fuels
Global Charcoal Market
Fuels
Fuel Oxygenate Market
Fuels
Hydrogen Tube Trailer Market
Fuels
South Africa Bunker Fuel Market
Fuels
Compressed Natural Gas Market
Fuels
China Bunker Fuel Market
Fuels
Heavy Fuel Oil Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
United States LNG Bunkering Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Solid Fuel Tablet Market