

Low-Level Order Picker Pallet Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Level Order Picker Pallet Truck Market Insights
OSHA's updated powered industrial truck standards are shifting the cost-of-entry calculus toward electric and semi-electric order picker models. Crown Equipment Corporation leverages its vertical integration in battery systems to sustain pricing flexibility across North American distribution networks. Jungheinrich anchors European demand through specialized cold-storage configurations that dominate temperature-controlled logistics corridors.
A low-level order picker pallet truck is a motorized or manually propelled material handling vehicle designed to lift loads typically up to 2,500 kilograms to heights below eye level, utilizing forks that slide beneath palletized goods for horizontal transport and ground-level order picking. Its primary commercial purpose centers on high-velocity SKU retrieval in confined warehouse aisles where full rack access remains unnecessary. Electric pallet trucks lead product type revenue pools due to sustained fleet electrification mandates, while lithium-ion battery technology captures the fastest expansion as lead-acid replacement cycles accelerate and regenerative braking extends operational uptime between charges. Third-party logistics providers represent a concentrated application segment where contract terms favor total-cost-of-ownership metrics over capital expenditure minimization.
FCC guidelines on warehouse wireless infrastructure intersect with OSHA ergonomic requirements to shape connectivity-enabled fleet management and operator safety system specifications. The EU Green Deal's material handling decarbonization targets, enforced through ECHA battery substance restrictions, are tightening product compliance thresholds for exporters. Stakeholders must monitor whether regional battery chemistry regulations fragment platform standardization or consolidate supplier ecosystems around modular lithium-ion architectures.
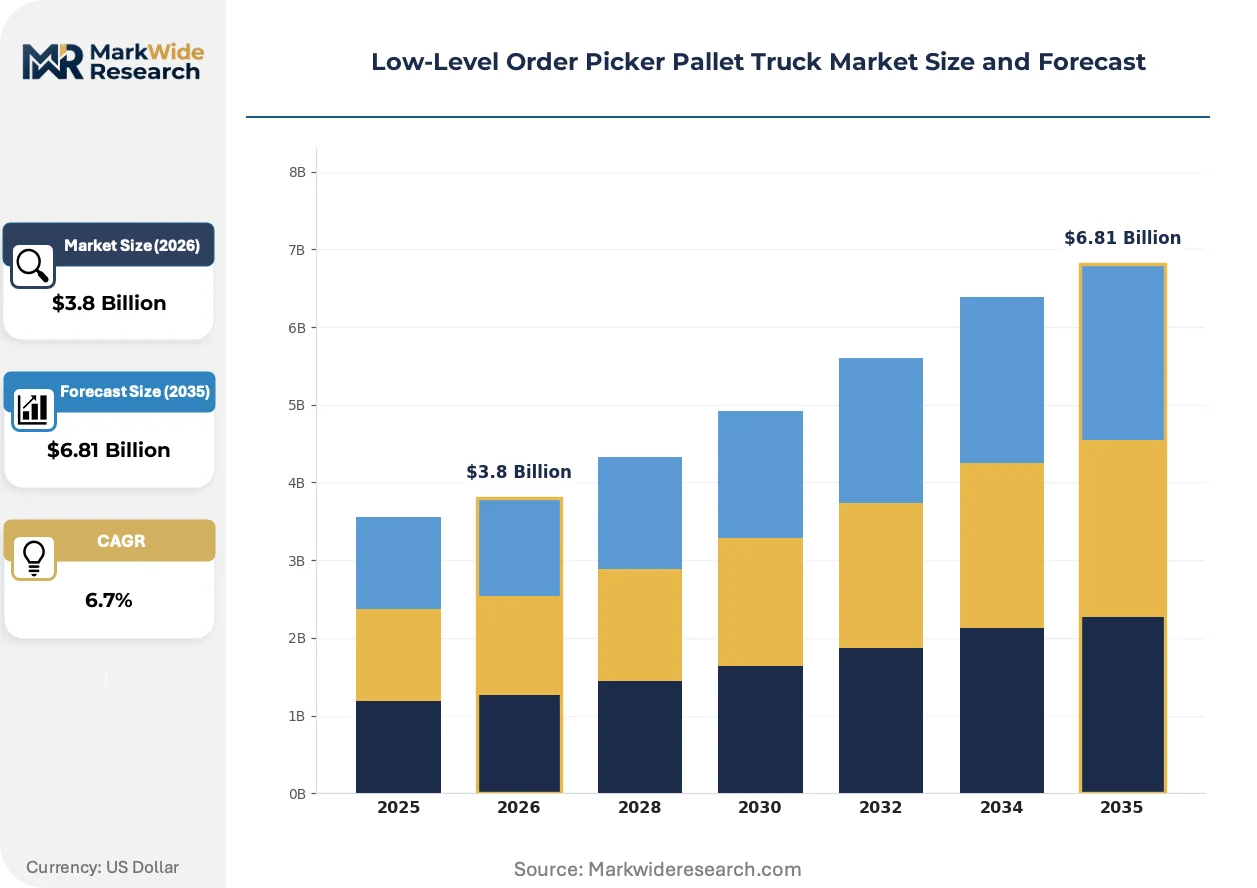
Market Dynamics
Fleet electrification economics are compressing replacement cycles as lithium-ion battery costs fall below lead-acid total-cost-of-ownership thresholds across high-velocity fulfillment networks.
Growth Catalysts
- OSHA Powered Industrial Truck Standards:Updated ergonomic and emissions requirements in US distribution centers are accelerating electric model substitution for internal combustion fleets.
- Third-Party Logistics Contract Structures:TCO-based procurement terms favoring operational expenditure models over capital minimization are expanding electric pallet truck deployment in multi-tenant warehouses.
- Lithium-Ion Chemistry Maturation:Energy density improvements and regenerative braking integration are extending runtime between charges in continuous-use e-commerce fulfillment environments.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material input cost swings for battery cathode production are compressing margin stability for electric model manufacturers.
- European Battery Substance Restrictions:ECHA compliance thresholds under EU Green Deal implementation are raising certification costs for exporters targeting temperature-controlled logistics corridors.
- Manual Pallet Jack Substitution:Low-cost hand-operated equipment retains cost advantage in capital-constrained small warehouse operations with limited throughput requirements.
Strategic Opportunities
- Cold-Storage Configuration Demand:Specialized insulated drive units and corrosion-resistant components for sub-zero pharmaceutical and food distribution represent underpenetrated premium segments.
- India Warehouse Automation:PLI scheme incentives for logistics infrastructure and organized retail expansion are creating first-mover advantages for electric fleet suppliers.
- FCC Wireless Infrastructure Guidelines:Connectivity-enabled fleet management integration with warehouse execution systems opens telemetry-based service revenue streams.
Industry Challenges
- Battery Technician Certification Bottlenecks:Lithium-ion servicing competency requirements are outpacing vocational training program throughput in key manufacturing regions.
- Legacy WMS Integration Complexity:Electric fleet telematics protocols require middleware development to synchronize with entrenched warehouse management software architectures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Level Order Picker Pallet Truck Market Trends and Innovations
Equipment intelligence and powertrain architecture are converging to redefine operational uptime metrics and fleet management economics in material handling operations.
Lithium-iron-phosphate battery chemistry is rewriting fleet electrification investment calculations by eliminating thermal runaway risks and enabling opportunity charging without full discharge cycles. Cold-storage logistics operators in Germany and the Netherlands are adopting these configurations fastest due to safety compliance requirements in temperature-controlled environments. The technology is compressing total-cost-of-ownership parity timelines against lead-acid alternatives.
EU Green Deal material handling decarbonization targets are mandating phased lead-acid battery phaseouts across member state logistics hubs by enforcement through national adaptation frameworks. Industrial consequence includes accelerated R&D expenditure toward modular battery architectures that simplify chemistry substitution. Exporters to European temperature-controlled corridors are restructuring product platforms around standardized lithium-ion form factors to maintain single-SKU compliance.
Buyer concentration among mega-fulfillment networks is consolidating procurement leverage and compressing vendor negotiation cycles toward multi-year fleet-as-a-service agreements. Third-party logistics providers are displacing direct equipment ownership with operational expenditure models bundling maintenance and battery replacement. This pattern is most visible in US e-commerce hub geographies where Amazon, Walmart, and Target distribution networks dominate volume allocation.
Low-Level Order Picker Pallet Truck Market Segmentation
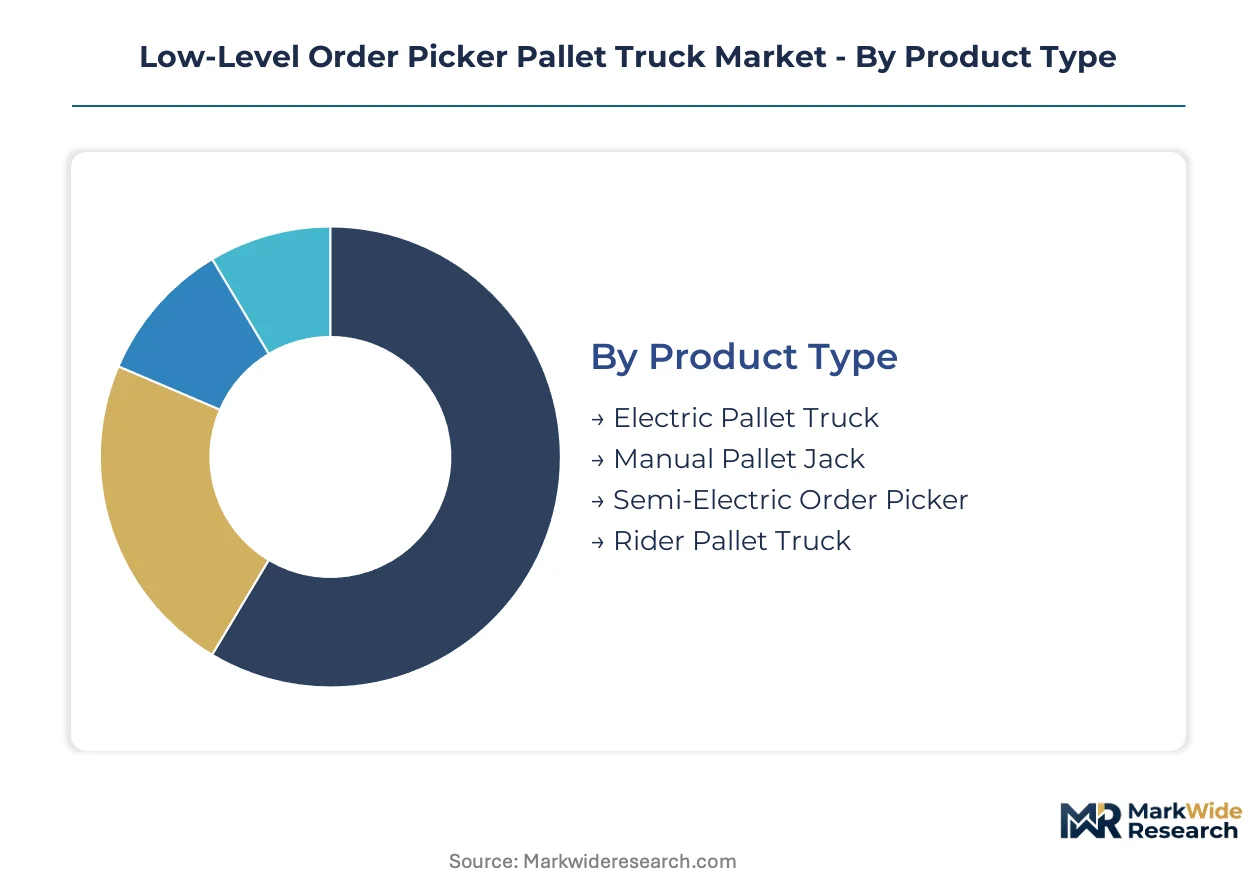
Segmentation in the low-level order picker pallet truck market reveals how powertrain architecture, operational intensity, and facility specifications dictate equipment selection. Procurement patterns diverge sharply between high-velocity fulfillment networks optimizing for total cost of ownership and capital-constrained operations prioritizing upfront expenditure minimization.
Product Type:
Powertrain configuration determines operational envelope, operator ergonomics, and fleet electrification economics across material handling environments.
- Electric Pallet Truck:Battery-powered units with sealed drive systems deliver continuous duty cycles in high-throughput corridors. Demand concentrates in German automotive parts distribution and US e-commerce hubs where OSHA emissions guidelines accelerate internal combustion displacement. Fleet-as-a-service procurement models favor this configuration for multi-year TCO optimization.
- Manual Pallet Jack:Hand-hydraulic units with no powertrain dependency serve intermittent-use environments with low SKU velocity. Capital-constrained small warehouse operations in India and Southeast Asia retain this equipment where throughput requirements remain below electrification payback thresholds.
- Semi-Electric Order Picker:Hybrid units combining manual propulsion with powered lift mechanisms bridge cost-performance gaps in mid-scale facilities. These configurations appear in European third-party logistics networks transitioning from manual equipment toward full electrification.
- Rider Pallet Truck:Stand-on platforms with elevated travel speeds serve horizontal transport over extended warehouse distances. Food and beverage distribution centers in the Netherlands deploy these for cross-dock operations requiring rapid pallet repositioning between inbound and outbound docks.
Mature deployment sits with manual pallet jacks in small-scale warehousing. Newer deployment is concentrated in electric pallet trucks across high-velocity fulfillment networks.
Technology:
Battery chemistry and motor architecture are reshaping maintenance intervals, charging infrastructure requirements, and thermal safety profiles.
- Lithium-Ion Battery:Energy-dense cells with opportunity charging capability eliminate full discharge cycles and extend operational uptime. Cold storage operators in Germany and the Netherlands adopt lithium-iron-phosphate variants fastest due to EU Green Deal safety compliance requirements in temperature-controlled environments.
- Lead-Acid Battery:Flooded-cell technology with established recycling infrastructure retains installed base in legacy fleets. Capital-constrained operations in India and Brazil continue procurement where battery replacement cycles align with shorter equipment depreciation schedules.
- AC Drive:Alternating current motor systems with reduced brush wear lower maintenance expenditure versus DC alternatives. These configurations dominate premium equipment specifications in Japanese automotive parts logistics.
- Regenerative Braking:Kinetic energy recovery systems extend runtime between charges in start-stop intensive picking operations. E-commerce fulfillment centers in the United States specify this feature for continuous-use corridors with high deceleration frequency.
- Brushless Motor:Permanent magnet designs with eliminated commutator maintenance suit sealed environments requiring minimal particulate generation. Pharmaceutical distribution facilities in Switzerland specify these for cleanroom-adjacent material handling zones.
Established infrastructure supports lead-acid battery servicing. Steepest expansion trajectory belongs to lithium-ion chemistry as replacement cycles accelerate.
Application:
Facility type dictates aisle width constraints, temperature exposure, and throughput velocity requirements.
- Third-Party Logistics:Multi-tenant operations with contract-based equipment utilization favor TCO-optimized electric fleets over capital-minimization strategies. These facilities concentrate in US distribution corridors serving Amazon, Walmart, and Target networks.
- Cold Storage Facilities:Sub-zero environments with condensation exposure require insulated drive units and corrosion-resistant component specifications. Pharmaceutical and food distribution hubs in Germany and the Netherlands dominate premium segment demand.
- Warehouse Operations:General-purpose storage facilities with standard aisle widths represent volume deployment for baseline electric and semi-electric configurations. These applications concentrate in Chinese manufacturing belt logistics parks.
- Distribution Centers:High-velocity cross-dock facilities with rapid inventory turnover specify rider pallet trucks for horizontal transport efficiency. US Midwest e-commerce hubs exhibit dense deployment of speed-optimized equipment.
- Manufacturing Plants:Production-adjacent material handling with just-in-time delivery requirements favors compact electric units for line-side pallet positioning. Automotive suppliers in Germany and Mexico specify these for assembly corridor integration.
Volume concentration remains in warehouse operations. Margin expansion concentrates in cold storage configurations.
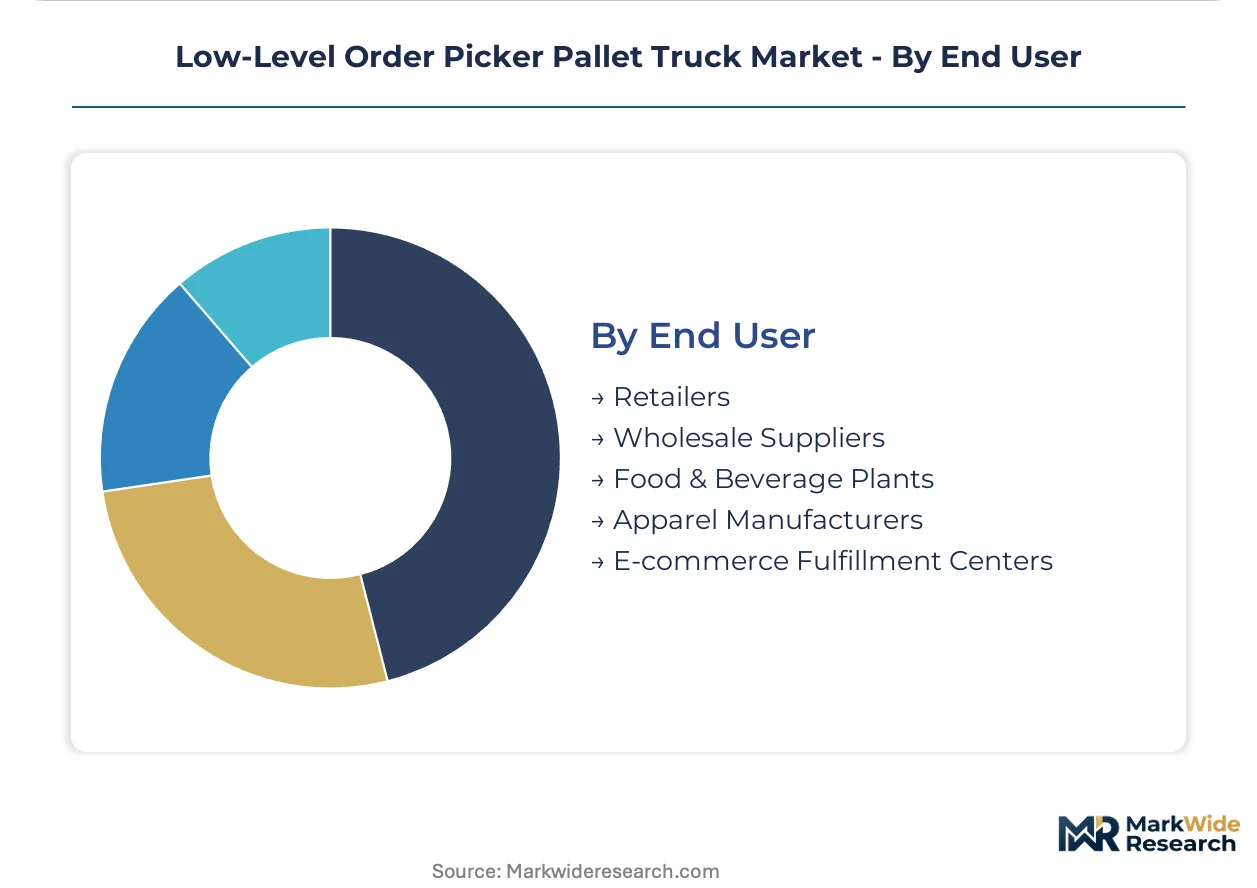
End User:
Industry vertical determines shift patterns, load characteristics, and regulatory exposure affecting equipment specification.
- E-commerce Fulfillment Centers:Continuous-operation facilities with high SKU proliferation require electric pallet trucks with extended runtime and telemetry integration. These operators in the United States and China displace manual equipment fastest under productivity-targeted procurement.
- Food & Beverage Plants:Temperature-variable environments with hygiene compliance requirements specify corrosion-resistant finishes and sealed electrical systems. European dairy and protein distributors anchor demand for cold-storage-configured equipment.
- Retailers:Store-backroom and regional distribution operations with intermittent use patterns favor semi-electric and manual configurations. Large-format grocery chains in India deploy these as organized retail infrastructure expands.
- Apparel Manufacturers:Seasonal volume fluctuation with lightweight pallet characteristics permits narrower fork configurations and reduced load capacity specifications. Bangladesh and Vietnam textile exporters concentrate demand for compact electric units.
- Wholesale Suppliers:Bulk commodity handling with standardized pallet dimensions favors rider pallet trucks for rapid dock-to-storage repositioning. US building materials and industrial parts distributors anchor this segment.
Procurement scale concentrates with e-commerce fulfillment networks. Equipment specification complexity peaks in food and beverage verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the United States as warehouse automation investments deepen and fleet electrification mandates reshape procurement patterns across high-velocity fulfillment networks.
United States
OSHA powered industrial truck standards are accelerating electric model substitution in distribution centers serving Amazon, Walmart, and Target networks. The agency's updated ergonomic requirements compress replacement cycles for internal combustion fleets. Midwest e-commerce hubs in Ohio and Illinois exhibit dense deployment of speed-optimized rider pallet trucks for cross-dock efficiency.
Germany
EU Green Deal material handling decarbonization targets are mandating phased lead-acid battery phaseouts across logistics hubs in Bavaria and North Rhine-Westphalia. ECHA battery substance restrictions under national adaptation frameworks raise certification costs for temperature-controlled corridor exporters. Jungheinrich anchors European demand through specialized cold-storage configurations dominating pharmaceutical distribution in Frankfurt and Hamburg corridors.
China
Dual carbon goals and MIIT industrial equipment electrification directives are reshaping fleet procurement in Yangtze River Delta manufacturing belt logistics parks. NMPA-aligned safety standards for pharmaceutical distribution infrastructure drive specification upgrades. Shenzhen and Shanghai e-commerce fulfillment centers displace manual equipment fastest under productivity-targeted procurement mandates.
India
PLI scheme incentives for logistics infrastructure and organized retail expansion are creating first-mover advantages for electric fleet suppliers in Maharashtra and Gujarat. BIS certification requirements for industrial battery systems are tightening product compliance thresholds. Delhi-NCR third-party logistics networks are transitioning from manual equipment toward semi-electric configurations under contract terms favoring total-cost-of-ownership metrics.
Netherlands
Cold-storage logistics operators in Rotterdam and Amsterdam distribution corridors are adopting lithium-iron-phosphate configurations fastest due to EU Green Deal safety compliance requirements in sub-zero environments. REACH-aligned substance restrictions for battery production inputs are restructuring supplier ecosystems. Food and beverage distributors anchor premium segment demand for insulated drive units with corrosion-resistant component specifications.
Low-Level Order Picker Pallet Truck Market Competitive Landscape
German producers anchor the premium-tier configuration market; Japanese and Chinese fabricators hold scale-driven and cost-optimized segments respectively. The vendor base stratifies across three tiers: integrated battery system specialists, regional chassis fabricators, and contract assembly operators serving private-label distributors. Crown Equipment Corporation exemplifies backward integration into powertrain components. Competitive moves concentrate on M&A for lithium-ion battery competency acquisition and geographic expansion through distribution network partnerships in India and Southeast Asia.
Within the integrated specialist tier, Crown Equipment Corporation and Jungheinrich occupy positions defined by captive battery system production and vertical control over charging infrastructure development. Toyota Material Handling represents the diversified industrial conglomerate archetype with cross-sector material handling platform standardization. Among Chinese fabricators, Anhui Heli sits within the state-affiliated heavy equipment expansion vector targeting Belt and Road logistics infrastructure deployment. These company structures illustrate how competitive positioning fragments across technology ownership depth, geographic origin, and end-market specialization rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Crown Equipment Corporation |
| Toyota Material Handling |
| Jungheinrich |
| KION Group |
| Hyster-Yale |
| Mitsubishi Logisnext |
| Anhui Heli |
| Komatsu |
| Doosan Industrial Vehicle |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot price volatility cascades through battery cathode production into three distinct equipment pricing tiers, compressing margin buffers for electric pallet truck manufacturers while amplifying procurement leverage for high-volume fulfillment networks.
Pricing Analysis
Volume concentration against margin dispersion separates the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade and cold-storage certification tier. Pricing pressure stems from cobalt and lithium input cost swings forcing manufacturers to absorb margin compression in contract negotiations. Third-party logistics providers exhibit lowest price sensitivity due to TCO-based procurement models, while small warehouse operators in India remain most price-sensitive.
Supply Chain Analysis
Battery cell supply rests on Chinese, South Korean, and Japanese producers controlling lithium-ion manufacturing capacity. Drive motor controllers and sealed hydraulic systems draw from German and Japanese component specialists. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through regional OEM assembly hubs with captive battery integration in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around lithium-ion competency ownership as ECHA substance restrictions and cobalt price volatility force capital-constrained fabricators toward exit or acquisition.
For Market Incumbents: Hedge against raw material cost exposure through captive battery system production or long-term offtake agreements with cathode suppliers. Deepen backward integration into powertrain components to defend margin position against Chinese cost-optimized entrants. Prioritize cold-storage certification investment to capture pharmaceutical distribution premium tiers.
For New Entrants and Emerging Players: Lithium-iron-phosphate battery platforms offer the most penetrable wedge for sub-zero logistics corridors in Germany and the Netherlands. Target India warehouse automation under PLI scheme incentives with semi-electric configurations bridging manual-to-electric transition. Pursue fleet-as-a-service partnerships with third-party logistics providers to bypass capital-intensive direct sales channels.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electric pallet truck specialists with established lithium-ion service networks in Maharashtra and Gujarat. Five-to-ten-year viability hinges on modular battery architecture adoption enabling chemistry substitution without platform redesign. Monitor ECHA enforcement intensity across EU member states as inflection indicator for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Systems | Crown Equipment's captive lithium-ion production sustains pricing flexibility across North American distribution networks. |
| Cold-Storage Configuration Development | Jungheinrich's specialized insulated drive units dominate pharmaceutical corridors in Frankfurt and Hamburg. |
| Fleet-as-a-Service Partnership | Amazon and Walmart distribution networks displace equipment ownership with operational expenditure bundling. |
| India Distribution Network Expansion | PLI scheme incentives in Maharashtra create first-mover positioning for organized retail infrastructure deployment. |
| Regenerative Braking Integration | US e-commerce fulfillment centers specify kinetic recovery systems for continuous-use corridor efficiency. |
Research Methodology
Independent corroboration across OEM procurement directors, third-party logistics fleet managers, and battery system engineers underwrites the qualitative findings. Maintenance directors at automotive parts distributors, cold-storage facility operators in Germany and the Netherlands, and aftermarket service heads provided primary field perspectives. Secondary validation drew from OSHA powered industrial truck standard filings, EU Green Deal national adaptation frameworks, MIIT industrial equipment electrification directives, and customs trade data for material handling equipment imports. Bottom-up equipment shipment analysis triangulates against top-down warehouse automation investment tracking.
Rate-of-change decomposition separates volume expansion from value migration across the analysis window. Segmentation dimensions span powertrain configuration, battery chemistry tier, application intensity, and regional regulatory cluster. CAGRs derive from equipment replacement cycle modeling and fleet electrification mandate compliance timelines. Forecast inputs incorporate lithium-ion battery cost curves and OSHA ergonomic standard enforcement schedules.
Several conditions sit outside the modeled scope, including speculative solid-state battery commercialization timelines and unannounced trade tariff adjustments on Chinese battery components. Forecasts reflect documented assumptions regarding cobalt price stabilization and EU member state enforcement uniformity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.