
 Material Handling Equipment Market | 2026-2036
Material Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Equipment Market Analysis
E-commerce fulfillment is broadening the end-use vertical mix for material handling equipment, pulling investment away from traditional manufacturing floor configurations. Toyota Industries Corporation leverages its integrated forklift and automated storage portfolio to anchor supply contracts with Asia-Pacific warehouse operators. Daifuku competes through specialized airport baggage and semiconductor cleanroom handling systems that command premium positioning. Jungheinrich AG sustains engineering leadership in narrow-aisle electric forklifts, a sub-area where battery energy density improvements are reshaping fleet economics.
Material handling equipment encompasses powered and non-powered machinery engineered to lift, transport, position, and store goods within industrial and commercial facilities, typically rated by load capacity from light-duty pallet jacks exceeding 2,200 pounds to ultra-heavy-duty overhead cranes surpassing 100 tons. Electromechanical and robotic technologies are displacing hydraulic systems in greenfield warehouse deployments, driven by precision requirements and energy efficiency mandates. Forklifts and automated storage solutions capture the dominant share of replacement demand, while conveyors represent the fastest-growing product category as omnichannel distribution centers require continuous-flow sortation architectures.
OSHA, the EU Machinery Directive, and ISO 3691-4 standards collectively shape product certification requirements, operator training protocols, and autonomous equipment deployment permissions across major demand centers. The EU Green Deal's industrial decarbonization targets are forcing manufacturers to redesign hydraulic systems and electrify pneumatic actuation pathways. Stakeholders must monitor regulatory divergence between North American and European autonomous vehicle approval frameworks, as compliance fragmentation threatens to segment supplier R&D budgets and delay cross-border equipment standardization.
Market Dynamics
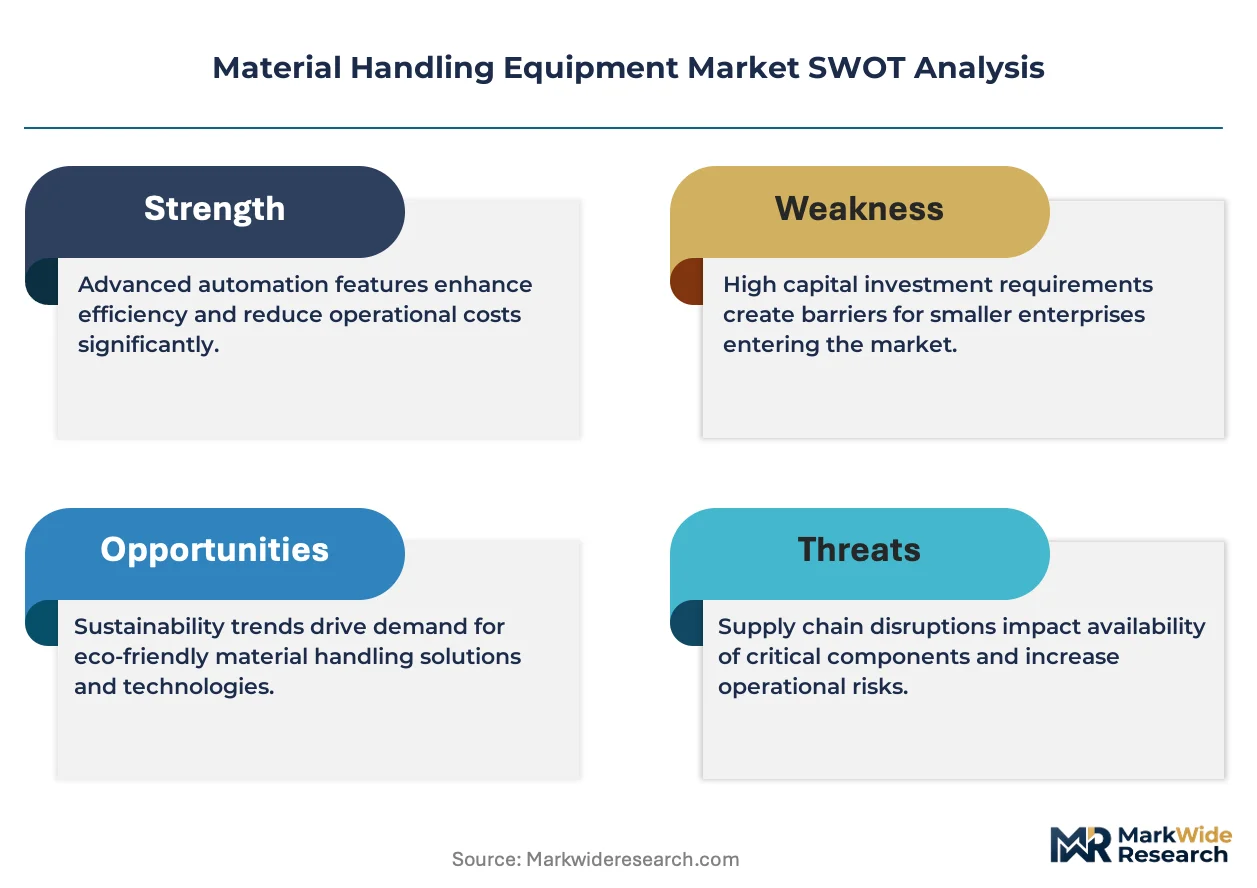
Electrification mandates and warehouse automation roadmaps are compressing replacement cycles for legacy forklift fleets while redrawing supplier competitive boundaries around energy storage integration and software stack ownership.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in Germany's industrial corridor are tripling automated storage procurement to match same-day delivery service levels demanded by retail platforms.
- EU Green Deal industrial decarbonization targets:The regulation is forcing automotive OEMs to electrify intralogistics fleets ahead of Scope 3 emissions reporting deadlines, pulling forward capital deployment timelines.
- ISO 3691-4 autonomous vehicle standards:Harmonized safety protocols are unlocking multi-site deployments of automated guided vehicles across jurisdictions that previously required country-specific certification.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing European and North American equipment assemblers to raw material availability constraints and tariff exposure.
- Skilled technician scarcity:Electromechanical system maintenance requires hybrid competencies across PLC programming, battery management, and mechanical hydraulics that vocational training pipelines have not scaled to match.
- Steel and rare earth input volatility:Overhead crane and magnetic separator manufacturers face margin compression from fluctuating neodymium and structural steel spot markets with limited forward-contract hedging depth.
Strategic Opportunities
- India's PLI scheme for manufacturing:The production-linked incentive framework is attracting material handling equipment assembly investments to serve domestic automotive and pharmaceutical distribution networks.
- Semiconductor cleanroom handling:Wafer transport systems represent a premium segment where contamination control specifications create defensible supplier positions with limited price-based competition.
- 5G-enabled fleet telematics:Real-time predictive maintenance data streams are converging with warehouse management systems to enable outcome-based equipment uptime contracts that shift revenue from capex to recurring service models.
Industry Challenges
- Multi-standard certification complexity:OSHA forklift operator training requirements diverge from EU Machinery Directive conformity assessment pathways, forcing suppliers to maintain parallel documentation systems and testing protocols for cross-border equipment shipments.
- Legacy warehouse retrofit friction:Narrow-aisle automated storage deployment in brownfield facilities requires structural reinforcement, fire suppression recertification, and floor flatness remediation that extends project timelines and erodes ROI calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Equipment Market |
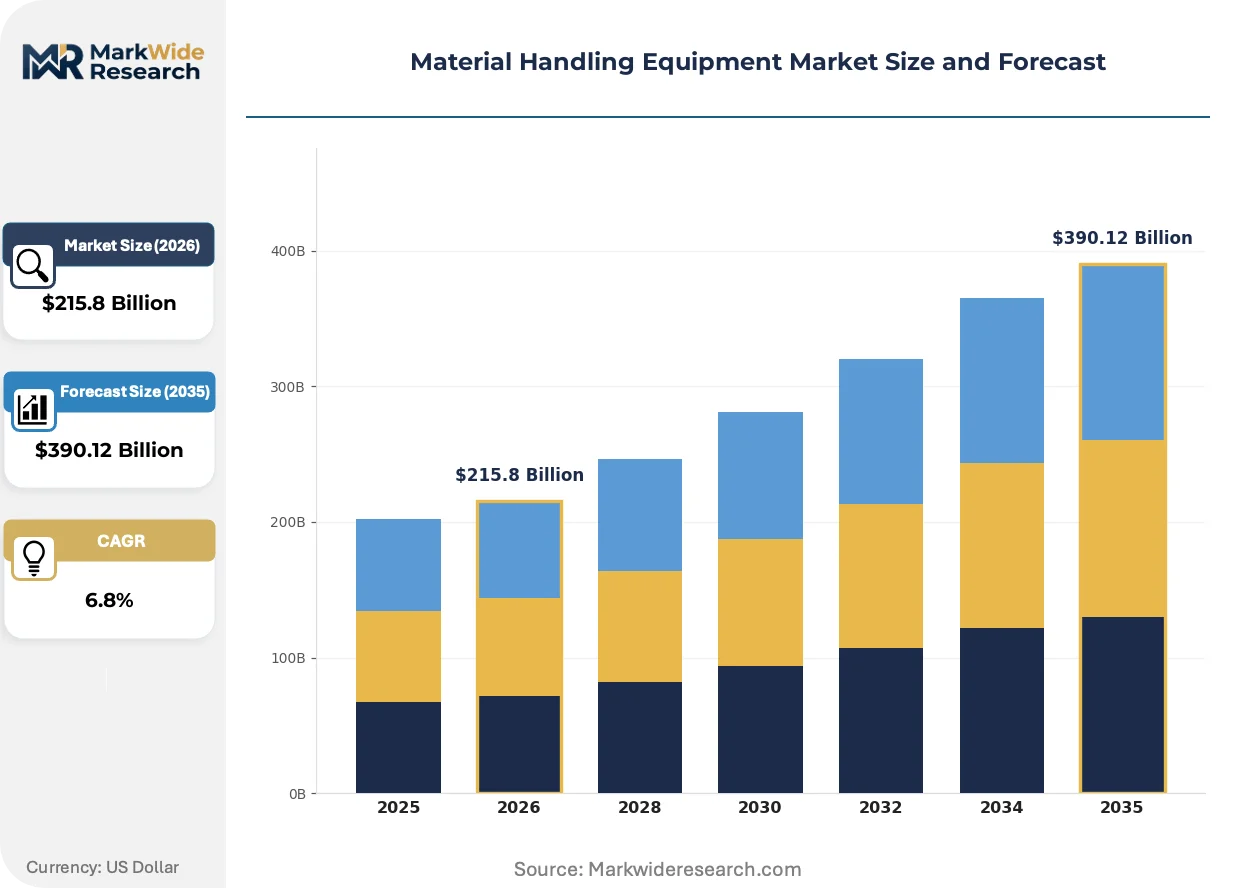
| Market Size in 2026 | $215.8 Billion |
| Market Size in 2035 | $390.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Conveyors, Pallet Jack, Automated Storage Technology: Electromechanical, Pneumatic, Hydraulic, Robotic End User: Warehousing, Manufacturing, Logistics, Retail Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | Toyota Industries Corporation, Honeywell International, Daifuku, Crown Equipment Corporation, Jungheinrich AG, KION Group, Dematic, Hyster-Yale Materials Handling, SSI Schaefer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Equipment Market Emerging Trajectories
Autonomous navigation and energy storage technologies are rewriting equipment specification sheets while regulatory pressure on emissions and operator safety accelerates replacement demand ahead of natural depreciation cycles.
LiDAR-based simultaneous localization and mapping is converging with computer vision systems to enable automated guided vehicles to operate without physical infrastructure modifications in dynamic warehouse environments. Food and beverage distributors with seasonal volume spikes are piloting these systems to eliminate fixed conveyor investments. The technology is converging with warehouse execution software to compress deployment timelines from eighteen months to under ninety days in greenfield sites.
The EU Machinery Directive's 2023 amendment on autonomous mobile robot safety requirements is mandating functional safety assessments and emergency stop interoperability that previous national implementations had left fragmented. Equipment suppliers must now certify against harmonized EN ISO 3691-4 standards to place CE marks, raising compliance costs but reducing market access friction across member states. Automated forklift deployments in France and the Netherlands are accelerating as certification clarity removes procurement committee risk aversion.
Third-party logistics providers are unbundling equipment procurement from maintenance contracts, selecting best-of-breed autonomous vehicle vendors while sourcing service capabilities from independent technical specialists. This disintermediation is compressing OEM service margins and forcing manufacturers to defend positions through proprietary battery management data and software update subscriptions. The pattern is most visible in Germany, where automotive supplier parks operate multi-vendor fleets requiring interoperable maintenance protocols.
Material Handling Equipment Market Segmentation
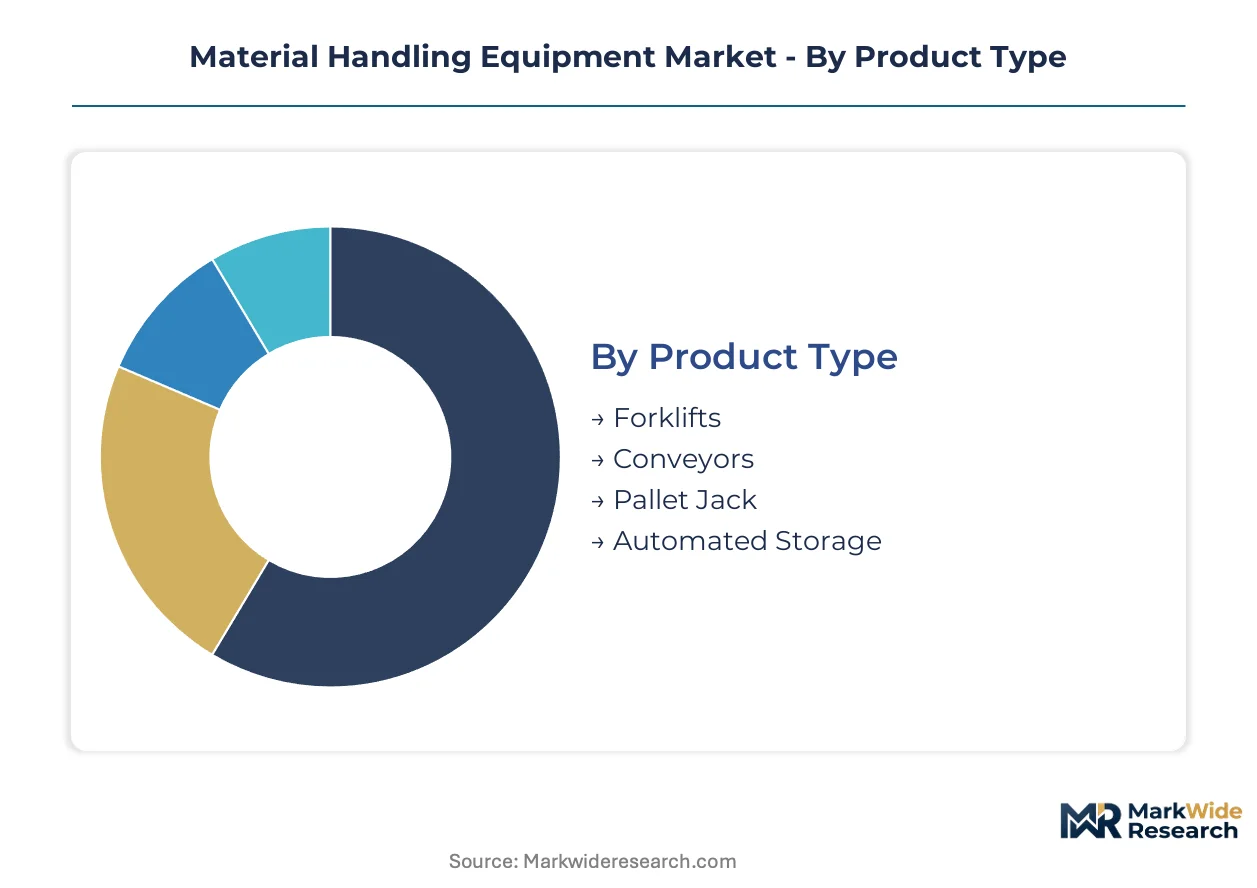
Equipment specification and duty rating determine procurement patterns across intralogistics environments. Technology integration and capacity classification reshape supplier positioning and service contract structures.
Product Type:
Load-bearing architecture and mobility configuration define operational deployment and replacement economics.
- Forklifts:Counterbalance and narrow-aisle variants dominate fleet procurement, with lithium-ion powertrains displacing lead-acid in Germany's automotive supplier parks. Electrification mandates and operator safety standards compress replacement cycles for internal combustion units.
- Conveyors:Belt, roller, and sortation systems enable continuous-flow architectures in omnichannel distribution centers. E-commerce fulfillment density in third-party logistics networks drives specification toward modular, reconfigurable designs.
- Pallet Jack:Manual and electric walk-behind units serve last-mile staging and retail backroom operations. Light-duty specifications concentrate in food and beverage distribution where load variability remains constrained.
- Automated Storage:Shuttle-based and crane-based systems maximize cube utilization in temperature-controlled facilities. Pharmaceutical distributors in India prioritize these configurations for serialization compliance and lot traceability.
Forklifts lead on scale; automated storage leads on momentum.
Technology:
Actuation methodology determines energy efficiency, precision tolerance, and maintenance protocol requirements.
- Electromechanical:Servo-driven systems deliver positional accuracy for semiconductor wafer transport and cleanroom handling. Battery energy density improvements reshape fleet economics for mobile equipment.
- Pneumatic:Compressed air actuation persists in explosive atmosphere applications and food-grade washdown environments. EU Green Deal decarbonization targets force redesign of compressor efficiency and leakage containment.
- Hydraulic:High-force lifting remains cost-effective for ultra-heavy-duty overhead cranes exceeding 100 tons. Steel input volatility and fluid disposal regulations compress margins for established suppliers.
- Robotic:Autonomous navigation and vision-guided manipulation enable goods-to-person fulfillment without fixed infrastructure. ISO 3691-4 harmonization accelerates multi-site deployments across France and the Netherlands.
Electromechanical systems lead on scale; robotic configurations lead on momentum.
End User:
Facility type and throughput velocity dictate equipment specification, duty cycle assumptions, and service intensity.
- Warehousing:High-bay distribution centers specify narrow-aisle forklifts and automated storage for cube optimization. Same-day delivery service levels demanded by retail platforms triple procurement of autonomous guided vehicles.
- Manufacturing:Just-in-sequence assembly lines require synchronized material delivery through tugger trains and automated conveyance. Automotive OEMs electrify intralogistics fleets ahead of Scope 3 emissions reporting deadlines.
- Logistics:Third-party operators unbundle equipment procurement from maintenance, selecting best-of-breed autonomous vendors. Multi-vendor fleet interoperability demands standardized battery management protocols.
- Retail:Backroom replenishment and cross-dock operations favor compact pallet jacks and low-level order pickers. Seasonal volume spikes drive interest in flexible automation without fixed conveyor investment.
Warehousing leads on scale; logistics leads on momentum.
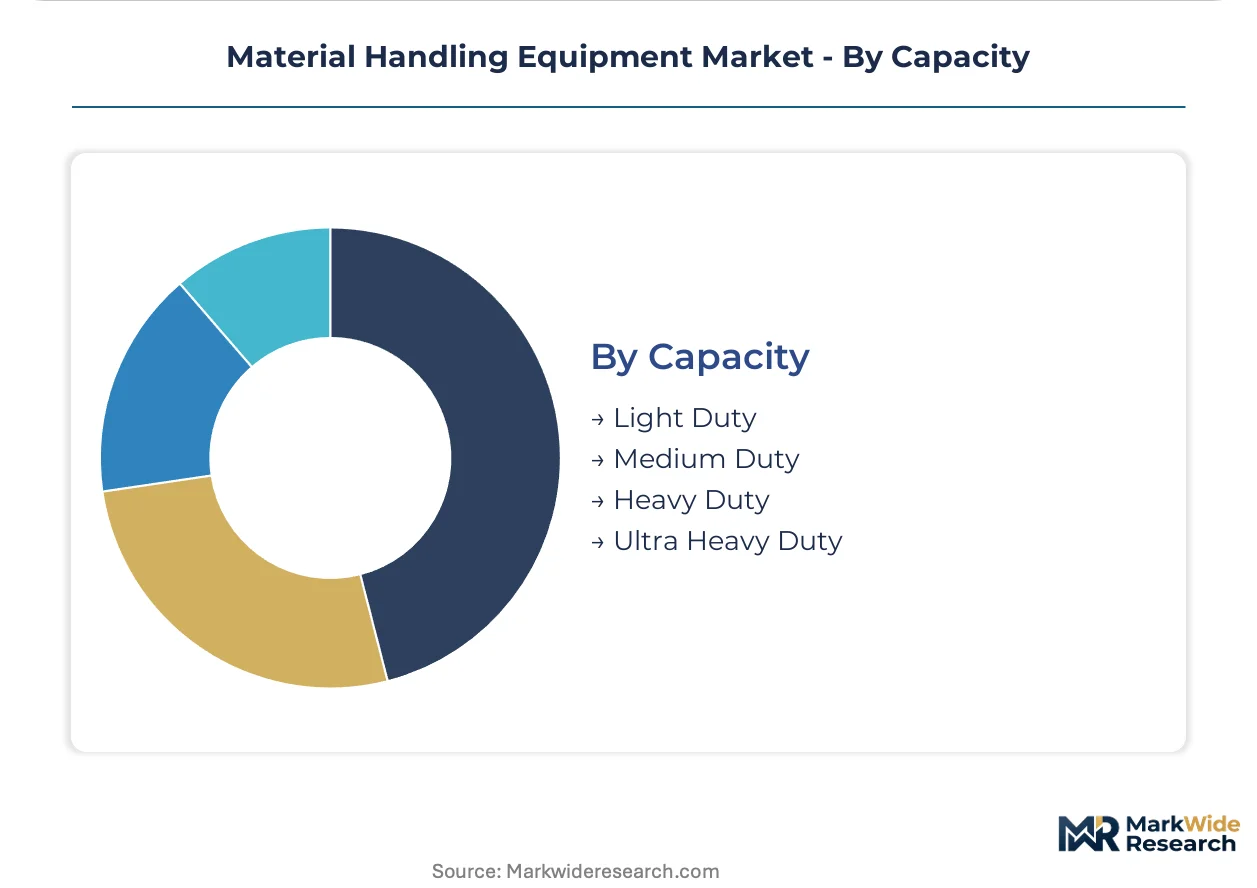
Capacity:
Load rating determines structural engineering, powertrain specification, and operator certification requirements.
- Light Duty:Equipment rated below 2,200 pounds serves retail backrooms and pharmaceutical distribution. Manual and semi-electric configurations dominate where capital constraints limit automation investment.
- Medium Duty:Standard industrial forklifts and pallet trucks handle typical manufacturing and warehousing loads. This segment captures the dominant share of replacement demand as electrification mandates accelerate fleet turnover.
- Heavy Duty:Counterbalance forklifts and reach trucks manage bulk storage and manufacturing feed operations. Battery thermal management and fast-charging infrastructure become critical specification factors.
- Ultra Heavy Duty:Overhead cranes and specialized handlers exceed 100 tons for steel, aerospace, and port applications. Rare earth magnet supply concentration and structural steel volatility expose manufacturers to margin compression.
Medium duty leads on scale; ultra heavy duty leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers are relocating assembly capacity to jurisdictions with streamlined autonomous vehicle certification pathways, exploiting regulatory-arbitrage gaps between established and emerging industrial bases.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are electrifying intralogistics fleets ahead of EU Green Deal Scope 3 deadlines. The EU Machinery Directive's 2023 amendment on autonomous mobile robot safety mandates functional safety assessments that harmonize cross-border deployment. Bavaria's Ingolstadt supplier corridor is tripling automated storage procurement to match just-in-sequence assembly requirements.
United States
OSHA forklift operator training requirements are tightening compliance costs for electromechanical equipment while accelerating replacement demand for legacy internal combustion fleets. The Inflation Reduction Act's clean energy incentives are pulling capital deployment toward battery-powered material handling in distribution networks. Chicago's third-party logistics hub is modernizing high-bay facilities with narrow-aisle configurations to serve e-commerce fulfillment density.
China
Dual carbon goals under MIIT guidance are forcing warehouse operators to retire diesel-powered forklifts ahead of natural depreciation cycles. GB standards for industrial robot safety are converging with ISO frameworks to reduce export certification friction. The Yangtze River Delta's Shanghai-Suzhou manufacturing corridor is absorbing automated guided vehicle deployments for semiconductor and electronics distribution.
India
The PLI scheme for manufacturing is attracting material handling equipment assembly investments to serve domestic automotive and pharmaceutical distribution networks. BIS certification requirements for electromechanical equipment are tightening product safety protocols that previously allowed faster market entry. Maharashtra's Pune-Chakan industrial belt is expanding automated storage capacity for serialization compliance in pharmaceutical warehousing.
Japan
METI's industrial decarbonization roadmap is pressuring manufacturers to electrify pneumatic actuation pathways in cleanroom handling systems. JIS standards for autonomous mobile robots are aligning with ISO 3691-4 to enable multi-site deployments across prefectural jurisdictions. Kyushu's semiconductor fabrication cluster is specifying wafer transport systems with contamination control specifications that command premium supplier positioning.
Material Handling Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as suppliers seek to unbundle hardware procurement from software stack ownership. The vendor base concentrates around integrated forklift-automation portfolios, specialized cleanroom handling systems, and narrow-aisle electric configurations. Three archetypes define positioning: diversified industrial conglomerates with captive battery technology, pure-play automation specialists with proprietary navigation software, and regional fabricators with cost-optimized mechanical designs. M&A activity and technology licensing agreements are the principal competitive moves reshaping supplier boundaries.
Among diversified industrial conglomerates, Toyota Industries Corporation and Honeywell International exemplify integrated portfolio strategies that span forklifts through automated storage. Daifuku occupies a position within the specialization archetype, representing premium positioning in airport baggage and semiconductor cleanroom segments. These anchors demonstrate how competitive positioning increasingly depends on energy storage integration capabilities and warehouse management software convergence rather than mechanical engineering alone.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Honeywell International |
| Daifuku |
| Crown Equipment Corporation |
| Jungheinrich AG |
| KION Group |
| Dematic |
| Hyster-Yale Materials Handling |
| SSI Schaefer |
| Others |
Supply Flow & Price Mechanics
EU Green Deal industrial decarbonization targets gate qualified supply for electromechanical equipment and reserve premium-tier pricing access to vendors with certified battery management systems and carbon-accounted production footprints. Automotive OEMs in Germany's industrial corridor now condition procurement contracts on Scope 3 emissions documentation, compressing margins for legacy hydraulic suppliers while elevating lithium-ion integrators.
Pricing Analysis
Distributor margins for material handling equipment compress as direct-to-OEM procurement expands in Germany and the United States. Three-tier pricing structure across premium, standard, and economy levels segments by battery energy density and ISO 3691-4 certification status. Cost compression in standard-tier forklifts is intensifying because Chinese cell manufacturers are flooding European spot markets with uncertified lithium-ion packs. Third-party logistics operators show highest price sensitivity due to unbundled procurement models, while semiconductor cleanroom handlers accept premium positioning for contamination control specifications.
Supply Chain Analysis
Skilled technician scarcity in Germany, Japan, and the United States constrains final assembly capacity for electromechanical systems requiring hybrid PLC and battery management competencies. Cathode material processing draws from Chinese refining clusters, while neodymium magnet supply rests on rare earth concentrate from Myanmar and Australia. Single-source vulnerability in lithium hydroxide precipitation exposes European equipment assemblers to tariff exposure under evolving trade frameworks. Distribution runs through authorized dealer networks for fleet procurement and direct technical sales for automated storage deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material handling equipment assembly offers geographic-arbitrage returns between India's PLI-subsidized production zones and Europe's carbon-border-adjusted import tariffs. The cost differential in battery cell qualification and labor arbitrage justifies greenfield capacity placement in Maharashtra over legacy German fabrication.
For Market Incumbents: Anticipate margin erosion from pure-play automation specialists with proprietary navigation software by deepening backward integration into battery management systems and captive energy storage production. Toyota Industries Corporation's integrated forklift-automation portfolio demonstrates how software stack ownership defends service contract pricing against disintermediation. Certification investment in EN ISO 3691-4 harmonization preserves cross-border market access as EU Machinery Directive amendments tighten conformity assessment pathways. For New Entrants and Emerging Players: Enter via India's pharmaceutical distribution automation corridor, where BIS certification requirements have slowed established European suppliers and created procurement gaps in serialization-compliant automated storage. Semiconductor cleanroom handling in Japan's Kyushu fabrication cluster presents penetrable white-space with limited price-based competition due to contamination control specifications. A go-to-market angle anchored in 5G-enabled fleet telematics subscriptions shifts revenue from capex to recurring service models that third-party logistics operators increasingly prefer. For Investors and Strategic Acquirers: Roll-up economics work for regional electromechanical fabricators with cost-optimized mechanical designs because procurement committees are unbundling equipment from maintenance and fragmenting vendor relationships across multi-vendor fleets. Long-term viability over the mid-decade horizon favors acquisition targets with proprietary battery management data streams that enable outcome-based uptime contracts. The signal to watch is OSHA-EU regulatory divergence on autonomous vehicle approval frameworks, which would segment R&D budgets and delay cross-border standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Assembly | Captive lithium-ion production insulates margin from Chinese cathode material supply concentration and tariff exposure. |
| ISO 3691-4 Certification Acceleration | Harmonized safety protocols unlock multi-site AGV deployments across France, Netherlands, and German automotive supplier parks. |
| 5G Fleet Telematics Platform Launch | Real-time predictive maintenance data enables outcome-based uptime contracts with third-party logistics operators. |
| Cleanroom Handling System Specialization | Wafer transport specifications in Japan's semiconductor corridor command premium positioning with limited price competition. |
| India PLI Manufacturing Footprint Expansion | Domestic assembly capacity serves pharmaceutical serialization compliance and automotive distribution network growth. |
Methodological Framework
Bottom-up warehouse operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads were validated against secondary sources including customs trade data, SEC equipment manufacturer filings, OSHA incident databases, and EU Machinery Directive implementation records. Triangulation across these inputs ensures segmentation integrity across technology, capacity, and end-use dimensions.
Input-output matrix framing connects lithium-ion battery supply assumptions to fleet electrification penetration rates across the projection horizon. Segmentation dimensions modeled include actuation methodology, load capacity tier, facility type, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis and greenfield automation deployment tracking. Industry-specific forecast inputs incorporate EU Green Deal Scope 3 compliance deadlines and ISO 3691-4 certification velocity.
Inputs from OEM production disclosures and logistics operator procurement surveys were available through the study window; gaps in brownfield retrofit project timelines introduce uncertainty bands around automated storage penetration assumptions. Forecasts reflect documented assumptions on battery energy density improvement curves and skilled technician training pipeline scaling. Material deviation in lithium hydroxide spot pricing or OSHA-EU regulatory convergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Middle East and Africa Conveyors Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Hydraulic Seals Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market