
 Global Dewatering Equipment Market | 2026-2036
Global Dewatering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dewatering Equipment Market Intelligence
Process engineering expertise for complex sludge management is bifurcating the competitive landscape. SUEZ Water Technologies & Solutions leverages its vast service network to support large-scale municipal wastewater projects. ANDRITZ differentiates through a comprehensive portfolio that includes belt presses and centrifuges. Alfa Laval sustains a strong position in the food processing sector with its high-speed separator technology.
Dewatering equipment encompasses machinery designed to separate water from solid materials in slurries and sludges. These systems apply mechanical forces, such as centrifugation or pressure via filter presses, to achieve solid-liquid separation. Centrifuges and screw presses command a significant share, driven by efficiency in wastewater treatment applications. The mining end-user segment shows strong potential, particularly for filter presses used in mineral processing.
Regulatory frameworks are a primary market accelerant. The US EPA's Biosolids Rule and the EU's Urban Waste Water Treatment Directive set stringent standards for sludge disposal, while China's dual carbon goals encourage water recycling. Consequently, equipment selection increasingly balances initial capital expenditure against long-term operational costs related to energy consumption and polymer usage.
Market Dynamics
The convergence of stringent environmental regulations and the industrial pursuit of water circularity is reshaping competitive positioning. This dynamic forces a balance between compliance with rules like the US EPA's Biosolids Rule and operational efficiency in water-intensive sectors such as mining and municipal treatment.
Growth Catalysts
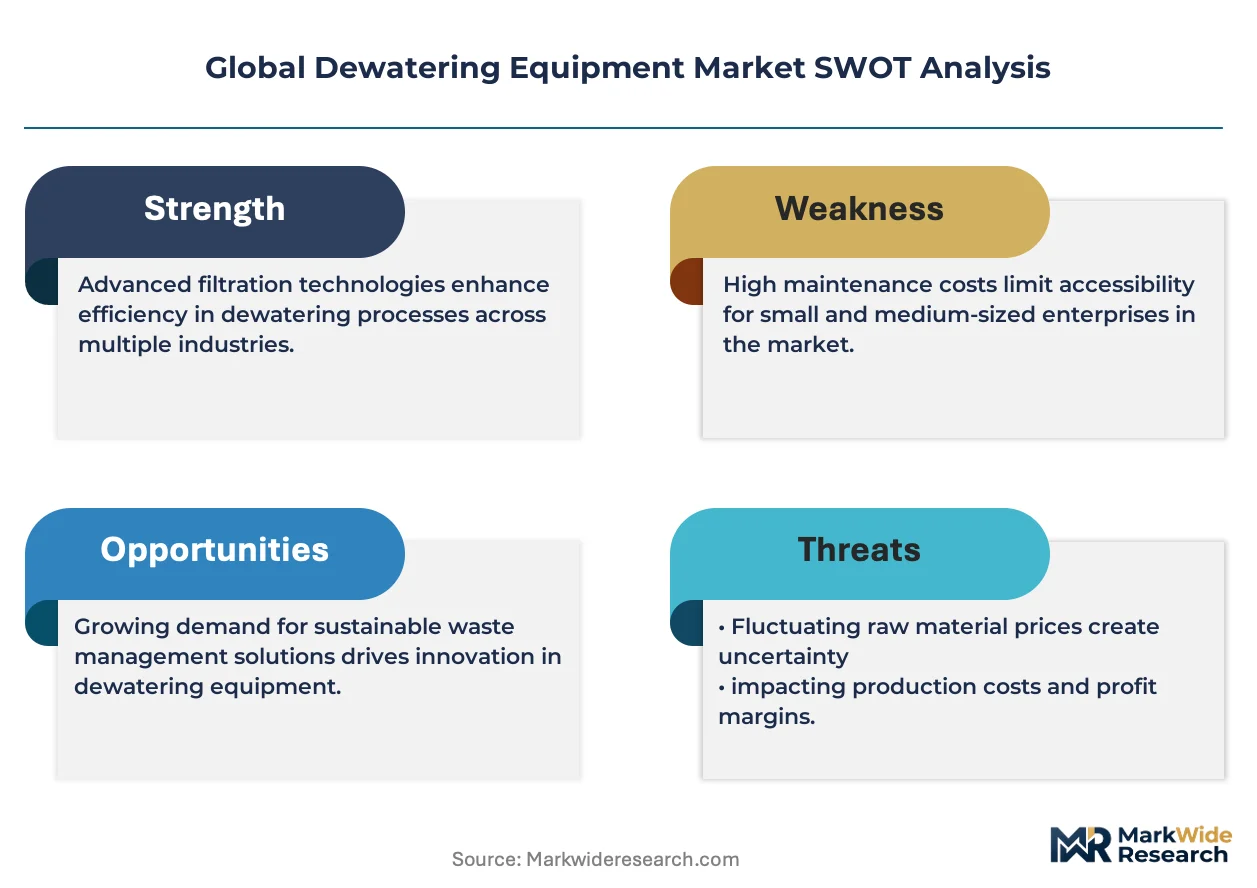
- Wastewater Directives:The EU's Urban Waste Water Treatment Directive mandates higher standards for nutrient removal and sludge management, compelling municipalities to invest in advanced dewatering technologies like screw presses and centrifuges to achieve compliance.
- Mining Sector Water Scarcity:In arid regions vital for mineral extraction, dewatering equipment is critical for water reclamation from tailings. This allows for operational continuity by creating a closed-loop water system, reducing reliance on scarce freshwater resources.
- Industrial Expansion in India:Rapid infrastructure development and industrialization in India generate substantial wastewater. This drives demand for new dewatering installations across municipal, manufacturing, and power generation sectors to manage increased sludge volumes.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for high-performance equipment, such as thermal dryers or high-speed centrifuges, acts as a barrier for smaller municipalities and industrial operators with constrained capital budgets.
- Energy Consumption:Certain dewatering technologies are highly energy-intensive, leading to substantial long-term operational costs. This economic factor can deter adoption despite the equipment's high efficiency in water removal.
- Polymer Price Volatility:The cost and availability of flocculants and polymers, which are essential for effective sludge conditioning before mechanical dewatering, are subject to market fluctuations, impacting the total cost of ownership.
Strategic Opportunities
- Emerging Contaminant Treatment:Developing specialized dewatering processes to manage sludge contaminated with persistent chemicals like PFAS presents a significant opportunity. This creates a new, high-value market for systems that can safely handle and concentrate hazardous materials.
- Smart Dewatering Systems:Integrating IoT sensors and AI-driven controls allows for real-time optimization of energy use and polymer dosing. This enables suppliers to offer outcome-based service contracts focused on performance and cost savings.
- Southeast Asia Infrastructure Gap:Underpenetrated markets in countries like Vietnam and Indonesia offer substantial growth potential. Rapid urbanization is outpacing existing wastewater treatment capacity, creating demand for both new and retrofitted dewatering systems.
Industry Challenges
- Process Engineering Talent Scarcity:A shortage of skilled engineers with expertise in complex sludge rheology and advanced dewatering chemistries limits the ability of end-users to optimize system performance and troubleshoot operational issues effectively.
- Legacy System Integration:Incorporating modern, high-efficiency dewatering units into aging wastewater treatment plants poses significant engineering and logistical challenges. Mismatches in capacity and footprint can complicate retrofitting projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dewatering Equipment Market |
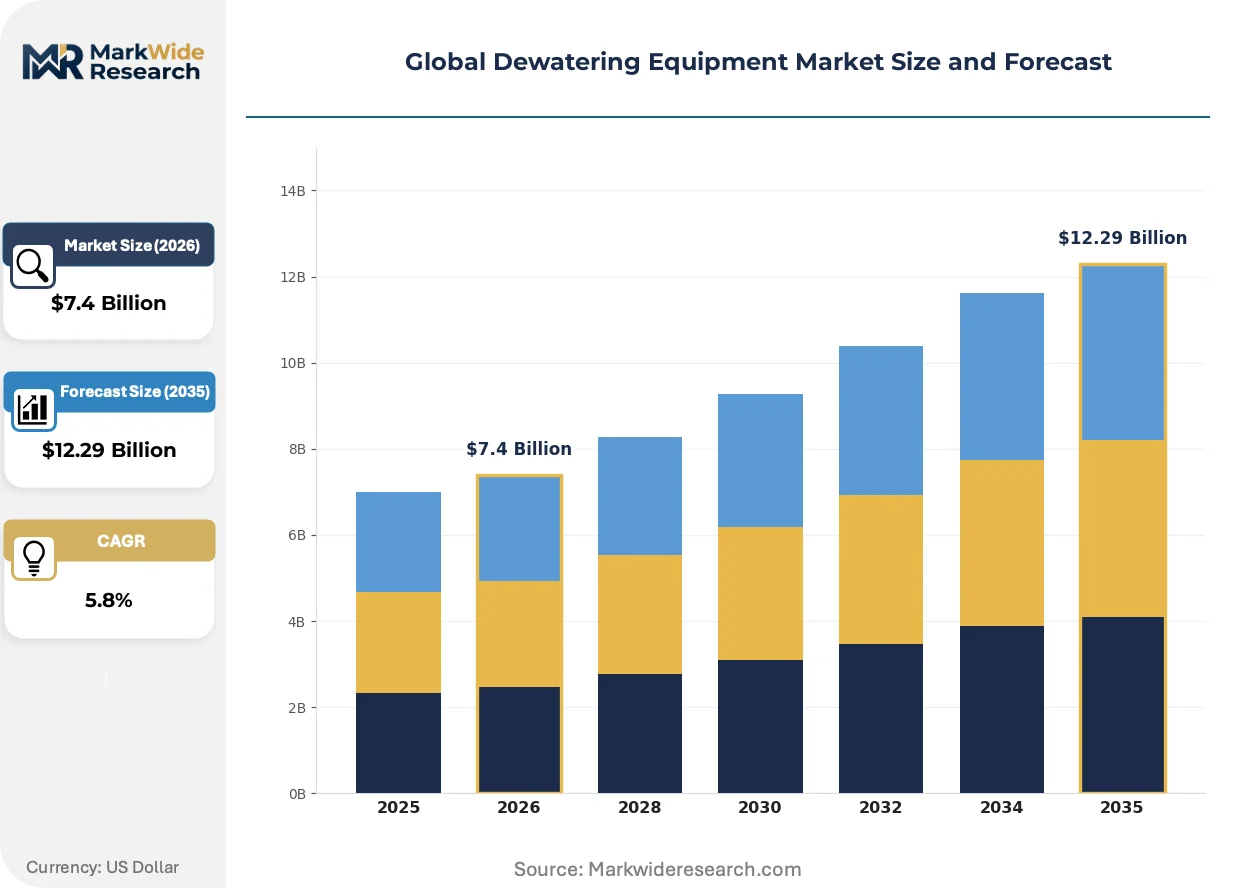
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.29 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifuges, Filter Presses, Belt Presses, Screw Presses End User: Mining, Construction, Wastewater Treatment, Food Processing Technology: Mechanical, Thermal, Chemical, Vacuum Application: Sludge Management, Water Recycling, Mineral Processing, Pulp & Paper |
| Companies Covered | SUEZ Water Technologies & Solutions, Huber SE, Veolia, GEA Group, Evoqua Water Technologies, Alfa Laval, Xylem, Flottweg SE, ANDRITZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dewatering Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by a move from purely mechanical separation toward intelligent, data-driven systems. This transition prioritizes resource recovery, reduced chemical consumption, and minimized operational expenditure, transforming equipment into integrated process solutions.
Mobile dewatering units, including containerized screw presses, provide on-demand sludge management. Small industrial facilities and remote mining sites adopt these for flexible, non-permanent installations. This trend is miniaturizing the capital-intensive footprint of dewatering, shifting from large centralized plants to distributed, point-of-use treatment.
China's dual carbon goals and MEE standards for industrial effluent compel factories to invest in water recycling. This creates a mandate for high-efficiency dewatering to reduce sludge volume and maximize water recovery. The policy most affects heavy industries like textiles, which now prioritize filter presses for closed-loop water management.
Operators are increasingly leasing equipment or signing service contracts instead of making large capital purchases. This model disrupts the traditional sales channel, favoring suppliers with strong service networks over pure manufacturers. The shift is most prominent in North America and Europe for managing biosolids, where performance guarantees are paramount.
Global Dewatering Equipment Market Segmentation
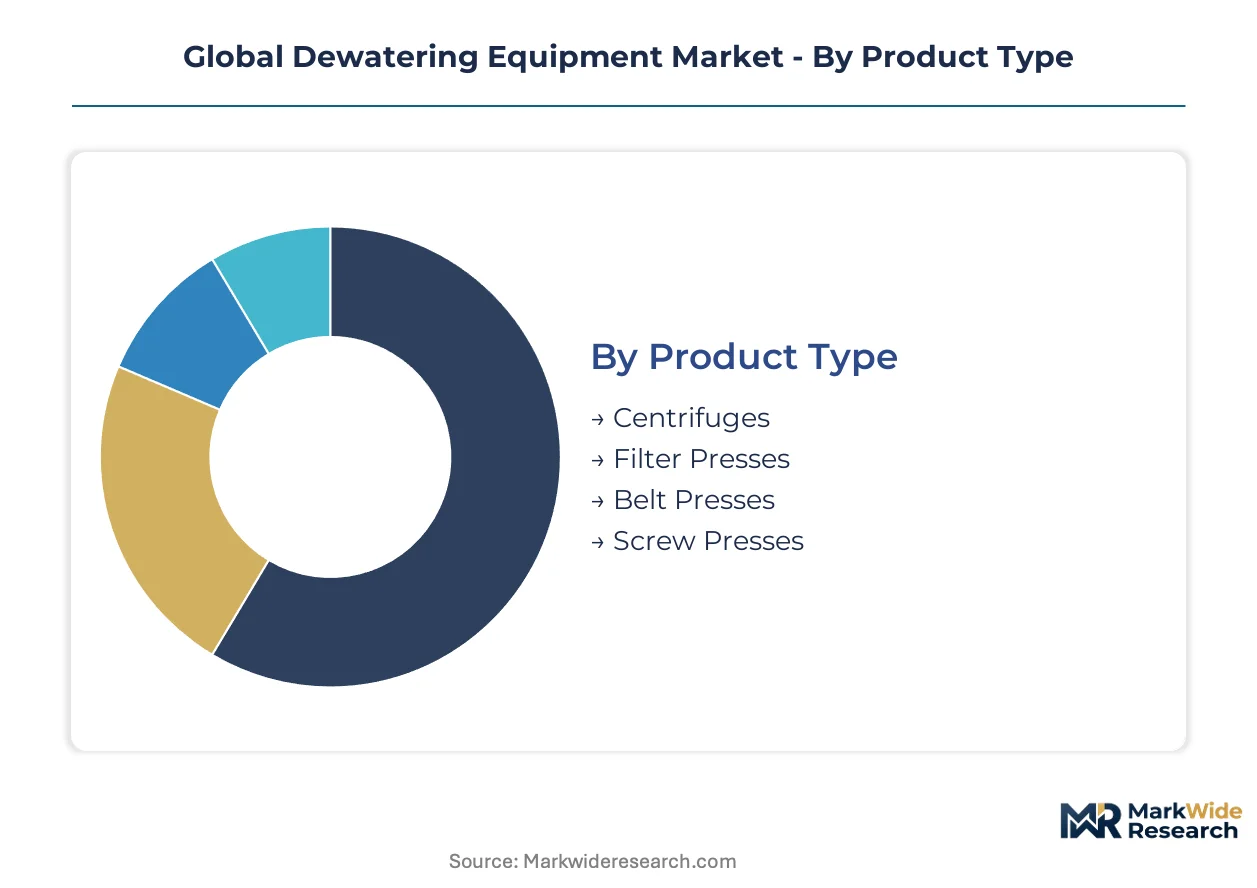
The dewatering equipment market's segmentation reveals how diverse operational needs and regulatory pressures drive equipment selection across various industrial and municipal contexts. Understanding these distinct segments helps suppliers tailor solutions for specific challenges, from high-volume sludge processing to specialized mineral recovery. Each category highlights critical differentiators impacting market penetration and growth trajectories.
Product Type:
The channel mix for dewatering equipment varies significantly by product type, reflecting specialized distribution networks and end-user procurement preferences for mechanical separation technologies.
- Centrifuges:These units utilize high-speed rotation to separate solids from liquids through centrifugal force, effectively dewatering sludge. Demand for centrifuges is concentrating in municipal wastewater treatment facilities across Europe, driven by stringent EU Urban Waste Water Treatment Directive compliance.
- Filter Presses:Filter presses employ pressure filtration, forcing slurries through permeable filter cloths to capture solid particles. Mining operations in Australia heavily utilize filter presses for mineral processing, where high-solids content and efficient water recovery are paramount for reducing environmental impact.
- Belt Presses:Belt presses use continuous pressure between two permeable belts to dewater sludge, offering a cost-effective solution for medium-volume applications.
- Screw Presses:Screw presses mechanically dewater sludge using a rotating screw within a cylindrical screen, favored by smaller industrial facilities for their compact footprint.
Centrifuges dominate the installed base for high-volume wastewater treatment. Screw presses are where expansion concentrates for distributed industrial applications.
End User:
End-user segments exhibit distinct cost tier preferences, influencing the adoption of dewatering technologies based on capital expenditure, operational costs, and regulatory compliance requirements.
- Wastewater Treatment:Municipal and industrial wastewater treatment plants process large volumes of sludge, necessitating reliable and efficient dewatering solutions to meet discharge regulations. Demand here is driven by urban expansion in India, requiring significant investments in advanced dewatering systems to handle increased wastewater generation.
- Mining:The mining sector requires robust dewatering equipment for tailings management and water reclamation, critical for sustainable mineral extraction. Operations in Chile prioritize high-capacity filter presses to recover water from mineral slurries, addressing water scarcity in arid regions.
- Construction:Construction sites utilize dewatering equipment for managing groundwater, excavations, and drilling slurries, focusing on mobile and easily deployable systems.
- Food Processing:Food processing facilities require hygienic dewatering solutions for by-products and wastewater, often opting for stainless steel equipment to meet strict sanitation standards.
Wastewater treatment represents a foundational demand segment. The mining sector is demonstrating the steepest expansion trajectory for specialized dewatering applications.
Technology:
The selection of dewatering technology is highly dependent on the specific application requirements, including sludge characteristics, desired dryness, and environmental mandates.
- Mechanical:Mechanical dewatering technologies, such as centrifuges and filter presses, apply physical force to separate solids from liquids. These systems are widely adopted in municipal wastewater treatment for primary sludge dewatering, offering a balance of efficiency and cost-effectiveness.
- Thermal:Thermal dewatering involves heating sludge to evaporate water, resulting in very high solids content and significant volume reduction. Industrial users in Germany are increasingly employing thermal dryers for biosolids, driven by stringent disposal regulations and energy recovery initiatives.
- Chemical:Chemical dewatering utilizes flocculants and coagulants to condition sludge, enhancing solid-liquid separation efficiency in subsequent mechanical stages.
- Vacuum:Vacuum dewatering employs negative pressure to draw water from sludge through a porous medium, often used for fine particles or materials sensitive to high pressure.
Mechanical methods form the bedrock of dewatering operations. Thermal dewatering solutions are gaining substantial traction for high-value applications requiring maximum dryness.
Application:
Different dewatering applications generate varying volumes of demand, influencing equipment scale, design, and the overall market landscape.
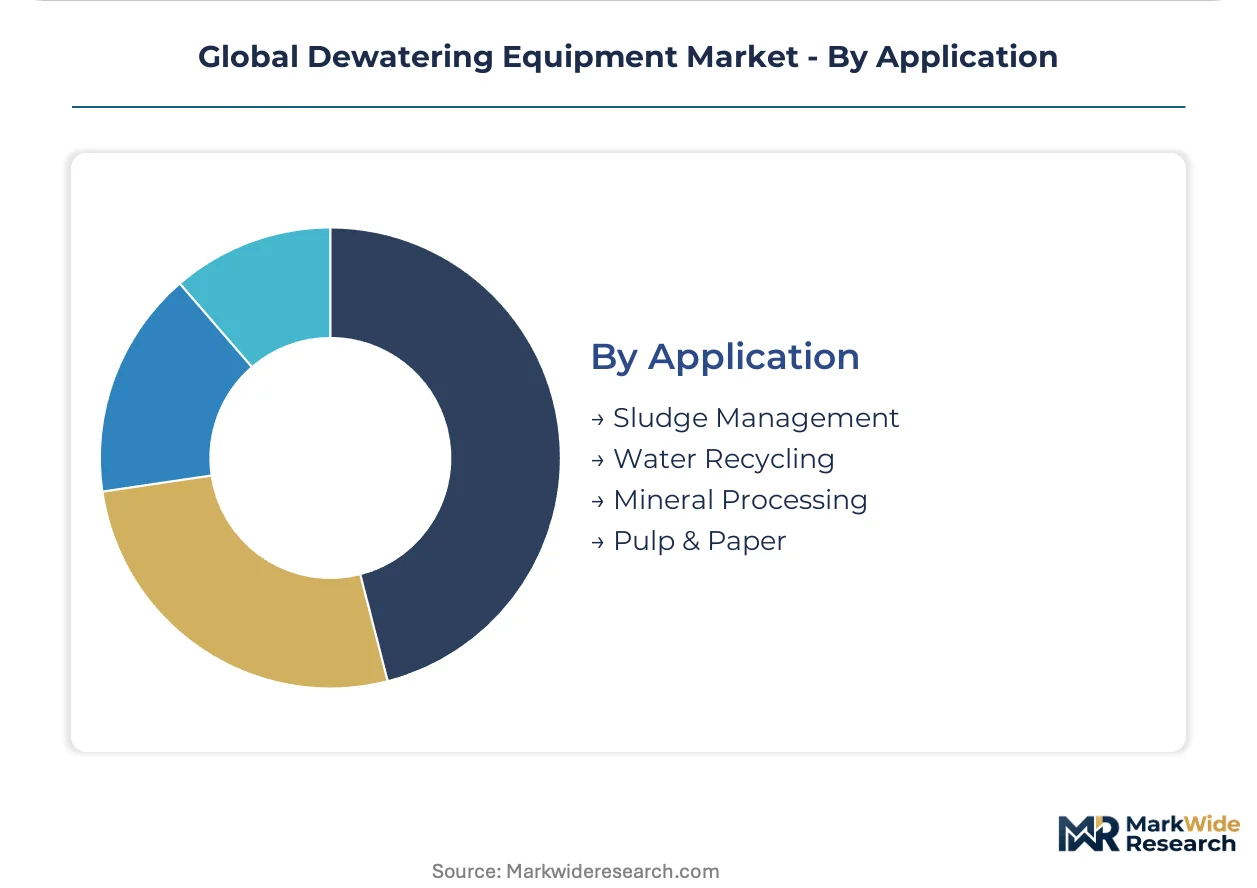
- Sludge Management:This application involves the reduction of sludge volume from wastewater treatment processes, facilitating easier disposal or beneficial reuse. Sludge management drives significant demand for belt presses and centrifuges in large municipal plants across the United States, adhering to EPA Biosolids Rule standards.
- Water Recycling:Dewatering equipment is crucial for recovering process water from industrial effluents, enabling closed-loop water systems and reducing freshwater consumption. Chinese manufacturing facilities are investing in advanced dewatering for water recycling, aligning with the nation's dual carbon goals and MEE standards.
- Mineral Processing:In mineral processing, dewatering separates valuable minerals from gangue, reducing transportation costs and improving product purity.
- Pulp & Paper:The pulp and paper industry uses dewatering for fiber recovery and sludge volume reduction from its manufacturing processes, often involving screw presses for efficient solids handling.
Sludge management consistently represents the largest volume application. Water recycling applications are rapidly expanding due to increasing environmental mandates and resource scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix differential for dewatering equipment varies significantly across global regions, reflecting diverse industrial landscapes and regulatory pressures. Demand for advanced systems is particularly high in regions with stringent environmental mandates and water scarcity challenges. Developing economies with rapid industrialization present substantial opportunities for new installations across various sectors.
United States
Sludge management and wastewater treatment drive substantial demand for dewatering equipment in the United States. The US EPA's Biosolids Rule mandates specific standards for sludge disposal, compelling upgrades in municipal facilities. Large municipal plants across the country utilize belt presses and centrifuges to adhere to these stringent regulations.
China
Water recycling initiatives and stringent environmental goals are accelerating dewatering equipment adoption in China. The nation's dual carbon goals and MEE standards for industrial effluent compel factories to invest in high-efficiency systems. Chinese manufacturing facilities, particularly in the textile industry, prioritize filter presses for closed-loop water management.
India
Rapid urban expansion and industrialization in India generate significant wastewater volumes, necessitating advanced dewatering solutions. Demand here is driven by the need to manage increased sludge across municipal, manufacturing, and power generation sectors. Significant investments are occurring in major industrial hubs like Gujarat and Maharashtra to support new installations.
Germany
Industrial users in Germany are increasingly employing thermal dryers for biosolids, driven by stringent disposal regulations and energy recovery initiatives. The EU's Urban Waste Water Treatment Directive mandates higher standards for nutrient removal and sludge management, impacting municipal operations. German industrial facilities prioritize high-value applications requiring maximum dryness for sludge.
Australia
Mining operations in Australia heavily utilize filter presses for mineral processing, where high-solids content and efficient water recovery are paramount. Water scarcity in arid regions drives the need for robust dewatering equipment for tailings management and water reclamation. Western Australia's mining sector prioritizes high-capacity systems to reduce environmental impact and ensure operational continuity.
Global Dewatering Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the dewatering equipment market. This tiered structure reflects varying capabilities, from comprehensive service offerings to niche technological expertise. Strategic archetypes include large-scale integrated solution providers, specialized technology developers, and regional equipment manufacturers. Competitive moves often involve expanding service networks and diversifying product portfolios to address evolving regulatory demands.
Integrated solution providers like SUEZ Water Technologies & Solutions leverage vast service networks to support large-scale municipal wastewater projects globally. Diversified technology firms such as ANDRITZ differentiate through comprehensive portfolios that include belt presses and centrifuges for various applications. Alfa Laval exemplifies a sector-specific specialist, sustaining a strong position in the food processing sector with its high-speed separator technology.
| Leading Market Players |
|---|
| SUEZ Water Technologies & Solutions |
| Huber SE |
| Veolia |
| GEA Group |
| Evoqua Water Technologies |
| Alfa Laval |
| Xylem |
| Flottweg SE |
| ANDRITZ |
| Others |
Cost & Logistics Intelligence
The US EPA's Biosolids Rule and similar global environmental certifications simultaneously gate supply qualification and shape price differentiation in the dewatering equipment market. This dynamic forces suppliers to invest in compliant technologies and operational excellence, directly impacting their cost structures and market positioning.
Pricing Analysis
Project-based contracts and long-term service agreements define the dominant pricing model for dewatering equipment. Price differentiation stems from the level of customization required for complex sludge rheology and the extent of after-sales service bundles. Pricing pressure stems from the high initial capital expenditure of advanced systems, particularly impacting smaller municipal operators. The mining sector, driven by critical water recovery needs, typically exhibits less price sensitivity compared to industrial facilities with constrained capital budgets.
Supply Chain Analysis
Component scarcity for specialized sensors and high-performance alloys underwriting advanced centrifuges represents a critical chokepoint. Supply concentration for these components resides in Germany, Japan, and the United States. Raw material dependencies include specialized stainless steel for hygienic applications and the volatile market for flocculants and polymers. Commodity price volatility for these chemical inputs poses a structural supply chain risk. Distribution runs through a mix of direct sales channels and integrated service networks, particularly for large-scale municipal and mining projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase, primarily driven by increasing global infrastructure spending on wastewater treatment and industrial expansion.
For Market Incumbents: Consolidate market share by acquiring niche technology developers specializing in smart dewatering systems or PFAS treatment solutions. This move can mitigate the threat of emerging contaminants requiring specialized processes. Invest significantly in R&D for energy-efficient technologies to address rising operational costs and polymer usage, enhancing long-term value propositions for end-users.
For New Entrants and Emerging Players: A service-layer gap exists in providing flexible, on-demand dewatering solutions for smaller industrial facilities and remote sites. Target underpenetrated markets in Southeast Asia with mobile dewatering units, such as containerized screw presses. A compelling go-to-market angle involves offering outcome-based service contracts focused on guaranteed performance and reduced total cost of ownership.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the advanced dewatering technology segment, signaling increased investment requirements for innovation. The long-term viability of this market is strong, anchored by stringent environmental regulations and global water scarcity. Target vertically integrated mid-cap specialists with proprietary technologies in smart controls or emerging contaminant treatment. The signal to watch is the pace of regulatory enforcement and infrastructure project approvals in key developing economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IoT and AI Integration | Optimizes energy consumption and polymer dosing for municipal wastewater plants. |
| Acquire PFAS Treatment Specialists | Addresses the high-value market for safely handling persistent chemical contaminants. |
| Develop Mobile Dewatering Solutions | Provides flexible, cost-effective sludge management for remote mining sites. |
| Invest in Energy Recovery Technologies | Reduces operational costs for industrial users and aligns with dual carbon goals. |
| Strengthen Service Network in Asia | Captures demand from rapid urbanization and industrialization in countries like India. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to build a comprehensive view of the market dynamics. This involved primary interviews with wastewater treatment plant managers, mining engineers, equipment manufacturers' R&D heads, and regulatory compliance officers. Secondary validation drew from US EPA reports, EU directives, company annual reports, and industry association publications, triangulating data through bottom-up and top-down approaches.
The analytical framework modeled market evolution across the analysis window, considering segmentation dimensions such as product type (centrifuges, filter presses), end user (wastewater, mining), technology (mechanical, thermal), and application (sludge management, water recycling). CAGRs were derived from historical trends and projected growth drivers, with infrastructure spending forecasts and environmental regulation enforcement trends serving as key inputs.
Underlying assumptions cover sustained infrastructure development and continuous regulatory tightening, with deviation risk concentrated in unforeseen economic downturns or significant shifts in raw material prices. Practitioners should keep alternative scenarios live as global economic conditions and environmental policy frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Vertical Lifts Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market