

Surface Contact Wire Rope Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Contact Wire Rope Market Insights
OSHA fall-protection mandates for construction hoisting is hardening compliance costs for wire rope suppliers entering the North American market. Bekaert leverages captive steel-drawing capacity to anchor its position in fatigue-resistant strand configurations. WireCo WorldGroup sustains geographic dominance across marine lifting channels through integrated rope-to-socket manufacturing. Kiswire specializes in compacted-strand technology for ultra-deep mining operations in Australia and South Africa.
Surface contact wire rope consists of multiple strands of metal wires laid helically around a central core, typically manufactured with tensile strengths exceeding 1,960 N/mm² and designed to transmit axial loads while resisting abrasion, bending fatigue, and environmental corrosion in continuous-flexure applications. Galvanized wire rope occupies the largest volume share due to its cost-performance balance in outdoor construction and mining environments, while stainless steel wire rope commands premium positioning in marine lifting and chemical-exposure settings where chloride corrosion threatens structural integrity. Fiber core wire rope maintains niche relevance in temporary rigging and lower-load material handling where weight reduction and shock absorption outweigh durability requirements.
FAA crane-safety directives for airport-adjacent construction, EU CE marking under the Machinery Directive, and China's GB/T standards enforced by SAMR collectively elevate testing documentation and traceability requirements across export-bound production. Japan's METI industrial standards further constrain entry for non-JIS-certified suppliers serving Tokyo Rope Mfg.'s domestic heavy machinery base. Stakeholders must monitor diverging regional certification timelines to avoid stranded inventory and misaligned capacity commitments.
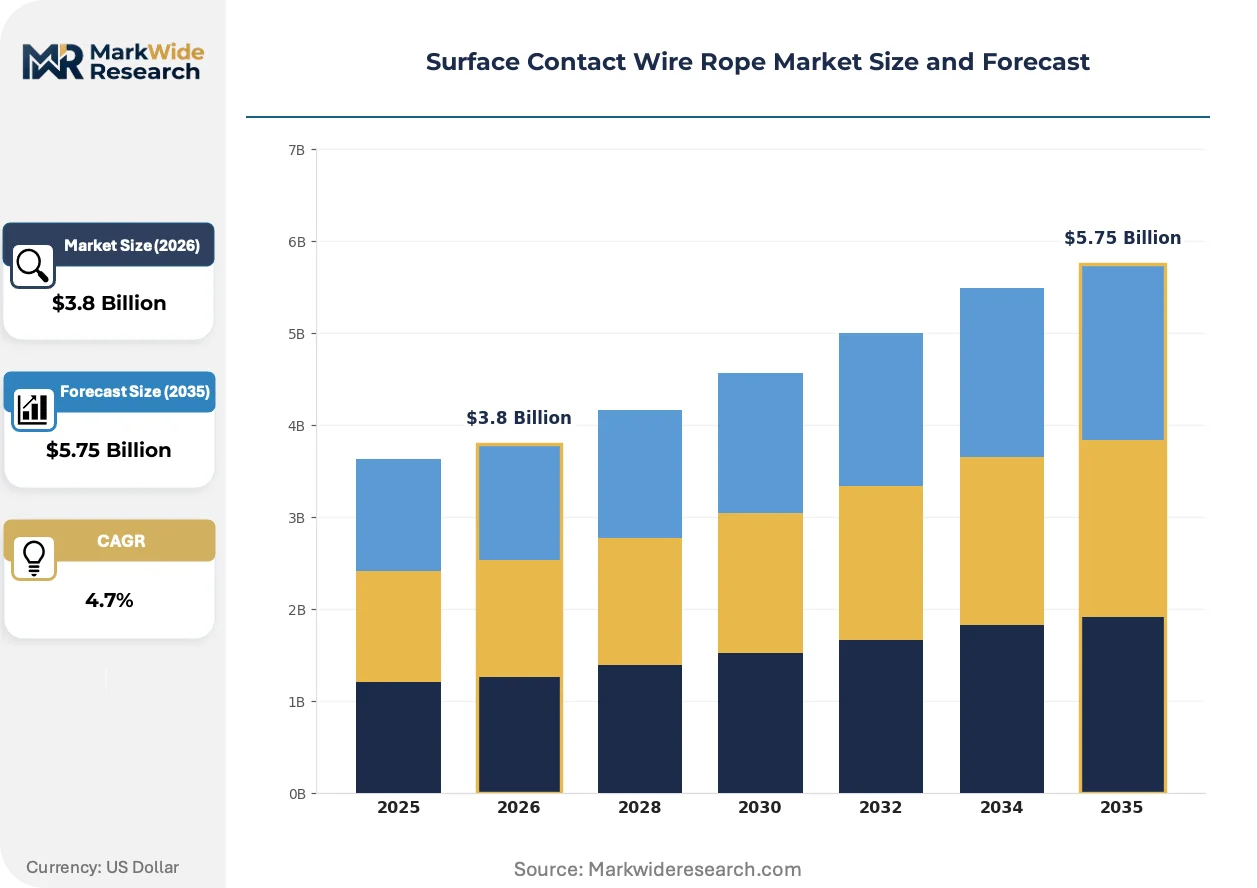
Market Dynamics
EU Machinery Directive fatigue-testing mandates and China's MEE environmental audits are forcing manufacturers to reconfigure production lines toward corrosion-resistant, traceable wire rope configurations.
Growth Catalysts
- OSHA fall-protection mandates:Construction hoisting regulations in the United States harden compliance requirements for wire rope suppliers, creating pull-through demand for certified fatigue-tested strand configurations.
- Deep mining expansion:Ultra-deep extraction operations in Australia and South Africa require compacted-strand technology capable of withstanding continuous flexure at depths exceeding 3,000 meters.
- Galvanized wire rope cost-performance:The material balance between tensile strength and environmental durability sustains volume leadership in outdoor construction and surface mining applications.
Market Restraints
- High-grade steel input volatility:Fluctuations in alloy steel pricing compress margin structures for manufacturers dependent on captive steel-drawing capacity.
- Regional certification fragmentation:Divergent timelines between EU CE marking, China's GB/T standards enforced by SAMR, and Japan's METI JIS certification create stranded inventory risk for export-bound production.
- Synthetic rope substitution:High-performance fiber alternatives threaten niche segments in temporary rigging and shock-absorption applications where weight reduction outweighs durability.
Strategic Opportunities
- Airport-adjacent construction:FAA crane-safety directives create specialized demand for documented traceability in tower suspension installations near critical aviation infrastructure.
- Marine lifting premiumization:Stainless steel wire rope configurations command positioning in chemical-exposure settings where chloride corrosion threatens structural integrity.
- Integrated rope-to-socket manufacturing:Channel consolidation toward bundled lifting system procurement favors suppliers with backward integration into termination hardware.
Industry Challenges
- Certification timeline compression:Accelerated GB/T testing documentation requirements in China strain laboratory capacity and extend product-to-market intervals.
- Skill gap in fatigue-testing protocols:Specialized technicians capable of interpreting Machinery Directive bending-fatigue specifications remain concentrated in Germany's heavy machinery corridor.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Contact Wire Rope Market Trends and Innovations
Surface contact wire rope manufacturing is experiencing material science convergence and regulatory documentation intensification that reshape competitive requirements across construction, mining, and marine verticals.
Compacted-strand technology is decentralizing traditional wire rope supply relationships by enabling ultra-deep mining contractors to specify custom helical configurations with tensile strengths exceeding 1,960 N/mm². Australian and South African extraction operators now demand strand geometries optimized for continuous-flexure drum systems rather than accepting standardized catalog offerings. This specification shift is decentralizing procurement authority from distributor networks toward direct manufacturer-engineer collaboration.
REACH substance restrictions and EU CE marking under the Machinery Directive are elevating corrosion-resistance testing documentation for galvanized and stainless steel rope configurations. Manufacturers must now maintain batch-level traceability for zinc coating thickness and alloy composition. Germany's shipyards and infrastructure contractors are responding by consolidating supplier relationships toward integrated producers with captive metallurgical laboratories.
After-sales service unbundling is disrupting traditional wire rope distribution in North American construction channels. Tower crane operators increasingly separate rope supply from installation and inspection services, compressing distributor margin capture. This pattern is most visible in airport-adjacent projects where FAA crane-safety directives mandate third-party inspection independence from material procurement.
Surface Contact Wire Rope Market Segmentation
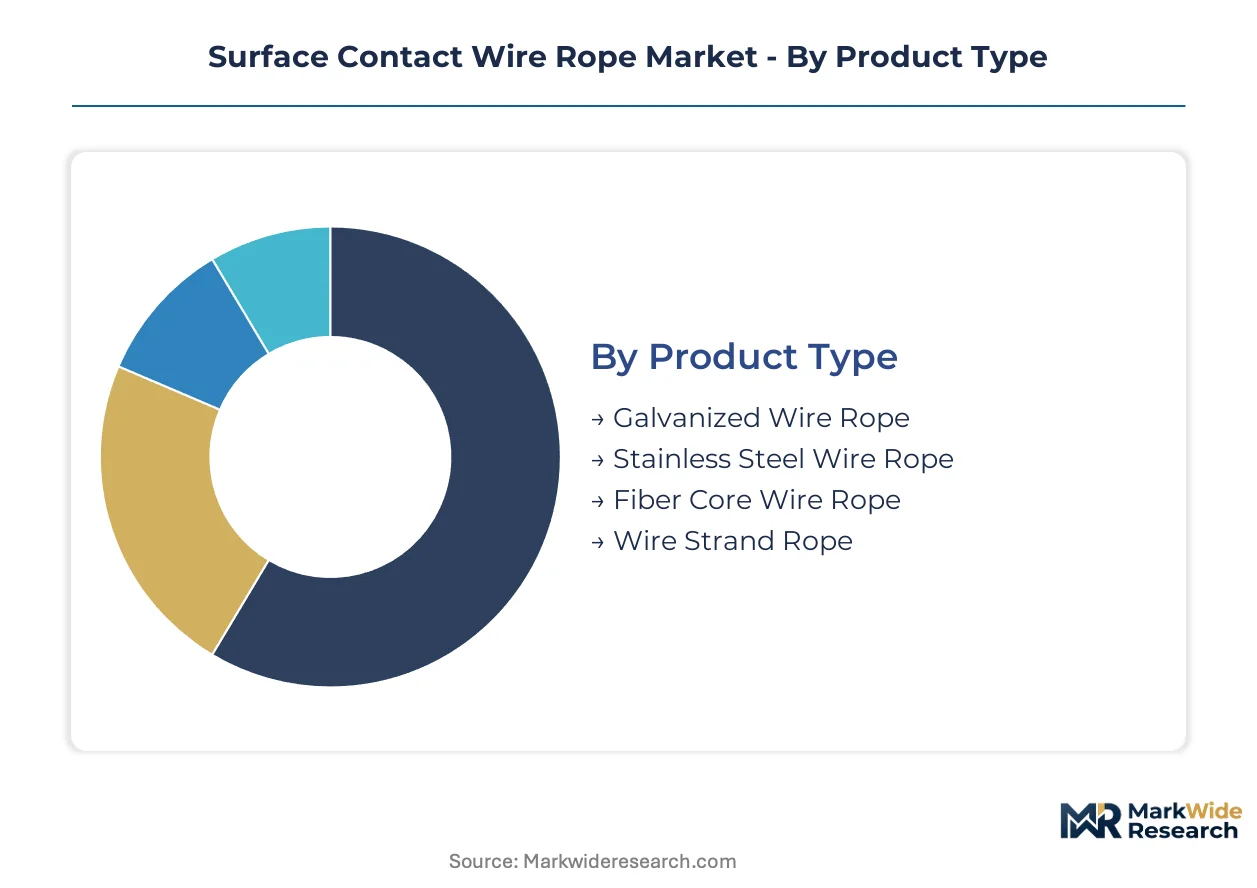
Surface contact wire rope procurement patterns diverge sharply across material grades, installation contexts, and end-user technical sophistication. Specification authority concentrates with engineering teams in heavy machinery corridors rather than distributor networks, fragmenting traditional supply relationships.
Product Type:
Capital intensity peaks with stainless steel configurations requiring captive metallurgical laboratories and batch-level traceability systems for corrosion-resistance documentation.
- Galvanized Wire Rope:Zinc-coated carbon steel construction delivers tensile strengths exceeding 1,960 N/mm² with cost-performance balance for outdoor exposure. Australian mining contractors specify this grade for surface extraction equipment where chloride exposure remains moderate. The coating thickness variability demands continuous bath monitoring, elevating operational overhead for smaller drawing mills.
- Stainless Steel Wire Rope:Austenitic and duplex alloy compositions resist chloride corrosion in marine lifting and chemical-processing environments. Germany's shipyards mandate this grade for tower suspension installations near North Sea ports where salt spray accelerates pitting. Premium positioning reflects nickel and molybdenum input volatility rather than manufacturing complexity alone.
- Fiber Core Wire Rope:Synthetic or natural fiber centers reduce weight and improve shock absorption in temporary rigging applications. Quarrying operations in South Africa deploy this configuration for short-duration material handling where drum fatigue is minimal.
- Wire Strand Rope:Multi-layer helical geometries optimize load distribution for continuous-flexure drum systems. Infrastructure contractors in China's heavy machinery corridor specify custom strand angles for ultra-deep mining beyond 3,000 meters.
Galvanized wire rope absorbs the bulk of installed capacity; stainless steel wire rope is expanding most quickly.
Application:
Volume concentration tracks extractive industry capital expenditure cycles, with procurement authority shifting from distributors to direct manufacturer-engineer collaboration in deep mining.
- Mining Operations:Ultra-deep extraction in Australia and South Africa demands compacted-strand technology with custom helical configurations for continuous-flexure drum systems. Contractors now reject standardized catalog offerings, forcing rope manufacturers to maintain engineering liaison offices near extraction sites.
- Construction Hoisting:Tower crane operations in airport-adjacent projects face FAA crane-safety directives mandating documented traceability. OSHA fall-protection regulations in the United States harden compliance documentation for axial load verification.
- Marine Lifting:Offshore platforms and port cargo systems prioritize corrosion-resistant terminations in salt-spray environments. The integration of rope-to-socket manufacturing favors suppliers with backward integration into termination hardware.
- Material Handling:Lower-load warehouse and logistics applications sustain demand for fiber-core configurations where weight reduction outweighs durability requirements.
Mining operations command the largest share of specification-grade procurement; construction hoisting shows the steepest expansion trajectory as infrastructure investment accelerates.
End User:
Customer sophistication determines whether procurement flows through integrated lifting system bundlers or fragmented distributor networks.
- Shipyards:German and Japanese builders consolidate supplier relationships toward producers with captive metallurgical laboratories capable of Machinery Directive fatigue-testing documentation. REACH substance restrictions elevate corrosion-resistance testing requirements for zinc coating thickness verification.
- Infrastructure Projects:Tower suspension installations specify premium wire strand rope with tensile strengths calibrated for dynamic load variation. EU CE marking under the Machinery Directive compels batch-level traceability that strains laboratory capacity.
- Quarrying Companies:Surface extraction operators balance durability against replacement frequency in abrasive environments. South African and Australian surface mines favor galvanized configurations for cost-performance in moderate corrosion exposure.
- Heavy Machinery Manufacturers:OEM integration of wire rope into crane and hoist systems requires fatigue-tested strand configurations with documented bending-fatigue specifications. Japan's METI industrial standards constrain entry for non-JIS-certified suppliers.
Heavy machinery manufacturers anchor specification-grade volume; infrastructure projects are gaining share fastest as airport-adjacent construction intensifies.
Installation Method:
Technical complexity escalates with elevation and dynamic load variation, concentrating premium procurement in tower suspension and crane-mounted systems.
- Crane Mounted:Mobile and tower crane systems require rope configurations optimized for multi-layer drum winding and rapid load cycling. FAA crane-safety directives for airport-adjacent construction mandate third-party inspection independence from material procurement.
- Tower Suspension:Fixed-height structural systems in bridge and building construction demand precise elongation characteristics under sustained tension. Germany's infrastructure contractors specify premium grades with fatigue-tested termination hardware.
- Pulley System:Redirected load paths through sheave assemblies accelerate bending fatigue, favoring compacted-strand geometries with optimized wire-to-strand ratios.
- Fixed Structural:Permanent installations in offshore platforms and suspension bridges prioritize corrosion-resistant alloys with minimal maintenance access.
Crane-mounted installations absorb the majority of replacement demand; tower suspension is climbing the fastest as urban vertical construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate wire rope manufacturing capacity serving domestic infrastructure and export markets. German heavy machinery corridors anchor European specification-grade demand. Australian mining belts drive premium-grade consumption for ultra-deep extraction.
China
MEE environmental audits and GB/T standards enforced by SAMR accelerate corrosion-resistant production line conversions. Infrastructure investment in tower suspension systems concentrates procurement authority in Shanghai and Jiangsu province engineering offices. Domestic manufacturers face compressed certification timelines for export-bound fatigue-tested configurations.
Germany
EU Machinery Directive fatigue-testing mandates elevate documentation requirements for shipyard and bridge construction applications. REACH substance restrictions constrain zinc coating chemistry in galvanized configurations. The North Rhine-Westphalia heavy machinery corridor concentrates specification-grade procurement among producers with captive metallurgical laboratories.
Australia
Surface and ultra-deep mining operations in Western Australia and Queensland demand compacted-strand technology for continuous-flexure drum systems. Mining contractors now specify custom helical geometries rather than standardized catalog offerings. Engineering liaison offices cluster in Perth to support direct manufacturer-contractor collaboration.
United States
OSHA fall-protection mandates for construction hoisting harden compliance documentation for axial load verification. FAA crane-safety directives for airport-adjacent projects mandate third-party inspection independence from material procurement. Tower crane operators in Texas and California increasingly unbundle rope supply from installation services.
Japan
METI industrial standards and JIS certification constrain market entry for non-certified suppliers serving domestic heavy machinery manufacturers. Tokyo Rope Mfg.'s domestic base anchors specification-grade volume for OEM crane and hoist integration. The Kanto region concentrates fatigue-testing protocol expertise for Machinery Directive-equivalent documentation.
Surface Contact Wire Rope Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and application verticals. Market structure tilts toward consolidation among integrated producers with captive steel-drawing capacity and in-house termination hardware manufacturing. Three archetypes dominate: metallurgical conglomerates with backward integration into alloy production, regional specialists in compacted-strand configurations for mining, and integrated lifting system bundlers combining rope-to-socket manufacturing. Competitive moves center on laboratory capacity expansion for accelerated certification documentation and geographic proximity engineering offices near extraction sites.
Among Belgian-Dutch metallurgical conglomerates, Bekaert occupies a position exemplifying captive steel-drawing capacity for fatigue-resistant strand configurations. WireCo WorldGroup represents the integrated lifting system archetype with rope-to-socket manufacturing capabilities. Kiswire sits within the regional specialist tier, anchoring compacted-strand expertise for ultra-deep mining applications in Australia and South Africa.
| Leading Market Players |
|---|
| WireCo WorldGroup |
| Bekaert |
| Bridon-Bekaert The Ropes Group |
| Kiswire |
| Usha Martin |
| Teufelberger |
| PFEIFER |
| Gustav Wolf |
| Tokyo Rope Mfg. |
| Others |
Pricing and Supply Chain Analysis
Compacted-strand technology adoption for ultra-deep mining applications is simultaneously elevating engineering-intensive cost structures and concentrating procurement authority among integrated manufacturers with captive metallurgical laboratories. This production-method transition compresses margin capture for standardized rope distributors while rewarding direct manufacturer-contractor relationships with pricing power anchored in specification-grade customization.
Pricing Analysis
Lead-time premiums dominate transactional pricing, with Australian mining contractors paying significant markups for certified fatigue-tested configurations delivered within compressed windows against standard catalog offerings with extended availability. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified OEM integration grades from CE-marked construction tiers and unbranded temporary rigging alternatives. Price differentiation rests on Machinery Directive documentation completeness and batch-level zinc coating traceability. Cost compression in economy-tier fiber-core configurations is intensifying because synthetic rope substitution threatens marginal applications. Quarrying operations in South Africa exhibit highest price sensitivity, while German shipyards demonstrate lowest elasticity due to REACH compliance mandates.
Supply Chain Analysis
Domestic-content requirements in China's GB/T enforcement zones and India's heavy machinery corridors are reshaping sourcing patterns toward regional steel-drawing capacity and localized termination hardware production. Geographic supply concentration centers on China, Germany, and Belgium-Dutch metallurgical clusters, with secondary nodes in Japan and South Korea for JIS-certified OEM integration. Raw material dependencies draw from high-carbon alloy steel wire rod, zinc galvanizing baths, and nickel-molybdenum austenitic alloys for marine grades. Single-source vulnerability concentrates in specialized fatigue-testing laboratory capacity for Machinery Directive documentation. Distribution runs through integrated rope-to-socket manufacturers serving direct procurement by mining contractors and heavy machinery OEMs, bypassing traditional distributor networks in specification-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface contact wire rope manufacturing is transitioning from standardized catalog production toward engineered-to-order compacted-strand configurations, displacing legacy distributor-centric supply relationships with direct manufacturer-engineer collaboration models.
For Market Incumbents: To counter synthetic rope substitution in temporary rigging segments, Bekaert-class integrated producers should expand captive metallurgical laboratory capacity for accelerated GB/T and Machinery Directive certification documentation. Backward integration into alloy steel wire rod production anchors margin defense against high-grade steel input volatility. Channel control through engineering liaison offices near Western Australian and Queensland extraction sites preserves specification-grade pricing power.
For New Entrants and Emerging Players: Airport-adjacent construction contractors represent an underserved buyer archetype requiring FAA crane-safety directive compliance with third-party inspection independence from material procurement. White-space targets include stainless steel wire rope for North Sea marine lifting applications and compacted-strand configurations for South African ultra-deep mining beyond 3,000 meters. A go-to-market angle emphasizing batch-level traceability documentation and rapid certification turnaround differentiates against incumbent laboratory bottlenecks.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated producers possessing captive steel-drawing capacity and in-house rope-to-socket manufacturing given EU Machinery Directive fatigue-testing mandates and China's MEE environmental audit acceleration. Long-term viability favors archetypes with geographic proximity to Australian mining belts and German heavy machinery corridors. The signal to watch as inflection indicator is consolidation of engineering liaison offices near extraction sites, indicating successful decentralization of procurement authority from distributor networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Capacity Expansion | Accelerated GB/T and Machinery Directive documentation reduces product-to-market intervals for export-bound fatigue-tested configurations. |
| Backward Integration into Alloy Steel Wire Rod | Captive steel-drawing capacity insulates margin structures from nickel and molybdenum input volatility in stainless steel grades. |
| Engineering Liaison Office Deployment | Perth and Johannesburg proximity enables direct manufacturer-contractor collaboration for custom helical geometry specification. |
| Rope-to-Socket Manufacturing Integration | Bundled lifting system procurement favors suppliers with in-house termination hardware production for marine lifting channels. |
| Corrosion-Resistant Coating Technology Investment | REACH-compliant zinc chemistry and duplex stainless formulations satisfy EU shipyard and North Sea infrastructure requirements. |
Research Methodology
Document review covered customs and trade data, SEC filings from publicly traded metallurgical conglomerates, and regulatory submissions to SAMR and METI, complemented by interviews with plant managers at wire rope drawing mills, procurement leads at Australian mining contractors, technical R&D directors at integrated lifting system manufacturers, and aftermarket service heads at tower crane operators. Secondary validation drew from EU Machinery Directive guidance documents, FAA crane-safety directive enforcement records, and GB/T standard amendments. Bottom-up volume estimates from application-level consumption patterns were cross-referenced against top-down capacity assessments from steel-drawing facility disclosures.
Historical shipment data from Chinese Yangtze River Delta manufacturing zones was cross-referenced against panel input from German heavy machinery corridor engineering offices and Western Australian mining procurement directors. The analytical framework models demand across material grade tiers, installation method complexity, and end-user sophistication levels throughout the forecast period. CAGRs were derived from regression analysis of capital expenditure cycles in extractive industries and infrastructure investment trajectories. Industry-specific inputs include drum system continuous-flexure specifications and REACH substance restriction compliance timelines.
Revisions become necessary when alloy steel pricing volatility exceeds historical bands, when regulatory certification timelines diverge from modeled assumptions, or when synthetic rope substitution accelerates beyond temporary rigging niches. Forecasts reflect documented assumptions regarding MEE audit enforcement intensity and EU CE marking documentation requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.