
 Autonomous Warehouse Equipment Market | 2026-2036
Autonomous Warehouse Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Warehouse Equipment Market Insights
Omnichannel distribution is tilting capital deployment toward flexible automation architectures. Daifuku Co., Ltd. anchors high-density automated storage and retrieval installations across Asia-Pacific manufacturing hubs. KION Group AG leverages its integrated forklift-to-robot portfolio to control European logistics corridors. Dematic specializes in software-orchestrated goods-to-person systems that sustain throughput during seasonal demand spikes.
Autonomous warehouse equipment encompasses self-navigating material handling systems that operate without direct human operator intervention, typically integrating LiDAR-based spatial mapping with machine vision object recognition and ISO 13849-compliant safety controllers to execute transport, storage, and retrieval tasks in industrial facilities. These systems eliminate manual travel time in fulfillment operations while reducing occupational injuries from repetitive lifting and forklift collisions. Autonomous mobile robots now capture the fastest expansion trajectory as their infrastructure-light deployment outpaces fixed conveyor installations, while automated storage and retrieval systems retain the deepest margin pools through proprietary rack engineering and control software lock-in. E-commerce fulfillment leads end-user demand as same-day delivery service levels compress order cycle times below human walking speeds.
OSHA enforces powered industrial truck operator certification requirements that accelerate substitution toward certified-operator-free autonomous alternatives, while ISO 3691-4 establishes functional safety benchmarks for mobile robot navigation that manufacturers must validate before North American deployment. The EU Machinery Directive and CE marking obligations impose additional conformity assessment burdens on equipment imported into European logistics networks. Stakeholders must monitor evolving liability frameworks for human-robot collaborative zones as jurisdictional precedents remain unsettled.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing order cycle times below human walking speeds, forcing capital deployment toward infrastructure-light autonomous mobile robots that eliminate manual travel time without fixed conveyor installations.
Growth Catalysts
- OSHA Powered Industrial Truck Mandates:Certification requirements for human forklift operators accelerate substitution toward certified-operator-free autonomous alternatives in US distribution networks.
- ISO 3691-4 Safety Validation:Functional safety benchmarks for mobile robot navigation create compliance-driven replacement cycles as manufacturers validate systems before North American deployment.
- LiDAR-Vision Sensor Fusion:Spatial mapping accuracy improvements enable autonomous navigation in dynamic warehouse environments without facility retrofits.
Market Restraints
- Proprietary Control Software Lock-In:Automated storage and retrieval systems require captive engineering support, creating switching costs that freeze mid-market buyers in legacy vendor relationships.
- LiDAR Component Concentration:Solid-state LiDAR supply concentrates among Asian optical component foundries, exposing lead time vulnerability to geopolitical friction.
- EU Machinery Directive Conformity Burden:CE marking obligations impose extended assessment timelines that delay equipment commissioning in European logistics corridors.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for electronics and automotive sectors are building greenfield warehouse infrastructure without legacy automation debt.
- Machine Vision-Edge Computing Convergence:Onboard processing eliminates cloud latency for real-time obstacle detection in high-density storage configurations.
- Same-Day Grocery Fulfillment:Temperature-controlled autonomous handling opens cold chain applications previously excluded from robot deployment.
Industry Challenges
- ISO 13849 Safety Controller Integration:Validation of compliant safety circuits extends commissioning timelines for human-robot collaborative zones.
- Legacy WMS API Fragmentation:Proprietary warehouse management system interfaces require custom middleware development for each facility integration.
- Mechatronics Technician Scarcity:Maintenance of autonomous fleets demands cross-trained personnel combining mechanical, electrical, and software diagnostics capabilities.
Report Scope
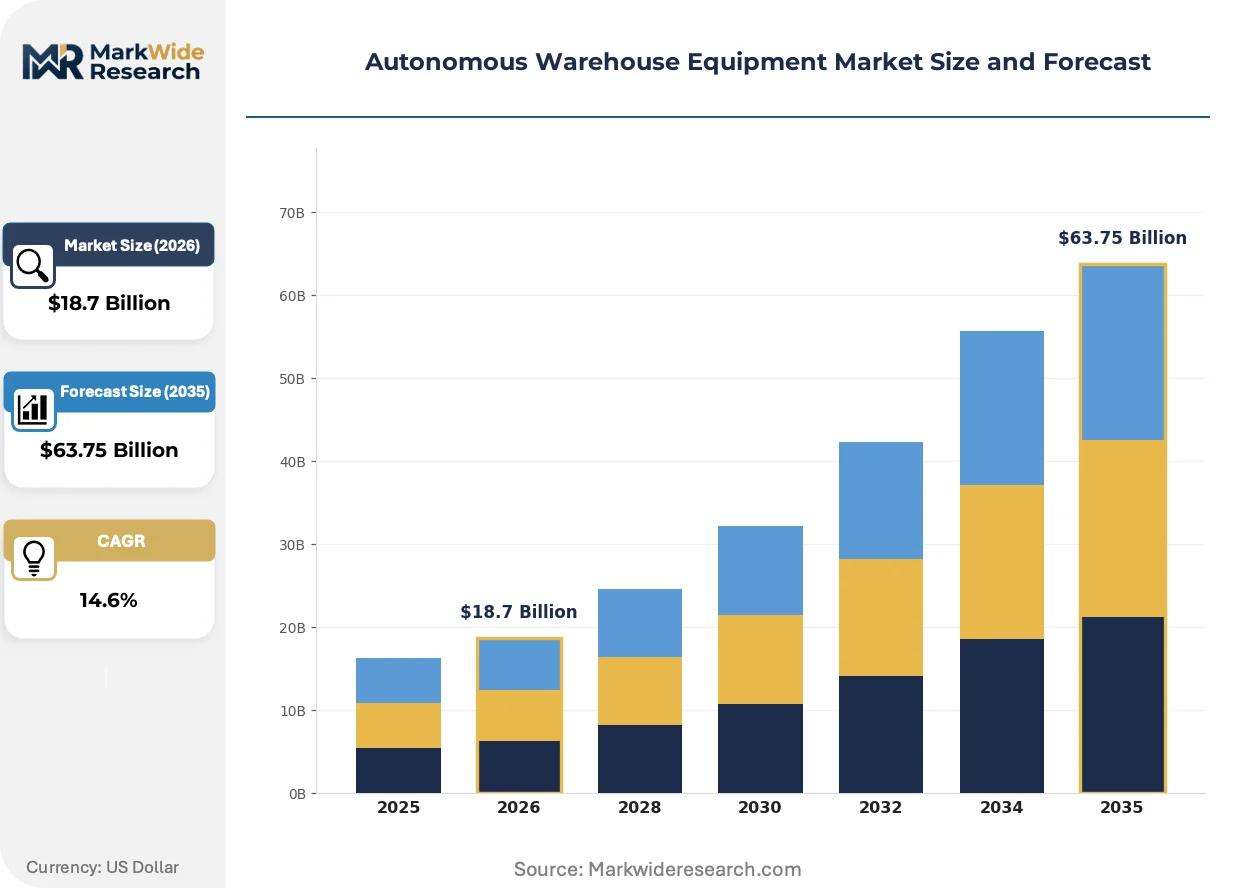
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Warehouse Equipment Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Guided Vehicles, Autonomous Mobile Robots, Automated Storage & Retrieval Systems, Conveyor Systems Technology: LiDAR, Machine Vision, Ultrasonic Sensors, RFID, GPS Application: Order Picking, Inventory Management, Material Transport, Sorting End User Industry: E-Commerce Fulfillment, Third-Party Logistics, Manufacturing Plants, Cold Storage Facilities |
| Companies Covered | Daifuku Co., Ltd., KION Group AG, SSI Schaefer, Toyota Industries Corporation, Honeywell Intelligrated, Dematic, Swisslog, Locus Robotics, Vecna Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Warehouse Equipment Market Trends and Innovations
Sensor fusion architectures and edge computing are collapsing the infrastructure requirements for autonomous navigation, enabling retrofit deployment in existing facilities without rack reconfiguration or floor-mounted guidance systems.
LiDAR-based spatial mapping combined with machine vision object recognition is collapsing the need for fixed infrastructure in warehouse automation. Third-party logistics providers are deploying autonomous mobile robots within weeks rather than months. Facility operators are eliminating magnetic tape and QR-code floor markings that previously constrained layout flexibility.
The EU AI Act risk classification framework is imposing conformity assessment obligations on autonomous navigation systems that make real-time pathfinding decisions. Equipment manufacturers must document algorithmic transparency and human oversight protocols. Mobile robot vendors are restructuring product architectures to isolate decision-making modules for regulatory audit.
Outcome-based fleet performance contracts are displacing capital purchase models among mid-market e-commerce fulfillment operators. Third-party logistics providers now charge per-pallet-move rather than equipment lease. This shift concentrates most visibly in US regional distribution networks where seasonal demand volatility makes fixed asset ownership uneconomical.
Autonomous Warehouse Equipment Market Segmentation
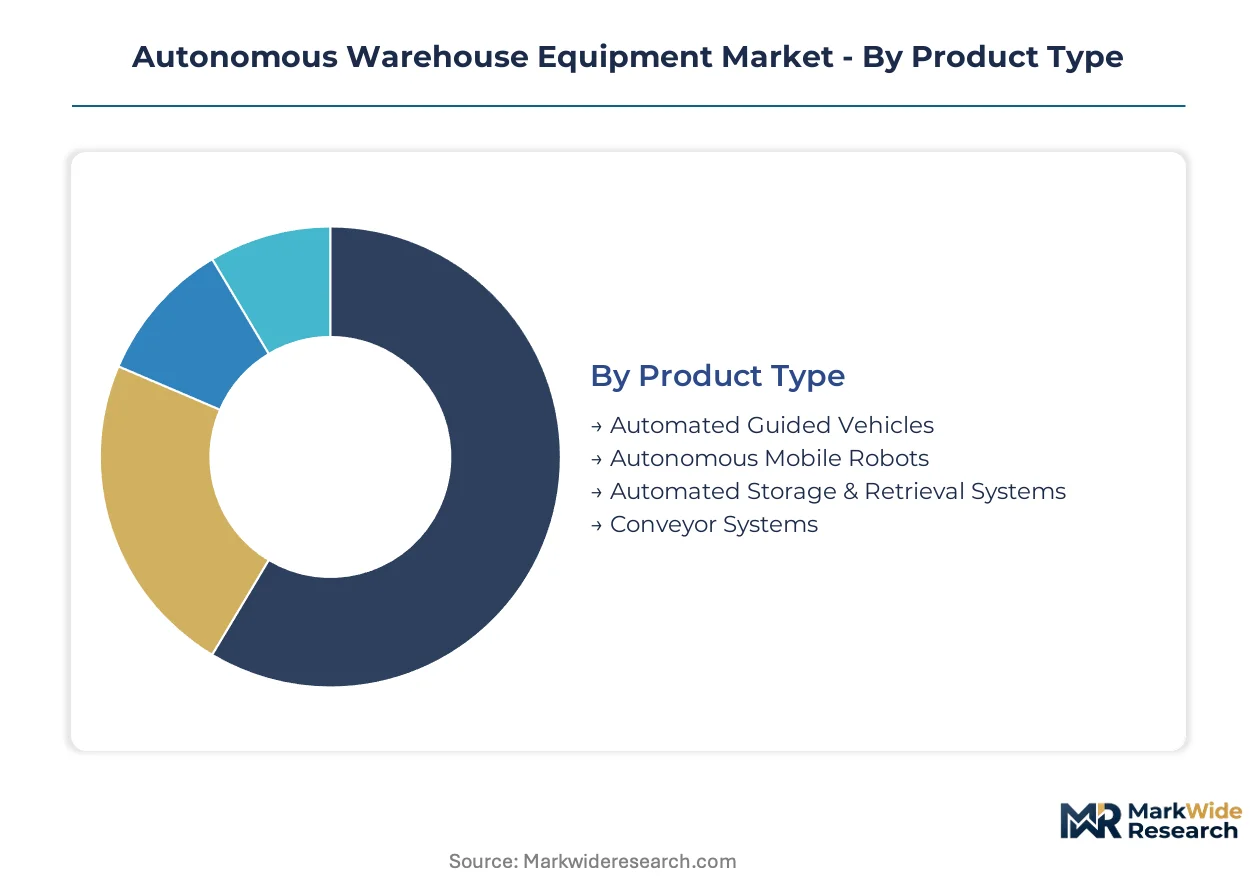
Equipment segmentation in autonomous warehousing reveals starkly different capital cycles and deployment timelines. Product categories range from decade-long automated storage installations to mobile robots commissioned within weeks. Understanding these velocity differentials shapes procurement strategy and vendor selection.
Product Type:
Cycle times vary from multi-year infrastructure builds to rapid retrofit deployments, with implications for capital allocation and facility planning.
- Automated Storage & Retrieval Systems:Fixed rack infrastructure with proprietary control software creates decade-long asset lifecycles. Deep margin pools attract Daifuku and KION Group engineering investments across Japanese and German automotive supplier networks. AS/RS dominates installed base. Autonomous Mobile Robots is where expansion concentrates.
- Autonomous Mobile Robots:Infrastructure-light navigation using LiDAR-vision fusion enables deployment without floor markings or facility retrofits. E-commerce fulfillment centers in the United States commission fleets within weeks to address same-day delivery compression. These units represent the fastest-growing trajectory as labor shortages intensify seasonal volatility.
- Automated Guided Vehicles:Magnetic tape and wire-guided systems require fixed path infrastructure that constrains layout flexibility. Legacy installations persist in automotive assembly plants with stable production flows.
- Conveyor Systems:Fixed belt and roller infrastructure for high-throughput sortation. Capital intensity and inflexibility drive substitution toward mobile alternatives in greenfield facilities.
AS/RS retains the deepest margin pools through software lock-in. AMR vendors capture the steepest expansion trajectory as infrastructure-light deployment outpaces fixed installations.
Technology:
Cost tiers separate premium sensor fusion from commodity positioning systems, with direct implications for navigation accuracy and deployment speed.
- LiDAR:Solid-state optical ranging enables millimeter-precision spatial mapping in dynamic warehouse environments. Component supply concentrates among Asian foundries, exposing lead time vulnerability to geopolitical friction. LiDAR anchors high-performance installations. Machine Vision is where adoption accelerates.
- Machine Vision:Camera-based object recognition with edge computing processing eliminates cloud latency for real-time obstacle detection. Onboard inference chips from NVIDIA and Intel enable deployment without facility network upgrades. Vision systems are climbing the fastest as compute costs decline.
- Ultrasonic Sensors:Short-range proximity detection for collision avoidance in human-robot collaborative zones. Lower cost suits budget-constrained retrofits with limited navigation requirements.
- RFID:Radio-frequency identification for inventory tracking and location verification. Passive tags enable bulk scanning without line-of-sight constraints.
- GPS:Satellite positioning for outdoor yard management and inter-facility transport. Limited indoor utility due to signal attenuation in warehouse structures.
LiDAR dominates premium navigation specifications. Machine Vision is gaining share fastest as edge computing collapses hardware requirements.
Application:
Volume concentration aligns with labor intensity — the most repetitive, travel-heavy tasks attract automation investment first.
- Order Picking:Goods-to-person systems eliminate operator walking time in e-commerce fulfillment. Dematic and AutoStore installations sustain throughput during seasonal demand spikes. Order Picking commands the largest installed base. Material Transport is where fleet expansion concentrates.
- Material Transport:Pallet and tote movement between receiving, storage, and shipping zones. AMR fleets from Locus Robotics and 6 River Systems scale within weeks in US regional distribution networks. This application is expanding most quickly as third-party logistics providers adopt outcome-based pricing.
- Inventory Management:Cycle counting and stock verification using autonomous drones and ground robots. RFID-tagged inventory enables automated reconciliation without operational shutdown.
- Sorting:Parcel and package sortation for last-mile delivery networks. High-speed tilt-tray and cross-belt systems retain fixed infrastructure advantages for peak throughput.
Order Picking retains the largest deployed fleet. Material Transport is where vendor growth concentrates as infrastructure-light deployment spreads.
End User Industry:
Customer maturity separates technology-forward adopters from legacy-bound facilities with sunk automation investments.
- E-Commerce Fulfillment:Same-day delivery service levels compress order cycle times below human walking speeds. Amazon-scale networks normalize autonomous material handling across the United States. E-Commerce Fulfillment leads deployment scale. Cold Storage Facilities is where application expansion concentrates.
- Third-Party Logistics:Outcome-based fleet performance contracts displace capital purchase models among mid-market operators. Per-pallet-move pricing concentrates in US regional networks where seasonal volatility makes fixed ownership uneconomical. 3PL adoption is gaining share fastest as contract structures evolve.
- Manufacturing Plants:Just-in-time component delivery and work-in-process transport. Automotive and electronics sectors in Japan and Germany deploy AGV infrastructure with stable production flows.
- Cold Storage Facilities:Temperature-controlled autonomous handling opens applications previously excluded from robot deployment. LiDAR and vision systems operate in sub-zero environments where human labor availability is constrained. Cold chain automation is climbing the fastest as grocery delivery expands.
E-Commerce Fulfillment dominates current deployment value. Cold Storage Facilities is where technology adaptation and vendor investment concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex anchors North American logistics throughput, while Rotterdam's Maasvlakte terminals and Singapore's Tuas megaport underwrite European and Asian distribution density respectively.
United States
Amazon-scale fulfillment networks normalize autonomous material handling across the Midwest and Southeast distribution corridors. OSHA powered industrial truck mandates accelerate substitution toward certified-operator-free alternatives in regional 3PL networks. The Inland Empire logistics cluster east of Los Angeles deploys infrastructure-light AMR fleets within weeks to address same-day delivery compression.
Germany
Automotive supplier networks in Baden-Württemberg and Bavaria demand just-in-time component delivery with stable production flows. The EU Machinery Directive and CE marking obligations impose extended conformity assessment timelines on equipment commissioning. The Rhine-Ruhr logistics corridor concentrates KION Group engineering investments across integrated forklift-to-robot portfolios.
China
E-commerce fulfillment velocity from Alibaba and JD.com compresses order cycle times below human walking speeds in Yangtze River Delta hubs. GB standards and MIIT equipment safety regulations govern autonomous navigation system deployment. The Pearl River Delta manufacturing belt builds greenfield warehouse infrastructure without legacy automation debt.
Japan
High-density automated storage and retrieval installations serve automotive and electronics sectors across Aichi and Kanagawa prefectures. METI industrial productivity initiatives subsidize facility upgrades in aging warehouse stock. The Kanto region around Tokyo anchors Daifuku engineering investments in proprietary rack control systems.
India
Production-linked incentives for electronics and automotive sectors build greenfield warehouse infrastructure in Maharashtra and Gujarat. BIS equipment safety standards and DGFT import regulations shape vendor selection for multinational logistics operators. The Delhi-NCR logistics corridor commissions AMR fleets to address seasonal demand volatility in e-commerce fulfillment.
Autonomous Warehouse Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated material handling portfolios that span fixed infrastructure and mobile robotics. Tiered competitive dynamics separate proprietary rack engineering specialists from infrastructure-light navigation vendors. Strategic archetypes include full-stack automation integrators, AMR pure-plays, and forklift incumbents extending into autonomous variants. Dominant competitive moves include vertical integration into safety controller hardware and outcome-based fleet performance contracting.
Within the full-stack integrator tier, Daifuku Co., Ltd. and KION Group AG exemplify geographic anchoring strategies that align engineering investments with regional manufacturing density. Dematic occupies a position bridging software-orchestrated goods-to-person systems and mobile fleet management. These three entities represent divergent approaches to customer lock-in: proprietary control software, integrated equipment portfolios, and outcome-based service models respectively.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| KION Group AG |
| SSI Schaefer |
| Toyota Industries Corporation |
| Honeywell Intelligrated |
| Dematic |
| Swisslog |
| Locus Robotics |
| Vecna Robotics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese solid-state LiDAR foundries is compressing component pricing while simultaneously eroding margin buffers for European and North American system integrators who lack captive optical manufacturing. This utilization imbalance forces buyers toward volume-commitment contracts that trade price concessions against supplier lock-in.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with fleet-scale deployments commanding 30-45% unit cost reductions against single-robot purchases. Pricing stratifies across ISO 3691-4 certified premium tiers, standard compliance-validated mid-tiers, and uncertified economy units for low-risk applications. Cost compression in the economy tier is intensifying because Asian component suppliers are absorbing margin erosion to maintain foundry utilization. Third-party logistics providers exhibit the highest price sensitivity due to outcome-based contract structures, while automotive manufacturers prioritize certification-grade premiums for safety liability coverage.
Supply Chain Analysis
Upstream feedstock for solid-state LiDAR sensors draws from specialized gallium arsenide and indium phosphide wafer production concentrated in China, Taiwan, and South Korea. Machine vision systems rest on CMOS image sensors from Sony and Samsung fabs, with edge computing chips sourced from NVIDIA and Intel packaging facilities in Malaysia and Vietnam. Single-source vulnerability concentrates around Asian optical component foundries, exposing lead time volatility to geopolitical friction. Distribution runs through direct OEM relationships for large fleet deployments and integrator channels for mid-market retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous warehouse equipment sector rewards organizations that control scarce mechatronics technician pipelines and proprietary safety controller architectures, as maintenance capacity constrains fleet scaling regardless of hardware availability.
For Market Incumbents: Entrench position through backward integration into safety controller hardware production and captive technician training academies in the Midwest and Rhine-Ruhr logistics corridors. Daifuku-style proprietary rack engineering creates switching costs that freeze mid-market buyers in legacy relationships. ISO 13849 compliance investment represents the priority defensive lever against emerging pure-play AMR vendors. For New Entrants and Emerging Players: Pursue cold storage facility automation as the most penetrable vertical, where temperature-constrained human labor availability and grocery delivery expansion create immediate deployment pull. India's PLI scheme-funded greenfield warehouses offer white-space entry without legacy automation displacement. Outcome-based per-pallet-move pricing models lower customer adoption friction against capital-purchase incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-orchestrated goods-to-person system vendors with multi-year maintenance contracts. Long-term viability across the analysis window favors acquisition targets combining edge computing machine vision capabilities with established European or North American service networks. Watch for inflection signals in third-party logistics provider RFP language shifting from capital expenditure to operational expenditure framing.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Fleet Performance Contracting | Dematic-style per-pallet-move pricing displaces capital ownership in seasonal 3PL networks. |
| Edge Computing Machine Vision Integration | NVIDIA inference chip deployment eliminates cloud latency for real-time obstacle detection. |
| ISO 3691-4 Safety Certification Investment | CE marking compliance opens European logistics corridors to North American AMR vendors. |
| Backward Integration into Safety Controllers | In-house ISO 13849-compliant circuit production accelerates commissioning timelines. |
| Cold Chain Automation Capability Buildout | Sub-zero LiDAR operation opens grocery fulfillment previously excluded from robot deployment. |
Research Methodology
A spread of perspectives from warehouse operations directors, mechatronics maintenance heads, OEM procurement teams, and third-party logistics contract managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K equipment disclosures, customs import records for LiDAR and vision components, and OSHA incident reporting databases. Bottom-up fleet deployment counts triangulated against top-down capital expenditure surveys from logistics real estate investment trusts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across equipment type, navigation technology tier, application intensity, and end-user industry maturity. CAGRs derived from installed base growth rates and replacement cycle compression rather than macroeconomic extrapolation. Forecast inputs incorporated e-commerce fulfillment velocity requirements and ISO 3691-4 compliance adoption curves as industry-specific demand drivers.
Sensitivities concentrate around solid-state LiDAR component lead times, EU AI Act algorithmic transparency requirements, and mechatronics technician wage inflation. Forecasts reflect documented assumptions about infrastructure-light AMR deployment velocity and cold chain technology adaptation. Cross-checking against Amazon-scale fulfillment network capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Conveyors and Belt Loaders Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Jaw Crushers Market