
 Global Submersible Slurry Pumps Market | 2026-2036
Global Submersible Slurry Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Submersible Slurry Pumps Market Outlook
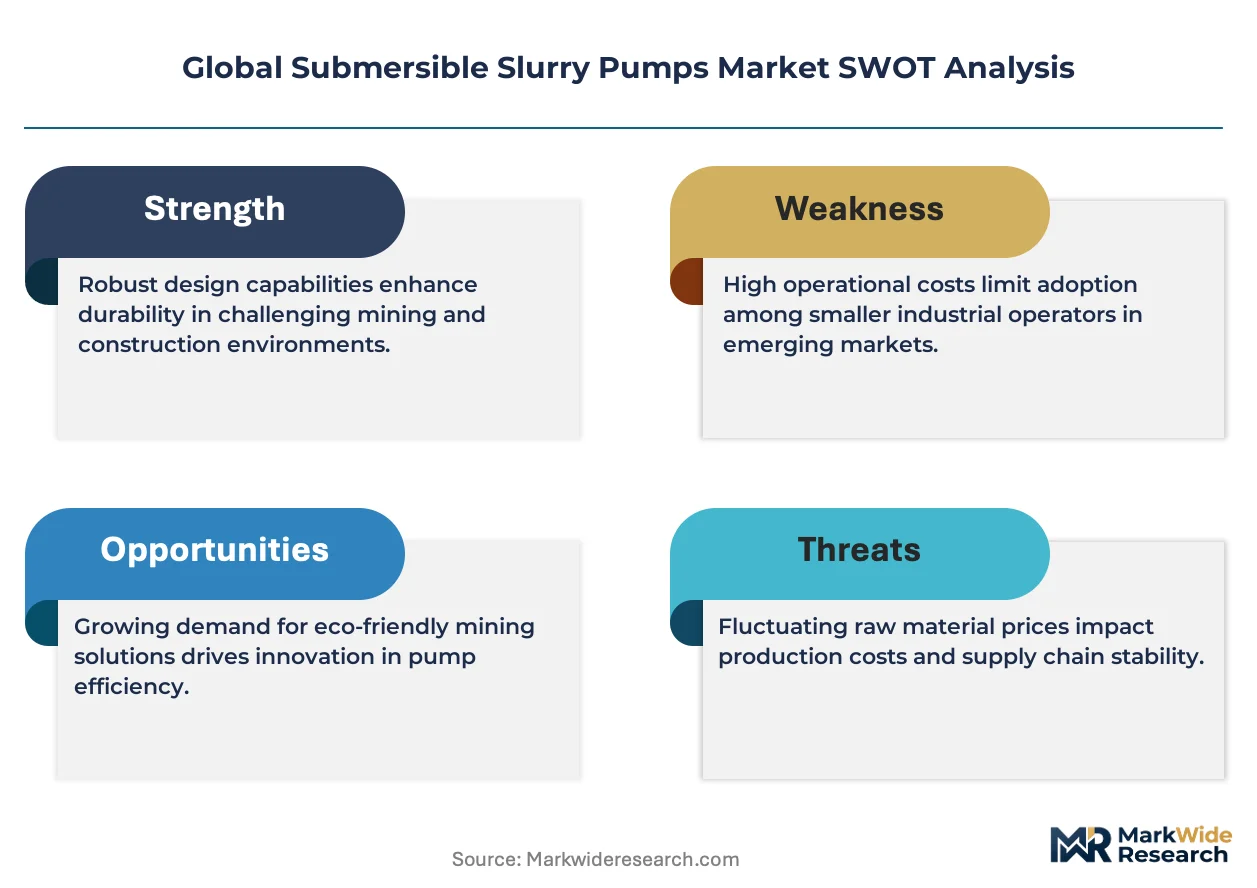
The EU Green Deal is repositioning procurement criteria for submersible slurry pumps across European mining and wastewater sectors, favoring energy-efficient designs with lower lifecycle carbon footprints. The Weir Group leverages its vertical integration in wear-resistant alloys to sustain premium positioning in hard-rock mining applications. KSB Group anchors its competitive stance through proprietary hydraulics R&D centers in Germany and China. Metso Outotec differentiates by bundling slurry pumps with downstream mineral processing equipment.
Submersible slurry pumps are centrifugal pumps designed to operate while fully immersed in fluid, typically constructed with hardened impellers and volutes capable of passing abrasive solids up to several millimeters in diameter; they handle mixtures of water and solid particles across pH ranges from acidic mine drainage to alkaline chemical slurries. Electric pumps dominate unit volume due to straightforward integration with automated control systems, while stainless steel configurations command margin premiums in chemical processing where corrosion resistance determines replacement cycles. Portable installations represent the fastest-growing installation category as contractors prioritize fleet flexibility across multiple job sites.
EPA effluent limitation guidelines and China's MEE water pollution prevention standards are tightening allowable suspended solids in discharged slurry, directly driving replacement demand for higher-efficiency pump designs with improved solids-handling curves. REACH compliance in Europe restricts certain elastomer compounds used in pump seals, pushing manufacturers toward fluoropolymer alternatives that extend service intervals. Stakeholders must monitor how evolving carbon border adjustment mechanisms affect sourcing decisions for cast iron and stainless steel pump housings.
Market Dynamics
Stricter effluent discharge mandates from regulators across multiple jurisdictions are forcing asset owners to retire legacy pump systems prematurely, compressing replacement cycles and elevating specification standards for abrasion-resistant hydraulics and seal technologies.
Growth Catalysts
- EPA effluent limitation guidelines:The US Environmental Protection Agency's tightened suspended solids thresholds for mining and industrial discharge are accelerating upgrades to higher-efficiency submersible slurry pumps with optimized solids-handling curves.
- Tailings management intensity:Australian hard-rock mining operators are expanding pump deployments for thickened tailings transport and containment, driven by catastrophic failure liabilities and rehabilitation bonding requirements.
- Dual carbon goals:China's national carbon neutrality targets are channeling state-backed infrastructure investment toward wastewater treatment clusters in industrial corridor cities, sustaining demand for energy-efficient pumping systems.
Market Restraints
- Chromium and nickel price volatility:Stainless steel alloy input costs swing with London Metal Exchange pricing, compressing margins on corrosion-resistant pump configurations specified for chemical processing duty.
- Foundry concentration in East Asia:Cast iron and specialty alloy pump housing production clusters in China and South Korea create geographic supply vulnerability for European and North American OEMs.
- REACH elastomer restrictions:The European Chemicals Agency's authorization requirements for certain nitrile and neoprene compounds are forcing seal material transitions that extend qualification timelines.
Strategic Opportunities
- Indonesia's nickel processing expansion:Battery-grade nickel refining projects in Sulawesi and Halmahera are generating greenfield demand for acid-resistant slurry pumping systems in laterite leaching circuits.
- EU Green Deal procurement criteria:Public and private mining tenders across Germany, Sweden, and Finland are embedding lifecycle carbon footprint scoring that rewards energy-efficient pump designs.
- Digital twin convergence:Integration of computational fluid dynamics modeling with IoT condition monitoring is enabling predictive maintenance contracts that transform pump vendors into service partners.
Industry Challenges
- Hydraulics engineering specialization:The scarcity of designers proficient in abrasive slurry CFD simulation and wear-resistant impeller geometry is constraining product development velocity at mid-tier manufacturers.
- Legacy SCADA integration:Brownfield mining and wastewater facilities operate proprietary control architectures that complicate retrofitting of variable-frequency drive pump systems with modern communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Submersible Slurry Pumps Market |
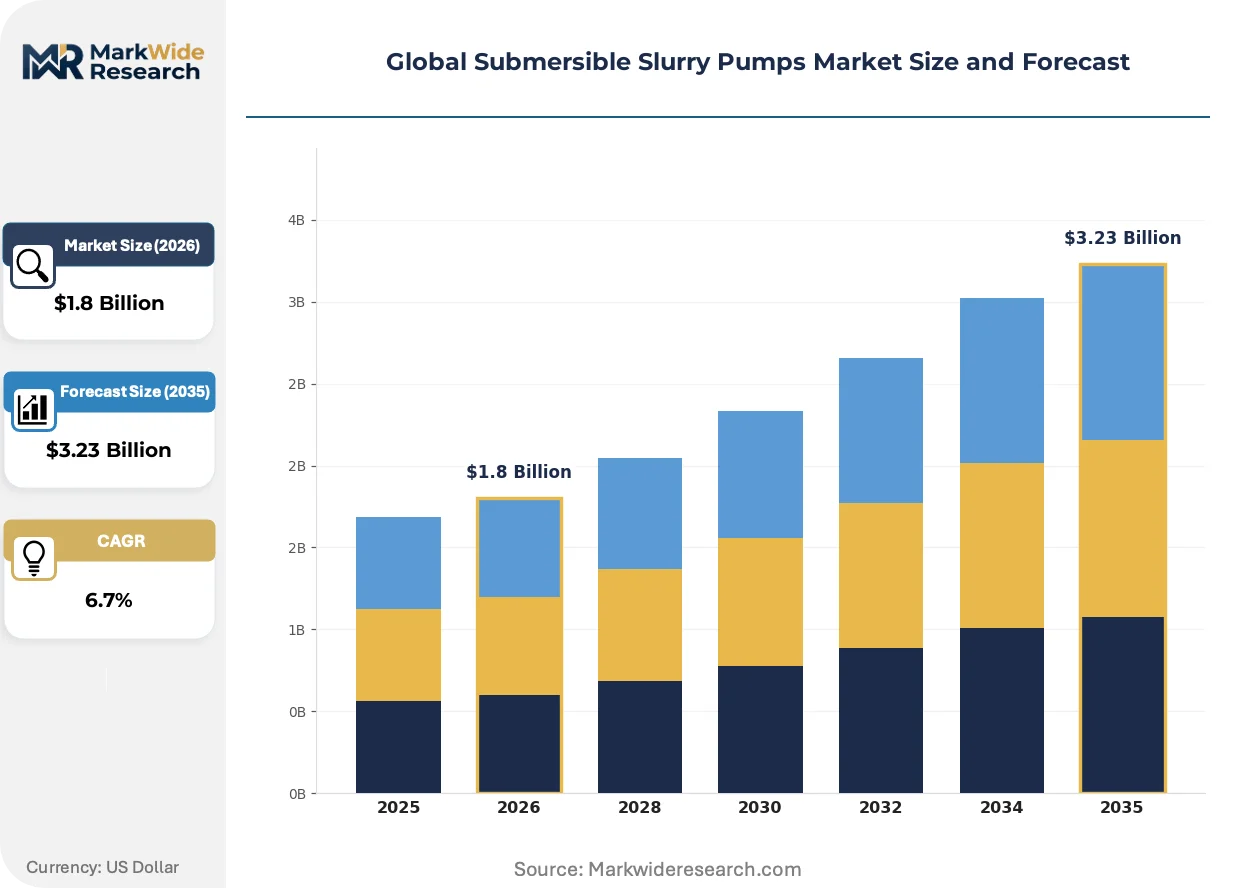
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Pumps, Horizontal Pumps, Diaphragm Pumps, Electric Pumps End User: Mining, Construction, Wastewater Treatment, Chemical Processing Material: Cast Iron, Stainless Steel, Polypropylene, Others Installation: Permanent Installation, Portable Installation, Submersible Installation, Custom Installation |
| Companies Covered | The Weir Group, KSB Group, Metso Outotec, Xylem Inc., Sulzer, DAE Pumps, ITT Goulds Pumps, Taian Ocean Pump Co., Ltd., Shijiazhuang Industrial Pump Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Submersible Slurry Pumps Market Strategic Shifts
Wet-end component design, regulatory material compliance, and service model restructuring are converging to redefine competitive differentiation in submersible slurry pump supply.
Ceramic-matrix composite impeller technology is modularizing across hard-rock mining applications in Western Australia and the Canadian Shield. Operators at BHP and Rio Tinto legacy sites are specifying these components for 40,000-hour service intervals in tailings recirculation duty. The shift is compressing traditional metal impeller replacement revenue while opening aftermarket attachment opportunities for bonded ceramic repair services.
REACH authorization procedures for persistent organic pollutants in seal compounds are restructuring European pump specification protocols. ECHA's 2023-2025 substance evaluation roadmap is disqualifying conventional nitrile elastomers from municipal wastewater tenders in Denmark and the Netherlands. German OEMs are accelerating fluoropolymer seal qualification programs to defend market position in chemical processing and biogas feedstock handling.
After-sales service unbundling is fragmenting traditional full-service contracts across North American mining contractors. Komatsu and Caterpillar equipment lessors are sourcing slurry pump maintenance separately from original supply agreements, driving independent service providers to build regional rapid-response fleets. The pattern is most visible in Arizona copper operations and Alberta oil sands tailings ponds where contractor equipment mobility prioritizes on-site repair capability over OEM warranty coverage.
Global Submersible Slurry Pumps Market Segmentation
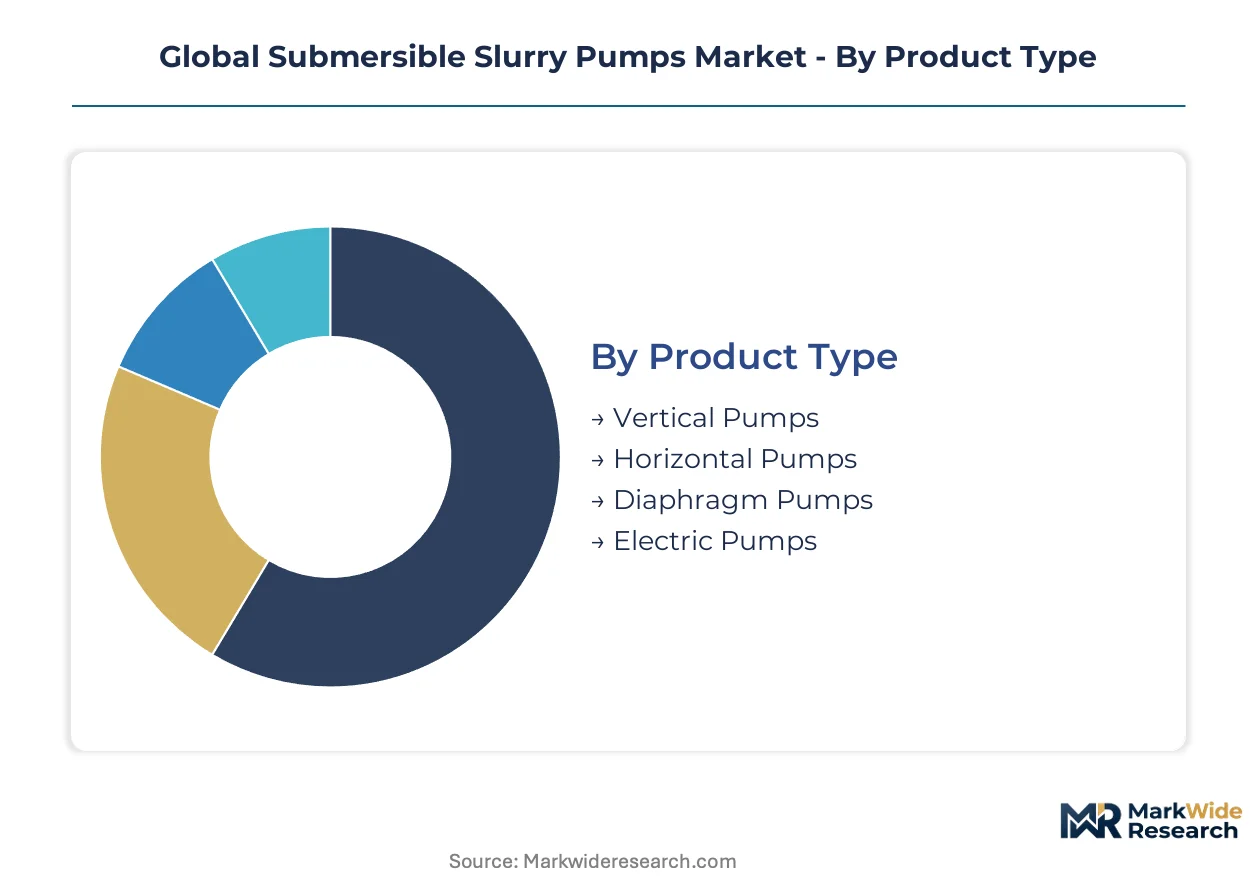
Submersible slurry pump procurement splits across four axes that determine hydraulic specification, duty cycle rating, and lifecycle cost. Each segmentation layer carries distinct margin profiles and replacement cadences that shape vendor portfolio strategy.
Product Type:
Configuration geometry determines immersion depth tolerance, solids passage capability, and motor cooling efficiency in abrasive environments.
- Vertical Pumps:Shaft-extended designs with column assemblies permit motor placement above fluid level while maintaining submerged suction. Australian hard-rock tailings operations specify these for thickened slurry transfer where floor space constraints limit horizontal footprints.
- Electric Pumps:Squirrel-cage induction motors with sealed stator housings integrate directly with variable-frequency drives for automated flow control. China's MEE-mandated wastewater upgrades in industrial corridor cities specify these configurations for energy efficiency compliance.
- Horizontal Pumps:End-suction arrangements with bearing frames suit above-ground slurry transfer stations where maintenance access is prioritized over immersion depth.
- Diaphragm Pumps:Positive displacement mechanisms with elastomeric membranes handle shear-sensitive chemical slurries and high-viscosity mine drainage where centrifugal designs cavitate.
Mature deployment sits with vertical configurations in established mining jurisdictions. Newer deployment is concentrated in electric pumps as industrial automation penetrates wastewater and chemical processing sectors.
End User:
Application severity varies from intermittent construction dewatering to continuous 24-hour mineral processing duty, driving specification divergence in abrasion resistance and seal redundancy.
- Mining:Hard-rock copper, iron ore, and nickel laterite operations demand hardened impellers and volutes rated for 50,000-hour service intervals in tailings recirculation circuits. Indonesia's Sulawesi nickel processing expansion is specifying acid-resistant configurations for pressure oxidation leaching.
- Wastewater Treatment:Municipal and industrial facilities require pumps with non-clog impeller geometries and dry-running protection for raw sewage and grit handling. Denmark and Netherlands tenders under ECHA REACH protocols are disqualifying conventional nitrile seals, accelerating fluoropolymer transitions.
- Construction:Foundation dewatering and tunnel boring applications favor portable electric submersibles with quick-discharge connections for contractor fleet mobility across multiple job sites.
- Chemical Processing:Acidic and alkaline slurry handling in fertilizer and battery chemical plants specifies stainless steel or polypropylene wet-ends with PTFE mechanical seals.
Volume concentration tracks mining replacement cycles in Australia and Canada. Steepest expansion trajectory is visible in wastewater treatment as China's dual carbon goals channel state investment toward energy-efficient pumping infrastructure.
Material:
Wet-end material selection determines corrosion allowance, abrasion resistance, and replacement economics across pH extremes from acidic mine drainage to caustic chemical processing.
- Cast Iron:Gray and ductile iron housings with hardened chrome-iron impellers dominate standard mining duty where moderate abrasion meets neutral pH. Foundry concentration in China and South Korea creates supply vulnerability for European OEMs.
- Stainless Steel:Austenitic and duplex grades command specification in chemical processing and biogas feedstock handling where chloride-induced pitting determines replacement cycles. London Metal Exchange nickel price volatility compresses margins on these configurations.
- Polypropylene:Thermoplastic housings and impellers suit low-temperature chemical duty with superior corrosion resistance to acids at fraction of alloy cost.
- Others:Ceramic-matrix composites and rubber-lined configurations serve specialized high-abrasion or low-impact applications.
Standard mining procurement clusters around cast iron for first-cost sensitivity. Premium specification is migrating toward stainless steel as REACH compliance and carbon border adjustments reshape European sourcing criteria.
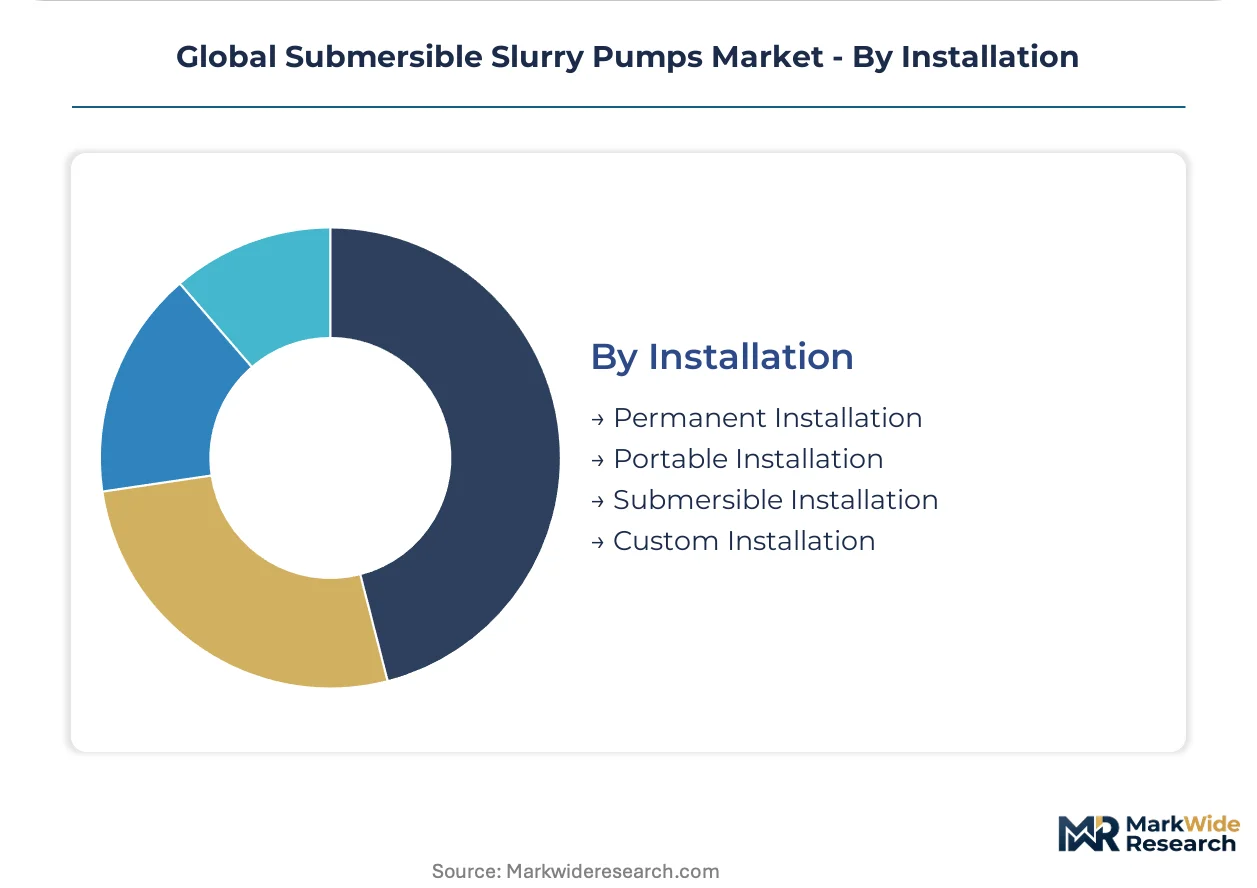
Installation:
Mounting architecture determines mobility, capital commitment, and integration depth with fixed infrastructure versus contractor fleet operations.
- Portable Installation:Skid-mounted or rail-hung units with quick-coupling discharge enable relocation across Arizona copper pits and Alberta oil sands tailings ponds. Independent service providers are building rapid-response fleets to serve contractor equipment lessors unbundling maintenance from supply agreements.
- Permanent Installation:Concrete-founded wet-pit arrangements with fixed piping and dedicated electrical feeds serve municipal wastewater headworks and mineral processing concentrators with 20-year asset horizons.
- Submersible Installation:Fully immersed motor-pump assemblies with cable penetration seals eliminate suction lift limitations and reduce noise footprint in urban wastewater facilities.
- Custom Installation:Engineered solutions for deep mine dewatering or offshore platform applications with pressure-balanced seal chambers and remote monitoring integration.
Fixed infrastructure commitment dominates municipal and large-scale mining capital projects. Gaining share fastest are portable configurations as contractor equipment mobility prioritizes on-site repair capability over OEM warranty coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial corridor sustains the densest concentration of submersible slurry pump procurement, anchored by state-backed wastewater infrastructure clusters in Shanghai and Jiangsu province.
China
Dual carbon goals channel MEE-mandated water pollution prevention standards into industrial corridor cities. The national carbon neutrality timeline accelerates energy-efficient pumping system upgrades across Jiangsu and Zhejiang provinces. State-backed investment concentrates in Shanghai's municipal wastewater treatment expansion and nickel refining circuits in Fujian.
United States
EPA effluent limitation guidelines compress replacement cycles for legacy mining pump systems. Tightened suspended solids thresholds in Arizona copper operations and Appalachian coal regions force specification upgrades. Independent service providers build rapid-response fleets across the Southwest to serve contractor equipment lessors unbundling maintenance contracts.
Australia
Hard-rock tailings management intensity drives thickened slurry transport deployments in Western Australia. Catastrophic failure liabilities and rehabilitation bonding requirements expand pump specifications at BHP and Rio Tinto legacy sites. Procurement concentrates in the Pilbara iron ore belt and Queensland coal basins for 24-hour recirculation duty.
Germany
EU Green Deal procurement criteria embed lifecycle carbon footprint scoring in mining tenders. REACH authorization procedures for seal compounds disqualify conventional nitrile elastomers from municipal wastewater tenders. Industrial demand clusters in the Ruhr wastewater treatment network and Saxony chemical processing corridors.
Indonesia
Battery-grade nickel refining projects in Sulawesi and Halmahera generate greenfield demand for acid-resistant pumping systems. Laterite leaching circuits specify corrosion-resistant configurations for pressure oxidation duty. State-backed mineral processing zones in Morowali anchor procurement concentration for downstream hydrometallurgical operations.
Global Submersible Slurry Pumps Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specification and service bundling dimensions. The vendor base stratifies between full-system integrators with captive alloy foundries and component specialists sourcing housings from East Asian foundries. Three archetypes dominate: vertically integrated mining equipment bundlers, hydraulics-focused engineering houses with proprietary R&D centers, and regional fabricators competing on first-cost sensitivity. Consolidation pressure manifests through strategic partnerships for ceramic-matrix composite technology and geographic expansion into Indonesian nickel processing zones.
Among European engineering houses, KSB Group and Sulzer occupy positions defined by proprietary hydraulics capabilities and regional service density. The Weir Group and Metso Outotec exemplify the bundling archetype, anchoring premium positioning through downstream mineral processing equipment integration. Chinese fabricators including Taian Ocean Pump Co., Ltd. and Shijiazhuang Industrial Pump Co., Ltd. represent the scale-driven tier, competing on cast iron configurations for standard mining duty.
| Leading Market Players |
|---|
| The Weir Group |
| KSB Group |
| Metso Outotec |
| Xylem Inc. |
| Sulzer |
| DAE Pumps |
| ITT Goulds Pumps |
| Taian Ocean Pump Co., Ltd. |
| Shijiazhuang Industrial Pump Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange nickel pricing volatility cascades through stainless steel alloy costs into three-tier pricing structure across premium, standard, and economy levels for submersible slurry pump configurations. Foundry concentration in China and South Korea compresses margin buffers on corrosion-resistant specifications while elevating procurement risk premiums for European and North American OEMs sourcing cast iron housings.
Pricing Analysis
Throughput-based pricing anchors premium tiers where vendors guarantee uptime metrics for tailings recirculation duty at BHP and Rio Tinto sites. Certification grade under EU Green Deal lifecycle carbon scoring separates premium energy-efficient designs from standard cast iron configurations, with economy tiers competing on first-cost sensitivity for contractor fleet procurement. Cost compression in stainless steel configurations is intensifying because London Metal Exchange nickel price swings directly transfer into bill-of-materials volatility. Mining operators exhibit lowest price sensitivity for hardened impeller replacements in 24-hour duty cycles, while municipal wastewater tenders in Denmark and the Netherlands show highest sensitivity to fluoropolymer seal premiums driven by REACH compliance transitions.
Supply Chain Analysis
Remanufacturing flows for ceramic-matrix composite impellers are establishing regional refurbishment hubs in Western Australia to compress 40,000-hour service interval logistics. Wet-end component production concentrates in China, South Korea, and Germany, with specialty alloy foundry capacity drawing from chromium and nickel feedstock tied to London Metal Exchange benchmarks. Single-source vulnerability in East Asian foundry clusters creates geographic concentration risk for European OEMs dependent on cast iron and duplex stainless steel housings. Distribution runs through OEM-direct channels for large mining capital projects, while independent service providers build rapid-response fleets to serve unbundled maintenance contracts across Arizona copper operations and Alberta oil sands tailings ponds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty alloy foundry capacity constraints in Europe and North America prop pricing premiums for corrosion-resistant pump configurations, sustaining margin pools for incumbent OEMs with captive upstream supply.
For Market Incumbents: Hedge against REACH elastomer transition delays by accelerating fluoropolymer seal qualification programs in German R&D centers. Backward integration into wear-resistant alloy foundry capacity in Germany or Finland defends margin position against Chinese fabricator price competition in standard mining duty. Channel control through predictive maintenance service contracts transforms pump vendors into service partners, locking out independent rapid-response fleets. For New Entrants and Emerging Players: The mid-tier price-point gap between Weir Group premium bundling and Chinese cast iron economy offerings creates entry space for specialized ceramic-matrix composite repair services. Indonesia's Sulawesi nickel processing expansion represents the most penetrable geography for acid-resistant configuration specialists without incumbent entrenched relationships. Go-to-market through EPC contractors on battery-grade nickel refining projects bypasses OEM-direct procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydraulics-focused engineering houses with proprietary CFD capabilities in Germany or China during foundry input cost spikes. Long-term viability over the next decade hinges on digital twin convergence and IoT condition monitoring integration that transforms hardware margins into recurring service revenue. Watch London Metal Exchange nickel price sustained elevation above historical bands as signal for stainless steel configuration margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Foundry Capacity | Captive supply of duplex stainless steel housings insulates KSB Group and Sulzer from London Metal Exchange nickel volatility. |
| Fluoropolymer Seal Qualification Acceleration | REACH-compliant seal transitions defend German OEM market position in Denmark and Netherlands municipal wastewater tenders. |
| Ceramic-Matrix Composite Repair Service Network | Bonded ceramic refurbishment hubs in Western Australia capture aftermarket attachment from 40,000-hour service interval specifications. |
| Predictive Maintenance Platform Integration | IoT condition monitoring convergence enables Weir Group and Metso Outotec to unbundle competitors from traditional full-service contracts. |
| Indonesian Nickel Processing Zone Expansion | Greenfield acid-resistant pump specifications in Sulawesi and Halmahera bypass entrenched Australian mining procurement relationships. |
Study Parameters
Multi-period observation of EPA effluent limitation guideline implementation, MEE water pollution prevention standard enforcement, and EU Green Deal procurement criteria adoption anchored the trend analysis, supplemented by interviews with maintenance directors at hard-rock mining operations, plant engineers in China's Yangtze River Delta industrial corridor, aftermarket service heads at independent rapid-response fleet operators, and procurement teams at Indonesian nickel processing EPC contractors. Secondary validation drew from EPA discharge monitoring reports, ECHA substance evaluation roadmaps, London Metal Exchange pricing data, and SEC filings of listed pump OEMs. Bottom-up unit demand modeling across mining, wastewater, construction, and chemical processing end-uses triangulated against top-down market sizing from foundry capacity and trade flow analysis.
Input-output matrix framing connected raw material alloy costs to finished pump pricing tiers across the projection horizon, with segmentation dimensions spanning product type configuration geometry, end-user application severity, wet-end material specification, and installation mobility architecture. CAGRs derived from fitted growth curves applied to base-year installed base estimates and replacement cycle compression factors. Industry-specific forecast inputs incorporated rehabilitation bonding requirement changes in Western Australia and state-backed infrastructure investment flows under China's dual carbon goals.
Inputs from EPA, ECHA, and MEE regulatory filings were available through the study window; gaps in real-time contractor fleet procurement data introduce uncertainty bands around portable installation growth trajectories. Forecasts reflect assumptions on REACH authorization timeline adherence and London Metal Exchange price regime stability. Practitioners should monitor ECHA 2023-2025 substance evaluation roadmap acceleration and Indonesian nickel processing project commissioning schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Asia-Pacific Forklift Rental Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Global Air Cannon System Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market