
 Gan on Silicon Technology Market | 2026-2036
Gan on Silicon Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Gan on Silicon Technology Market Analysis
Buyer concentration in consumer electronics is rebalancing as smartphone OEMs consolidate adapter sourcing while automotive Tier 1s fragment procurement across multiple GaN suppliers. Infineon Technologies AG leverages its vertically integrated Si and GaN substrate operations to control cost curves in power devices. Navitas Semiconductor specializes in monolithic GaN ICs that reduce external component counts for fast-charging applications. Qorvo, Inc. dominates RF GaN-on-Si portfolios for 5G infrastructure deployments.
GaN on Silicon technology deposits gallium nitride epitaxial layers onto standard silicon wafers, enabling 650V-class power switching with electron mobility exceeding 1500 cm²/V·s and critical electric fields near 3.3 MV/cm. This platform serves power conversion, RF amplification, and optoelectronic emission where silicon reaches physical limits. Power Devices anchors current revenue as server PSU and EV onboard charger designs displace silicon MOSFETs. RF Devices represents the fastest-growing category as 5G massive MIMO arrays and radar modules adopt GaN-on-Si for thermal and efficiency advantages. Optoelectronic Devices occupies a mature niche in micro-LED backplane development.
The U.S. Department of Energy enforces minimum efficiency standards that disqualify legacy silicon adapters above 65W, directly expanding GaN-on-Si addressable demand. The European Union's Ecodesign Directive and CE marking requirements mandate standby power below 0.5W, favoring GaN topologies that reduce switching losses. China's GB standards for EV charging infrastructure specify efficiency tiers that domestic GaN suppliers target with localized production. Stakeholders must monitor foundry utilization for 8-inch GaN-on-Si wafers against silicon carbide price erosion as the decisive competitive variable.
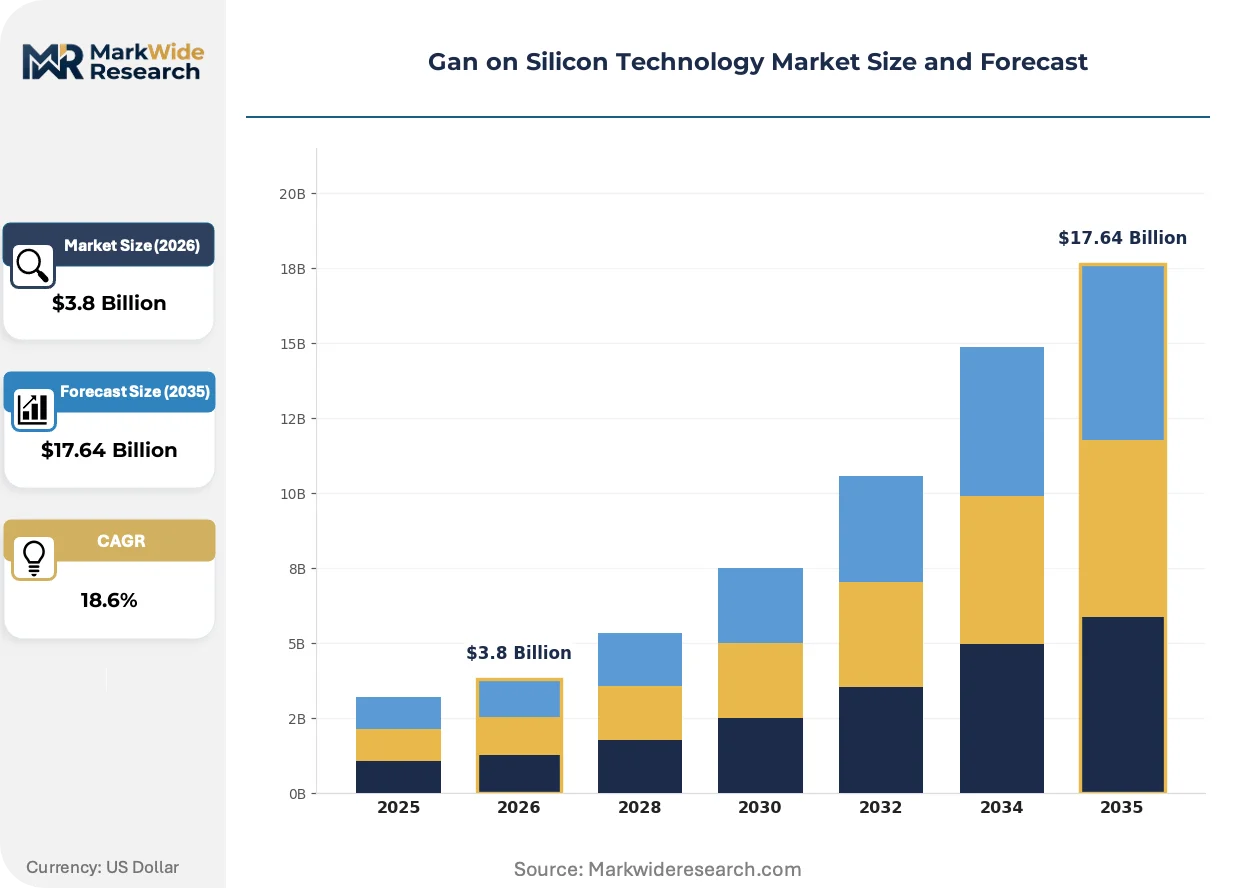
Market Dynamics
Automotive electrification is compressing design cycles for power electronics, forcing foundries to prioritize 8-inch GaN-on-Si wafer capacity over legacy silicon processes. This structural pivot creates simultaneous pull from EV drivetrains and fast-charging infrastructure while straining epitaxial growth equipment availability.
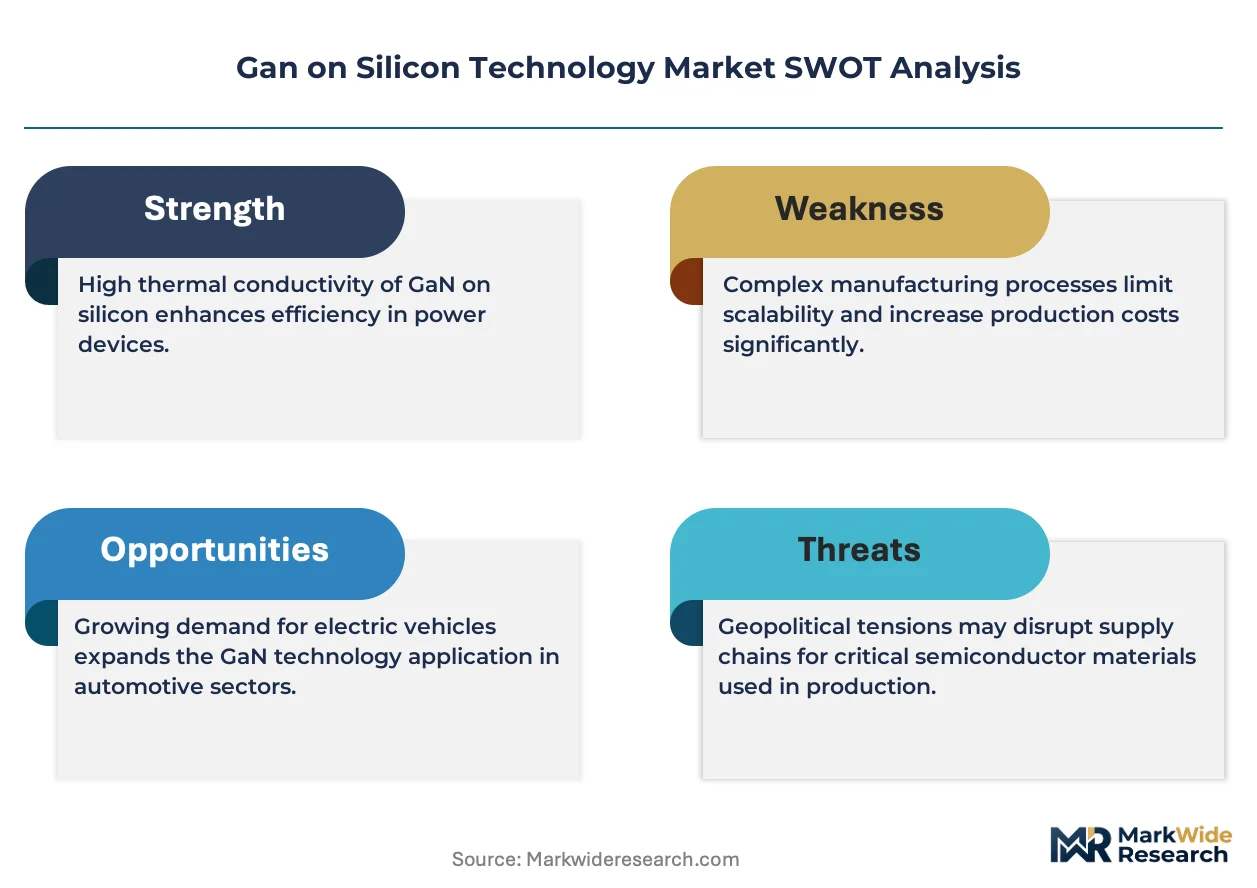
Growth Catalysts
- EU Ecodesign Directive:Standby power mandates below 0.5W disqualify silicon adapters above 65W, expanding GaN-on-Si penetration in consumer power supplies.
- EV onboard charger redesign:Automotive Tier 1s are replacing silicon IGBTs with GaN switches to reduce thermal management mass and improve charging efficiency.
- China's captive capacity buildout:Domestic foundries and IDMs are constructing localized GaN-on-Si fabrication lines to serve GB-standard EV charging infrastructure.
Market Restraints
- Epitaxial equipment bottlenecks:Metal-organic chemical vapor deposition reactors face 18-24 month lead times, constraining wafer output expansion.
- Silicon carbide price erosion:6-inch SiC substrate costs are falling faster than projected, creating substitution pressure in 650V-1200V applications.
- Defect density limitations:Threading dislocation rates in GaN-on-Si epilayers remain 2-3 orders of magnitude higher than native GaN substrates, limiting RF performance.
Strategic Opportunities
- Micro-LED backplane integration:GaN-on-Si wafers enable monolithic driver integration for next-generation display architectures in augmented reality headsets.
- India's PLI scheme for semiconductors:Domestic assembly and test incentives could attract GaN packaging investments serving South Asian consumer electronics demand.
- 5G massive MIMO deployment:RF GaN-on-Si power amplifiers offer thermal advantages over LDMOS in base station installations across mid-band spectrum allocations.
Industry Challenges
- Power electronics talent scarcity:Compound semiconductor device physics expertise concentrates among a limited pool of engineers with GaN and SiC design experience.
- Qualification timeline compression:Automotive AEC-Q101 certification cycles conflict with EV platform launch schedules, forcing parallel validation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan on Silicon Technology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Devices, RF Devices, Optoelectronic Devices, Integrated Circuits End User: Consumer Electronics, Automotive Industry, Telecommunications, Industrial Applications Application: Power Management, Wireless Charging, High-Frequency Applications, LED Lighting Technology: Monolithic Integration, Hybrid Integration, InGaN Technology, Heterojunction Devices |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors N.V, Toshiba Corporation, Renesas Electronics Corporation, Texas Instruments Incorporated, Navitas Semiconductor, Qorvo, Inc., ROHM Co., Ltd., Panasonic Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan on Silicon Technology Market Emerging Trajectories
Monolithic integration of drive and protection circuits onto GaN-on-Si die is collapsing external component counts while enabling higher switching frequencies. This architectural shift is redefining competitive advantage around IC design capability rather than discrete device performance.
Monolithic GaN ICs embedding gate drivers and protection logic are overtaking discrete GaN FET-plus-driver configurations in sub-100W adapters. Smartphone OEMs and laptop manufacturers are adopting these integrated solutions to reduce PCB area by 40-60% while simplifying EMI compliance. The structural consequence is margin compression for discrete component suppliers as system-level value migrates to fabless GaN IC designers.
REACH restrictions on per- and polyfluoroalkyl substances are forcing solder mask and conformal coating reformulations for GaN power modules. European EMS providers are qualifying alternative chemistries that maintain thermal cycling reliability without fluorinated compounds. Consumer power supply assemblers serving EU markets face 12-18 month material requalification cycles.
Adapter sourcing consolidation among top-five smartphone OEMs is concentrating procurement leverage and squeezing second-tier GaN suppliers. Direct foundry relationships are replacing distributor channels for high-volume programs, with OEMs negotiating wafer-level pricing and capacity reservations. This pattern is most pronounced in China, where domestic brands command 70% of global fast-charger shipments.
Gan on Silicon Technology Market Segmentation
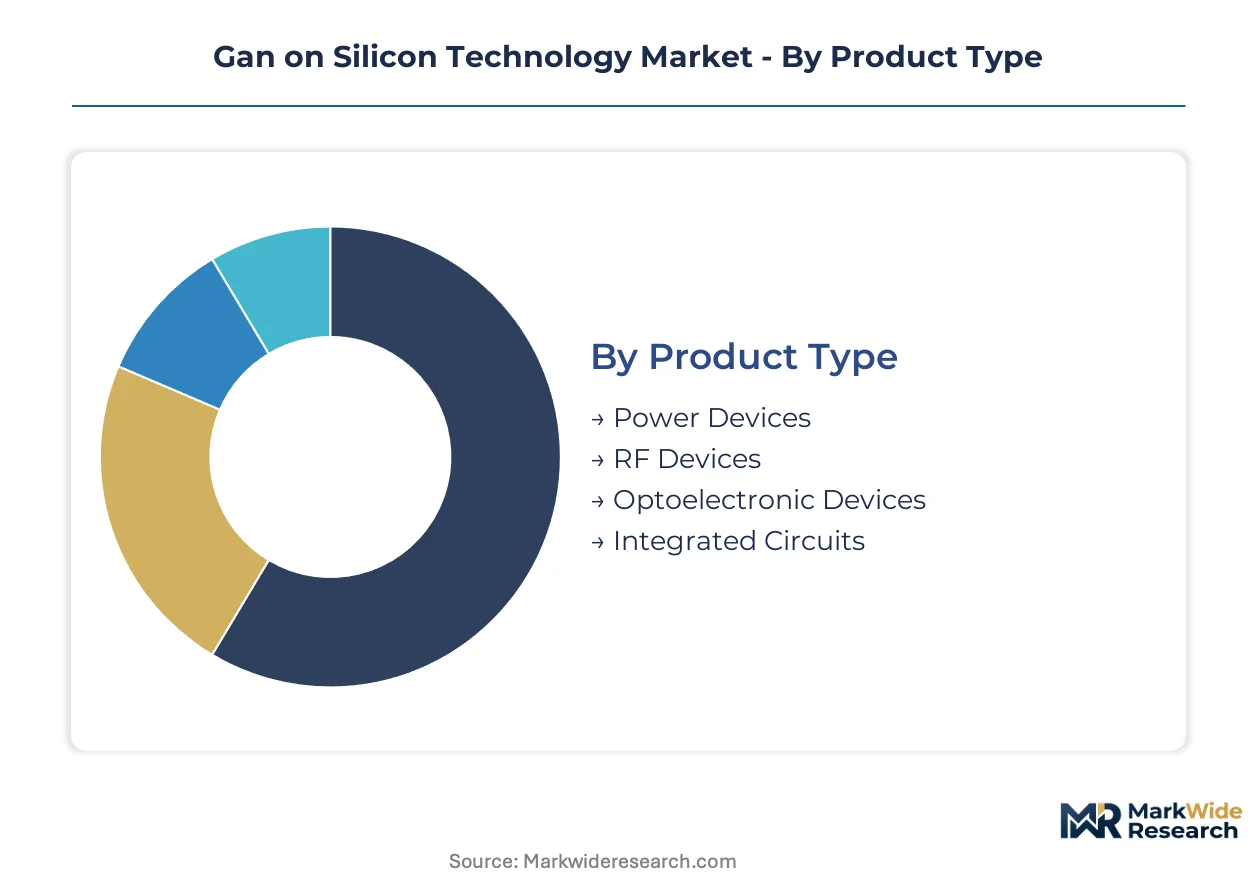
GaN-on-Si technology spans discrete power switches, RF amplifiers, and monolithic ICs with divergent performance requirements and customer qualification timelines. Segmentation reveals how technical specifications map to end-use economics, from consumer fast-charging cost sensitivity to automotive reliability mandates.
Product Type:
Standardization dominates at the wafer level while customization intensifies at the package and circuit level across this category.
- Power Devices:Discrete GaN FETs and diodes targeting 650V switching applications with electron mobility exceeding 1500 cm²/V·s. Demand concentrates in China's domestic fast-charger supply chain where local foundries serve OEM adapter programs under GB efficiency standards.
- RF Devices:High-electron-mobility transistors and power amplifiers for 5G massive MIMO and radar modules operating in sub-6GHz spectrum. European base station deployments under EU Green Deal efficiency mandates are pulling thermal-optimized GaN-on-Si alternatives to LDMOS.
- Optoelectronic Devices:Micro-LED backplanes and UV emitters leveraging GaN bandgap properties for display and sterilization applications.
- Integrated Circuits:Monolithic GaN ICs embedding gate drivers and protection logic for sub-100W adapter designs.
Leading the category by volume: Power Devices. Expanding most quickly: RF Devices.
End User:
Volume concentration shifts from consumer electronics toward automotive as electrification accelerates procurement cycles.
- Consumer Electronics:Smartphone and laptop adapter manufacturers specifying GaN solutions for 65W-140W fast-charging bricks. China's top-five OEMs now command 70% of global charger shipments, consolidating procurement leverage over foundry capacity.
- Automotive Industry:Tier 1 suppliers integrating GaN switches into onboard chargers and DC-DC converters for EV platforms. U.S. Department of Energy efficiency standards and EU Ecodesign Directive mandates are disqualifying silicon IGBTs above 3.3kW power levels.
- Telecommunications:5G infrastructure OEMs specifying RF GaN-on-Si for macro and small cell deployments.
- Industrial Applications:Server PSU and motor drive manufacturers adopting GaN for datacenter efficiency gains.
Dominant volume share: Consumer Electronics. Steepest expansion trajectory: Automotive Industry.
Application:
Frequency requirements separate cost-optimized from performance-premium segments across this category.
- Power Management:AC-DC and DC-DC conversion circuits spanning adapter, server PSU, and EV charger designs. China's GB standards for EV charging infrastructure specify efficiency tiers that domestic GaN suppliers target with localized 8-inch wafer production.
- Wireless Charging:Resonant converter topologies for smartphone and automotive pad systems requiring high-frequency switching.
- High-Frequency Applications:5G massive MIMO and radar modules where GaN-on-Si thermal advantages over LDMOS justify premium positioning.
- LED Lighting:Driver circuits and micro-LED backplanes for display and general illumination products.
Highest volume concentration: Power Management. Gaining share fastest: High-Frequency Applications.
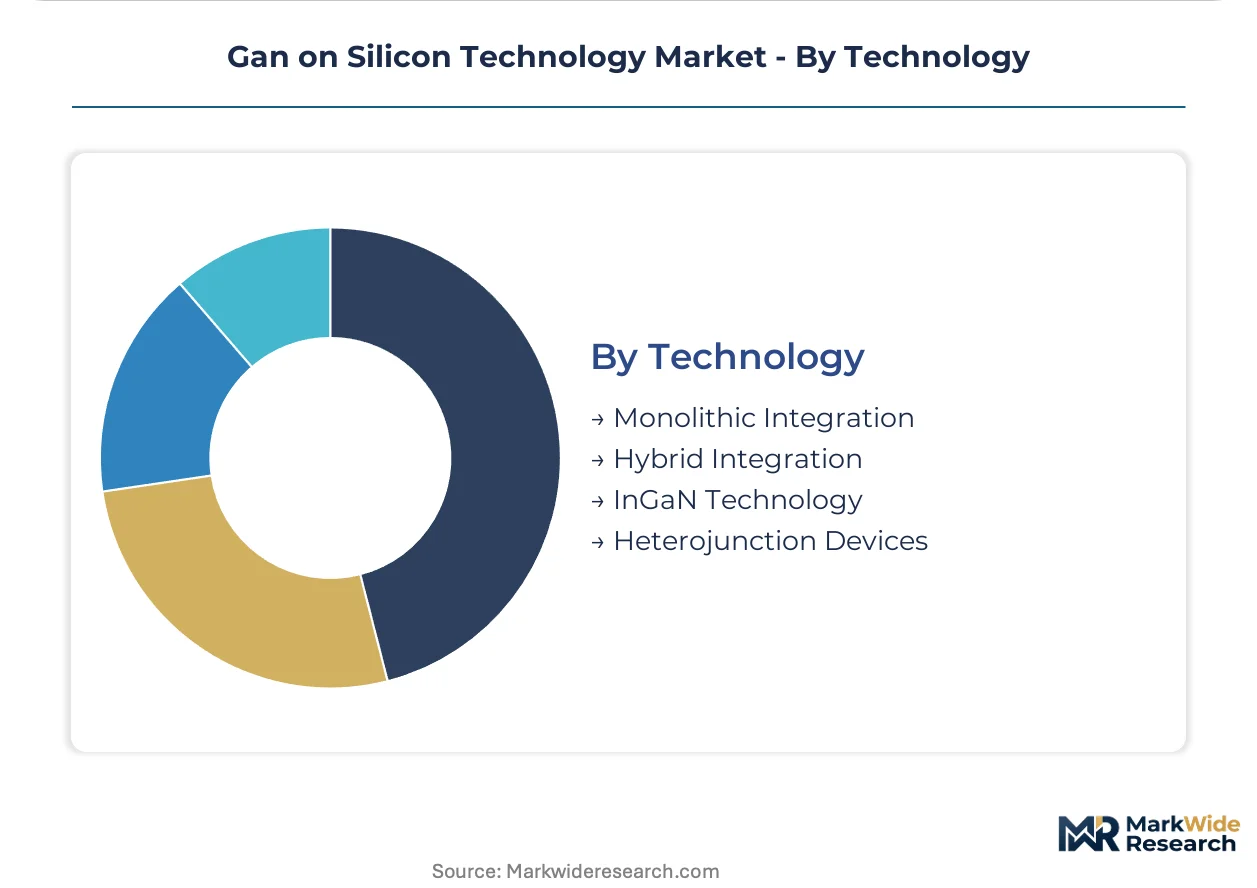
Technology:
Integration depth determines competitive moat as monolithic architectures displace discrete-plus-driver configurations.
- Monolithic Integration:Single-die GaN ICs embedding gate drivers, level shifters, and protection circuits. Navitas Semiconductor and Infineon are shipping these solutions to smartphone OEMs seeking 40-60% PCB area reduction in sub-100W adapters.
- Hybrid Integration:Co-packaged GaN FETs with silicon driver ICs bridging cost and performance for mid-power industrial applications.
- InGaN Technology:Indium gallium nitride heterostructures for optoelectronic emission and specialized RF devices.
- Heterojunction Devices:Advanced epitaxial structures targeting RF and power performance beyond standard GaN-on-Si limits.
Widest commercial deployment: Monolithic Integration. Climbing the fastest: Hybrid Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement leverage for GaN-on-Si power devices through domestic foundry capacity serving consumer fast-charging and EV inverter demand. The U.S. Department of Energy and EU Ecodesign Directive are accelerating adapter redesigns in North America and Europe. Industrial clusters in Germany, Japan, and South Korea anchor RF device development for 5G infrastructure.
China
Domestic OEMs command 70% of global fast-charger shipments, consolidating adapter procurement leverage over 8-inch GaN-on-Si foundry capacity. MIIT and GB standards for EV charging infrastructure specify efficiency tiers that local IDMs target with captive fabrication lines. The Yangtze River Delta anchors epitaxial growth equipment deployment for automotive onboard charger programs.
United States
Datacenter operators and server PSU manufacturers specify GaN switches under DOE efficiency mandates disqualifying legacy silicon above 65W. The U.S. Department of Energy enforces minimum standards that expand GaN-on-Si addressable demand in power conversion applications. Texas and California clusters concentrate fabless GaN IC design houses serving consumer electronics OEMs.
Germany
Automotive Tier 1 suppliers integrate GaN devices into EV drivetrains under EU Ecodesign Directive standby power mandates below 0.5W. The KBA and EU Green Deal efficiency frameworks disqualify silicon IGBTs in onboard chargers above 3.3kW. Bavaria and Baden-Württemberg host power electronics engineering centers qualifying GaN modules for AEC-Q101 certification.
Japan
Base station OEMs specify RF GaN-on-Si for 5G massive MIMO deployments under METI spectrum allocation policies. METI efficiency mandates favor thermal-optimized GaN alternatives to LDMOS in sub-6GHz infrastructure. The Kanto region around Tokyo concentrates epitaxial wafer production for radar module and telecommunications applications.
South Korea
Consumer electronics conglomerates drive monolithic GaN IC adoption for smartphone adapter programs targeting PCB area reduction. The MFDS and national efficiency standards align with EU Ecodesign benchmarks for standby power in consumer power supplies. The Seoul Capital Area anchors foundry partnerships between domestic IDMs and global GaN technology licensors.
Gan on Silicon Technology Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue monolithic integration and RF specialization. The vendor base spans vertically integrated IDMs with captive silicon substrate operations and fabless designers outsourcing to dedicated GaN foundries. Three archetypes dominate: integrated semiconductor conglomerates controlling epitaxial supply chains, pure-play GaN IC specialists collapsing external component counts, and RF-focused suppliers targeting 5G infrastructure thermal requirements. Competitive moves center on 8-inch wafer capacity reservations and strategic partnerships with automotive Tier 1 qualification programs.
Among integrated device manufacturers, Infineon Technologies AG and Toshiba Corporation exemplify the vertically integrated archetype with in-house silicon and GaN substrate operations. Navitas Semiconductor occupies a position within the fabless GaN IC specialist tier. Qorvo, Inc. anchors the RF-focused supplier segment. These three companies represent distinct competitive vectors: substrate control, monolithic integration, and thermal-optimized RF performance.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors N.V |
| Toshiba Corporation |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Navitas Semiconductor |
| Qorvo, Inc. |
| ROHM Co., Ltd. |
| Panasonic Holdings Corporation |
| Others |
Supply Flow & Price Mechanics
Discrete GaN FETs and monolithic ICs diverge sharply on cost-per-watt metrics, with the premium tier commanding three-to-five-fold multiples over economy-grade discrete switches while sourcing through entirely different channel structures. This bifurcation concentrates margin capture among vertically integrated IDMs controlling epitaxial supply, whereas fabless designers compete on integration density rather than die cost alone. Procurement leverage tilts toward China's domestic OEMs consolidating adapter programs under GB efficiency standards.
Pricing Analysis
High-volume consumer adapter programs trade margin for wafer-level capacity reservations, while automotive onboard charger designs sustain premium positioning through AEC-Q101 qualification requirements. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-fast-charging tiers reflects certification investment recovery and volume scale. Cost compression in sub-100W adapters intensifies as smartphone OEMs negotiate direct foundry pricing. China's top-five charger OEMs exhibit lowest price sensitivity; European automotive Tier 1s accept premium positioning for reliability assurance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's consolidated adapter manufacturers, while distributor networks serve fragmented industrial and automotive qualification programs. Epitaxial wafer supply concentrates in China, Japan, and Germany, with metal-organic chemical vapor deposition equipment anchoring capacity expansion timelines. Gallium precursor chemicals and 8-inch silicon substrates feed from specialized chemical suppliers and captive silicon operations. Single-source vulnerability in MOCVD reactor manufacturing constrains foundry output scaling. Distribution runs through regional EMS providers for consumer programs and direct Tier 1 partnerships for automotive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal-organic chemical vapor deposition equipment lead times stretching eighteen to twenty-four months prop pricing power for incumbent foundries with installed capacity. This structural bottleneck favors suppliers with reserved equipment slots and captive epitaxial operations.
For Market Incumbents: Anchor 8-inch wafer capacity through multi-year automotive qualification programs before silicon carbide price erosion accelerates in 650V-1200V segments. Deepen backward integration into gallium precursor supply to offset raw material volatility. Prioritize monolithic IC R&D to defend margin position against discrete component commoditization in consumer adapters.
For New Entrants and Emerging Players: The price-point gap between automotive-certified modules and consumer-grade discretes offers entry space for industrial-grade hybrid integration targeting server PSU and motor drive applications. India's PLI scheme for semiconductors presents the most penetrable geography for packaging and test investments. Pursue foundry partnerships rather than capital-intensive epitaxial capacity builds.
For Investors and Strategic Acquirers: Exit pathways concentrate in RF specialization and automotive qualification assets as compound semiconductor expertise scarcity intensifies acquisition premiums. Fabless GaN IC designers with smartphone OEM design wins represent the target archetype with highest strategic value. Monitor silicon carbide substrate cost curves for substitution inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| 8-Inch Wafer Capacity Expansion | Captures automotive onboard charger demand under EU Ecodesign Directive mandates. |
| Monolithic GaN IC Development | Reduces external component counts for smartphone OEMs seeking PCB area compression. |
| Automotive AEC-Q101 Qualification | Unlocks Tier 1 procurement channels for EV drivetrain power electronics. |
| Epitaxial Equipment Reservation | Secures MOCVD reactor slots amid eighteen-to-twenty-four month lead time constraints. |
| India PLI Scheme Participation | Accesses domestic assembly incentives for South Asian consumer electronics demand. |
Methodological Framework
SEC filings, customs trade databases, and hyperscaler power supply procurement disclosures formed the secondary backbone, supplemented by technical documentation from MIIT, the U.S. Department of Energy, and EU Ecodesign Directive regulatory filings. Primary interviews with GaN device engineering directors, automotive Tier 1 power electronics procurement managers, foundry operations executives, and smartphone OEM supply chain strategists validated demand assumptions. Bottom-up wafer shipment analysis and top-down end-use equipment penetration estimates were triangulated across primary and secondary sources.
Historical trendline analysis of epitaxial equipment shipments, foundry utilization rates, and end-use equipment bill-of-materials transitions informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture (discrete versus monolithic), end-use vertical (consumer electronics, automotive, telecommunications, industrial), application frequency requirements, and regional regulatory cluster. CAGRs were derived from equipment installation trajectories and substitution elasticity parameters. Forecast inputs incorporated silicon carbide substrate cost curves and automotive platform electrification timelines.
Inputs from MOCVD equipment manufacturers and foundry utilization reports were available through the study window; gaps in long-term automotive platform commitment data introduce uncertainty bands around EV onboard charger penetration assumptions. Practitioners should monitor silicon carbide 6-inch substrate pricing and automotive AEC-Q101 qualification cycle compression for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Global Trench Gate Power MOSFET Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
China Semiconductor Diode Market