
 Japan MCU Market | 2026-2036
Japan MCU Market Size, Share, and Industry Trends Forecast 2026-2036
Japan MCU Market Insights
Kyushu is fragmenting as a secondary MCU production corridor alongside the traditional Kanto belt. Renesas Electronics leverages its Naka and Kawashiri fabs to sustain captive wafer supply for automotive-grade controllers. Toshiba Electronic Devices & Storage Corporation anchors legacy industrial MCU demand through its Oita manufacturing complex. ROHM Semiconductor differentiates via silicon carbide-integrated MCU modules targeting power electronics.
A microcontroller unit integrates a processor core, volatile and non-volatile memory, and programmable peripherals on a single die, typically fabricated at 40nm to 90nm nodes for automotive reliability. Automotive Systems applications command the widest margin pools due to ASIL-D safety certification requirements and extended product lifecycles. Smart Homes represents the fastest-growing application segment as Japanese utilities mandate connected metering under grid modernization directives. 32-bit MCU products dominate value capture, while 8-bit variants retain volume relevance in cost-constrained consumer subsystems.
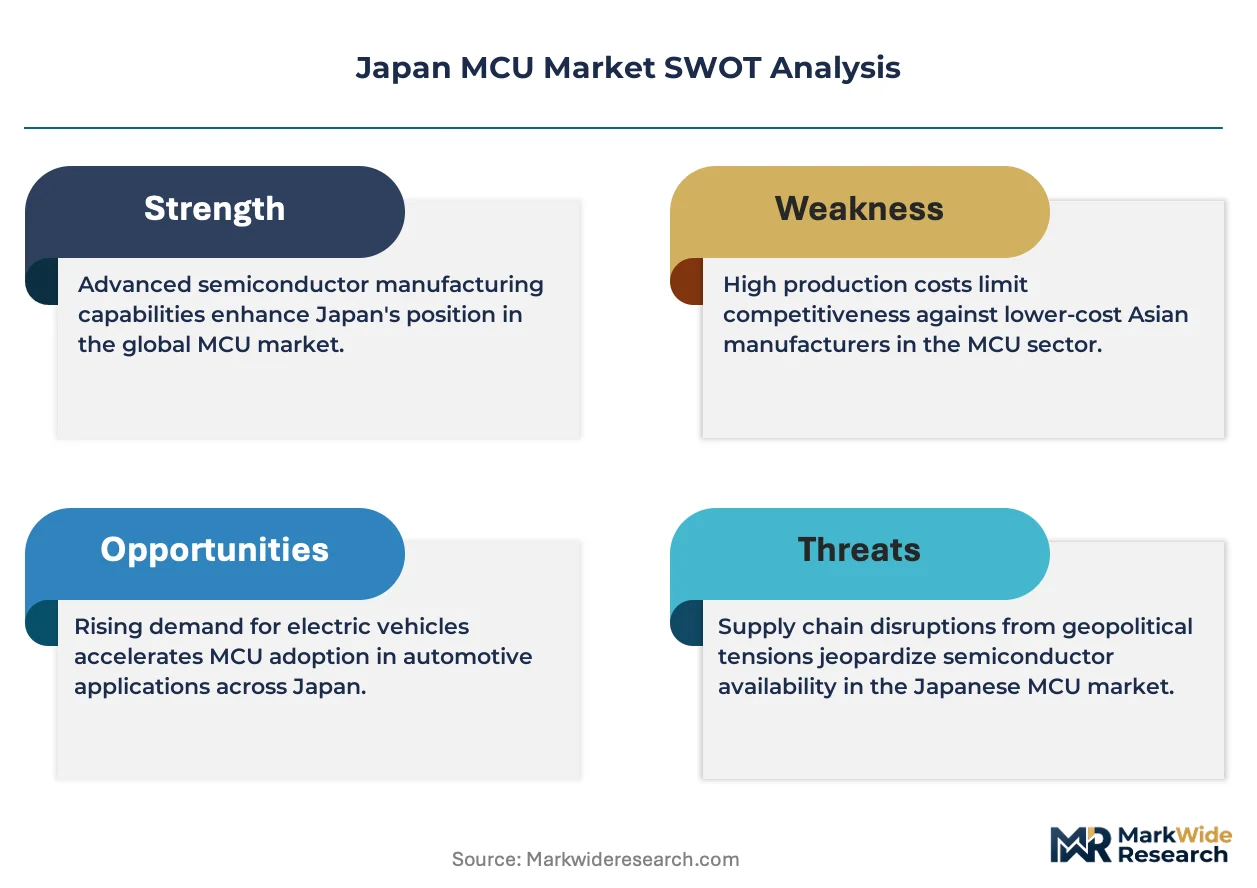
METI's semiconductor and digital industry strategy directs subsidy eligibility toward domestic MCU capacity, while JIS standards govern automotive component qualification. PMDA oversight extends to medical equipment controllers, creating dual certification burdens for Healthcare Devices suppliers. Stakeholders must monitor METI subsidy allocation timing and foundry utilization rates to calibrate inventory and partnership strategies.
Market Dynamics
Automotive electrification is compressing MCU qualification cycles while METI's domestic foundry subsidies restructure wafer supply geography across Japan's semiconductor belt.
Growth Catalysts
- EV Powertrain Electrification:Automotive OEMs are expanding embedded controller procurement for electric powertrains, requiring ASIL-D certified MCUs with extended thermal tolerance.
- Grid Modernization Mandates:Japanese utilities mandate connected metering infrastructure under national grid directives, accelerating 32-bit MCU deployment in smart home energy management systems.
- Kanto Industrial Cluster Density:Tokyo and Yokohama headquarters concentration creates localized demand pull for automotive and industrial equipment controllers.
Market Restraints
- Wafer Supply Concentration:Captive fab dependency at 40nm-90nm nodes creates vulnerability to earthquake disruption along Kyushu's Naka and Kawashiri production corridors.
- Dual Certification Burden:PMDA oversight of medical equipment controllers叠加 JIS automotive standards extends qualification timelines for Healthcare Devices suppliers.
- Silicon Carbide Module Cost:Power electronics integration with SiC substrates elevates bill-of-materials pressure versus legacy silicon-only architectures.
Strategic Opportunities
- Kyushu Secondary Corridor Development:Oita and Kumamoto prefectures offer underutilized cleanroom capacity for foundry partnerships serving industrial MCU demand.
- Silicon Carbide-Integrated Modules:Convergence of wide-bandgap semiconductors with motor control firmware opens premium positioning in power electronics applications.
- Smart Metering Channel Expansion:Direct utility procurement contracts bypass traditional distribution, enabling margin capture for qualified domestic suppliers.
Industry Challenges
- Automotive Safety Certification Timeline:ASIL-D functional safety validation requires 18-24 month qualification cycles that compress product refresh windows.
- Legacy Industrial System Integration:8-bit MCU replacement in cost-constrained consumer subsystems demands backward-compatible peripheral architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan MCU Market |
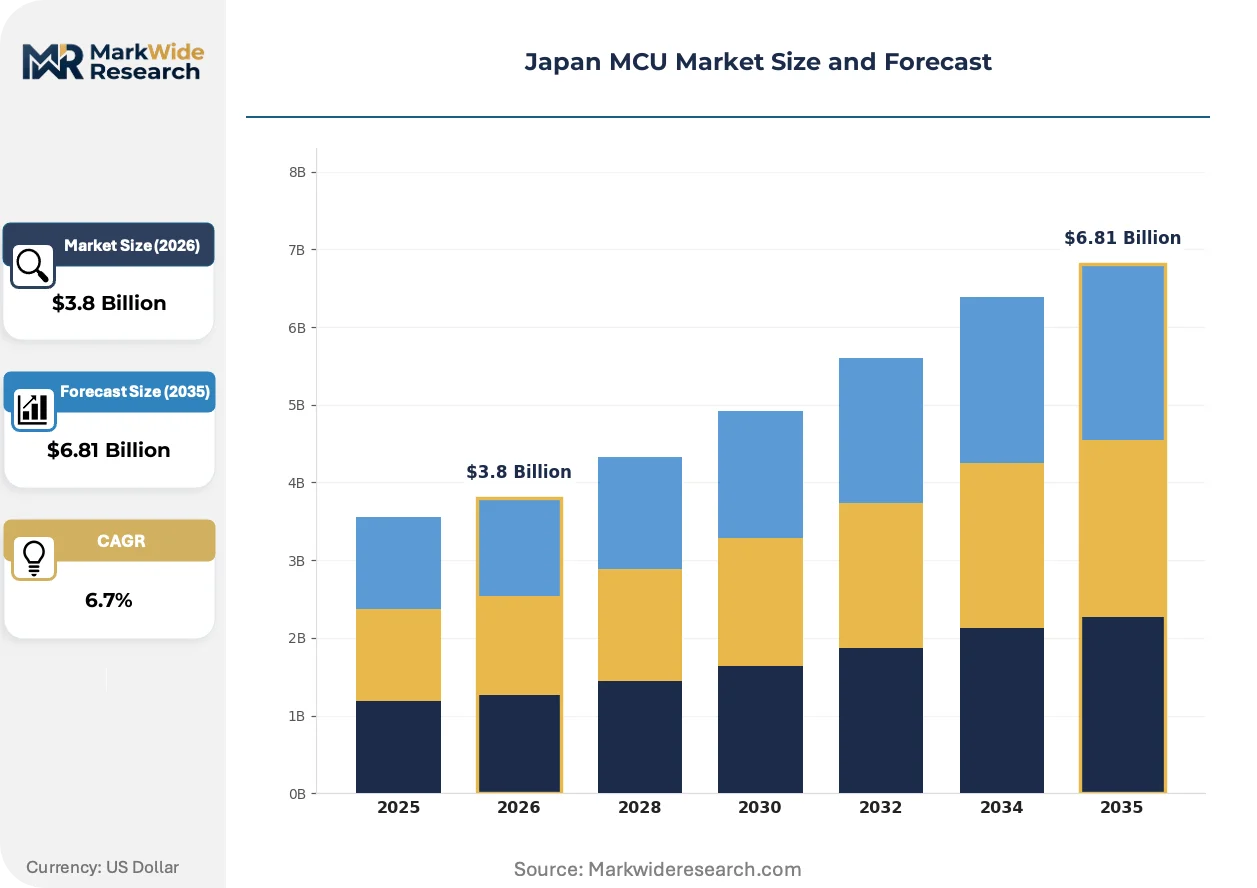
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 8-bit MCU, 16-bit MCU, 32-bit MCU, Digital Signal Controllers End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Devices Application: Smart Homes, Automotive Systems, Robotics, Medical Equipment Technology: UART, SPI, I2C, CAN |
| Companies Covered | Renesas Electronics, Toshiba Electronic Devices & Storage Corporation, Sony Semiconductor Solutions, Panasonic Corporation, Fujitsu Semiconductor, NXP Semiconductors, Texas Instruments, Infineon Technologies, ROHM Semiconductor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan MCU Market Trends and Innovations
Edge computing architectures are migrating processing loads from centralized controllers to distributed sensing nodes, restructuring MCU memory and peripheral specifications across automotive and industrial deployments.
Embedded AI inference engines are digitizing real-time motor control decisions in electric powertrain systems. Tier-1 suppliers are adopting neural network accelerators at the actuator level. This compression of control loops is digitizing traditional PID-based architectures into predictive maintenance-capable subsystems.
METI's semiconductor reinforcement policies are redirecting subsidy eligibility toward domestic 40nm-90nm MCU capacity. Automotive component qualification under JIS standards now requires documented supply chain resilience. Tier-2 suppliers are restructuring foundry partnerships to secure METI allocation timing advantages.
Utility-led procurement consolidation is compressing supplier tiers in smart metering deployments. Regional power companies are mandating unified communication stacks that displace proprietary industrial fieldbus protocols. This standardization push is most visible in Kanto and Kansai metropolitan service territories.
Japan MCU Market Segmentation
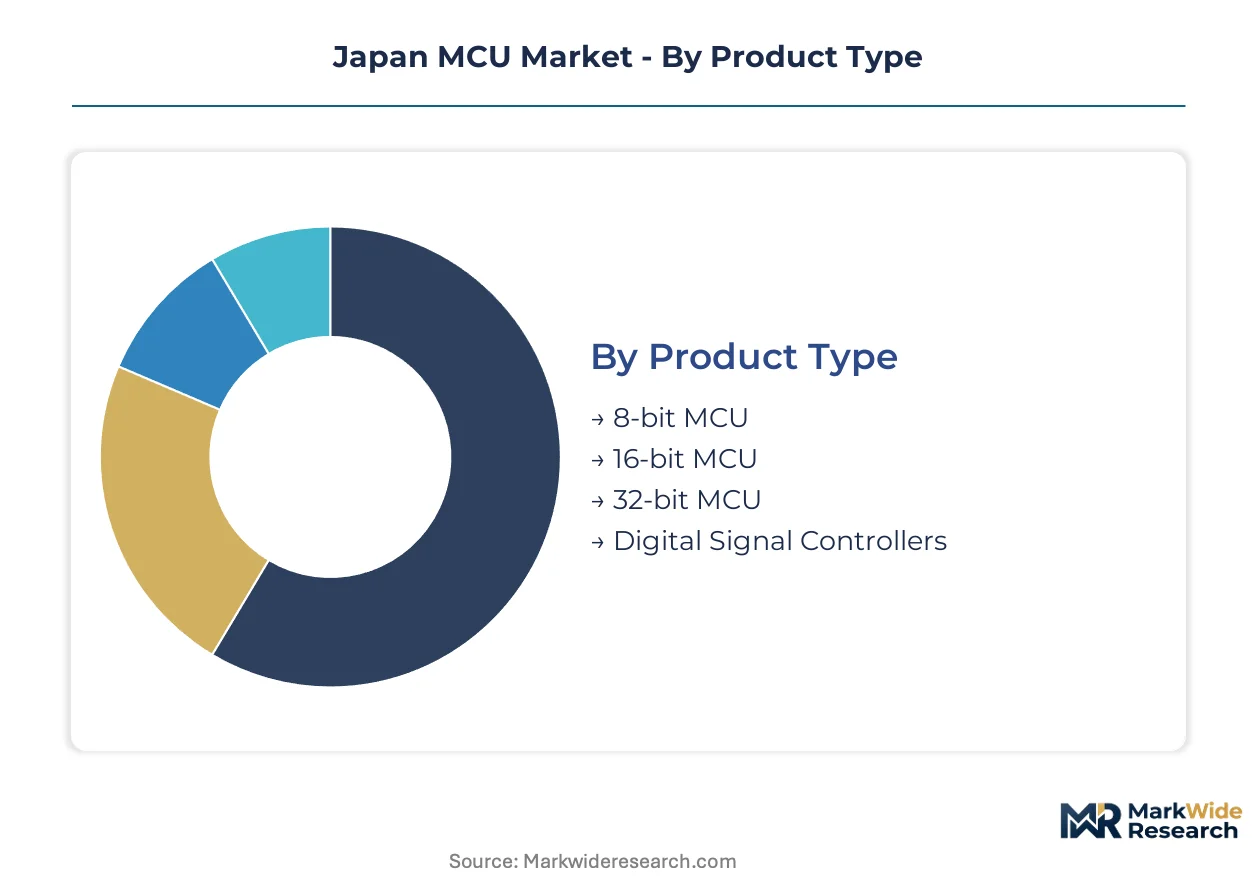
MCU segmentation in Japan reflects divergent qualification cycles across automotive, industrial, and consumer verticals. Product bit-width and peripheral integration depth determine which segments command premium positioning versus volume turnover.
Product Type:
Cycle times stretch longest for automotive-certified 32-bit devices, while 8-bit variants turn inventory fastest in cost-driven consumer subsystems.
- 32-bit MCU:These devices integrate ARM Cortex-M or proprietary RISC-V cores with embedded flash and rich analog peripherals. Automotive Systems applications in Tokyo and Yokohama headquarters clusters pull the strongest demand for ASIL-D certified variants with extended thermal tolerance.
- 8-bit MCU:Simplified architectures with limited memory addressing dominate legacy industrial equipment and basic consumer controls. Replacement demand concentrates in Kanto region factory automation retrofits where backward-compatible peripheral mappings reduce redesign costs.
- 16-bit MCU:Mid-range processing bridges cost-sensitive motor control and entry-level automotive body electronics.
- Digital Signal Controllers:DSP-enhanced cores target real-time power conversion and motor control algorithms in industrial drives.
32-bit MCU anchors the volume base while Digital Signal Controllers gains share at the steepest rate.
End User:
Margin structures stratify sharply between safety-certified automotive procurement and price-elastic consumer electronics sourcing.
- Automotive:OEMs and Tier-1 suppliers specify ASIL-D functional safety with 18-24 month qualification timelines. Electric powertrain electrification across domestic OEM headquarters in Tokyo and Yokohama is compressing refresh cycles for embedded controllers.
- Industrial Automation:Factory equipment builders prioritize 10-15 year supply continuity over leading-edge performance. Kyushu manufacturing corridors serve this demand through captive fab arrangements at legacy nodes.
- Consumer Electronics:White goods and appliance manufacturers drive high-volume, short-lifecycle procurement with minimal certification overhead.
- Healthcare Devices:PMDA oversight叠加 JIS standards creates dual certification burdens that extend qualification timelines for diagnostic and therapeutic equipment controllers.
Automotive commands the widest margin pools while Healthcare Devices faces the steepest regulatory escalation.
Application:
Deployment complexity scales from standalone sensing nodes to distributed real-time control networks across physical infrastructure.
- Automotive Systems:Powertrain, chassis, and body domain controllers require deterministic latency and fail-operational behavior. METI subsidy eligibility for domestic 40nm-90nm capacity reinforces supply security for these safety-critical applications.
- Smart Homes:Grid modernization mandates from Japanese utilities are accelerating 32-bit MCU deployment in connected metering and energy management subsystems. Direct utility procurement contracts bypass traditional distribution channels.
- Robotics:Servo motor control and kinematic processing demand high-frequency PWM and encoder feedback integration.
- Medical Equipment:Diagnostic imaging and patient monitoring systems require isolation-rated peripherals and documented EMC compliance under PMDA guidance.
Automotive Systems anchors the volume base while Smart Homes expands most quickly under utility procurement consolidation.
Technology:
Communication peripheral selection determines real-time determinism versus wiring cost tradeoffs in distributed architectures.
- CAN:Controller Area Network dominates automotive powertrain and chassis networks with prioritized message arbitration and fault confinement. JIS automotive standards now require documented supply chain resilience for CAN transceiver integration.
- SPI:Serial Peripheral Interface serves high-speed sensor fusion and external memory expansion in robotics motor control modules.
- I2C:Inter-Integrated Circuit reduces pin count for slow-speed configuration and monitoring buses in consumer subsystems.
- UART:Universal Asynchronous Receiver-Transmitter persists in legacy industrial fieldbus bridges and debug interfaces.
CAN anchors the volume base while SPI climbs the fastest in robotics and servo applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication concentrates along Kyushu's Naka and Kawashiri corridors, while demand pull clusters in Kanto's Tokyo-Yokohama headquarters belt. METI's domestic foundry subsidies are redistributing capacity investments across Japan's semiconductor geography.
Kanto
Automotive OEM headquarters in Tokyo and Yokohama drive embedded controller procurement for electric powertrains. METI's semiconductor reinforcement policies direct subsidy eligibility toward suppliers serving this corridor. Dense clusters of Tier-1 suppliers in Saitama and Kanagawa prefectures compress qualification cycles for ASIL-D certified devices.
Kyushu
Oita and Kumamoto prefectures host captive fab capacity for industrial and automotive-grade MCUs at 40nm-90nm nodes. METI's domestic capacity subsidies are attracting foundry partnerships to underutilized cleanroom facilities. Renesas Electronics leverages Naka and Kawashiri fabs to sustain captive wafer supply for automotive controllers.
Kansai
Osaka-based industrial equipment builders source legacy 8-bit MCUs for factory automation retrofits. JIS standards govern component qualification for machinery controllers deployed across the manufacturing belt. Kyoto and Hyogo prefectures maintain backward-compatible peripheral demand for cost-constrained subsystem replacements.
Chubu
Nagoya's automotive supplier ecosystem pulls 32-bit MCU demand for body electronics and chassis control modules. PMDA oversight叠加 JIS standards creates dual certification burdens for diagnostic equipment controllers sourced from regional medical device manufacturers. Aichi prefecture's robotics sector drives servo motor control integration.
Japan MCU Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base stratifies between captive fab operators and fabless design houses serving niche verticals. Three archetypes dominate: vertically integrated IDMs with in-house wafer supply, fabless specialists licensing ARM or RISC-V cores, and diversified conglomerates cross-leveraging semiconductor divisions. Competitive moves center on foundry partnership restructuring and silicon carbide module integration.
Among Japan-based integrated device manufacturers, Renesas Electronics, Toshiba Electronic Devices & Storage Corporation, and ROHM Semiconductor occupy positions spanning automotive certification tiers. Renesas exemplifies the captive fab archetype through Kyushu manufacturing corridors. Toshiba Electronic Devices & Storage Corporation anchors legacy industrial demand through Oita complex operations. ROHM Semiconductor represents the wide-bandgap integration vector with silicon carbide-integrated MCU modules targeting power electronics applications.
| Leading Market Players |
|---|
| Renesas Electronics |
| Toshiba Electronic Devices & Storage Corporation |
| Sony Semiconductor Solutions |
| Panasonic Corporation |
| Fujitsu Semiconductor |
| NXP Semiconductors |
| Texas Instruments |
| Infineon Technologies |
| ROHM Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Kyushu's Naka and Kawashiri fab corridors concentrate captive wafer capacity for automotive-grade MCUs, translating earthquake-vulnerable supply geography into pricing power for vertically integrated IDMs serving Tokyo-Yokohama OEM headquarters.
Pricing Analysis
METI's semiconductor reinforcement policies dictate the pricing tier structure across Japan's MCU market. Three-tier pricing separates ASIL-D certified automotive controllers from standard industrial variants and economy-grade consumer subsystems. Price differentiation hinges on functional safety certification grade and volume procurement scale. Cost compression in 8-bit consumer segments is intensifying because appliance manufacturers prioritize bill-of-materials reduction over peripheral performance. Healthcare device OEMs exhibit the lowest price sensitivity due to PMDA-mandated dual certification burdens that extend replacement cycles.
Supply Chain Analysis
Foundry concentration at Renesas Electronics' Naka and Kawashiri facilities, Toshiba's Oita complex, and ROHM's Kyoto operations anchors domestic 40nm-90nm MCU production. Raw material dependencies include silicon wafers from Shin-Etsu Chemical, photoresist from JSR Corporation, and specialty gases from Taiyo Nippon Sanso. Single-source vulnerability to seismic disruption along Kyushu's Pacific fault lines threatens wafer throughput. Distribution runs through direct OEM procurement contracts for automotive tiers and utility-led consolidated purchasing for smart metering deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across Japan's MCU landscape as electric powertrain electrification splinters demand into specialized thermal-tolerance and safety-certification niches that captive-fab IDMs and agile fabless designers can each exploit.
For Market Incumbents: Build certification moats through accelerated ASIL-D validation pipelines that compress 18-24 month qualification windows. Deepen foundry partnerships in Kyushu's underutilized Oita and Kumamoto cleanrooms to secure METI subsidy allocation timing advantages. Defensive positioning requires silicon carbide module integration to capture power electronics premium positioning before wide-bandgap convergence commoditizes motor control firmware. For New Entrants and Emerging Players: Pursue smart metering channel expansion through direct utility procurement contracts that bypass entrenched automotive distribution hierarchies. White-space concentrates in Kansai's legacy 8-bit industrial retrofit segment where backward-compatible peripheral architectures reduce incumbent switching costs. Go-to-market leverage rests on JIS standards pre-certification that accelerates factory automation qualification timelines against captive-fab competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fabless design houses licensing ARM or RISC-V cores for utility-mandated grid modernization subsystems. Long-term viability over a multi-year horizon favors acquisition targets with documented METI subsidy eligibility and established foundry partnerships at 40nm-90nm nodes. Monitor quarterly fab utilization rates across Kyushu corridors as the primary inflection indicator for inventory cycle positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Integration | ROHM Semiconductor's wide-bandgap convergence captures premium positioning in power electronics motor control. |
| Kyushu Foundry Partnership Expansion | Oita and Kumamoto cleanroom utilization secures METI subsidy eligibility for domestic 40nm-90nm capacity. |
| ASIL-D Certification Pipeline Acceleration | Compressed 18-24 month validation timelines defend automotive tier-1 supplier relationships against emerging entrants. |
| Direct Utility Procurement Channel Development | Smart metering contracts under grid modernization mandates bypass traditional distribution margin extraction. |
| Backward-Compatible 8-bit Peripheral Architecture | JIS-compliant industrial retrofit solutions reduce redesign costs in Kansai factory automation replacement cycles. |
Research Methodology
Initial hypotheses were tested against primary input from MCU product managers at IDMs, Tier-1 automotive supplier procurement directors, utility smart metering program officers, and industrial equipment OEM engineering leads and refined through secondary validation across METI semiconductor policy filings, JIS automotive standard documentation, PMDA medical device guidance releases, and Renesas-Toshiba-ROHM investor disclosure materials. Bottom-up segment sizing triangulated against top-down wafer fab capacity modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product bit-width, end-use vertical, application complexity, and communication peripheral technology. CAGRs were derived through regression analysis of historical procurement patterns and forward-looking OEM electrification roadmaps. Industry-specific forecast inputs incorporated electric vehicle platform rollout schedules and utility grid modernization directive implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates, automotive production volumes, or earthquake frequency would shift the trajectory. Forecasts reflect documented assumptions regarding METI subsidy allocation timing and foundry partnership stability. Quarterly review of Kyushu fab utilization rates, OEM powertrain procurement announcements, and utility metering contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
IGBT and Super Junction MOSFET Market
Semiconductor Devices
Transistor Arrays Market