
 Japan MLCC Market | 2026-2036
Japan MLCC Market Size, Share, and Industry Trends Forecast 2026-2036
Japan MLCC Market Insights
Component distribution through authorized distributors is tilting toward direct OEM partnerships as automotive and telecommunications buyers consolidate procurement. Murata Manufacturing Co., Ltd. leverages its vertically integrated ceramic powder operations to secure feedstock autonomy. TDK Corporation anchors high-frequency product lines through sustained R&D spending on ultra-high capacitance formulations. Taiyo Yuden Co., Ltd. specializes in compact chip architectures for consumer electronics miniaturization trends.
Multilayer ceramic capacitors consist of alternating layers of ceramic dielectric and metal electrodes fired into monolithic blocks, typically achieving capacitance values from picofarads to microfarads with voltage ratings spanning low-voltage signal paths to high-voltage power rails. These components filter noise, stabilize voltage, and store charge across printed circuit assemblies in virtually every electronic system. The multilayer product category commands the dominant revenue position due to its unmatched volumetric efficiency and compatibility with surface mount installation workflows. Automotive end users represent the fastest-expanding demand pool as electrified powertrains and advanced driver-assistance systems multiply per-vehicle MLCC counts. Surface mount installation types capture the majority of unit volume given their suitability for automated assembly lines and miniaturized device footprints.
METI's critical component supply chain resilience programs, JIS standards for electronic component reliability, and PMDA-adjacent quality frameworks for automotive-grade parts collectively elevate domestic manufacturing requirements and certification burdens. These regulations compel suppliers to maintain traceable production records and accelerated life-test documentation for qualified product lines. Stakeholders must monitor METI subsidy allocations for domestic capacity expansion and the evolving JIS revision cycle governing high-temperature operational specifications.
Market Dynamics
Automotive electrification programs are compressing product development cycles and forcing MLCC suppliers to align capacity expansion with tier-one OEM qualification timelines. METI's component material security initiatives are simultaneously reshaping domestic sourcing requirements and accelerating localization investments.
Growth Catalysts
- XEV Powertrain Proliferation:Battery electric and hybrid vehicle platforms are multiplying per-unit MLCC counts by three to five times over internal combustion equivalents. Tier-one automotive suppliers are locking in multi-year procurement agreements with Japanese manufacturers.
- METI Critical Component Resilience Programs:Subsidy allocations for domestic capacity expansion are incentivizing foundry investments in the Kansai industrial corridor. These programs mandate traceable production records and accelerated life-test documentation.
- Advanced Driver-Assistance Systems:Sensor fusion and compute-intensive safety features are driving demand for high-reliability, high-temperature-rated components. Automotive-grade qualification cycles are shortening as OEMs compress platform development schedules.
Market Restraints
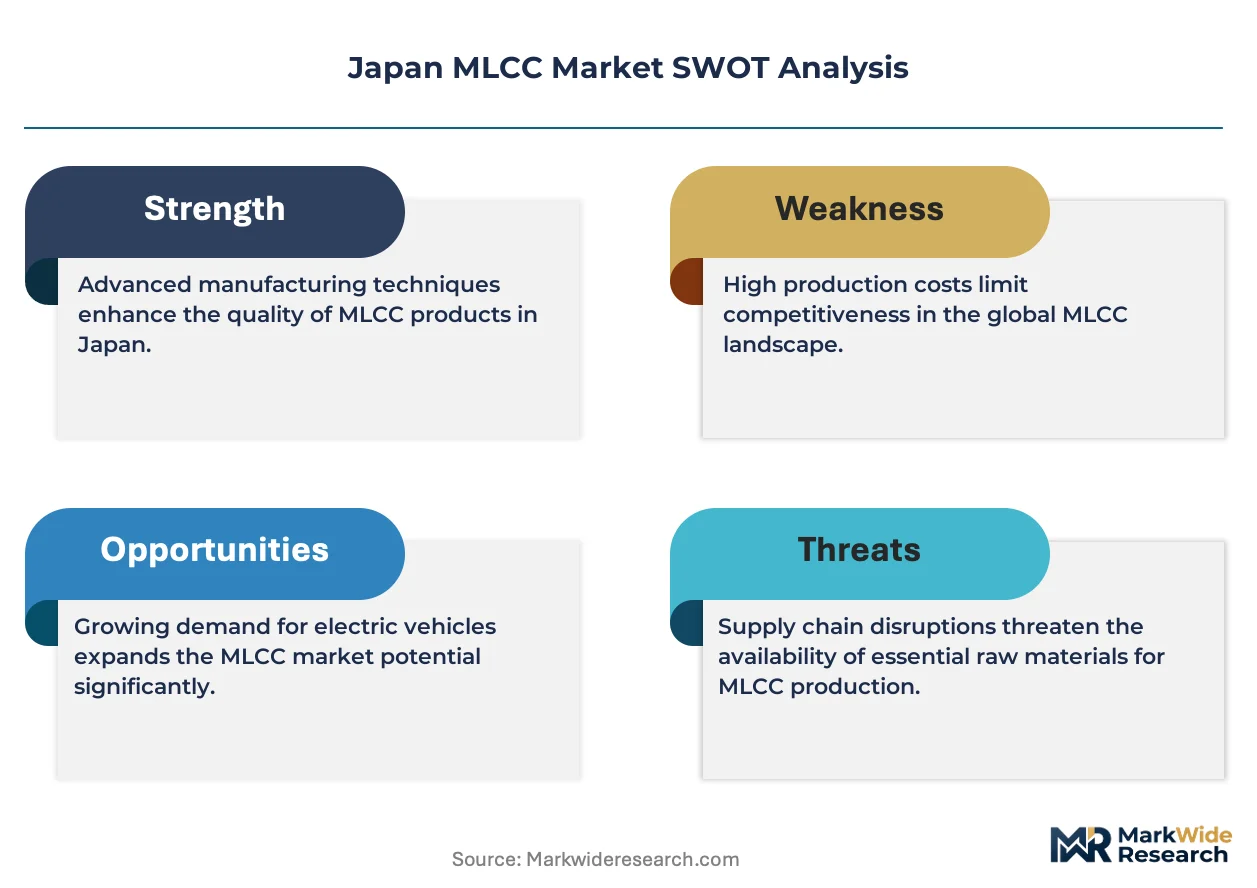
- Raw Material Concentration Risk:High-purity barium titanate and nickel electrode feedstock supply concentrates in Chinese processing facilities. Japanese manufacturers face input cost volatility and geopolitical supply disruption exposure.
- JIS Certification Burden:Revised high-temperature operational specifications are extending qualification timelines by twelve to eighteen months. Smaller domestic suppliers struggle with accelerated life-test documentation requirements.
- Polymer Capacitor Substitution:Tantalum polymer and aluminum polymer technologies are capturing select high-ripple automotive power applications. MLCC suppliers must defend position through volumetric efficiency advantages in space-constrained modules.
Strategic Opportunities
- Hokkaido Green Energy Manufacturing:Renewable-powered production facilities in northern Japan offer carbon-neutral component qualification for European automotive OEMs. METI subsidies support geothermal and wind-powered foundry investments.
- Telecommunications Infrastructure Refresh:Base station densification for 5G-Advanced and early 6G trials requires high-frequency, low-loss MLCC formulations. Network equipment manufacturers are qualifying new chip architectures for millimeter-wave applications.
- Medical Device Miniaturization:Implantable and portable diagnostic equipment manufacturers are specifying compact, biocompatible capacitor solutions. PMDA-adjacent quality frameworks create certification pathways for qualified product lines.
Industry Challenges
- Thin-Film Deposition Expertise Gap:Advanced dielectric layering processes require specialized ceramic engineering talent that domestic universities and technical institutes are not producing at sufficient scale. Manufacturers compete for limited experienced process engineers.
- Multi-Site Quality Harmonization:OEMs are demanding identical performance distributions across geographically dispersed production lines. Achieving statistical process control equivalence between Osaka and Kyoto facilities strains metrology and calibration systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan MLCC Market |
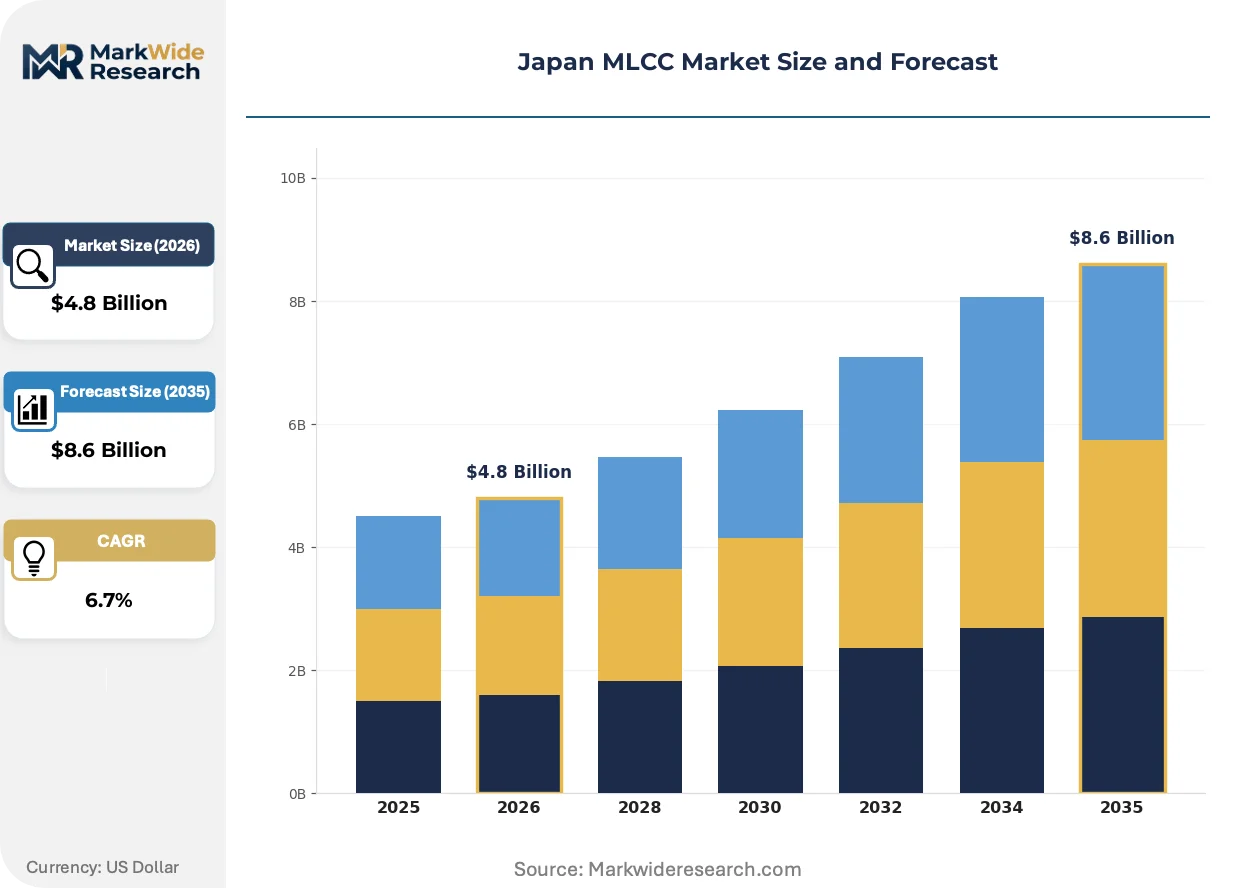
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multilayer, Ceramic, Tantalum, Aluminum End User: Consumer Electronics, Automotive, Industrial Applications, Telecommunications Installation Type: Surface Mount, Through-Hole, Hybrid, Chip Capacitance Range: Low, Medium, High, Ultra-High |
| Companies Covered | Kyocera AVX Components Corporation, Nippon Chemi-Con Corporation, Murata Manufacturing Co., Ltd., Yageo Group, Samsung Electro-Mechanics Co., Ltd., TDK Corporation, Maruwa Co., Ltd., Kyocera Corporation, Taiyo Yuden Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan MLCC Market Trends and Innovations
Dielectric material science and installation packaging are converging to enable higher capacitance density in smaller footprints. These advances are reshaping competitive positioning between integrated manufacturers and specialized component suppliers.
Nickel-based electrode formulations are replacing silver-palladium systems in mid-voltage automotive applications. Tier-one suppliers are adopting these formulations to reduce precious metal exposure and stabilize input costs. The technology is migrating from consumer electronics into powertrain modules as reliability data accumulates from fleet testing programs.
METI's semiconductor and component material security initiatives are mandating domestic sourcing thresholds for critical electronic components. Japanese manufacturers are reconfiguring supply networks to qualify local ceramic powder and electrode material suppliers. Automotive-grade product lines face the most stringent traceability requirements under these frameworks.
Direct OEM partnerships are displacing authorized distributor relationships for high-volume automotive and telecommunications procurement. Tier-one buyers are consolidating supplier lists and negotiating frame contracts with guaranteed capacity allocation. This concentration is most visible in the Kansai industrial corridor where major OEMs maintain engineering co-location facilities.
Japan MLCC Market Segmentation
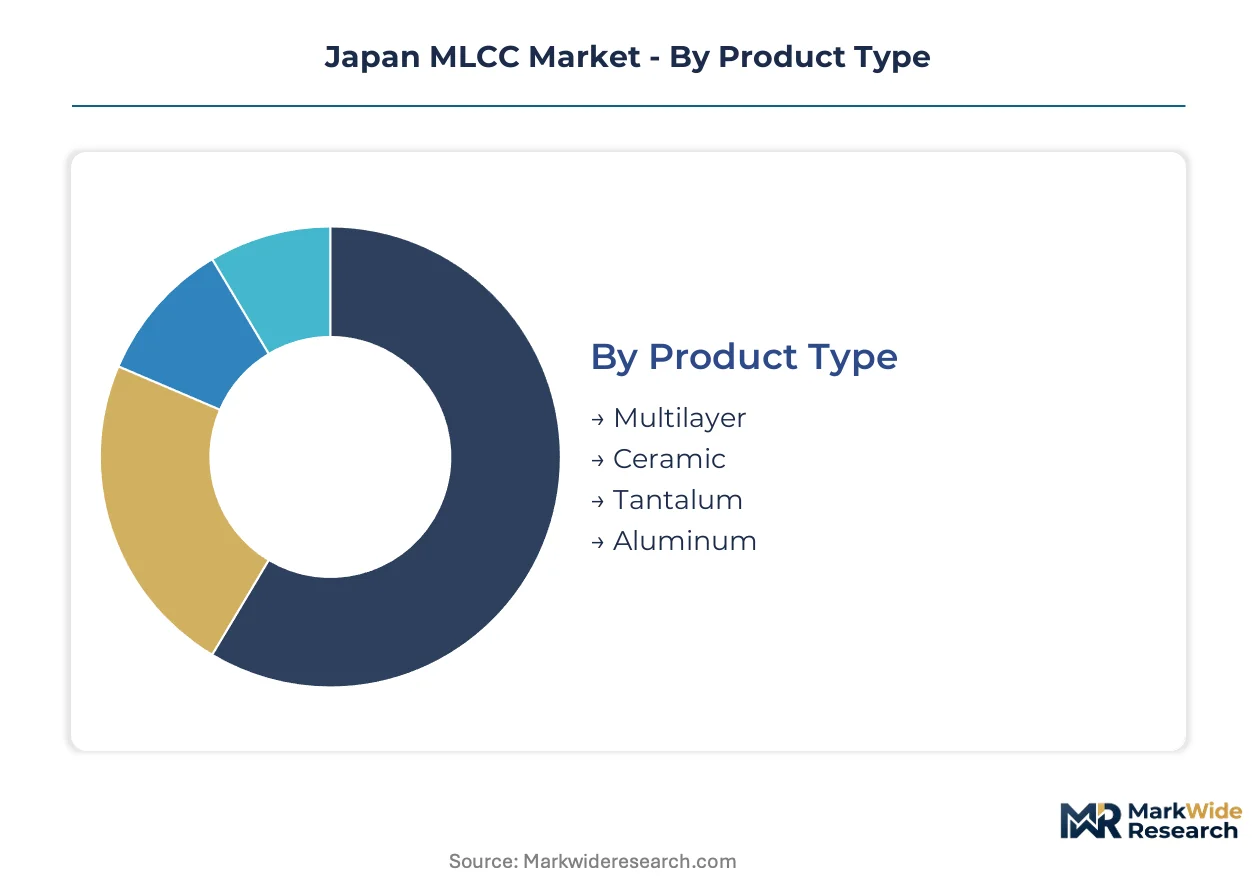
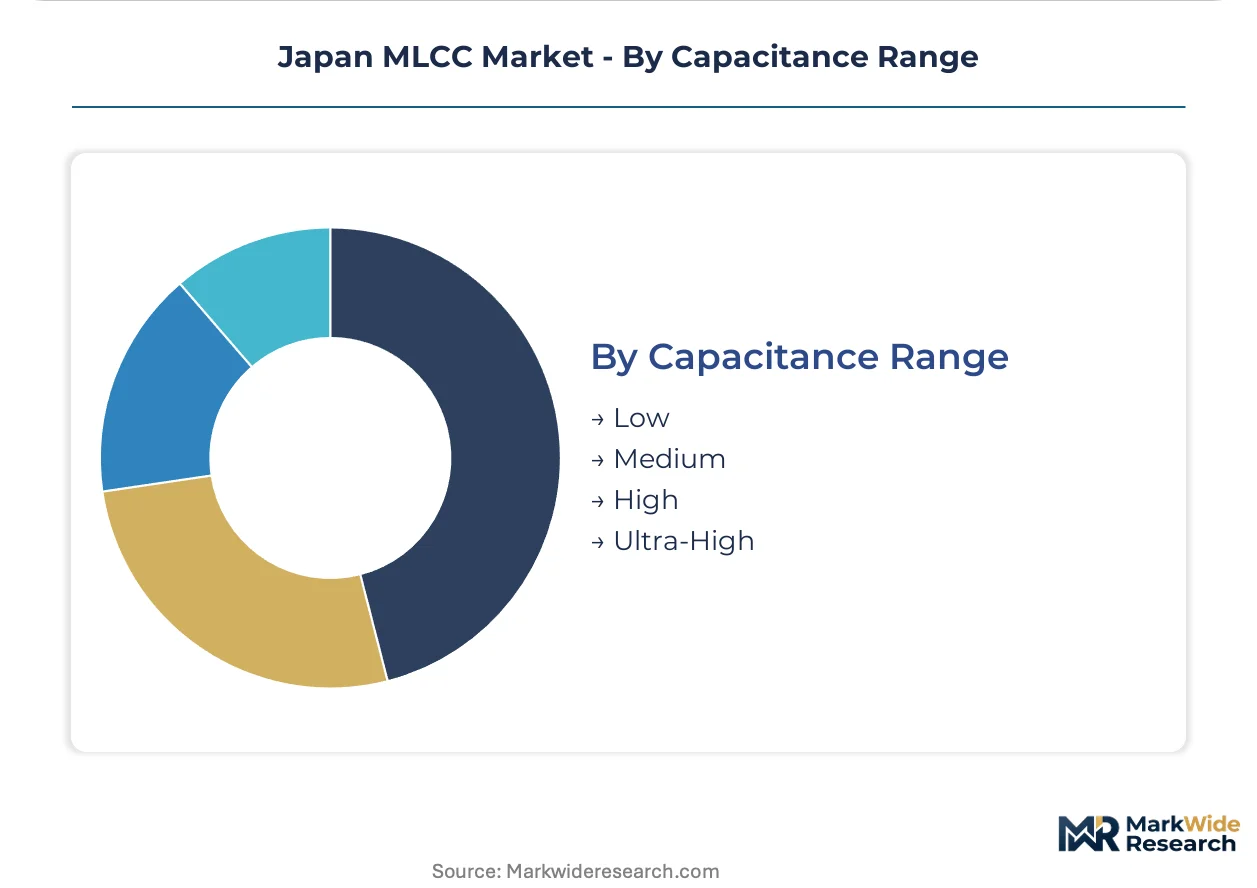
MLCC segmentation in Japan reflects the tension between automotive electrification timelines and consumer electronics miniaturization imperatives. Each dimension carries distinct qualification burdens and margin structures that reshape supplier resource allocation across the Kansai industrial corridor.
Product Type:
Cost tier differentiation separates commodity dielectric formulations from precision-engineered automotive-grade architectures.
- Multilayer:Alternating ceramic dielectric and metal electrode layers fire into monolithic blocks achieving unmatched volumetric efficiency. Osaka-based tier-one automotive suppliers lock in multi-year procurement agreements for electrified powertrain modules.
- Ceramic:Monolithic dielectric bodies deliver temperature stability and low equivalent series resistance for high-frequency filtering. Kyoto prefecture manufacturers concentrate capacity expansion on these formulations for 5G-Advanced base station deployments.
- Tantalum:Manganese or polymer cathode systems suit high-capacitance density in space-constrained medical implantables.
- Aluminum:Etched foil and electrolyte combinations dominate cost-sensitive consumer power supply applications.
Multilayer holds installed capacity. Ceramic is rotating up the share rankings.
End User:
Application-specific qualification cycles range from six months for consumer electronics to thirty-six months for automotive-grade certification.
- Automotive:Battery electric and hybrid platforms multiply per-vehicle MLCC counts three to five times over internal combustion equivalents. METI subsidy programs mandate traceable production records and accelerated life-test documentation for qualified product lines.
- Consumer Electronics:Smartphones, wearables, and portable computing devices drive demand for compact chip architectures. Taiyo Yuden specializes in these miniaturization trends through advanced thin-film deposition expertise.
- Industrial Applications:Factory automation and power conversion equipment require extended temperature range specifications.
- Telecommunications:Base station densification for 5G-Advanced trials demands high-frequency, low-loss formulations.
Automotive commands qualification investment. Consumer Electronics maintains volume leadership.
Installation Type:
Mounting methodology determines automation compatibility and thermal management characteristics in finished assemblies.
- Surface Mount:Rectangular chip terminals enable high-speed pick-and-place assembly and miniaturized device footprints. Automated production lines across Osaka prefecture facilities process these components at highest throughput rates.
- Chip:Unencapsulated dielectric bodies integrate directly into substrate-embedded architectures for ultra-compact modules. Network equipment manufacturers qualify these for millimeter-wave 6G trial applications.
- Through-Hole:Radial or axial leads suit high-vibration industrial environments and repairable equipment.
- Hybrid:Mixed mounting approaches accommodate legacy system upgrades and transition designs.
Surface Mount dominates unit economics. Chip formats are climbing the fastest.
Capacitance Range:
Performance tier segmentation aligns with voltage rail requirements from signal conditioning to power delivery subsystems.
- High:Microfarad-scale values stabilize voltage in electrified powertrain DC-link and inverter stages. TDK anchors these product lines through sustained R&D spending on ultra-high capacitance formulations.
- Ultra-High:Extended capacitance density enables bulk energy storage in space-constrained automotive modules. Murata leverages vertically integrated ceramic powder operations to secure feedstock autonomy for these specifications.
- Low:Picofarad values filter high-frequency noise in RF and timing circuits.
- Medium:Mid-range values balance cost and performance in general-purpose decoupling applications.
High capacitance commands premium positioning. Ultra-High is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka prefecture commands premium pricing for automotive-grade MLCCs while Hokkaido manufacturing clusters compete on carbon-neutral credentials. This pricing-power asymmetry shapes capacity investment decisions across Japanese sub-regions.
Kansai Industrial Corridor
Osaka and Kyoto prefectures concentrate tier-one automotive supplier engineering co-location facilities. METI subsidy programs for domestic capacity expansion prioritize traceable production records in this corridor. Murata Manufacturing anchors vertically integrated ceramic powder operations across Osaka facilities.
Kanto Metropolitan Region
Tokyo and surrounding prefectures drive telecommunications infrastructure procurement for 5G-Advanced base station deployments. JIS standards for electronic component reliability govern qualification timelines for network equipment manufacturers. TDK Corporation sustains R&D spending on ultra-high capacitance formulations from Kanto research centers.
Chubu Manufacturing Belt
Nagoya and Aichi prefectures supply industrial automation and power conversion equipment manufacturers. PMDA-adjacent quality frameworks for automotive-grade parts extend certification requirements to adjacent industrial applications. Taiyo Yuden specializes in compact chip architectures from Chubu production facilities.
Hokkaido Green Energy Zone
Northern Japan's renewable-powered production facilities target European automotive OEM carbon-neutral qualification requirements. METI subsidies support geothermal and wind-powered foundry investments across the island. Emerging capacity expansion focuses on high-temperature operational specifications for electrified powertrains.
Kyushu Semiconductor Cluster
Fukuoka and Kumamoto prefectures host back-end packaging and testing operations for consumer electronics miniaturization. Regional technical institutes struggle to produce sufficient thin-film deposition engineering talent. Samsung Electro-Mechanics maintains assembly operations alongside domestic Japanese suppliers.
Japan MLCC Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base consolidates around vertically integrated ceramic material producers and specialized chip architecture designers. Three archetypes dominate: integrated material-to-component manufacturers, precision deposition specialists, and scale-driven commodity suppliers. Competitive moves concentrate on direct OEM partnership formation and nickel-based electrode formulation migration from precious metal systems.
Among Japan-based integrated manufacturers, Murata Manufacturing Co., Ltd., TDK Corporation, and Taiyo Yuden Co., Ltd. occupy positions across distinct specialization vectors. Murata exemplifies feedstock-autonomous operations through captive ceramic powder production. TDK anchors high-reliability product line development for automotive electrification programs. Taiyo Yuden represents compact architecture expertise targeting consumer electronics miniaturization trends.
| Leading Market Players |
|---|
| Kyocera AVX Components Corporation |
| Nippon Chemi-Con Corporation |
| Murata Manufacturing Co., Ltd. |
| Yageo Group |
| Samsung Electro-Mechanics Co., Ltd. |
| TDK Corporation |
| Maruwa Co., Ltd. |
| Kyocera Corporation |
| Taiyo Yuden Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
High-purity barium titanate processing concentration in Chinese facilities funnels margin capture toward electrode material suppliers and tier-one automotive OEMs with locked-in procurement agreements. Japanese manufacturers absorb input cost volatility through long-term offtake structures while passing qualification premiums to electrified powertrain buyers.
Pricing Analysis
Configured-to-order automotive-grade MLCCs command spreads of three to five times over standard consumer electronics pricing. Contract-based long-term offtake agreements dominate procurement between Osaka-based tier-one suppliers and domestic manufacturers. Price differentiation hinges on JIS certification grade and volume scale, with automotive buyers showing least sensitivity due to platform lock-in. Cost compression in consumer tiers is intensifying because polymer capacitor substitutes are capturing select high-ripple power applications.
Supply Chain Analysis
High-purity ceramic powder and nickel electrode feedstock draws from Chinese, South Korean, and select Japanese processing facilities. Raw material dependencies center on barium titanate dielectric precursors, nickel cathode formulations, and rare-earth dopants for temperature stability. Single-source vulnerability concentrates in Chinese barium titanate refinement capacity. Distribution runs through direct OEM partnerships that are displacing authorized distributor channels for automotive and telecommunications procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's MLCC market sits in early-cycle expansion as battery electric vehicle platforms multiply per-unit component counts three to five times over internal combustion equivalents. METI subsidy programs for domestic capacity expansion provide additional tailwinds for localization investments.
For Market Incumbents: Harden feedstock security through backward integration into ceramic powder operations or captive supply agreements with qualified Japanese material suppliers. Lock in multi-year procurement agreements with tier-one automotive OEMs before qualification cycles compress further. Polymer capacitor substitution in high-ripple automotive power applications represents the most credible technology threat requiring defensive R&D allocation.
For New Entrants and Emerging Players: Hokkaido's renewable-powered production facilities offer underpenetrated entry points for carbon-neutral component qualification with European automotive OEMs. Medical device miniaturization applications specify compact, biocompatible solutions where PMDA-adjacent quality frameworks create certification pathways without incumbent lock-in. Pursue qualification partnerships with implantable equipment manufacturers seeking second-source capacitor supply.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision deposition specialists holding thin-film ceramic engineering expertise. Five-to-ten year viability hinges on automotive electrification sustaining qualification investment cycles and METI subsidy programs maintaining localization incentives. Monitor JIS revision cycles for high-temperature operational specifications as inflection indicators for certification burden expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Powder Operations | Murata's captive barium titanate production secures feedstock autonomy against Chinese supply volatility. |
| Direct OEM Partnership Formation | Tier-one automotive suppliers in Osaka are consolidating procurement through frame contracts with guaranteed capacity allocation. |
| Nickel-Based Electrode Migration | Replacing silver-palladium systems reduces precious metal exposure and stabilizes input costs for powertrain modules. |
| Hokkaido Green Energy Manufacturing | Geothermal and wind-powered foundries qualify for European OEM carbon-neutral component requirements. |
| JIS High-Temperature Certification Investment | Accelerated life-test documentation capabilities differentiate qualified product lines for automotive-grade procurement. |
Research Methodology
Desk research of METI subsidy allocation records, JIS standards documentation, and automotive OEM procurement disclosures preceded structured interviews with tier-one supplier procurement directors, ceramic process engineers, and foundry operations managers. Primary fieldwork across Osaka, Kyoto, and Hokkaido production facilities was cross-referenced against customs data for barium titanate and nickel electrode feedstock imports. Bottom-up capacity modeling and top-down demand segmentation from vehicle production databases were triangulated to establish market sizing.
Assumptions held fixed include METI critical component resilience program continuity, JIS revision timelines for high-temperature specifications, and automotive electrification penetration curves. Variables tested across the projection horizon encompass polymer capacitor substitution rates, Chinese feedstock export restriction scenarios, and European OEM carbon-neutral qualification adoption. Segmentation dimensions modeled include product type, end-user industry, installation format, and capacitance performance tier. CAGRs were derived from installed capacity expansion schedules matched against OEM platform launch timelines.
Practitioners should monitor JIS revision triggers for high-temperature operational specifications and METI subsidy reallocation signals for early indications of forecast deviation. Automotive-grade qualification cycle compression and polymer capacitor technology maturation represent specific risk factors that could revise demand projections. Cross-checking against vehicle production databases and tier-one supplier procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Gan on Diamond Technology Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Spin Filters Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Bipolar Transistors Market
Semiconductor Devices
Super Junction Mosfet Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Precision Link Carrier Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Photosensitive Semiconductor Device Market