
 Copper Clad Laminate for Consumer Electronics Market | 2026-2036
Copper Clad Laminate for Consumer Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Clad Laminate for Consumer Electronics Market Insights
Multi-source procurement is rebalancing toward dual-source strategies among major laminate buyers. Kingboard Laminates Holdings Ltd. leverages its integrated resin-to-foil operations across Guangdong facilities. Shengyi Technology Co., Ltd. anchors high-volume supply into Shenzhen-based smartphone OEMs. Panasonic Holdings Corporation differentiates through halogen-free formulations for premium wearable segments.
Copper clad laminate for consumer electronics consists of a copper foil layer bonded to a reinforced resin substrate, typically achieving glass transition temperatures between 150°C and 200°C for surface-mount assembly compatibility. The material serves as the foundational conductive platform for printed circuit boards in compact, thermally constrained devices. Low Loss formulations capture expanding margin pools as millimeter-wave antenna modules penetrate flagship smartphone tiers. Thermal Clad variants sustain stable demand from tablet and laptop OEMs managing processor heat density. Reinforced substrates dominate volume shipments through contract manufacturers serving mid-range electronics assembly.
China's SAMR enforces GB standards for flame-retardant laminate grades, while the EU RoHS framework restricts halogenated compounds in devices sold across member states. Japan's METI oversees JIS certification for high-reliability materials bound for automotive-integrated consumer electronics. Stakeholders must monitor evolving dual carbon goals from China's MEE and their downstream impact on resin energy accounting and copper smelter carbon intensity disclosures.
Market Dynamics
Millimeter-wave antenna integration in flagship smartphones is compressing design cycles and forcing laminate suppliers to certify Low Loss formulations under tighter thermal budgets.
Growth Catalysts
- 5G Substrate Demand:Smartphone OEMs in Shenzhen and Seoul are expanding orders for high-frequency laminates supporting sub-6GHz and mmWave bands.
- EU RoHS Directives:Halogen-free material mandates across member states are pulling premium laminate grades into wearable and tablet supply chains.
- East Asian Manufacturing Clusters:Contract electronics manufacturers in Guangdong and Taiwan concentrate PCB assembly demand for mid-range consumer devices.
Market Restraints
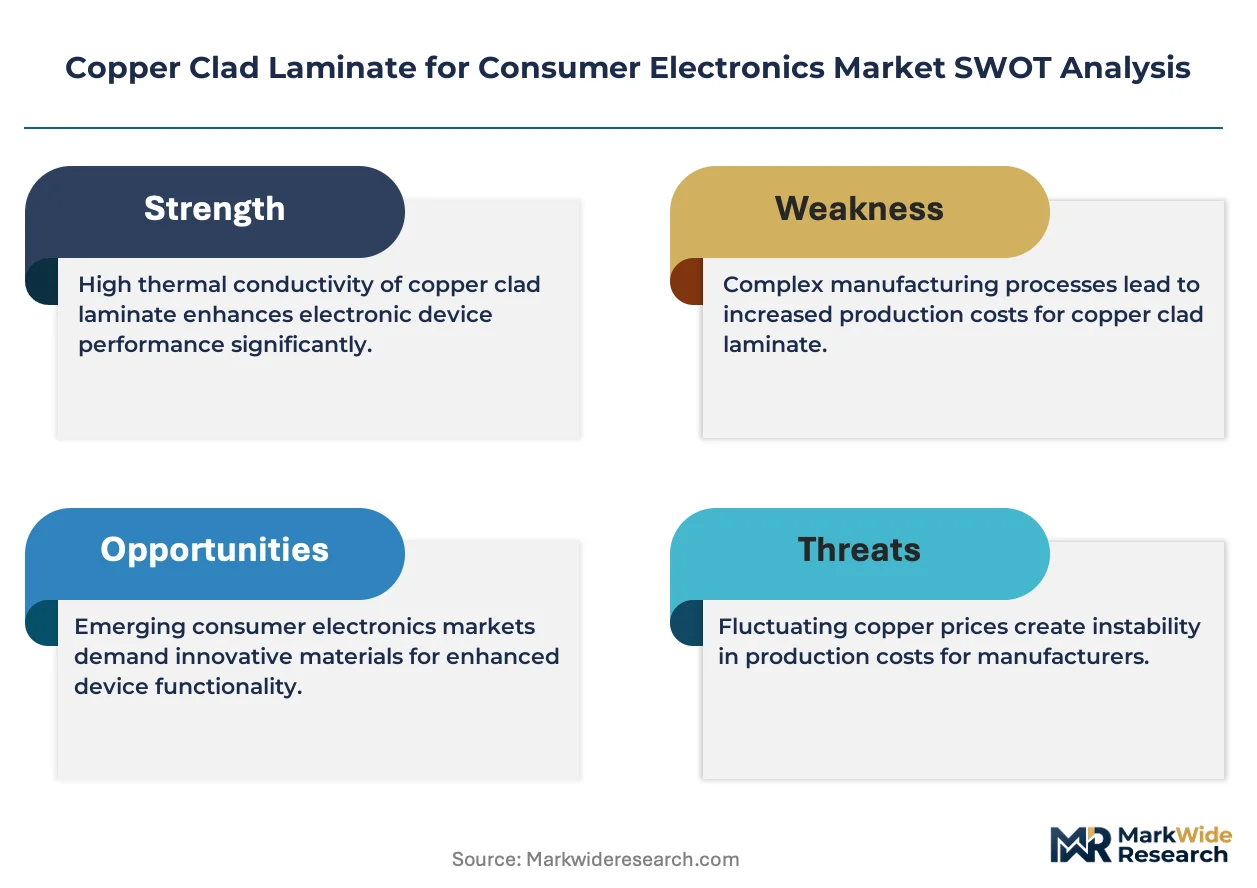
- Copper Foil Volatility:Electrodeposited foil pricing fluctuates with LME copper benchmarks and Chinese smelter output constraints.
- Resin Supply Concentration:Epoxy and polyimide precursor production clusters in Japan and South Korea create single-source exposure for high-Tg formulations.
- Halogen-Free Technical Limits:Flame-retardant performance in non-halogen laminates remains below brominated alternatives for ultra-thin smartphone PCBs.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for smartphone assembly are pulling laminate demand toward Mumbai and Chennai production zones.
- Automotive-Consumer Convergence:Infotainment modules in electric vehicles require consumer-grade laminates with automotive reliability certification.
- Recyclable Substrate Formulations:China's MEE dual carbon goals are creating preferential procurement channels for bio-based resin laminates.
Industry Challenges
- GB Standard Certification Timelines:China's SAMR flame-retardant testing protocols extend qualification periods by four to six months for new laminate grades.
- High-Frequency Design Talent Scarcity:Millimeter-wave PCB layout expertise concentrates among senior engineers in Taiwan and South Korea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Clad Laminate for Consumer Electronics Market |
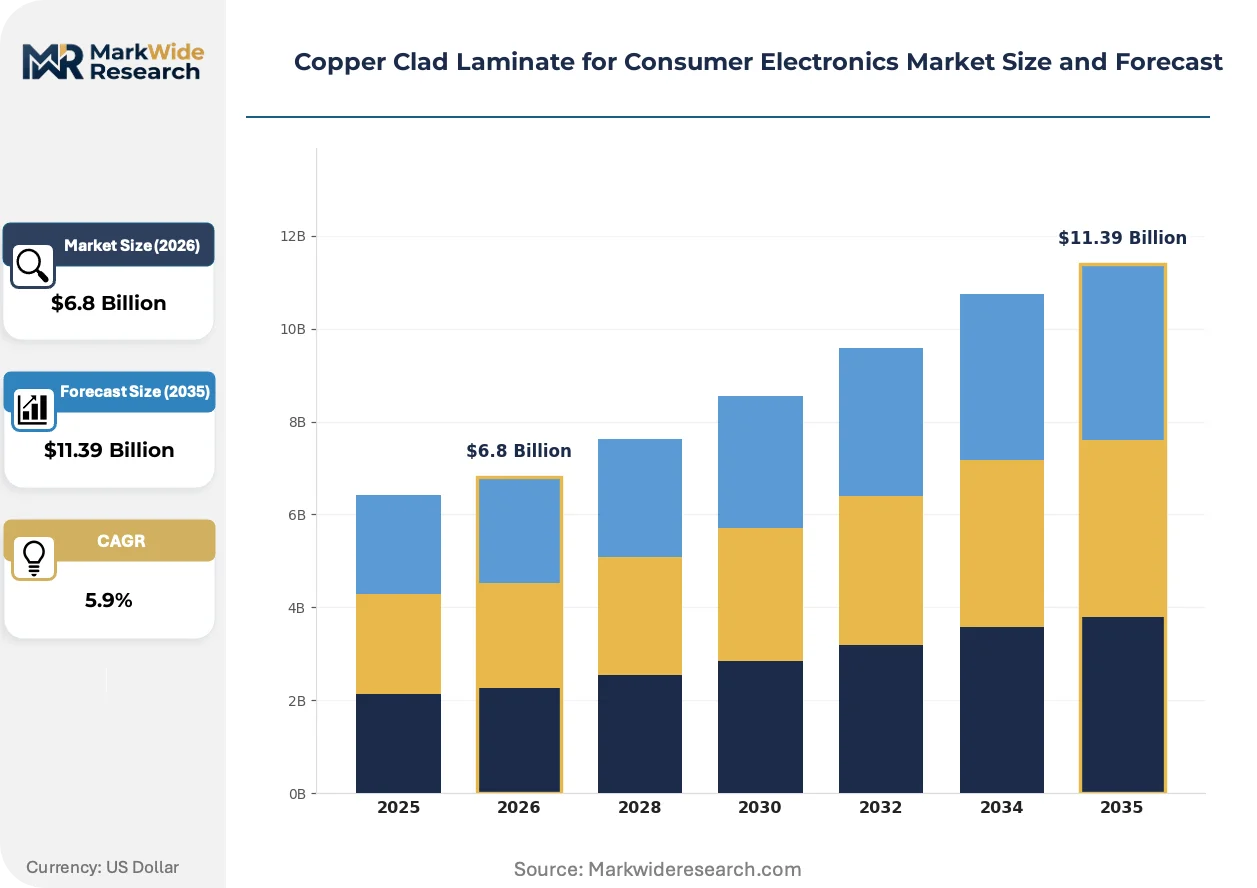
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Clad, High Tg, Low Loss, Reinforced Application: Smartphones, Tablets, Laptops, Wearables End User: OEMs, Aftermarket Providers, Contract Manufacturers, Distributors Packaging Type: Rolls, Sheets, Panels, Custom Sizes |
| Companies Covered | Kingboard Laminates Holdings Ltd., Shengyi Technology Co., Ltd., Nan Ya Plastics Corporation, Panasonic Holdings Corporation, Taiwan Union Technology Corporation, ITEQ Corporation, Doosan Corporation, Guangdong Chaohua Technology Co. Ltd., Sytech Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Clad Laminate for Consumer Electronics Market Trends and Innovations
Material architectures are fragmenting into application-specific formulations as thermal and signal integrity requirements diverge across smartphone, wearable, and computing segments.
Low Loss dielectric laminates are modularizing around disaggregated antenna-in-package designs. Flagship smartphone OEMs in South Korea and China are qualifying these substrates for mmWave modules at compressed two-quarter cycles. This modularization is compressing supplier margins on standardized FR-4 alternatives while opening premium pools for tailored formulations.
China's GB standards for flame-retardant laminates are tightening test protocols under SAMR enforcement. Domestic suppliers must recertify legacy halogenated grades or exit government procurement channels. Premium wearable OEMs serving EU markets are accelerating halogen-free transitions to preempt RoHS scope expansions.
Dual-source procurement mandates from tier-one smartphone assemblers are fragmenting long-term contracts. Buyers in Shenzhen and Taipei are splitting volume across integrated resin producers and specialized foil laminators. This pattern is most visible in 5G-ready substrate categories where qualification costs lock out tertiary suppliers.
Copper Clad Laminate for Consumer Electronics Market Segmentation
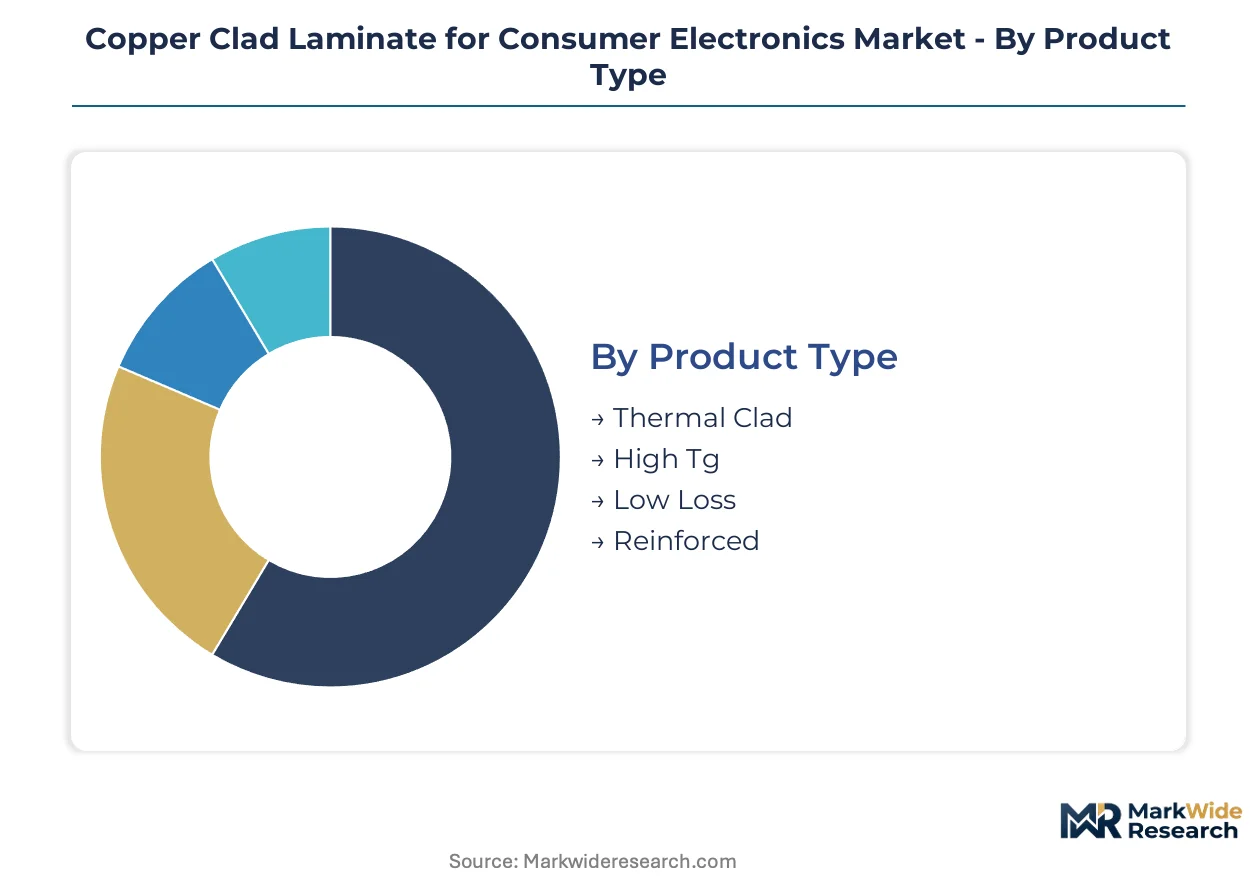
Material specifications diverge sharply across consumer electronics subsystems, forcing laminate suppliers to maintain parallel production lines for thermal, dielectric, and mechanical performance tiers. Procurement patterns track directly to the geographic clustering of final assembly capacity.
Product Type:
Resin formulation and copper foil bonding processes concentrate among integrated producers in Guangdong and Taiwan, creating supply bottlenecks for specialized thermal and high-frequency grades.
- Low Loss:Dielectric constant below 3.5 at 10 GHz enables millimeter-wave signal integrity in 5G antenna modules. Samsung and Xiaomi flagship programs in Seoul and Shenzhen are qualifying these substrates on compressed two-quarter cycles. Halogen-free Low Loss variants command premium positioning as EU RoHS scope expands.
- Thermal Clad:Aluminum-backed metal core construction dissipates processor heat density in tablets and ultrabooks. Dell and HP laptop programs in Taiwan-bound ODM channels sustain steady volume offtake despite longer qualification timelines than standard FR-4.
- High Tg:Glass transition temperatures exceeding 170°C support lead-free reflow assembly in high-density smartphone PCBs. Guangdong-based laminate producers dominate volume output for mid-tier handset OEMs.
- Reinforced:Woven glass fiber substrates bonded with epoxy resin provide mechanical rigidity for consumer electronics chassis integration. Contract manufacturers in Shenzhen pull the majority of standard-grade reinforced laminate volume.
Reinforced substrates absorb the bulk of installed capacity; Low Loss is expanding most quickly.
Application:
End-use thermal budgets and signal frequency requirements stratify laminate procurement into four distinct specification clusters with minimal overlap in supplier qualification.
- Smartphones:Sub-6GHz and mmWave antenna integration demands Low Loss laminates with tight thickness tolerance for folded-flex designs. Shenzhen-based OEMs are dual-sourcing 5G substrate grades to mitigate qualification risk.
- Tablets:Larger form factors accommodate Thermal Clad variants managing display driver and processor heat density. Taiwan ODMs serving Apple and Amazon programs anchor demand concentration.
- Wearables:Ultra-thin halogen-free laminates balance flame-retardant compliance with flexural endurance in curved form factors. EU-bound wearable OEMs are accelerating transitions ahead of anticipated RoHS scope revisions.
- Laptops:High Tg and Reinforced grades dominate motherboard and keyboard controller applications. HP and Lenovo procurement channels split volume between integrated resin producers and specialized foil laminators.
Smartphone procurement absorbs the bulk of laminate R&D investment; wearables are climbing the fastest specification ladder.
End User:
Procurement authority concentrates differently across direct OEM channels versus contract manufacturing intermediaries, fragmenting pricing structures and technical support requirements.
- OEMs:Apple, Samsung, and Xiaomi maintain direct laminate qualification programs with locked specification control. Their technical teams conduct independent reliability testing at Shenzhen and Seoul facilities.
- Contract Manufacturers:Foxconn, Pegatron, and BYD Electronics aggregate laminate demand across multiple OEM programs. Their procurement offices enforce dual-source mandates that fragment long-term supply agreements.
- Distributors:Arrow Electronics and Avnet maintain regional inventory positions for aftermarket repair channels and smaller OEMs without direct mill relationships.
- Aftermarket Providers:Independent repair networks source standard-grade reinforced laminates for logic board refurbishment, primarily through Shenzhen component trading hubs.
Contract manufacturers absorb the bulk of volume throughput; OEM direct procurement is gaining share fastest in premium 5G substrate categories.
Packaging Type:
Logistics configuration tracks to downstream automation requirements, with panel and roll formats dominating high-volume assembly lines versus sheet formats for prototype and repair channels.
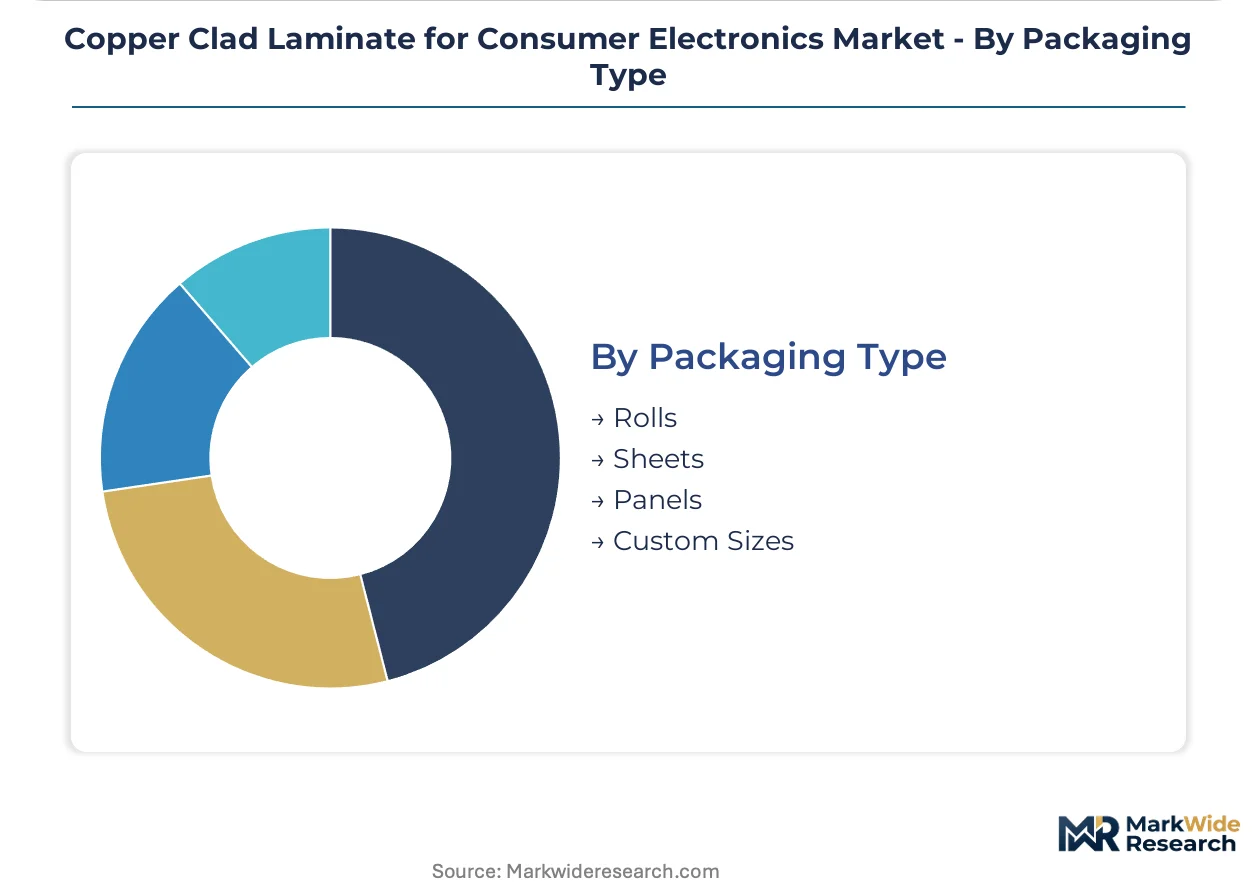
- Panels:Standard 48x36 inch formats optimize automated PCB fabrication line throughput. Taiwan and South Korea-based PCB fabricators pull panelized laminate on quarterly contract schedules.
- Rolls:Continuous copper-clad webs enable roll-to-roll processing for flexible circuit production in wearable and foldable smartphone programs. Guangdong flex circuit specialists are expanding roll-format offtake.
- Sheets:Cut-to-size formats serve prototype development and low-volume repair operations. Distributor inventories concentrate sheet stock in Shenzhen and Hong Kong logistics hubs.
- Custom Sizes:Non-standard dimensions accommodate specialized antenna-in-package modules and miniaturized wearable substrates. Qualification overhead limits custom formats to flagship OEM programs with dedicated laminate engineering support.
Panels absorb the bulk of laminate square-meter shipments; rolls are expanding most quickly alongside flex circuit adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper smelter capacity and resin precursor production anchor regional supply patterns for consumer electronics laminates. Electrodeposited foil output concentrates near Chinese and South Korean metal refining complexes. Epoxy resin feedstock flows from Japanese and South Korean chemical producers shape formulation access.
China
Guangdong province hosts integrated resin-to-foil laminate producers serving Shenzhen smartphone OEMs. SAMR enforces GB flame-retardant standards that extend qualification timelines for new material grades. Dongguan and Huizhou manufacturing clusters absorb the majority of domestic 5G substrate volume.
South Korea
Seoul-based smartphone OEMs drive millimeter-wave laminate demand for flagship antenna modules. MFDS oversees chemical safety in resin formulations bound for consumer devices. Gyeonggi-do and Incheon production zones concentrate high-frequency substrate qualification facilities.
Japan
Epoxy and polyimide precursor producers in Chubu and Kansai regions supply high-Tg resin systems globally. METI administers JIS certification for materials entering automotive-integrated consumer electronics. Osaka chemical complexes remain critical single-source exposure points for specialized formulations.
Taiwan
Taoyuan and Hsinchu science parks anchor PCB fabrication capacity pulling panelized laminate on quarterly schedules. The island's semiconductor ecosystem creates adjacent demand for high-reliability substrates. Kaohsiung port logistics handle roll-format imports for flexible circuit specialists.
India
Mumbai and Chennai production zones are emerging under PLI scheme incentives for smartphone assembly. BIS standards for electronic materials are tightening import compliance requirements. Gujarat and Tamil Nadu states are attracting laminate distributor inventory positions for regional aftermarket channels.
Copper Clad Laminate for Consumer Electronics Market Competitive Landscape
Global majors compete with regional champions across resin integration and foil bonding capabilities. The vendor base separates into integrated producers controlling precursor chemistry and specialized laminators focusing on high-frequency grades. Three archetypes dominate: vertically integrated resin-to-foil operators, high-frequency formulation specialists, and scale-driven contract suppliers. Competitive moves center on dual-source qualification partnerships and compressed design cycle collaboration with flagship OEMs.
Among China-based integrated producers, Kingboard Laminates Holdings Ltd. and Shengyi Technology Co., Ltd. exemplify the resin-captive archetype with Guangdong manufacturing footprints. Panasonic Holdings Corporation represents the premium formulation specialist tier, differentiated through halogen-free material positioning for EU-bound wearable programs. Taiwan Union Technology Corporation occupies a position bridging high-frequency specialization and scale supply into Taipei-based ODM channels.
| Leading Market Players |
|---|
| Kingboard Laminates Holdings Ltd. |
| Shengyi Technology Co., Ltd. |
| Nan Ya Plastics Corporation |
| Panasonic Holdings Corporation |
| Taiwan Union Technology Corporation |
| ITEQ Corporation |
| Doosan Corporation |
| Guangdong Chaohua Technology Co. Ltd. |
| Sytech Technology Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen-based smartphone OEMs anchor procurement volume and enforce contract-based long-term offtake structures across laminate tiers. Their dual-source mandates fragment pricing power while compressing margins on standardized FR-4 grades.
Pricing Analysis
Warranty and technical support bundling separates premium Low Loss formulations from unbundled standard-grade transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale. Cost compression in mid-tier reinforced substrates is intensifying because Guangdong producers are absorbing copper foil volatility. Contract manufacturers exhibit highest price sensitivity; flagship OEM direct programs show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for 5G substrate grades while distributor networks serve prototype and aftermarket repair segments. Resin precursor production draws from Japan and South Korea; electrodeposited foil output centers on China and South Korea. Epoxy and polyimide feedstock dependencies create single-source vulnerability for high-Tg formulations. Distribution runs through quarterly panel contracts with Taiwan PCB fabricators and roll-format offtake to Guangdong flex circuit specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is mounting as GB standard recertification timelines and dual-source mandates force subscale laminate producers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression in standard-grade reinforced laminates as Kingboard and Shengyi expand Guangdong resin-captive capacity. Defend positioning through halogen-free certification investment for EU-bound wearable programs and backward integration into copper foil bonding operations. Lock dual-source partnerships with Seoul and Shenzhen smartphone OEMs before qualification cycles harden. For New Entrants and Emerging Players: Aftermarket repair networks in Shenzhen trading hubs represent the most penetrable buyer archetype with minimal qualification overhead. Target halogen-free substrate supply for EU-bound wearable OEMs accelerating RoHS transitions. Enter through distributor inventory partnerships rather than direct mill relationships to bypass OEM certification barriers. For Investors and Strategic Acquirers: The window for entry favors integrated resin-to-foil operators with captive Guangdong manufacturing footprints. Mid-cap laminate specialists with SAMR GB certification pipelines offer acquisition appeal against a five-to-ten year horizon. Monitor MFDS chemical safety enforcement in South Korea as inflection indicator for regional formulation consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursor Production | Captive epoxy supply insulates Kingboard and Shengyi from Japanese and South Korean feedstock volatility. |
| Halogen-Free Formulation Certification | EU RoHS compliance unlocks premium positioning in wearable and tablet supply chains bound for member states. |
| Dual-Source Partnership Lock-In | Long-term offtake agreements with Foxconn and Pegatron secure volume visibility through OEM program cycles. |
| Roll-Format Capacity Expansion | Continuous web processing capability captures flexible circuit demand from foldable smartphone programs in Guangdong. |
| India PLI Scheme Localization | Mumbai and Chennai distributor positions anticipate laminate demand migration under smartphone assembly incentives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with laminate plant managers, smartphone OEM procurement leads, PCB fabrication engineers, and resin R&D directors combined with SAMR GB standard documentation, METI JIS certification databases, and copper smelter output disclosures. Bottom-up volume modeling triangulated against top-down electronics assembly forecasts.
Granularity-level modeling tracked resin formulation type, copper foil bonding process, end-use thermal budget, and regional manufacturing cluster across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by smartphone OEM program ramps and wearable form factor adoption. Forecast inputs included millimeter-wave antenna module penetration rates and EU RoHS scope expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LME copper benchmark volatility and China's dual carbon enforcement on resin energy accounting. Forecasts reflect documented assumptions regarding Shenzhen and Seoul OEM program timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Anti-Sulfur Chip Resistors Market
Passive And Interconnecting Electronic Components
Galvanic Isolation Market
Passive And Interconnecting Electronic Components
Global Fixed Resistor Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Flexible Printed Circuit Board (PCB) Market
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Miniature Ball Bearing Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Chip Capacitor Market
Passive And Interconnecting Electronic Components
Galvanic Isolators Market