
 Hybrid Capacitor Market | 2026-2036
Hybrid Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Capacitor Market Analysis
Buyer concentration in the automotive sector is expanding as electric vehicle manufacturers consolidate procurement around fewer qualified suppliers. KEMET Corporation leverages its vertical integration in tantalum and ceramic dielectrics to secure long-term supply agreements. LICAP Technologies specializes in lithium-ion capacitor architectures for heavy-duty transport applications. JTEKT Corporation anchors its position through proprietary electrode formulations developed for regenerative braking systems.
Hybrid capacitors combine electrostatic double-layer capacitance with battery-like faradaic charge transfer, achieving energy densities of 10-30 Wh/kg while maintaining cycle stability exceeding 100,000 charge events. Solid-state technology leads in reliability-critical deployments where electrolyte leakage risks disqualify conventional designs. Carbon-based architectures dominate cost-sensitive renewable energy buffering due to mature manufacturing pathways and abundant precursor supply. Nanostructured electrodes represent the fastest-growing technology segment as graphene and carbon nanotube composites narrow the energy density gap with lithium-ion cells.
Japan's PMDA and METI coordinate safety certification for medical and industrial hybrid capacitor installations, while China's NMPA enforces GB standards for electric vehicle energy storage components. The EU's REACH and RoHS frameworks restrict hazardous substances in electrode manufacturing, forcing reformulation of conventional electrolyte systems. Stakeholders must monitor evolving solid-state certification pathways and regional material compliance deadlines to preserve market access across manufacturing jurisdictions.
Market Dynamics
Automotive electrification is compressing qualification timelines for energy storage suppliers as OEMs consolidate procurement around vertically integrated capacitor manufacturers capable of meeting METI efficiency mandates and NMPA safety protocols simultaneously.
Growth Catalysts
- Japan's METI efficiency mandates:Tightening performance benchmarks for next-generation capacitors are forcing electrode formulation upgrades across industrial and transport applications.
- Heavy-duty transport electrification:Regenerative braking systems in electric buses and rail networks demand cycle-stable components exceeding 100,000 charge events.
- Graphene-carbon nanotube composites:Nanostructured electrodes are narrowing energy density gaps with lithium-ion cells in grid-scale renewable buffering installations.
Market Restraints
- Tantalum supply concentration:Captive mining operations in Central Africa and Southeast Asia expose dielectric material flows to geopolitical disruption and export restriction risk.
- REACH electrolyte reformulation costs:EU hazardous substance restrictions force replacement of conventional solvent systems with unproven solid-state alternatives.
- Lithium-ion cost compression:Battery pack price declines below $100 per kilowatt-hour threaten hybrid capacitor positioning in cost-sensitive stationary storage.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives create local assembly pathways for hybrid capacitor modules serving two-wheeler electrification.
- Medical device miniaturization:Implantable cardioverter-defibrillators and infusion pumps require solid-state components eliminating electrolyte leakage liability.
- Wind turbine pitch control systems:Cold-weather cycling specifications in North Sea and Baltic installations favor electrostatic-faradaic hybrid architectures over pure batteries.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in solid-state ion transport and nanostructured carbon synthesis commands premium compensation across Japan, South Korea, and Germany.
- Dual certification timelines:Simultaneous PMDA medical device and METI industrial safety approvals extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Capacitor Market |
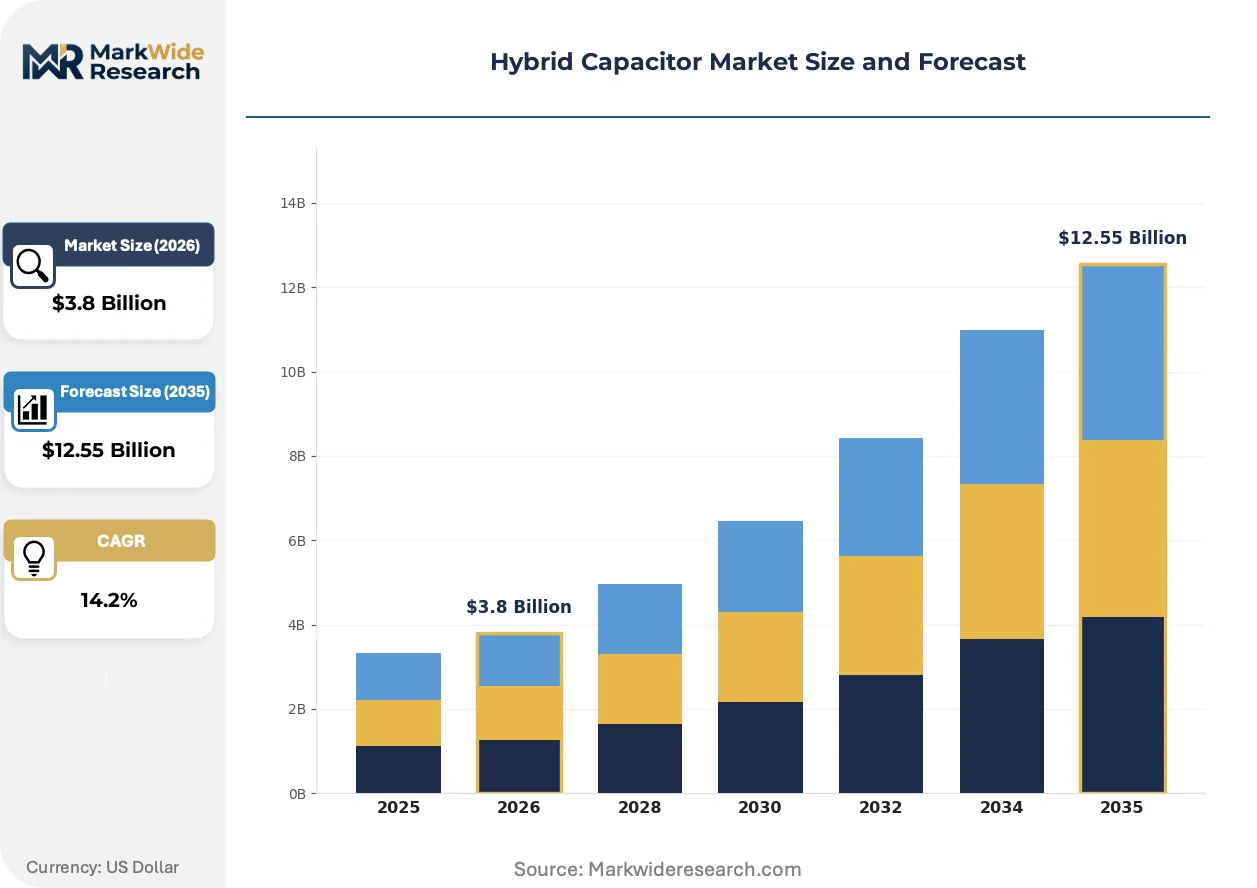
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Supercapacitor, Hybrid Supercapacitor, Thin Film Technology: Electrolytic, Carbon-based, Nanostructured, Solid-state End User: Consumer Electronics, Renewable Energy, Automotive, Industrial Applications Application: Energy Storage Systems, Power Backup, Electric Vehicles, Power Electronics |
| Companies Covered | KEMET Corporation, LICAP Technologies, Inc., JTEKT Corporation, Yunasko, SOCOMEC GROUP, TAIYO YUDEN CO., LTD., EVE Energy Co., Ltd., Electro Standards Laboratories, Vishay Intertechnology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Capacitor Market Emerging Trajectories
Solid-state hybrid architectures are compressing the traditional separation between electrostatic and electrochemical storage, forcing simultaneous advances in electrode nanostructuring and ceramic electrolyte processing.
Graphene-carbon nanotube composite electrodes are unifying double-layer capacitance with battery-like faradaic transfer in single-component designs. Electric vehicle manufacturers in Germany and Japan are qualifying these architectures for 48-volt mild-hybrid systems. The technology is unifying previously separate procurement categories for supercapacitors and lithium-ion cells into single-source supplier relationships.
China's NMPA is accelerating GB standard enforcement for electric vehicle energy storage components, mandating thermal runaway propagation resistance and cycle-life disclosure. Domestic cell manufacturers must submit electrode composition data and manufacturing traceability documentation. Heavy-duty commercial vehicle segments face the steepest compliance burdens as NMPA aligns with UN GTR battery safety protocols.
Buyer concentration among top-tier automotive OEMs is compressing supplier qualification cycles from 36 months to 18 months. Tier-1 component distributors are ceding direct relationships to captive procurement arms at Volkswagen, Toyota, and BYD. South Korea's electric bus manufacturers demonstrate the most aggressive supplier consolidation, with Seoul Metro and Gyeonggi Province operators mandating single-source capacitor module contracts.
Hybrid Capacitor Market Segmentation
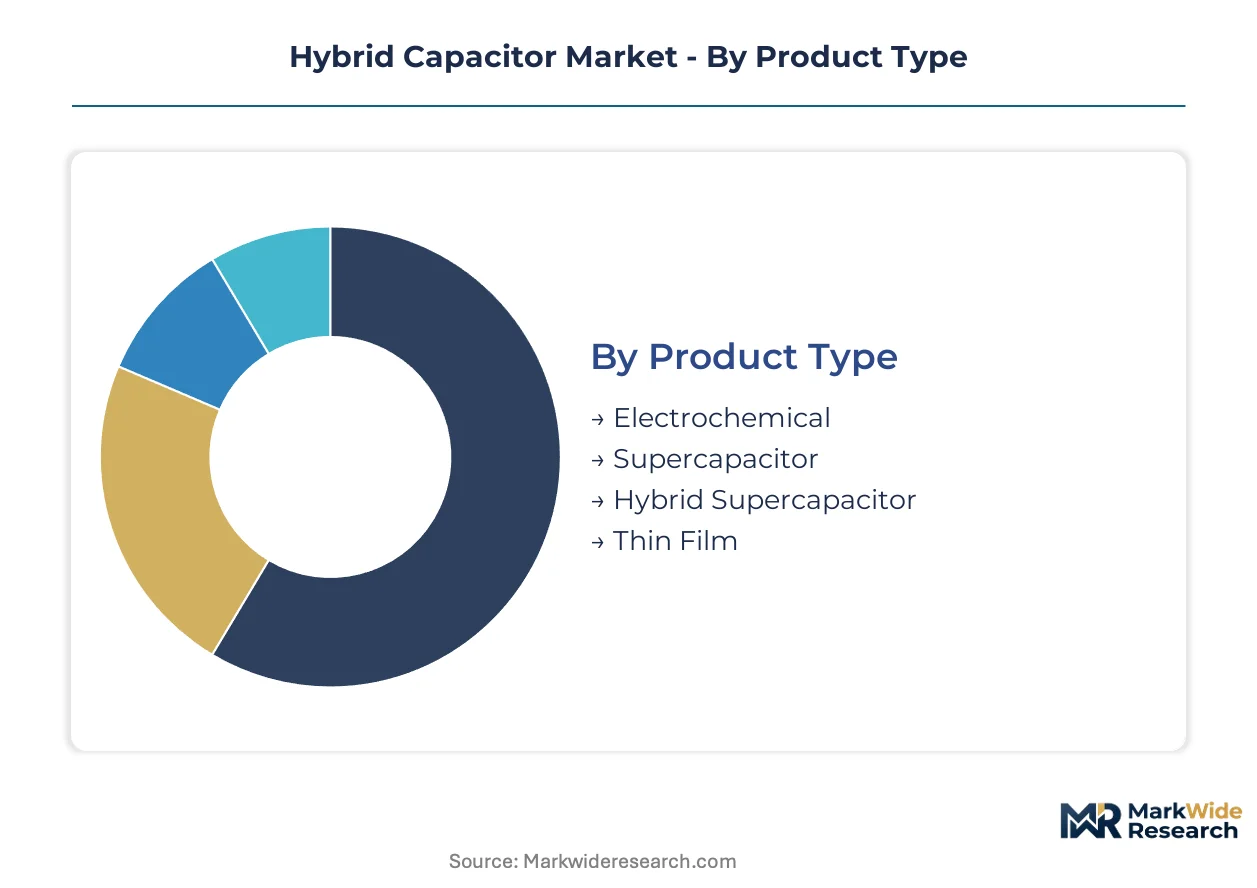
Hybrid capacitor procurement patterns diverge sharply across application environments, with automotive and grid-scale buyers demanding validated cycle-life data while consumer electronics prioritizes form-factor miniaturization. Segment boundaries are blurring as nanostructured electrodes enable single-component designs that previously required separate supercapacitor and battery procurement.
Product Type:
Supply concentration for dielectric materials and electrode substrates determines which architectures achieve production scale first.
- Hybrid Supercapacitor:Combines electrostatic double-layer capacitance with faradaic charge transfer in unified electrode designs. Automotive 48-volt mild-hybrid systems in Germany and Japan are consolidating procurement around these architectures to replace separate supercapacitor and lithium-ion sourcing.
- Supercapacitor:Pure electrostatic storage achieves power densities exceeding batteries by an order of magnitude but sacrifices energy density. Regenerative braking systems in South Korean electric bus fleets and Seoul Metro rail networks specify these for cycle stability exceeding 100,000 events.
- Electrochemical:Battery-like redox reactions dominate stationary grid buffering where energy density requirements exceed 20 Wh/kg.
- Thin Film:Solid-state layered constructions serve implantable medical devices and miniaturized consumer electronics where electrolyte leakage liability is unacceptable.
Hybrid Supercapacitor absorbs the bulk of installed capacity; Thin Film is expanding most quickly.
Technology:
Cost tier stratification separates mature manufacturing pathways from emerging solid-state platforms requiring capital-intensive ceramic processing equipment.
- Solid-state:Ceramic electrolyte architectures eliminate leakage risks for medical implants and aerospace deployments. Japan's PMDA and METI coordinate safety certification timelines that extend product launches by 18-24 months for these designs.
- Nanostructured:Graphene-carbon nanotube composites narrow energy density gaps with lithium-ion cells. Wind turbine pitch control systems in North Sea and Baltic installations favor these for cold-weather cycling specifications.
- Carbon-based:Activated carbon electrodes leverage mature precursor supply chains for cost-sensitive renewable energy buffering.
- Electrolytic:Liquid electrolyte systems face REACH reformulation mandates in Europe forcing solvent system replacements.
Carbon-based technology holds the largest production footprint; Nanostructured platforms are climbing the fastest.
End User:
Volume concentration among top-tier automotive OEMs compresses supplier qualification cycles and consolidates procurement around vertically integrated manufacturers.
- Automotive:Electric vehicle powertrain integration demands components meeting simultaneous METI efficiency mandates and NMPA thermal runaway protocols. BYD, Toyota, and Volkswagen captive procurement arms are displacing Tier-1 distributors.
- Renewable Energy:Grid-scale storage and wind turbine systems require cold-weather cycling performance. China's state grid operators and European offshore wind developers specify hybrid architectures over pure batteries for frequency regulation.
- Industrial Applications:Factory automation and uninterruptible power systems favor cycle-stable components for high-duty cycling environments.
- Consumer Electronics:Miniaturization pressures drive demand for thin-film solid-state formats in wearable and portable device segments.
Automotive absorbs the bulk of installed capacity; Renewable Energy is gaining share fastest.
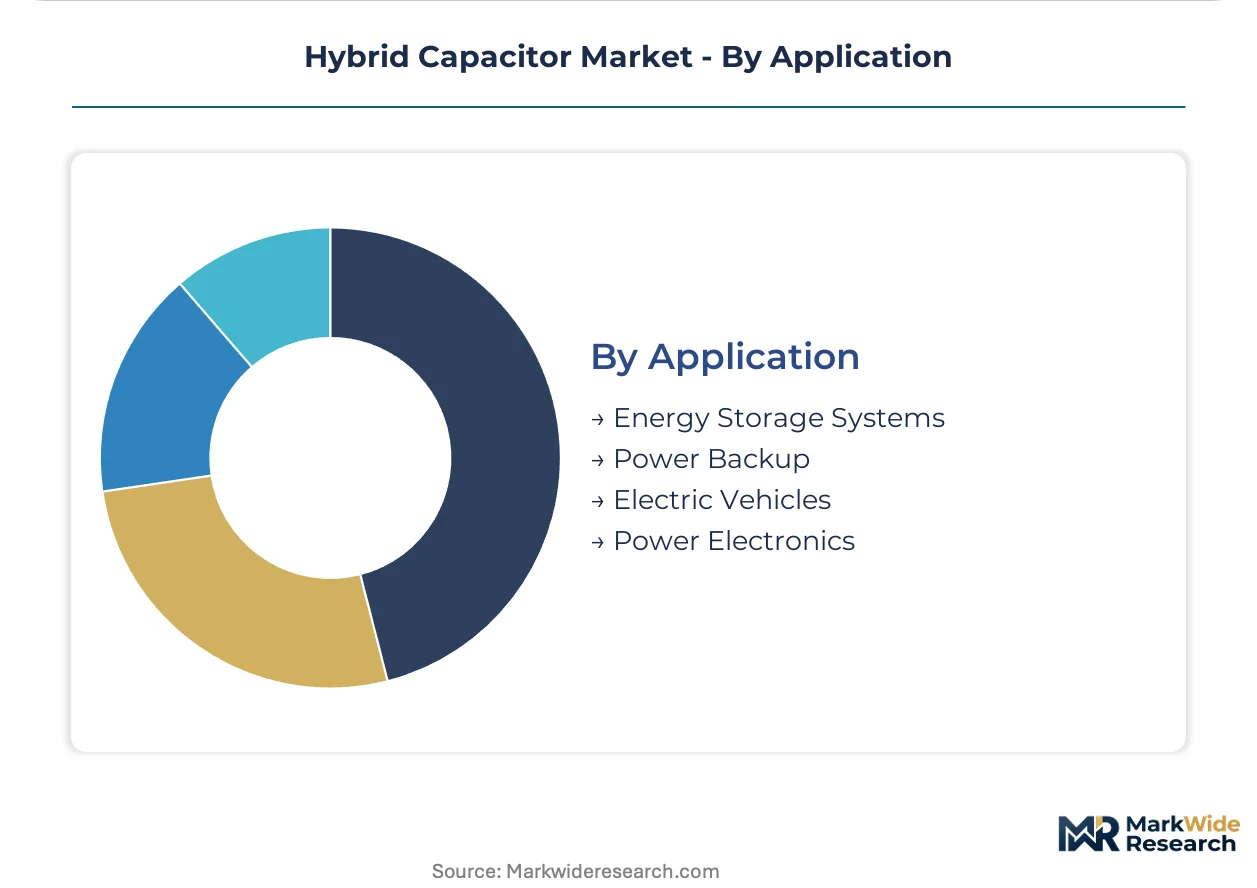
Application:
Customer type divergence separates specification-heavy transport electrification from price-sensitive stationary storage procurement.
- Electric Vehicles:Heavy-duty commercial vehicle segments face steep compliance burdens as China's NMPA aligns GB standards with UN GTR battery safety protocols. Regenerative braking and 48-volt mild-hybrid systems dominate demand composition.
- Energy Storage Systems:Grid-scale renewable buffering favors carbon-based architectures with mature manufacturing pathways and abundant precursor supply.
- Power Backup:Industrial uninterruptible power supply installations prioritize cycle stability over energy density.
- Power Electronics:Voltage regulation and smoothing applications in telecommunications infrastructure specify hybrid designs for rapid charge acceptance.
Electric Vehicles absorbs the bulk of installed capacity; Energy Storage Systems is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters in automotive electrification corridors where OEM procurement arms consolidate supplier relationships around vertically integrated capacitor manufacturers. Japan, China, Germany, South Korea, and the United States anchor distinct regional ecosystems shaped by divergent regulatory timelines and industrial cluster specialization.
Japan
Automotive OEM captive procurement and medical device miniaturization drive specification-heavy demand for solid-state architectures. METI efficiency mandates and PMDA safety certification coordinate 18-24 month product launch timelines for ceramic electrolyte designs. The Kanto region surrounding Tokyo concentrates electrode formulation R&D and regenerative braking system integration for Toyota and Nissan supply chains.
China
Electric vehicle powertrain integration and grid-scale renewable buffering absorb the bulk of regional capacity expansion. NMPA enforcement of GB standards for thermal runaway propagation resistance and cycle-life disclosure tightens compliance burdens on heavy-duty commercial vehicle segments. The Yangtze River Delta cluster around Shanghai and Suzhou hosts captive procurement operations for BYD and state grid operators.
Germany
48-volt mild-hybrid system qualification and wind turbine pitch control specifications favor nanostructured electrode architectures. REACH electrolyte reformulation mandates force solvent system replacements ahead of solid-state certification pathways. Bavaria's industrial corridor around Munich anchors supplier development programs for Volkswagen Group's consolidated procurement arm.
South Korea
Electric bus fleet electrification and Seoul Metro rail network modernization specify cycle-stable components exceeding 100,000 charge events. Domestic manufacturers face compressed qualification timelines as public transit operators mandate single-source capacitor module contracts. The Busan-Ulsan manufacturing belt concentrates heavy-duty transport system integration and electrode substrate processing.
United States
Medical implant miniaturization and telecommunications infrastructure voltage regulation sustain demand for thin-film solid-state formats. FDA coordination with industrial safety frameworks shapes certification timelines for implantable cardioverter-defibrillator applications. The Pacific Northwest cluster around Portland and Seattle hosts wind turbine system integrators specifying cold-weather cycling performance for North Sea export markets.
Hybrid Capacitor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue nanostructured electrode specialization and solid-state ceramic processing. The supplier base stratifies across three maturity tiers: legacy dielectric manufacturers with backward integration into tantalum supply, lithium-ion capacitor specialists serving heavy-duty transport, and graphene-composite startups narrowing energy density gaps. Consolidation pressures intensify as automotive OEMs displace Tier-1 distributors with captive procurement arms. Dominant competitive moves include strategic partnerships for electrode material supply security and technology licensing for solid-state electrolyte formulations.
Among Japan-based manufacturers, KEMET Corporation and JTEKT Corporation exemplify contrasting strategic positions. KEMET represents the backward-integrated archetype with captive control over tantalum and ceramic dielectric supply chains. JTEKT occupies a specialization tier focused on proprietary electrode formulations for regenerative braking applications. LICAP Technologies, a lithium-ion capacitor specialist, anchors the heavy-duty transport segment with architectures designed for cycle stability in commercial vehicle powertrains. These three companies illustrate how geographic clustering around distinct regulatory frameworks—METI efficiency mandates, PMDA medical certification, and NMPA safety protocols—shapes competitive positioning without requiring uniform strategic responses.
| Leading Market Players |
|---|
| KEMET Corporation |
| LICAP Technologies, Inc. |
| JTEKT Corporation |
| Yunasko |
| SOCOMEC GROUP |
| TAIYO YUDEN CO., LTD. |
| EVE Energy Co., Ltd. |
| Electro Standards Laboratories |
| Vishay Intertechnology, Inc. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and Japan anchor electrode material supply chains, translating state-supported capacity expansion into pricing discipline that resists spot-market volatility. Their captive financing insulates long-term contract structures from commodity swings affecting tantalum and carbon precursor markets.
Pricing Analysis
High-volume automotive procurement absorbs margin compression while medical-grade solid-state capacitors sustain premium positioning. Three-tier pricing structure across automotive, industrial, and medical certification levels segments buyers by thermal runaway compliance burden. Pricing pressure stems from lithium-ion battery cost compression below utility-scale storage thresholds. Renewable energy developers exhibit highest price sensitivity; implantable device manufacturers show lowest.
Supply Chain Analysis
Electrochemist talent scarcity in Japan, South Korea, and Germany constrains electrode formulation throughput at specialized manufacturing clusters. Tantalum sourcing concentrates in Central African mining operations and Southeast Asian processing facilities. Carbon precursor supply draws from abundant biomass and petrochemical feedstocks. Single-source vulnerability pervades ceramic electrolyte substrate supply. Distribution runs through captive procurement arms at Toyota, BYD, and Volkswagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation functions as a forced exit mechanism, eliminating capacitor suppliers incapable of simultaneous METI and NMPA certification.
For Market Incumbents: Cement supply security through backward integration into tantalum and ceramic dielectric production, insulating against Central African export disruptions. Accelerate solid-state electrolyte R&D to capture medical device miniaturization demand ahead of 18-24 month PMDA certification cycles. Graphene-carbon nanotube composite specialists threaten premium positioning in 48-volt mild-hybrid architectures. For New Entrants and Emerging Players: Launch via direct partnerships with South Korean electric bus fleet operators mandating single-source capacitor module contracts. India's PLI scheme for advanced chemistry cells offers localized assembly pathways for two-wheeler electrification without incumbent qualification burdens. Target wind turbine pitch control specifications in North Sea and Baltic installations favoring cold-weather cycling performance. For Investors and Strategic Acquirers: NMPA acceleration of GB standard enforcement is the leading indicator that regulatory compliance scale will separate viable acquisition targets from stranded assets. Five-to-ten year viability hinges on captive electrode material supply and multi-jurisdiction certification capability. Acquisition target archetype: lithium-ion capacitor specialists with heavy-duty transport validation and incomplete vertical integration. Monitor METI efficiency mandate tightening as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tantalum Supply | Captive mining access insulates KEMET and JTEKT from Central African geopolitical disruption. |
| Solid-State Electrolyte Certification Investment | PMDA-METI coordinated timelines extend product launches but lock out liquid-electrolyte competitors. |
| Graphene-Carbon Nanotube Composite Scale-Up | Nanostructured electrode production narrows energy density gaps with lithium-ion cells for Volkswagen qualification. |
| Single-Source Procurement Contract Capture | Seoul Metro and Gyeonggi Province mandates displace Tier-1 distributors with direct manufacturer relationships. |
| Dual-Jurisdiction Compliance Infrastructure | Simultaneous METI efficiency and NMPA thermal runaway certification preserves access to Toyota and BYD supply chains. |
Methodological Framework
Document review covered customs trade data for tantalum and carbon precursor flows, SEC filings from dielectric manufacturers, METI efficiency mandate documentation, and NMPA GB standard enforcement records, complemented by interviews with electrode formulation chemists, automotive Tier-1 procurement directors, wind turbine system integrators, and medical device regulatory affairs specialists. Secondary validation drew from patent filings for graphene-carbon nanotube composite architectures, PMDA medical device registration databases, and REACH electrolyte reformulation compliance disclosures. Bottom-up production capacity estimates and top-down demand absorption models were triangulated against qualification timeline data from Toyota, BYD, and Volkswagen captive procurement arms.
Installed capacity projections and value trajectories across the analysis window reflect segmentation by product type, technology platform, end-user industry, and application environment. Modeled dimensions included solid-state versus liquid-electrolyt architectures, nanostructured versus carbon-based electrode compositions, and automotive versus renewable energy versus medical device demand clusters. CAGRs were derived from regression analysis of historical qualification cycle compression and OEM procurement consolidation patterns. Forecast inputs incorporated METI mandate implementation schedules, NMPA thermal runaway protocol alignment with UN GTR standards, and electrochemist labor market tightness indices for Japan, South Korea, and Germany.
Tantalum supply disruption, REACH electrolyte reformulation cost overruns, and lithium-ion battery price trajectories below stationary storage parity are the dominant revision risks for hybrid capacitor demand forecasts. Forecasts reflect documented assumptions regarding OEM procurement consolidation velocity and certification timeline stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Integrated Passive Devices (Ipds) Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Plastic Film Capacitors Market
Passive And Interconnecting Electronic Components
Discrete Assortment Kits Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Soft Ferrite Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market
Passive And Interconnecting Electronic Components
Beryllium Copper for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market