
 Galvanic Isolators Market | 2026-2036
Galvanic Isolators Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanic Isolators Market Analytics
China's Pearl River Delta manufacturing belt is reconfiguring regional supply dynamics for magnetic and capacitive isolation components. Texas Instruments leverages its fab network to sustain high-volume digital isolator output for industrial automation clients. Infineon Technologies anchors European demand through specialized automotive-qualified isolation products. Pepperl+Fuchs dominates hazardous-environment applications with intrinsically safe isolation interfaces.
Galvanic isolators are passive or active electrical devices that block DC current flow between interconnected metallic systems while permitting AC and transient signals to pass, typically rated for breakdown voltages from 500 V to 5 kV depending on marine or industrial grade. They prevent electrolytic corrosion in bonded metal structures by eliminating stray current paths, serving critical protection roles in shore power connections, offshore platforms, and cathodic protection systems. Digital isolators lead product-type margins due to integration with silicon-based signal chains, while transformer isolation retains share in high-voltage renewable energy inverters where galvanic separation must withstand sustained kilovolt stresses. Optical isolation competes most intensely in telecommunications data communication links where latency budgets constrain magnetic alternatives.
IEC 60364-5-54 and ABYC E-11 standards shape marine product specifications across European and North American markets, with China's GB/T standards adding conformance layers for export-oriented manufacturers. The EU's F-Gas Regulation indirectly pressures isolation component sealing integrity in hermetically protected switchgear. OSHA electrical safety mandates in US industrial settings drive periodic replacement cycles for aged isolation barriers. Stakeholders must monitor evolving semiconductor content rules and traceability requirements that could reroute procurement away from non-compliant assembly sources.
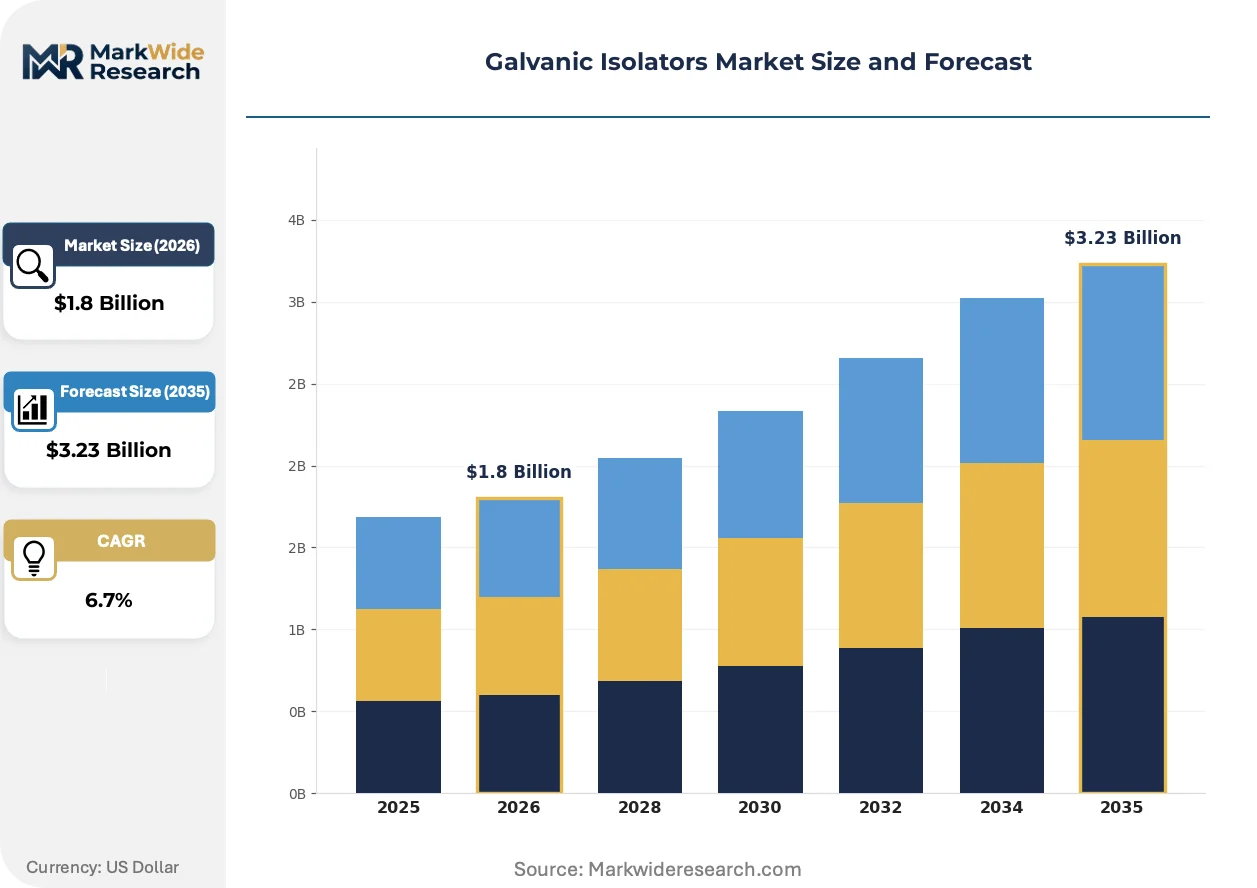
Market Dynamics
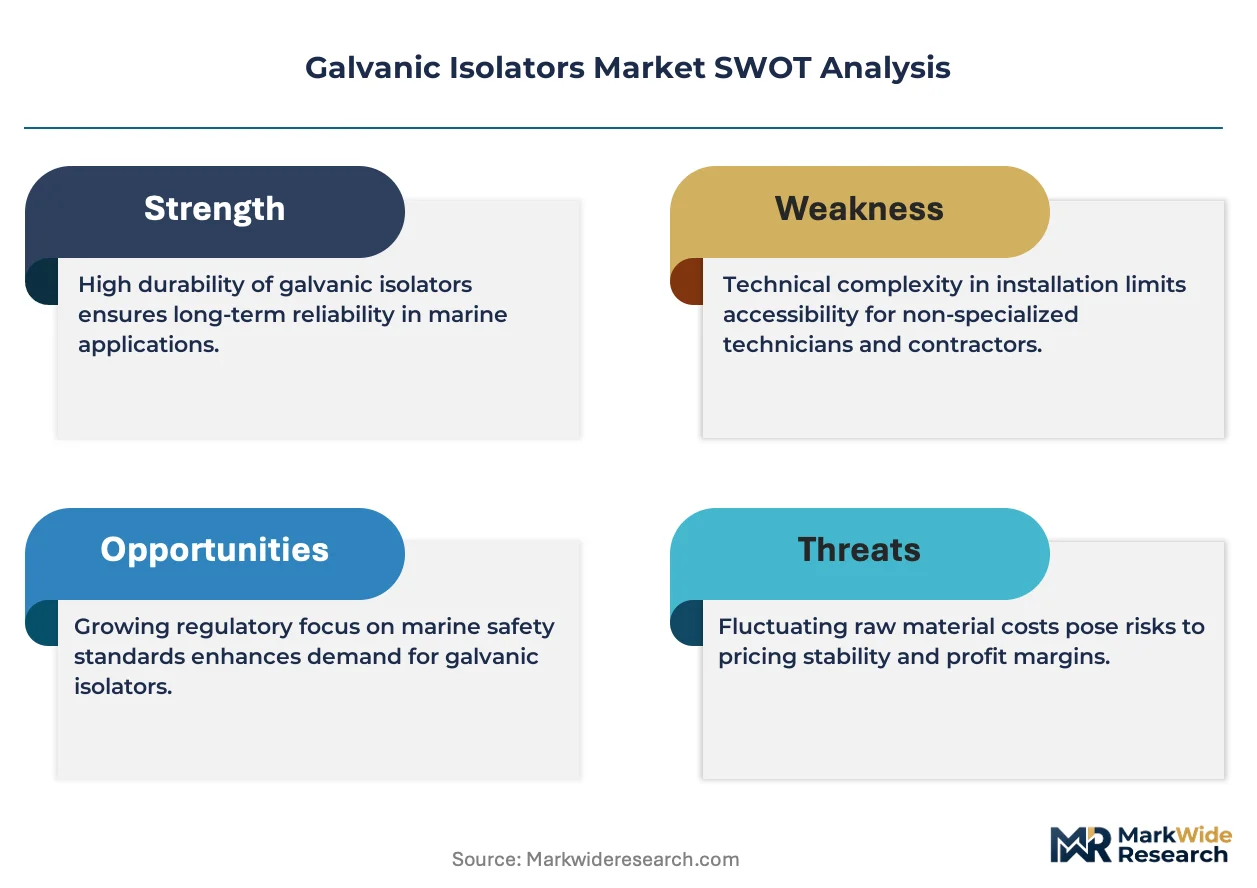
Marine fleet electrification and industrial automation retrofits are compressing replacement cycles for galvanic isolation hardware as operators confront accelerated corrosion risks from higher-voltage shore power systems.
Growth Catalysts
- ABYC E-11 revisions:Stricter shore power safety mandates in US recreational marine markets force wholesale replacement of legacy isolation barriers on vessels over 20 meters.
- Industrial automation corridors:Germany's Ruhr manufacturing belt deploys capacitive isolators at scale for PLC signal conditioning in process control networks.
- Silicon carbide integration:Wide-bandgap semiconductors enable compact digital isolators handling 150°C ambient temperatures in electric vehicle charging infrastructure.
Market Restraints
- Epoxy resin cost volatility:Potting compounds for hermetic sealing face price pressure from petrochemical feedstock fluctuations, squeezing mid-tier manufacturer margins.
- Transformer core supply concentration:Nanocrystalline magnetic material production clusters in Japanese specialty steel foundries, creating single-source vulnerability for high-voltage isolation units.
- Optical isolation bandwidth ceilings:LED-to-photodiode latency limits constrain data rates below 50 Mbps, excluding telecom backhaul applications from galvanic isolator addressable demand.
Strategic Opportunities
- Offshore wind expansion:China's Jiangsu coastal province mandates galvanic separation in turbine nacelle power conversion systems, opening specialized marine-grade certification pathways.
- EU F-Gas Regulation:Hermetic sealing requirements for switchgear containing fluorinated gases drive demand for vacuum-impregnated isolation barriers in European utility infrastructure.
- Condition-based monitoring convergence:Integration of isolation health sensors with industrial IoT platforms enables predictive replacement contracts for critical cathodic protection systems.
Industry Challenges
- IEC 62368-1 certification timelines:Audio-video and IT equipment safety standard harmonization delays product launches by 8-14 months for multimedia isolation interfaces.
- Legacy vessel electrical retrofits:Space-constrained engine rooms on pre-2010 commercial fleets resist physical accommodation of modern isolation transformer footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanic Isolators Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Isolators, Integrated Isolators, Modular Isolators, Digital Isolators Technology: Capacitive Isolation, Optical Isolation, Magnetic Isolation, Transformer Isolation End User: Marine, Industrial, Renewable Energy, Telecommunications Application: Power Distribution, Signal Regulation, Data Communication, Equipment Isolation |
| Companies Covered | Texas Instruments, Broadcom, Infineon Technologies, STMicroelectronics, Analog Devices, ROHM Semiconductor, Schneider Electric, Pepperl+Fuchs, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanic Isolators Market Evolving Landscape
Capacitive and magnetic coupling architectures are diverging as application-specific performance requirements harden, while regulatory pressure on hermetic integrity intensifies component-level engineering investment.
Monolithic CMOS-based digital isolators leveraging on-chip transformer windings are rendering obsolete discrete optocoupler assemblies in motor drive control circuits. Industrial automation OEMs in automotive manufacturing plants adopt these devices for 3-phase inverter gate drives. The shift compresses bill-of-materials count by 60% while eliminating LED aging failure modes.
REACH substance restrictions on halogenated flame retardants compel reformulation of potting compounds used in high-voltage isolation barriers. Compound suppliers in the EU must certify new epoxy formulations through ECHA notification procedures. Marine certification bodies ABYC and DNV are updating test protocols to verify long-term thermal cycling performance of replacement materials.
Shipyard procurement departments now specify certified isolator assemblies rather than component-level sourcing, consolidating vendor relationships. This specification tightening favors integrated subsystem suppliers over discrete component distributors. The pattern is most pronounced in South Korean shipbuilding clusters where Hyundai Heavy Industries and Samsung Heavy Industries enforce unified electrical standards across subcontractor tiers.
Galvanic Isolators Market Segmentation
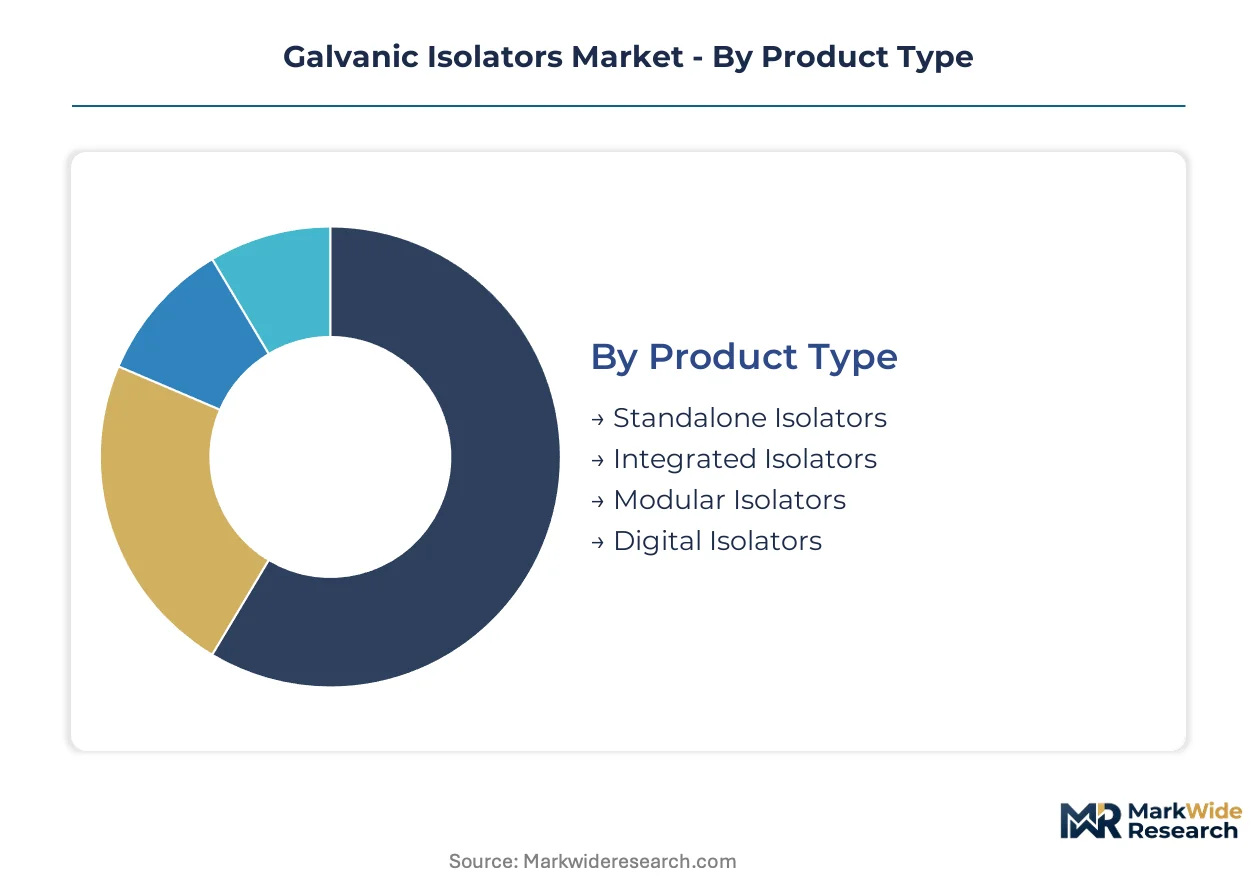
Galvanic isolator procurement patterns diverge sharply across product architectures and deployment contexts. Segment-specific replacement cycles and certification requirements create distinct competitive arenas for component suppliers and system integrators.
Product Type:
Replacement velocity separates this category, with integrated and digital variants cycling faster than standalone units due to semiconductor content obsolescence.
- Standalone Isolators:Discrete barrier devices housed in dedicated enclosures, typically deployed in legacy marine shore power installations and heavy industrial cathodic protection systems. Demand concentrates in US Gulf Coast shipyards confronting ABYC E-11 retrofit mandates, though physical footprint constraints slow adoption on space-limited vessels.
- Digital Isolators:CMOS-based monolithic devices integrating isolation barriers with signal conditioning logic. Germany's Ruhr industrial automation corridor deploys these at scale for PLC networks, driven by silicon carbide compatibility requirements in high-temperature motor drive applications.
- Integrated Isolators:Subsystem-level assemblies combining isolation barriers with power conversion or filtering stages. Chinese shipbuilding clusters specify these for offshore wind turbine nacelles to reduce installation complexity.
- Modular Isolators:Field-replaceable card-based units designed for rack-mounted industrial control systems. Process manufacturing facilities in Japan's Kansai chemical belt favor these for maintenance accessibility.
Standalone isolators anchor the volume base while digital isolators gain share at the steepest rate.
Technology:
Cost-to-performance ratios stratify sharply, with magnetic and transformer architectures commanding premium positioning against capacitive alternatives.
- Magnetic Isolation:Transformer-coupled architectures using nanocrystalline cores for high-voltage renewable energy inverters. Japanese specialty steel foundries concentrate supply of core materials, creating procurement vulnerability for European wind turbine OEMs.
- Capacitive Isolation:Silicon dioxide barrier layers fabricated through standard CMOS processes. Texas Instruments leverages fab scale to supply industrial automation clients with cost-optimized variants for sub-kilovolt signal conditioning.
- Optical Isolation:LED-to-photodiode coupling for telecommunications data links. Latency ceilings below 50 Mbps exclude these from 5G backhaul applications, constraining addressable demand to legacy infrastructure.
- Transformer Isolation:Wound magnetic components rated for sustained kilovolt stresses in utility-scale power distribution. EU F-Gas Regulation hermetic sealing requirements drive specification tightening for switchgear applications.
Transformer isolation commands the highest unit economics while capacitive isolation expands most quickly through semiconductor integration.
End User:
Customer procurement sophistication varies, with marine and renewable energy buyers imposing the most stringent certification requirements.
- Marine:Shore power and cathodic protection systems for commercial and recreational vessels. ABYC E-11 and IEC 60364-5-54 compliance mandates force replacement of legacy isolation barriers on US and European fleets exceeding 20 meters.
- Industrial:Process control networks and manufacturing automation infrastructure. Germany's automotive manufacturing plants specify digital isolators for 3-phase inverter gate drives to achieve bill-of-materials compression.
- Renewable Energy:Wind turbine power conversion and solar inverter galvanic separation. China's Jiangsu coastal province mandates certified isolator assemblies in offshore wind installations.
- Telecommunications:Data center power distribution and network equipment isolation. Optical isolation retains position in legacy copper infrastructure despite bandwidth limitations for fiber-dominant architectures.
Industrial end users provide the steadiest replacement demand while renewable energy installations scale fastest.
Application:
Functional criticality determines specification intensity, with power distribution applications tolerating the least failure risk.
- Power Distribution:Galvanic separation in utility infrastructure and industrial feeder systems. OSHA electrical safety mandates in US industrial settings drive periodic replacement cycles for aged isolation barriers.
- Signal Regulation:PLC input conditioning and process control loop isolation. South Korean shipbuilding clusters specify certified assemblies rather than component sourcing, consolidating vendor relationships.
- Data Communication:High-speed serial link isolation for industrial Ethernet and telecommunications. REACH substance restrictions on halogenated flame retardants compel reformulation of potting compounds for these lower-voltage applications.
- Equipment Isolation:Machine-level protection for rotating equipment and motor drives. Condition-based monitoring convergence enables predictive replacement contracts through industrial IoT platform integration.
Power distribution applications dominate absolute unit volume while equipment isolation climbs fastest through predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel foundries in Japan concentrate nanocrystalline core supply for high-voltage transformer isolation, while CMOS fabrication networks in the United States and Germany scale capacitive barrier production for industrial automation clients.
United States
OSHA electrical safety mandates and ABYC E-11 shore power revisions force replacement cycles across Gulf Coast shipyards and Great Lakes marina infrastructure. The Department of Transportation coordinates with maritime safety boards on vessel electrification standards. Houston's energy corridor deploys certified isolator assemblies for offshore platform cathodic protection retrofits.
Germany
Ruhr manufacturing belt demand for PLC signal conditioning and automotive inverter gate drives absorbs substantial digital isolator volume. ECHA REACH substance restrictions on halogenated flame retardants compel potting compound reformulation for hermetic sealing compliance. Bavaria's industrial automation corridor integrates silicon carbide-compatible isolation devices into electric vehicle charging infrastructure.
China
Jiangsu coastal province mandates galvanic separation in offshore wind turbine nacelles while Pearl River Delta manufacturing clusters reconfigure supply chains for magnetic and capacitive components. GB/T standards add conformance layers for export-oriented isolator manufacturers. Shanghai's shipbuilding ports specify integrated isolator subsystems to reduce installation complexity in new vessel construction.
Japan
METI industrial efficiency programs accelerate automation retrofit cycles in Kansai chemical belt process control networks. JIS standards govern isolation barrier performance in utility-scale power distribution equipment. Nagoya's automotive manufacturing plants adopt monolithic CMOS isolators for 3-phase motor drive applications, compressing bill-of-materials counts.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries enforce unified electrical standards across shipbuilding subcontractor tiers, consolidating vendor relationships for certified isolator assemblies. MFDS-equivalent maritime safety coordination aligns with international IEC certification protocols. Busan-Ulsan shipbuilding clusters now specify subsystem-level sourcing rather than discrete component procurement.
Galvanic Isolators Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies between semiconductor fabs with captive isolation IP and discrete magnetic component houses serving legacy industrial accounts. Three archetypes dominate: CMOS-integrated digital isolator suppliers, transformer-coupled high-voltage specialists, and hazardous-environment interface providers. Capacity expansion in wide-bandgap-compatible fabrication and strategic partnerships for hermetic sealing certification represent the dominant competitive vectors.
Among North American semiconductor houses, Texas Instruments and Analog Devices occupy positions scaling capacitive isolation through fab network utilization. Infineon Technologies anchors European demand through automotive-qualified product lines. Pepperl+Fuchs exemplifies the hazardous-environment specialist archetype, sitting within intrinsically safe interface applications where certification depth creates positioning defensibility.
| Leading Market Players |
|---|
| Texas Instruments |
| Broadcom |
| Infineon Technologies |
| STMicroelectronics |
| Analog Devices |
| ROHM Semiconductor |
| Schneider Electric |
| Pepperl+Fuchs |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
Japanese specialty steel foundries concentrate nanocrystalline core production for high-voltage transformer isolation, anchoring margin capture in the premium tier while mid-market manufacturers absorb epoxy resin cost volatility from petrochemical feedstock fluctuations.
Pricing Analysis
ABYC E-11 and IEC 60364-5-54 certification requirements dictate the pricing tier structure across marine and industrial segments. Three-tier pricing stratifies across marine-grade certified assemblies, industrial automation-qualified units, and economy-tier replacement components. Price differentiation centers on hermetic sealing integrity and silicon carbide temperature tolerance ratings. Cost compression in mid-tier standalone isolators is intensifying because REACH-compliant potting compound reformulation adds ECHA notification overhead. Marine fleet operators exhibit the highest price sensitivity due to legacy vessel space constraints forcing custom engineering, while offshore wind developers accept premium positioning for integrated subsystem sourcing.
Supply Chain Analysis
Epoxy resin feedstocks and nanocrystalline magnetic materials draw from Japanese specialty steel foundries, German industrial chemical producers, and Chinese petrochemical refineries. Raw material dependencies include potting compound formulations, transformer core laminations, and CMOS wafer substrates. Single-source vulnerability concentrates in Japanese nanocrystalline core supply for high-voltage renewable energy inverters. Distribution runs through certified subsystem suppliers in South Korean shipbuilding clusters rather than discrete component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across certification-tier gaps as marine fleet electrification and industrial automation retrofits create specialized demand niches requiring distinct technical competencies.
For Market Incumbents: Build certification depth moats around ABYC E-11 and IEC 62368-1 compliance pathways to delay competitive entry by 8-14 months. Deepen backward integration into hermetic sealing compound formulation to capture REACH compliance value. Consolidate channel control through subsystem-level assembly partnerships with Hyundai Heavy Industries and Samsung Heavy Industries procurement tiers. Threat vector: CMOS-based digital isolators displacing discrete optocoupler assemblies in motor drive applications. For New Entrants and Emerging Players: Establish a beachhead in condition-based monitoring convergence for predictive replacement contracts in cathodic protection systems. Target the EU F-Gas Regulation hermetic sealing upgrade cycle in utility-scale switchgear as the most penetrable near-term entry point. White-space exists in silicon carbide-compatible isolation devices for electric vehicle charging infrastructure above 150°C ambient tolerance. Go-to-market leverage: industrial IoT platform integration partnerships with predictive maintenance software vendors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated isolator subsystems due to hermetic sealing certification infrastructure requirements. Long-term viability favors semiconductor fabs with captive isolation IP over discrete magnetic component houses tethered to legacy industrial accounts. Acquisition target archetype: hazardous-environment interface specialists with intrinsically safe certification depth creating positioning defensibility. Signal to monitor: consolidation of vendor relationships in South Korean shipbuilding clusters toward subsystem-level sourcing mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hermetic Sealing Certification Investment | ECHA REACH compliance for potting compounds captures EU F-Gas Regulation upgrade demand in utility switchgear. |
| Silicon Carbide Compatibility Development | 150°C temperature tolerance unlocks electric vehicle charging infrastructure contracts in Bavaria's automation corridor. |
| Subsystem-Level Integration Partnership | Certified assembly relationships with Hyundai Heavy Industries consolidate procurement tiers in Busan-Ulsan clusters. |
| Condition-Based Monitoring Platform Integration | Industrial IoT sensor fusion enables predictive replacement contracts for critical cathodic protection systems. |
| Backward Integration into Core Materials | Captive nanocrystalline supply reduces Japanese foundry dependency for European wind turbine OEMs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of IEC certification databases, ABYC technical committee minutes, semiconductor foundry capacity disclosures, and marine classification society protocols. Primary interviews engaged electrical system engineers at shipyards, cathodic protection specialists at offshore platform operators, procurement directors at wind turbine OEMs, and regulatory affairs managers at isolation component manufacturers. Secondary validation drew from customs trade data for magnetic core materials, SEC filings of listed semiconductor houses, ECHA substance restriction notifications, and shipbuilding order books from Clarksons Research. Bottom-up unit economics triangulate against top-down market size estimates across product architectures.
Forecast inputs incorporate segmentation dimensions spanning isolation technology type, voltage rating tier, end-use industry vertical, certification standard cluster, and regional regulatory framework. CAGRs derive from replacement cycle compression analysis in marine electrification retrofits and industrial automation corridors, cross-referenced against semiconductor content trajectory in digital isolator adoption. Industry-specific modeling variables include ABYC E-11 revision implementation timelines, EU F-Gas Regulation hermetic sealing phase-in schedules, and silicon carbide temperature tolerance migration curves across the projection horizon.
Sensitivities concentrate around IEC 62368-1 certification timeline delays, nanocrystalline core supply disruptions from Japanese specialty steel foundries, and REACH substance restriction scope expansion affecting potting compound formulations. Forecasts embed assumptions regarding marine fleet electrification penetration rates and offshore wind installation scaling in China's Jiangsu province. Cross-checking against IHS Markit shipbuilding production data and semiconductor industry association capacity reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Molded Interconnect Devices (MID) Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Inductors, Cores and Beads Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Global Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Ultra-Thin Electronic PI Film Market
Passive And Interconnecting Electronic Components
Hybrid Capacitor Market
Passive And Interconnecting Electronic Components
Global EMI Shielding Market
Passive And Interconnecting Electronic Components
Passive Infrared Sensor Market
Passive And Interconnecting Electronic Components
Fiber Splice Closure Market
Passive And Interconnecting Electronic Components
Fuse Market
Passive And Interconnecting Electronic Components
LAMEA Thermal Protector Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Power and Utilities MLCC Market
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Germany MLCC Market