
 Global Transistor Market | 2026-2036
Global Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transistor Market Foresight
Market Context
Buyer concentration among Automotive Tier-1 Suppliers is decoupling from traditional consumer electronics procurement patterns as electric vehicle programs multiply. Infineon Technologies AG leverages its vertical integration into silicon carbide substrate supply to secure long-term automotive contracts. Texas Instruments sustains dominance in analog-intensive BJT and MOSFET portfolios through captive 300mm fabrication. STMicroelectronics N.V. anchors European supply security via its agreements with French and Italian national semiconductor initiatives.
Technical Definition and Segment Structure
A transistor is a three-terminal semiconductor device that modulates current or voltage between input and output terminals through controlled carrier injection or field effect, with switching speeds exceeding 100 GHz in advanced gallium nitride implementations and power handling from milliwatts to multi-megawatts depending on architecture. Its primary industrial purpose spans signal amplification in telecommunications equipment and power conversion in renewable energy inverters, where efficiency thresholds now dictate technology selection. MOSFET variants occupy the largest value share across consumer electronics and computing applications due to mature CMOS manufacturing economics, while GaN technology leads growth trajectories in telecommunications base stations and aerospace systems demanding higher frequency operation. IGBT modules retain structural importance in renewable energy inverters and industrial motor drives where kilovolt-class blocking capability remains essential.
Regulatory Framework
The EU Green Deal and REACH chemical frameworks constrain hazardous material use in European-bound transistor supply chains, while the EPA and OSHA shape American manufacturing emissions and worker exposure protocols for compound semiconductor fabrication. China's MEE enforces dual carbon goals that accelerate domestic migration toward wide-bandgap technologies in power applications. Stakeholders must monitor evolving efficiency certification tiers and carbon-border adjustment mechanisms to anticipate which device architectures secure preferential market access.
Market Dynamics
Wide-bandgap semiconductor architectures are forcing a capital reallocation across power electronics supply chains as silicon carbide and gallium nitride displace legacy silicon in high-voltage applications. Automotive electrification programs in Germany, China, and the United States now specify efficiency thresholds that only compound semiconductor devices can satisfy.
Growth Catalysts
- EU Green Deal efficiency mandates:The framework tightens carbon intensity requirements for industrial motor drives and renewable energy inverters, compelling equipment manufacturers to specify wide-bandgap transistors.
- Electric vehicle platform proliferation:Automotive OEMs in China, Germany, and the United States are qualifying silicon carbide MOSFETs for 800-volt drivetrain architectures.
- Silicon carbide substrate supply expansion:East Asian manufacturing clusters in Taiwan, South Korea, and Japan are scaling 150mm and 200mm wafer production to meet power semiconductor demand.
Market Restraints
- Epitaxial wafer supply concentration:High-quality silicon carbide epitaxy remains concentrated among Japanese and American suppliers, creating single-source vulnerability for European and Chinese device fabricators.
- Plasma etching equipment dependency:Gallium nitride HEMT manufacturing requires inductively coupled plasma systems dominated by American and Japanese capital equipment vendors.
- REACH chemical compliance costs:The European framework restricts perfluorinated compounds used in compound semiconductor etching processes, forcing process requalification expenses.
Strategic Opportunities
- India PLI scheme for semiconductors:The production-linked incentive program subsidizes domestic transistor fabrication facilities serving automotive and renewable energy equipment markets.
- Silicon carbide-gallium nitride heterointegration:Hybrid power modules combining both materials enable optimized performance across voltage and frequency domains.
- Direct OEM contracting:Power semiconductor vendors are bypassing traditional distribution channels to secure long-term supply agreements with renewable inverter manufacturers.
Industry Challenges
- Compound semiconductor process engineering talent:The specialized expertise for gallium nitride HEMT and silicon carbide MOSFET fabrication remains scarce relative to silicon CMOS staffing pools.
- AEC-Q101 automotive qualification timelines:The stress-test protocol for discrete semiconductors extends 12-18 months, compressing product development windows for new vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transistor Market |
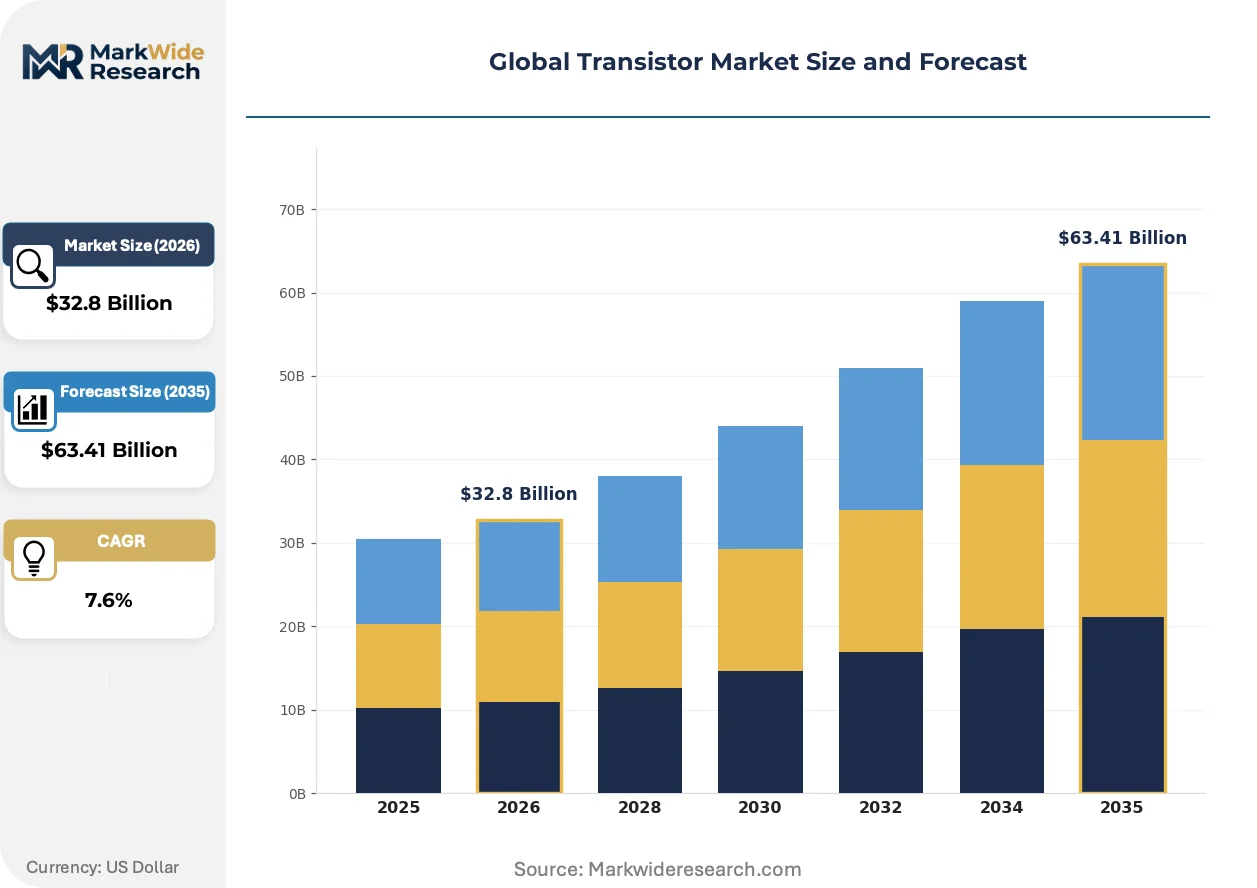
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $63.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BJT, MOSFET, IGBT, JFET, MESFET Technology: Planar, Bipolar, CMOS, BiCMOS, GaN Application: Consumer Electronics, Telecommunications Equipment, Aerospace Systems, Renewable Energy Inverters, Robotics End User Industry: Semiconductor Foundries, Electronic Assemblers, Automotive Tier-1 Suppliers, Defense Contractors, Industrial Automation Firms |
| Companies Covered | Texas Instruments Incorporated, Infineon Technologies AG, NXP Semiconductors N.V., STMicroelectronics N.V., Vishay Intertechnology, Inc., ROHM Co., Ltd., Diodes Incorporated, Renesas Electronics Corporation, onsemi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transistor Market Shifts & Advancements
Power module packaging architectures are converging with thermal management systems as operating frequencies rise and form factors shrink. This convergence demands simultaneous innovation in materials, interconnect technologies, and system-level integration approaches.
Gallium nitride power integrated circuits are modularizing discrete transistor functions with gate drivers and protection circuitry onto single die. Data center power supply manufacturers in the United States and Taiwan are adopting these monolithic solutions for 48-volt bus converters. The integration is compressing bill-of-material counts and enabling higher switching frequencies that reduce passive component sizes.
China's MIIT is enforcing GB standards for energy efficiency in variable-frequency motor drives that exceed international IEC thresholds. Domestic equipment manufacturers must now source transistors meeting stricter conduction and switching loss specifications. This regulatory divergence is fragmenting global product portfolios as vendors develop China-specific device variants.
Automotive Tier-1 suppliers are consolidating power semiconductor procurement under single-source agreements with guaranteed volume commitments. German and Japanese inverter manufacturers are displacing spot-market purchasing with five-year contracts tied to electric vehicle production schedules. This contractual shift concentrates supplier risk but secures allocation during substrate supply constraints.
Global Transistor Market Segmentation
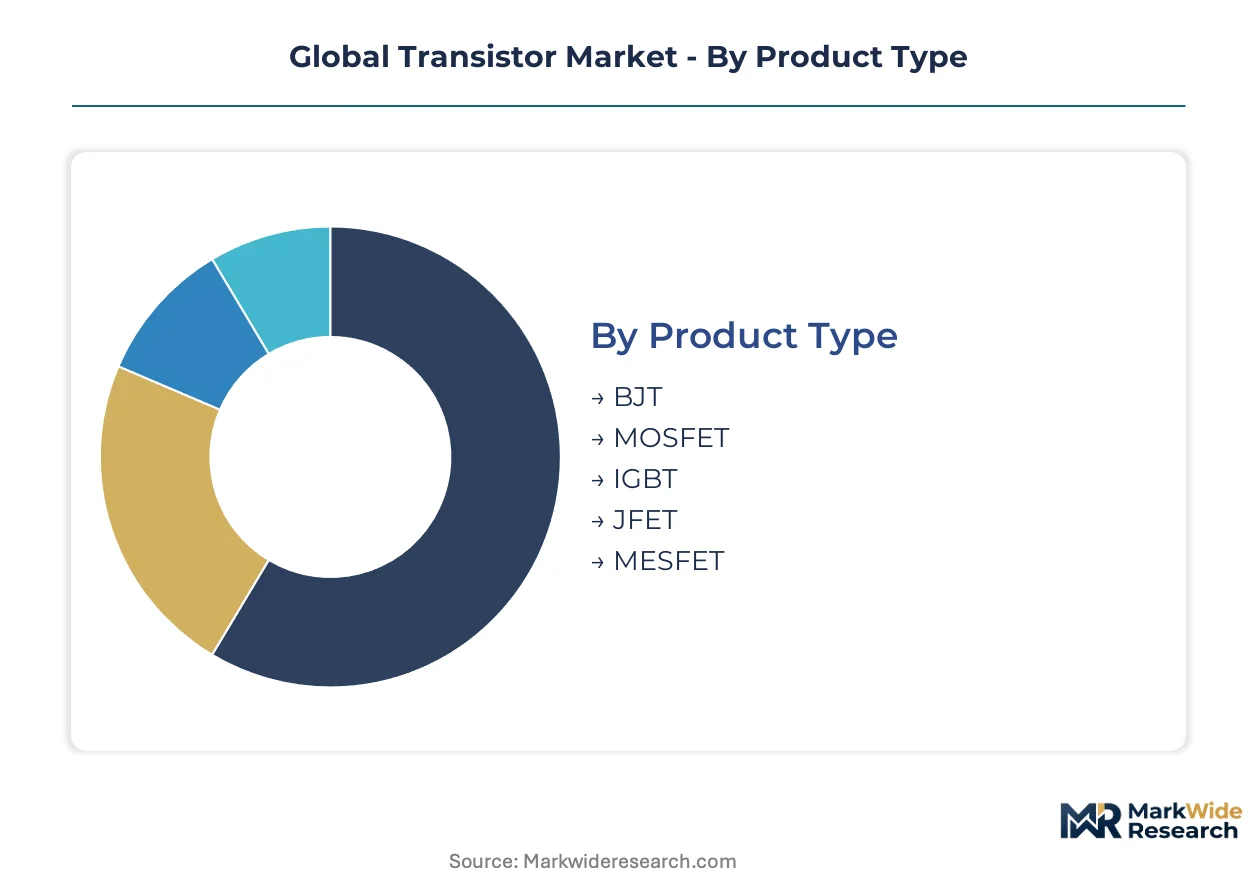
Transistor segmentation reveals divergent value capture across power handling thresholds and frequency domains. Device architecture selection directly determines addressable end-use markets and margin profiles.
Product Type:
Volume manufacturing concentrates in silicon-based architectures, while premium pricing attaches to wide-bandgap implementations serving high-voltage applications.
- MOSFET:Field-effect architecture dominates consumer electronics and computing through mature CMOS manufacturing economics. Demand concentrates in Taiwan and South Korea for smartphone and laptop power management circuits, driven by 5-nanometer node scaling requirements.
- IGBT:Insulated-gate bipolar junction combines MOSFET input impedance with bipolar current capability for kilovolt-class blocking. Renewable energy inverter manufacturers in Germany and China specify these modules for grid-tied solar and wind conversion systems, constrained by silicon substrate thermal limitations.
- BJT:Bipolar junction technology persists in analog-intensive signal amplification where cost sensitivity outweighs efficiency optimization.
- JFET:Junction-gate architecture serves specialized sensor interfaces and high-impedance buffer applications requiring minimal gate leakage.
- MESFET:Metal-semiconductor field-effect devices enable microwave-frequency operation in satellite communications equipment.
Mature deployment sits with MOSFET variants across consumer and computing platforms. Newer deployment is concentrated in IGBT modules for electrified transportation and grid infrastructure.
Technology:
Process maturity creates a cost-structure divide between silicon-established nodes and compound semiconductor investments requiring specialized epitaxy and etching equipment.
- CMOS:Complementary metal-oxide-semiconductor pairs n-channel and p-channel MOSFETs for digital logic and mixed-signal integration. Foundry capacity in Taiwan and South Korea sustains cost leadership for microprocessor and memory peripheral transistors, pressured by EUV lithography capital intensity.
- GaN:Gallium nitride heterostructure devices achieve switching speeds exceeding silicon limits for radio-frequency power amplification. Telecommunications base station deployments in the United States and Japan drive substrate demand, constrained by plasma etching equipment import dependencies.
- Planar:Traditional lateral current flow architecture retains cost advantages in legacy analog and discrete applications.
- Bipolar:Current-controlled devices persist in precision analog circuits where transconductance linearity outweighs power efficiency.
- BiCMOS:Bipolar-CMOS integration combines logic density with analog performance for mixed-signal system-on-chip designs.
Planar and bipolar technologies anchor mature industrial and automotive analog segments. GaN and advanced CMOS nodes are climbing the fastest in telecommunications and data center power conversion.
Application:
End-use requirements fragment the market across efficiency thresholds, frequency specifications, and environmental operating ranges.
- Consumer Electronics:Smartphones, laptops, and wearables demand sub-milliwatt to watt-scale power management with minimal leakage current. Procurement concentrates in East Asian electronics manufacturing services, shaped by MIIT GB efficiency standards for variable-frequency motor drives.
- Renewable Energy Inverters:Grid-tied solar and wind systems require megawatt-class power modules with 98%+ conversion efficiency. Equipment manufacturers in Germany and China specify wide-bandgap transistors to meet EU Green Deal carbon intensity mandates for industrial motor drives.
- Telecommunications Equipment:5G base stations and satellite systems drive radio-frequency power device demand.
- Aerospace Systems:Radiation-hardened and high-reliability specifications govern military and satellite applications.
- Robotics:Motor drive and sensor interface requirements span industrial automation and service robot platforms.
Consumer electronics represents the highest-volume deployment channel. Renewable energy inverters and aerospace systems concentrate newer wide-bandgap qualification efforts.
End User Industry:
Procurement authority is consolidating under automotive and renewable energy OEMs, displacing traditional distributor-mediated purchasing patterns.
- Automotive Tier-1 Suppliers:Electric drivetrain inverter and onboard charger manufacturers in Germany, China, and the United States are qualifying silicon carbide MOSFETs for 800-volt architectures. Five-year supply agreements with guaranteed volume commitments are replacing spot-market purchasing, concentrating allocation risk during substrate constraints.
- Semiconductor Foundries:Contract manufacturing capacity in Taiwan, South Korea, and Japan enables fabless power semiconductor design houses. AEC-Q101 automotive qualification timelines extending 12-18 months compress development windows for new vehicle platforms.
- Electronic Assemblers:Contract manufacturers integrate discrete transistors into subsystem modules for OEM customers.
- Defense Contractors:ITAR and national security requirements govern sourcing for military and aerospace applications.
- Industrial Automation Firms:Variable-frequency drives and servo motor controls specify transistors across voltage and current ratings.
Mature procurement relationships persist with electronic assemblers and industrial automation firms. Newer contractual structures are emerging with automotive Tier-1 suppliers and renewable energy OEMs seeking direct power semiconductor partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate production clusters in Taiwan, South Korea, and Japan anchor transistor manufacturing geography. East Asian wafer fabrication capacity concentrates near raw material refining and epitaxial growth facilities. Automotive electrification programs in Germany, China, and the United States now dictate regional demand distribution.
United States
Data center power supply manufacturers in California and Texas drive gallium nitride transistor procurement for 48-volt bus converters. The EPA enforces emissions protocols for compound semiconductor fabrication facilities. Austin and Phoenix host expanding 300mm fabrication complexes serving analog-intensive BJT and MOSFET portfolios.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify silicon carbide MOSFETs for 800-volt electric drivetrain architectures. The EU Green Deal tightens carbon intensity requirements for industrial motor drives manufactured domestically. Dresden anchors European supply security through agreements with French and Italian national semiconductor initiatives.
China
Domestic equipment manufacturers source transistors for variable-frequency motor drives under MIIT GB efficiency standards exceeding international IEC thresholds. The MEE enforces dual carbon goals accelerating migration toward wide-bandgap technologies. Yangtze River Delta manufacturing clusters scale 150mm and 200mm silicon carbide wafer production.
Japan
Telecommunications base station deployments in Tokyo and Osaka drive radio-frequency power device demand for 5G infrastructure. METI coordinates national semiconductor strategy securing substrate supply chains. Kyushu hosts concentrated epitaxial wafer production creating single-source vulnerability for European device fabricators.
South Korea
Smartphone and laptop power management circuit procurement concentrates through Seoul-based electronics manufacturing services. Foundry capacity sustains cost leadership for microprocessor peripheral transistors at 5-nanometer node scale. Busan-Ulsan industrial corridors integrate memory and logic fabrication with power semiconductor packaging facilities.
Global Transistor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wide-bandgap specialization through substrate control and automotive qualification. The market structures around three tiers: integrated device manufacturers with captive fabrication, fabless design houses leveraging contract foundries, and materials suppliers controlling epitaxial wafer supply. Two strategic archetypes dominate: silicon carbide substrate backward integrators securing automotive contracts, and analog-focused incumbents sustaining dominance through 300mm scale. Competitive moves concentrate on capacity expansion for 200mm silicon carbide wafers and direct OEM contracting bypassing distribution channels.
Among European-integrated device manufacturers, Infineon Technologies AG and STMicroelectronics N.V. exemplify substrate-backward integration archetypes, while Texas Instruments Incorporated represents analog-scale incumbency through captive 300mm fabrication. These three entities occupy distinct competitive positions: Infineon anchors German automotive supply security, STMicroelectronics sits within Franco-Italian national semiconductor initiatives, and Texas Instruments sustains North American analog dominance. Their collective presence defines tier boundaries that emerging entrants must penetrate through wide-bandgap qualification or foundry partnership models.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| STMicroelectronics N.V. |
| Vishay Intertechnology, Inc. |
| ROHM Co., Ltd. |
| Diodes Incorporated |
| Renesas Electronics Corporation |
| onsemi Corporation |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate manufacturing migration from 150mm to 200mm wafer diameters is simultaneously compressing per-die costs and concentrating supply authority among East Asian capital equipment holders. This dual transformation rewards fabricators with in-house epitaxial growth capability while penalizing fabless design houses exposed to spot-market wafer pricing.
Pricing Analysis
Warranty and qualification documentation bundling separates automotive-grade silicon carbide MOSFETs from unqualified commercial equivalents. Three-tier pricing structure across AEC-Q101 certified, industrial-grade, and consumer-tier devices reflects qualification investment recovery. Pricing pressure stems from Chinese domestic wafer capacity additions compressing margins on standard-grade silicon devices. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to five-year supply agreement structures, while consumer electronics assemblers demand continuous cost reduction.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and renewable energy procurement, displacing traditional distribution for wide-bandgap devices. Taiwan, South Korea, and Japan anchor substrate fabrication and epitaxial wafer supply. High-purity silicon carbide source material, inductively coupled plasma etching systems, and specialized packaging substrates constitute critical input dependencies. Single-source vulnerability concentrates in Japanese epitaxial equipment vendors. Distribution runs through authorized franchised partners for smaller industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide epitaxial wafer supply constraints prop pricing power for substrate-backward-integrated incumbents. This supply-constrained structure favors asset-heavy competitive positions over fabless alternatives.
For Market Incumbents: Acquire silicon carbide substrate fabrication assets to secure allocation during supply crunches. Expand 200mm wafer qualification capacity in Taiwan or South Korea to capture automotive contract migration. Defend against GaN-on-silicon challengers by accelerating integrated module development with embedded gate drivers. For New Entrants and Emerging Players: Industrial motor drive manufacturers in India and Southeast Asia represent underserved buyer archetypes seeking cost-optimized IGBT alternatives. Penetrate these markets through direct technical sales bypassing established distribution markups. Qualify devices under India's PLI scheme subsidy framework to offset AEC-Q101 timeline costs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automotive Tier-1 suppliers seeking captive semiconductor supply. Long-term viability hinges on substrate supply security rather than design innovation alone. Monitor silicon carbide wafer price indices and automotive platform qualification announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive wafer supply secures allocation priority with German and Chinese automotive OEMs. |
| GaN Power IC Monolithic Integration | Single-die solutions with gate drivers reduce BOM counts for Taiwan data center power supply manufacturers. |
| Automotive Qualification Fast-Track | Compressed AEC-Q101 timelines enable earlier entry onto United States electric vehicle platforms. |
| Direct OEM Contracting Structure | Five-year supply agreements with guaranteed volumes displace spot-market purchasing for renewable inverter manufacturers. |
| India PLI Scheme Facility Qualification | Domestic fabrication subsidies offset capital intensity for serving automotive and renewable energy equipment markets. |
Research Methodology
SEC 10-K filings, EIA power electronics deployment data, and automotive supplier qualification registries formed the secondary backbone. Primary interviews with silicon carbide substrate procurement managers, power module packaging engineers, and Tier-1 supplier semiconductor commodity directors validated demand assumptions. Bottom-up wafer capacity modeling and top-down equipment spending analysis enabled triangulation across the analysis window.
Historical capacity utilization trends and automotive platform rollout schedules anchored the projection framework. Segmentation modeling spanned device architecture, substrate technology, voltage class, and end-use industry vertical. CAGRs derived from supply-demand balance analysis incorporating epitaxial wafer expansion timelines and electric vehicle production forecasts.
Revisions become necessary when silicon carbide substrate yield improvements accelerate or automotive platform delays materialize beyond modeled assumptions. Forecasts reflect substrate supply constraints and regulatory efficiency mandate enforcement as core assumptions. Practitioners should monitor 200mm wafer qualification announcements and EU carbon-border adjustment implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Global Semiconductor Lead Frame Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Asia-Pacific Semiconductor Device Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Wttx Market