
 Transistor Arrays Market | 2026-2036
Transistor Arrays Market Size, Share, and Industry Trends Forecast 2026-2036
Transistor Arrays Market Analytics
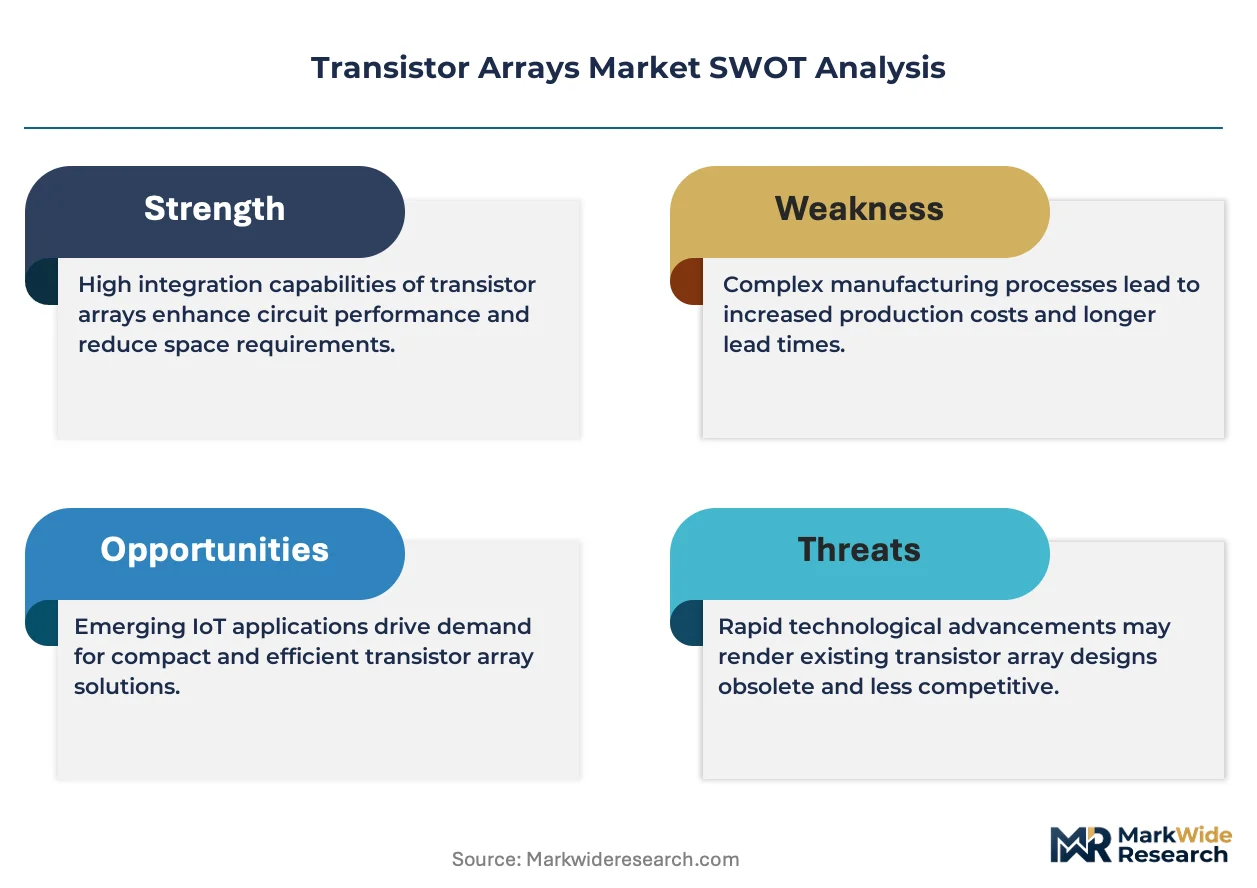
Asset-light foundry partnerships is narrowing the capital barrier for fabless competitors in transistor arrays. Texas Instruments Incorporated leverages captive fabrication to sustain margin control across analog switch lines. Infineon Technologies AG anchors European supply for automotive-grade BiCMOS arrays. ON Semiconductor competes through vertical integration into silicon carbide-adjacent processes.
Transistor arrays are monolithic integrated circuits containing multiple transistors fabricated on a single semiconductor die, typically specified by channel count, on-resistance, and switching speed parameters, serving as compact switching or amplification engines in signal routing and power management systems. CMOS technology dominates volume production due to low static power draw, while bipolar arrays retain niche dominance in high-current industrial automation applications. QFN packages lead in consumer electronics for thermal performance at miniaturized footprints, though TSSOP maintains cost advantages in legacy industrial retrofit markets.
FDA oversight of medical device electronics and EPA hazardous substance rules shape material choices in U.S.-bound transistor arrays, while REACH compliance in Europe restricts certain substrate chemistries in packaging. China's SAMR enforces GB standards on reliability testing that foreign suppliers must clear for market access. Stakeholders should monitor how dual carbon goals in Beijing and EU Green Deal sourcing rules recast foundry location decisions before committing long-term capacity.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are concentrating automotive-grade BiCMOS capacity, creating supply bottlenecks for industrial automation OEMs while China's GB standards tighten entry barriers for foreign array suppliers.
Growth Catalysts
- Automotive electrification mandates:EU Green Deal sourcing rules and NHTSA safety electronics standards are accelerating demand for high-channel-count switching arrays in battery management systems and motor control units.
- Industrial automation retrofit cycles:Factory modernization programs across Germany, Japan, and the United States are replacing discrete transistor banks with monolithic arrays to reduce board space and assembly cost.
- REACH-compliant substrate innovation:European packaging hubs are qualifying lead-free and halogen-free molding compounds that satisfy ECHA restrictions while maintaining thermal performance for power arrays.
Market Restraints
- 300mm silicon wafer cost volatility:Raw substrate prices fluctuate with polysilicon spot markets and energy costs in Xinjiang and Inner Mongolia, compressing foundry margins for commodity CMOS arrays.
- Single-source photoresist dependency:Advanced lithography chemistries for sub-130nm feature arrays concentrate with Japanese suppliers, exposing fabless designers to supply interruption risk.
- Silicon carbide MOSFET substitution:Discrete wide-bandgap devices are displacing traditional bipolar arrays in high-temperature power switching above 600V, narrowing the addressable market for legacy technologies.
Strategic Opportunities
- Medical device electronics certification:FDA 510(k) pathways for implantable and diagnostic equipment create premium pricing tiers for arrays meeting ISO 13485 quality systems and biocompatibility testing protocols.
- Silicon photonics co-packaging:Convergence of CMOS transistor arrays with optical transceiver dies enables 800G datacenter interconnect modules, opening volume demand from cloud infrastructure deployers.
- India PLI scheme localization:Electronics manufacturing incentives under the Production Linked Incentive program attract packaging and test investment for arrays serving domestic appliance and automotive markets.
Industry Challenges
- Automotive AEC-Q100 qualification timelines:Extended stress testing and documentation requirements for temperature grade 0 devices delay revenue recognition by 18-24 months for new array designs.
- Legacy system integration friction:Replacement of through-hole transistor arrays in installed industrial equipment requires pin-compatible footprint engineering and firmware adaptation, complicating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transistor Arrays Market |
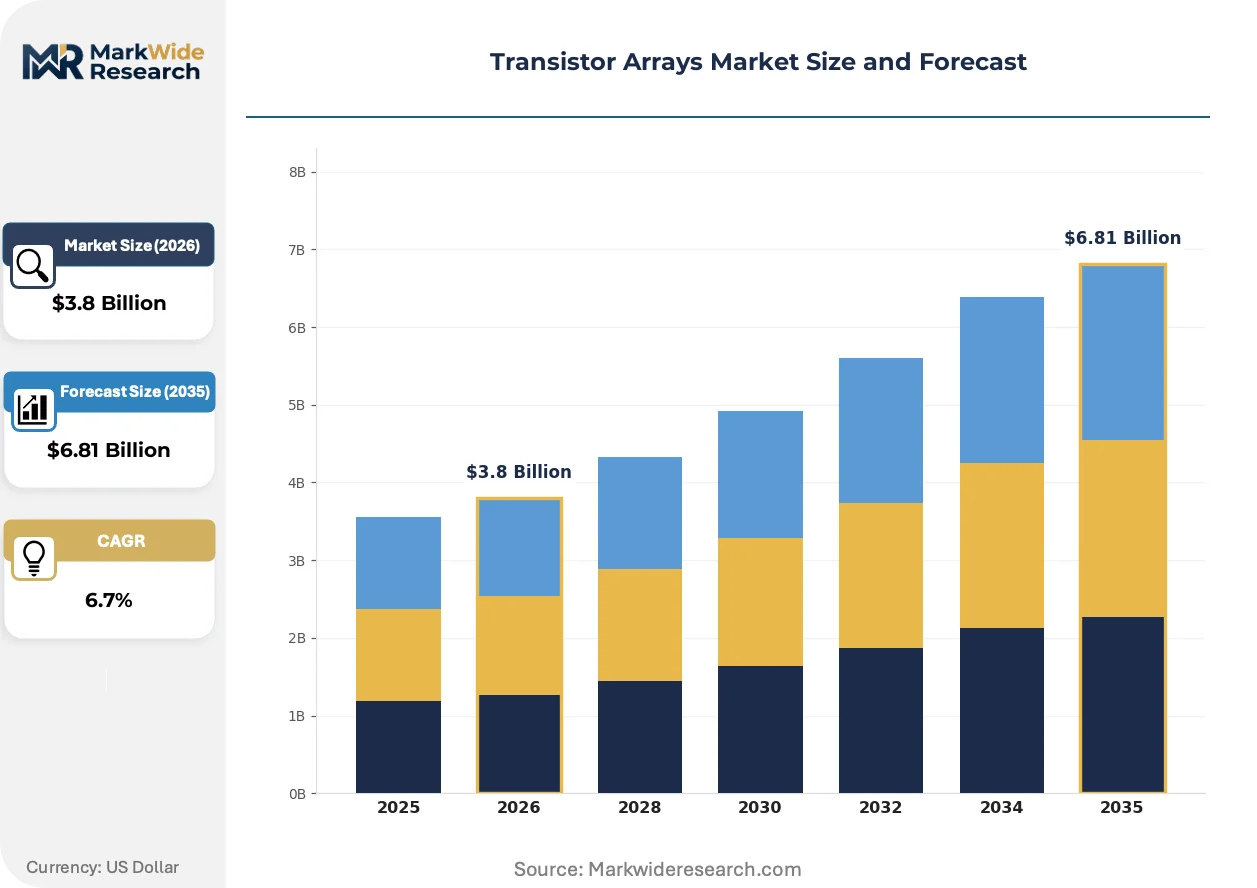
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Switches, Damping Resistors, Digital Logic, High-Speed Logic Technology: Bipolar, CMOS, BiCMOS, JFET End User: Aerospace, Automotive OEMs, Consumer Electronics, Industrial Automation Package Type: DIP, LGA, QFN, TSSOP |
| Companies Covered | Unisonic Technologies, AVX Corporation, Micrel Semiconductor, ON Semiconductor, STMicroelectronics, Texas Instruments Incorporated, Infineon Technologies AG, Renesas Electronics Corporation, ROHM Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transistor Arrays Market Evolving Landscape
Power density requirements and regulatory material restrictions are forcing concurrent evolution in transistor array architecture, packaging chemistry, and procurement models across industrial and automotive verticals.
Gate-all-around nanosheet transistors are collapsing the traditional planar CMOS footprint for high-density switching arrays. Automotive ECU designers at German and South Korean OEMs are sampling 3nm-class silicon for next-generation body electronics modules. This geometry compression is collapsing the die-size advantage that discrete MOSFETs previously held in space-constrained applications, shifting value toward integrated array solutions.
China's SAMR enforcement of updated GB/T reliability testing standards is disqualifying legacy packaging materials for industrial-grade arrays. Foreign suppliers must now submit accelerated life-test data under elevated temperature-humidity conditions to maintain distribution licenses. European array vendors are responding by relocating final test operations to qualified facilities in Suzhou and Chengdu to satisfy local content verification requirements.
Consolidated procurement by tier-one automotive electronics suppliers is compressing supplier panels for standard logic arrays. Bosch, Continental, and Denso are centralizing qualified vendor lists and demanding multi-year price commitments with indexed raw material adjustments. This concentration is most visible in Bavaria and Baden-Württemberg, where powertrain electrification programs are absorbing disproportionate shares of available automotive-grade BiCMOS foundry output.
Transistor Arrays Market Segmentation
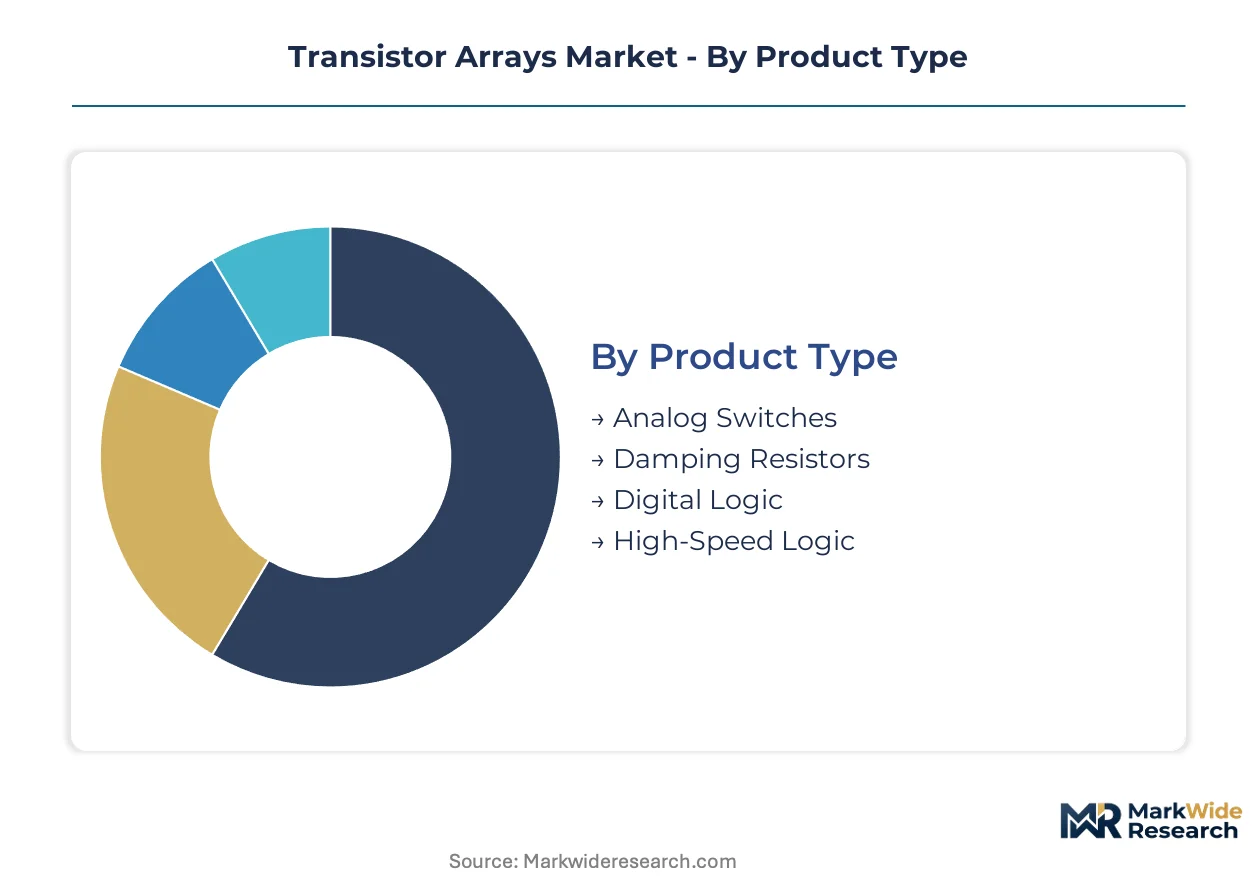
Segmentation in transistor arrays reveals divergent replacement cycles across applications. Automotive and industrial programs run 7-10 year qualification timelines, while consumer electronics refresh annually. Technology choices lock in foundry partnerships and margin structures for product lifetimes.
Product Type:
Analog switches turn over slowest due to long automotive validation cycles, while high-speed logic refreshes fastest to match datacenter upgrade cadences.
- Analog Switches:Multiplexer and signal-routing devices specified by on-resistance flatness and charge injection parameters. Demand concentrates in German automotive ECU programs where Bosch and Continental specify 16-channel arrays for battery management systems. EU Green Deal sourcing rules favor suppliers with qualified European test facilities.
- High-Speed Logic:Level translators and bus switches operating above 100MHz with sub-nanosecond propagation delays. Expansion concentrates in Taiwan and South Korea packaging hubs serving cloud infrastructure deployers upgrading to 800G optical modules. JEDEC standards for signal integrity drive specification tightening.
- Damping Resistors:Termination arrays suppressing signal reflections in high-speed digital buses. Japanese telecom equipment manufacturers specify these for 5G baseband units.
- Digital Logic:Standard gates and buffers for general-purpose switching. Chinese appliance OEMs drive volume procurement through consolidated vendor panels.
Analog switches dominate installed base. High-speed logic is where expansion concentrates.
Technology:
Cost tiers separate mature geometries from advanced nodes, with BiCMOS commanding premium pricing for automotive qualification overhead.
- CMOS:Dominant volume technology leveraging sub-100nm geometries for low static power draw. Taiwan foundries concentrate output for consumer electronics and computing applications. Scaling to 3nm-class nodes is collapsing die size advantages previously held by discrete solutions.
- BiCMOS:Combined bipolar-CMOS process delivering high current drive with logic compatibility. South Korean automotive electronics suppliers anchor demand for AEC-Q100 grade 0 devices in powertrain modules. Extended 18-24 month qualification timelines restrict supplier entry.
- Bipolar:High-current industrial arrays retaining niche in factory automation above 500mA drive requirements. German machine tool OEMs specify these for legacy retrofit compatibility.
- JFET:Low-noise input stages for sensor interface applications. Medical device electronics in the United States drive limited volume through FDA 510(k) pathways.
Bipolar retains legacy industrial footprint. BiCMOS captures the steepest expansion trajectory as automotive electrification absorbs foundry capacity.
End User:
Customer concentration varies sharply, with automotive OEMs consolidating procurement while industrial automation fragments across retrofit projects.
- Automotive OEMs:Centralized qualified vendor lists with multi-year price commitments and indexed raw material adjustments. German and South Korean programs absorb disproportionate shares of available BiCMOS foundry output. NHTSA safety electronics standards and EU battery regulations shape specification requirements.
- Industrial Automation:Retrofit cycles replacing discrete transistor banks with monolithic arrays. Japanese and United States factory modernization programs prioritize pin-compatible footprint engineering to minimize firmware adaptation. REACH-compliant substrate requirements complicate material selection.
- Consumer Electronics:Annual refresh cycles with aggressive cost targets. QFN packaging dominates for thermal performance at miniaturized footprints.
- Aerospace:Radiation-tolerant and high-reliability grades with extended documentation requirements. Limited volume but premium pricing tiers.
Industrial automation dominates installed base. Automotive OEMs concentrate expansion through electrification mandates.
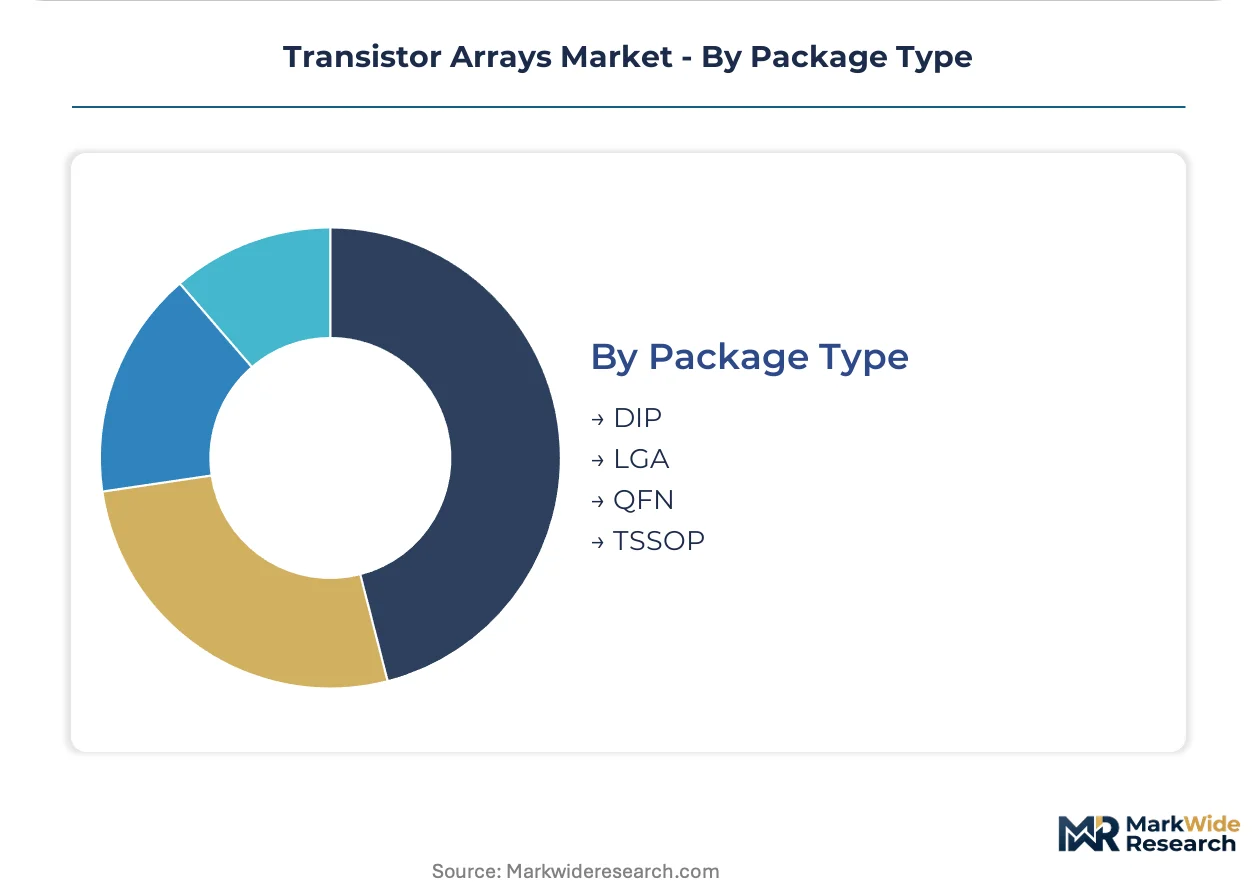
Package Type:
Volume scale inversely correlates with thermal performance, forcing trade-offs between cost and power dissipation requirements.
- QFN:Leadless near-chip-scale package with exposed thermal pad for power dissipation. Taiwan and South Korea packaging hubs concentrate output for smartphone and tablet applications. Miniaturized footprints suit space-constrained portable designs.
- TSSOP:Thin shrink small outline package maintaining cost advantages in legacy industrial retrofit markets. Through-hole compatibility variants ease replacement of obsolete DIP arrays.
- LGA:Land grid array for high-pin-count switching matrices in server and networking equipment. Cloud infrastructure deployers drive specification for 800G interconnect modules.
- DIP:Dual in-line package for through-hole legacy systems. Declining volume concentrated in maintenance of installed industrial equipment.
DIP retains legacy maintenance demand. QFN captures expansion in portable and high-density applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German automotive OEMs and South Korean electronics suppliers, while Taiwanese foundries extract margin through capacity scarcity. East Asian packaging hubs capture value from industrial automation demand. Regulatory divergence across SAMR, REACH, and NHTSA frameworks fragments procurement strategies.
United States
NHTSA safety electronics standards and industrial automation retrofit cycles drive demand for high-channel-count switching arrays. FDA 510(k) pathways for medical device electronics create premium pricing tiers for qualified suppliers. Greater Boston and Austin clusters concentrate fabless design activity for aerospace and defense applications.
Germany
Bosch and Continental procurement centralization absorbs disproportionate shares of automotive-grade BiCMOS foundry output. EU Green Deal sourcing rules and REACH-compliant substrate requirements reshape material selection for power arrays. Bavaria and Baden-Württemberg anchor European demand for battery management system components.
China
SAMR enforcement of updated GB/T reliability testing standards disqualifies legacy packaging materials for industrial-grade arrays. Dual carbon goals accelerate foundry location decisions toward renewable-energy-powered facilities. Suzhou and Chengdu qualified test facilities satisfy local content verification requirements for foreign suppliers.
South Korea
Automotive electronics suppliers anchor demand for AEC-Q100 grade 0 devices in powertrain electrification programs. Extended qualification timelines restrict supplier entry while concentrating procurement leverage. Seoul Capital Area packaging hubs scale output for smartphone and datacenter interconnect modules.
Japan
METI industrial modernization programs prioritize pin-compatible footprint engineering to minimize firmware adaptation in legacy equipment replacement. JIS standards for signal integrity drive specification tightening in telecom baseband applications. Nagoya and Osaka clusters maintain niche dominance in high-current bipolar arrays for factory automation.
Transistor Arrays Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin through process control and qualification overhead. The vendor base stratifies across captive fabrication, fabless design, and foundry-service archetypes with divergent capital intensity. IDM players leverage backward integration into silicon carbide-adjacent processes; fabless competitors narrow capital barriers through asset-light foundry partnerships. Dominant competitive moves include multi-year price commitments with indexed raw material adjustments and geographic relocation of test operations to satisfy local content requirements.
Within the integrated device manufacturer tier, Texas Instruments Incorporated and Infineon Technologies AG exemplify archetypes sustaining margin control through captive fabrication and automotive-grade qualification depth. ON Semiconductor occupies a position bridging vertical integration into wide-bandgap materials with standard CMOS array portfolios. STMicroelectronics and Renesas Electronics Corporation sit within the European-Japanese axis serving industrial automation and automotive electrification programs with extended product lifecycles.
| Leading Market Players |
|---|
| Unisonic Technologies |
| AVX Corporation |
| Micrel Semiconductor |
| ON Semiconductor |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| ROHM Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Automotive-grade BiCMOS foundry undercapacity in South Korea and Taiwan is compressing supplier margins while elevating pricing power for qualified vendors serving German OEM electrification programs. This utilization squeeze forces trade-offs between long-term contract commitments and spot market exposure across the transistor array value chain.
Pricing Analysis
Configured-to-order analog switch arrays for AEC-Q100 grade 0 automotive applications command 40-60% premiums over standard catalog CMOS products. Contract-based long-term offtake agreements dominate procurement, with price differentiation driven by certification tier and volume scale. Cost compression in commodity digital logic arrays is intensifying because Chinese appliance OEMs consolidate vendor panels. Industrial automation buyers exhibit highest price sensitivity due to retrofit budget constraints, while medical device electronics purchasers show lowest sensitivity given FDA 510(k) qualification barriers.
Supply Chain Analysis
TSMC, Samsung Foundry, and GlobalFoundries hold concentrated capacity for sub-130nm transistor array fabrication. Geographic supply concentrates in Taiwan, South Korea, and the United States for advanced lithography, with back-end packaging anchored in China, Malaysia, and Vietnam. Raw material dependencies include 300mm silicon wafers, Japanese-sourced photoresist chemistries, and lead-free molding compounds. Single-source photoresist vulnerability poses structural supply chain risk. Distribution runs through authorized distributors serving tier-one automotive electronics suppliers and direct OEM contracts for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide MOSFET substitution above 600V threatens legacy bipolar array incumbents, demanding active substitution defense through integrated solution bundling and qualification depth.
For Market Incumbents: Build automotive qualification moats by deepening AEC-Q100 grade 0 certification portfolios and securing multi-year price commitments with Bosch, Continental, and Denso. Anchor captive fabrication in Taiwan and South Korea to defend margin control against fabless competitors leveraging asset-light foundry partnerships. Counter SiC MOSFET displacement by co-packaging transistor arrays with gate drivers in powertrain modules. For New Entrants and Emerging Players: Establish a beachhead in medical device electronics where FDA 510(k) pathways create premium pricing tiers with limited incumbent saturation. Target JFET sensor interface arrays for implantable equipment as the most penetrable segment given ISO 13485 quality system requirements. Pursue qualification partnerships with Greater Boston and Austin fabless design clusters to bypass direct foundry competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-grade BiCMOS processes due to extended 18-24 month qualification timelines and 300mm wafer cost volatility. Prioritize acquisition targets with established AEC-Q100 certification libraries and qualified European test facilities. Monitor polysilicon spot market movements in Xinjiang and Inner Mongolia as inflection indicators for foundry margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Qualification Expansion | Extended stress testing at Bosch and Continental secures multi-year automotive supply agreements. |
| Silicon Carbide-Adjacent Process Integration | Backward integration into wide-bandgap materials defends against discrete MOSFET substitution above 600V. |
| European Test Facility Relocation | Suzhou and Chengdu operations satisfy SAMR local content verification for GB/T compliance. |
| Medical Device Electronics Certification | FDA 510(k) pathways for implantable arrays unlock premium pricing tiers in diagnostic equipment. |
| Silicon Photonics Co-Packaging Development | Convergence with optical transceiver dies captures 800G datacenter interconnect demand from cloud deployers. |
Research Methodology
Initial hypotheses were tested against primary input from semiconductor foundry operations managers, fabless design house CTOs, tier-one automotive electronics procurement directors, and industrial automation OEM plant engineers and refined through secondary validation. Sources included SEC 10-K filings from IDM players, Taiwan Semiconductor Industry Association capacity reports, SAMR GB standards documentation, and JEDEC signal integrity specifications. Bottom-up die-size and wafer-start estimates were triangulated against top-down OEM procurement data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology node, end-user vertical, and package format alongside regional regulatory cluster. CAGRs were derived from fitted growth curves applied to foundry capacity expansion schedules and OEM electrification program timelines. Forecast inputs incorporated AEC-Q100 qualification pipeline data and REACH-compliant substrate qualification status from European packaging hubs.
Macroeconomic conditions sit as an overlay; deviation in polysilicon spot prices, energy costs in Xinjiang and Inner Mongolia, or EU Green Deal sourcing rule enforcement would shift the trajectory. Forecasts reflect underlying assumptions about foundry utilization rates and automotive electrification mandate adherence. Quarterly review of SAMR GB/T standard updates and tier-one automotive supplier qualified vendor list changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Reachers Market
Semiconductor Devices
Flip Chip Market
Semiconductor Devices
Global Zener Diode Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Global Semiconductor Device Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Amorphous-Semiconductor Devices Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Semiconductor Tubular Heaters Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Semiconductor Wafer Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market