
 Schottky Rectifiers Market | 2026-2036
Schottky Rectifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Schottky Rectifiers Market Analytics
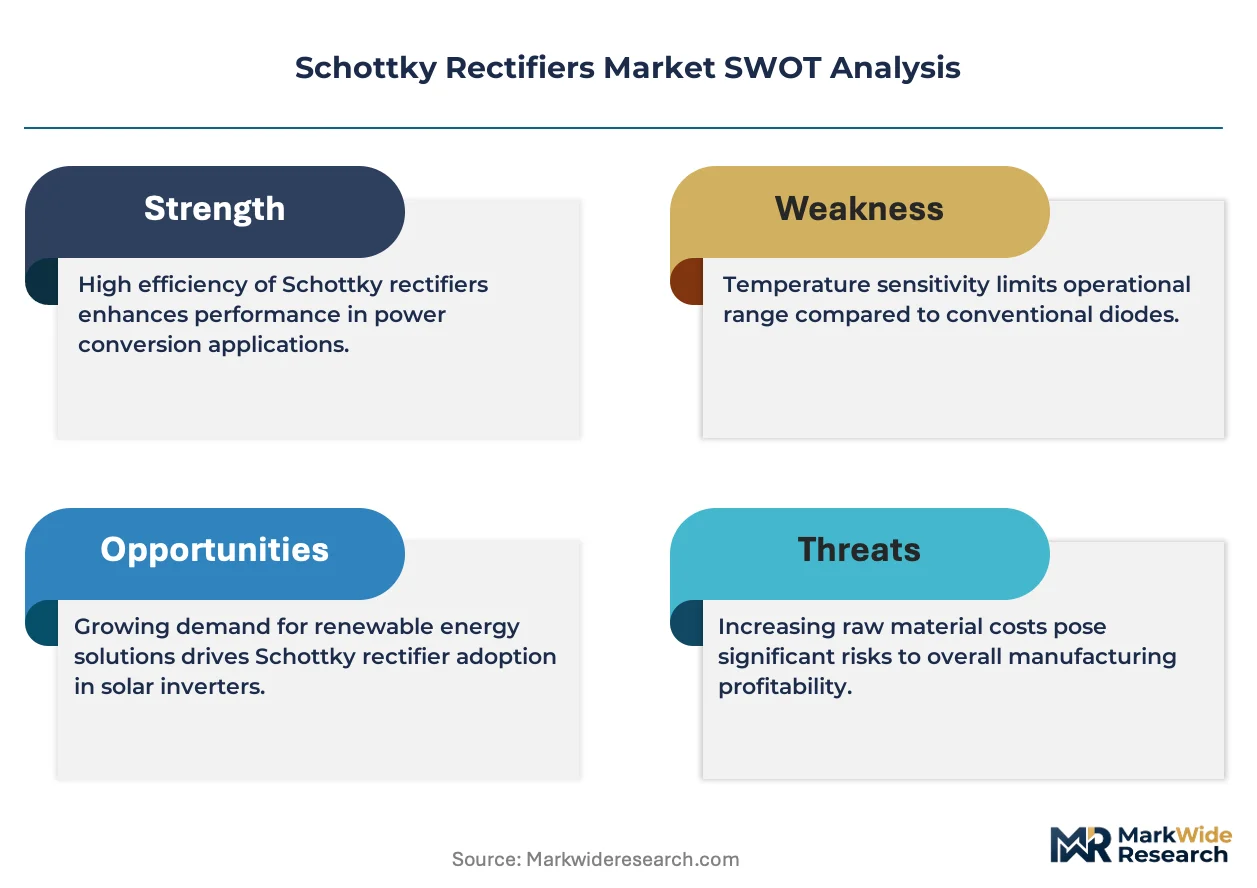
Wide-bandgap semiconductor migration is rewriting power electronics architecture across automotive and industrial verticals. Infineon Technologies AG leverages its silicon carbide foundry investments to anchor high-voltage Schottky portfolios for EV onboard chargers. STMicroelectronics N.V. competes through integrated module packaging that reduces thermal resistance in compact form factors. Vishay Intertechnology Inc. specializes in through-hole and surface-mount discrete devices for legacy industrial equipment retrofits.
Schottky rectifiers are majority-carrier metal-semiconductor junction diodes with forward voltage drops typically ranging from 0.15V to 0.45V, enabling faster switching and reduced conduction losses in high-frequency power conversion circuits. Their primary commercial purpose centers on rectification, OR-ing, and clamping functions in switch-mode power supplies, DC-DC converters, and photovoltaic inverter stages. Silicon carbide technology variants command premium positioning due to superior thermal conductivity and breakdown field strength versus silicon predecessors. Gallium nitride Schottky devices represent the fastest-growing technology segment, though from a smaller installed base, as telecommunications base stations and server power supplies demand sub-nanosecond recovery characteristics.
FDA oversight of medical power supplies, EPA efficiency mandates under Energy Star programs, and EU RoHS restrictions on hazardous substances collectively shape product qualification pathways and material selection for Schottky rectifier manufacturers. NHTSA fuel economy standards and California Air Resources Board regulations indirectly accelerate automotive adoption by requiring lighter, more efficient power electronics. Stakeholders must monitor foundry capacity allocation between silicon carbide and gallium nitride process nodes to secure supply for next-generation rectifier designs.
Market Dynamics
Wide-bandgap semiconductor migration is compressing switching losses in power conversion architectures, forcing incumbent silicon rectifier portfolios toward obsolescence while reallocating foundry capacity toward silicon carbide and gallium nitride process nodes.
Growth Catalysts
- EPA Energy Star mandates:Efficiency thresholds for server power supplies and telecommunications equipment are accelerating replacement cycles for legacy silicon rectifiers in United States data centers.
- Silicon carbide foundry expansion:Tier-one automotive suppliers in Germany and China are securing long-term supply agreements for 650V and 1200V Schottky devices for EV onboard chargers.
- EU Green Deal industrial decarbonization:Renewable energy inverter deployments across Spain, Italy, and Poland are creating procurement pull for high-efficiency rectification modules.
Market Restraints
- Silicon carbide substrate scarcity:Limited 150mm and 200mm wafer supply from specialized crystal growth facilities constrains unit output expansion.
- Platinum-group metal contact costs:Palladium and ruthenium price volatility in Schottky barrier metallization layers compresses gross margins on discrete devices.
- Gallium nitride lateral device competition:GaN HEMT alternatives with integrated rectification functions threaten discrete Schottky adoption in sub-100V applications.
Strategic Opportunities
- India PLI scheme for power electronics:Domestic manufacturing incentives are attracting module assembly investments for solar inverter and EV charger supply chains.
- Avionics 270V DC bus architectures:FAA certification pathways for more-electric aircraft are opening qualification requirements for high-reliability Schottky OR-ing diodes.
- AI training cluster power density:Hyperscale facility builds in Singapore and Taiwan are specifying 98%+ efficiency rectification for 100kW+ rack densities.
Industry Challenges
- Wide-bandgap packaging thermal management:Dissipating heat from SiC devices operating above 175°C junction temperatures requires ceramic substrate and sintering process expertise that remains concentrated among Japanese and German material suppliers.
- AEC-Q101 automotive qualification timelines:1,000-hour high-temperature reverse bias testing and temperature cycling protocols extend product release cycles to 18-24 months for EV powertrain applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schottky Rectifiers Market |
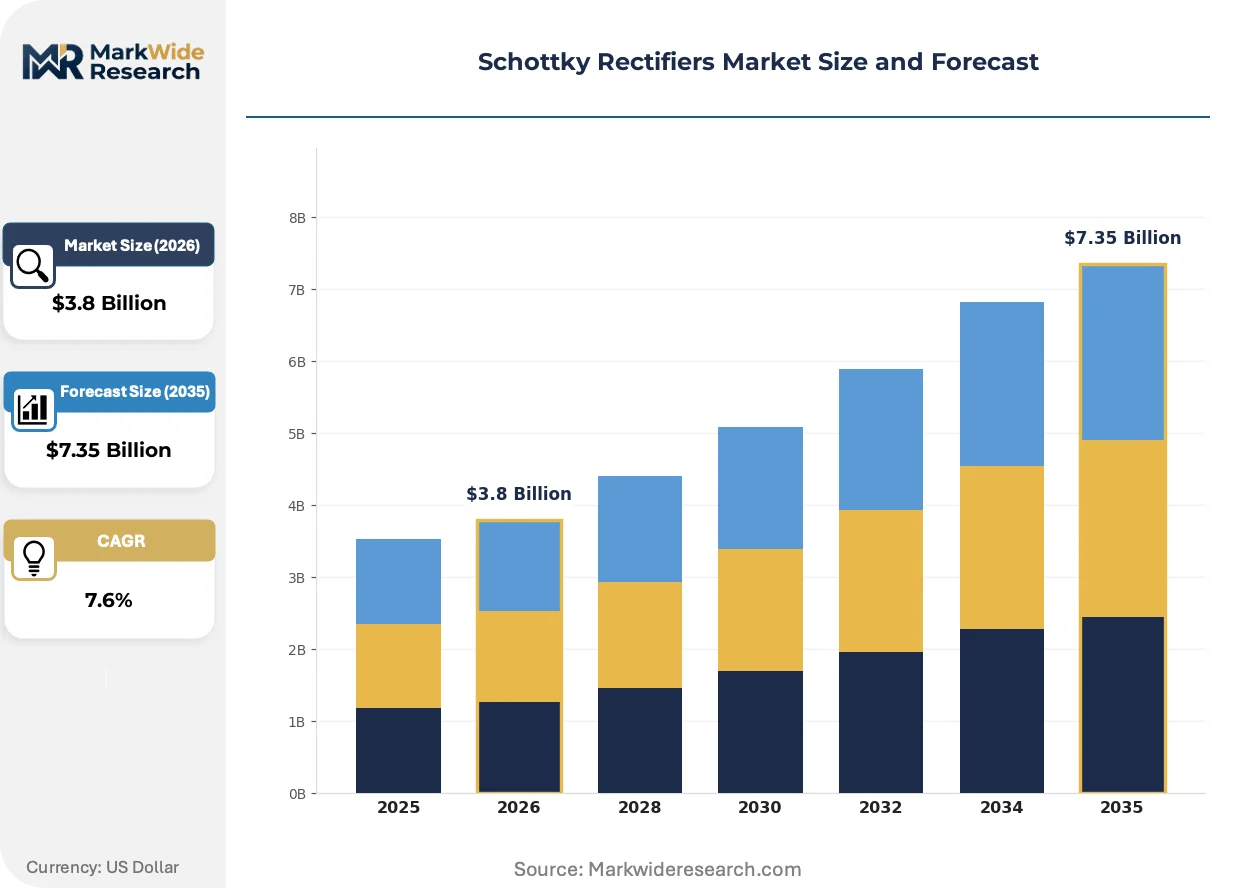
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Diodes, Modules, Arrays, Discrete Devices Application: Power Supplies, Solar Inverters, Motor Drives, Battery Chargers End User: Telecommunications, Consumer Electronics, Automotive, Industrial Technology: Silicon, Silicon Carbide, Gallium Nitride, High Voltage |
| Companies Covered | STMicroelectronics N.V., Infineon Technologies AG, onsemi, Vishay Intertechnology Inc., Diodes Incorporated, ROHM Semiconductor, Microchip Technology Inc., Nexperia B.V., Central Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schottky Rectifiers Market Evolving Landscape
Power electronics architecture is converging around integrated module platforms that embed rectification, switching, and protection functions within single thermal-mechanical envelopes.
Silicon carbide Schottky diodes with merged PiN-Schottky structures are hybridizing avalanche ruggedness with low forward voltage operation. Automotive traction inverter designers in Germany and Japan are adopting these devices for freewheeling protection at switching frequencies above 50kHz. This hybridization is compressing the performance gap between discrete diodes and fully integrated power modules.
REACH restrictions on hexavalent chromium and cadmium in surface finishes are forcing electroplating process conversions across European supply chains. Component manufacturers are shifting to nickel-palladium-gold or pure tin termination chemistries to maintain CE marking eligibility. Medical and industrial equipment OEMs in France and Switzerland are experiencing 6-12 month requalification delays during material transition.
Direct procurement contracts between automotive OEMs and semiconductor foundries are disintermediating traditional distribution channels for high-voltage rectifiers. Tier-one suppliers in China and the United States are negotiating wafer-level agreements that bypass authorized distributors for 70% of silicon carbide volume. This channel compression is restructuring margin allocation and technical support responsibilities across the supply chain.
Schottky Rectifiers Market Segmentation
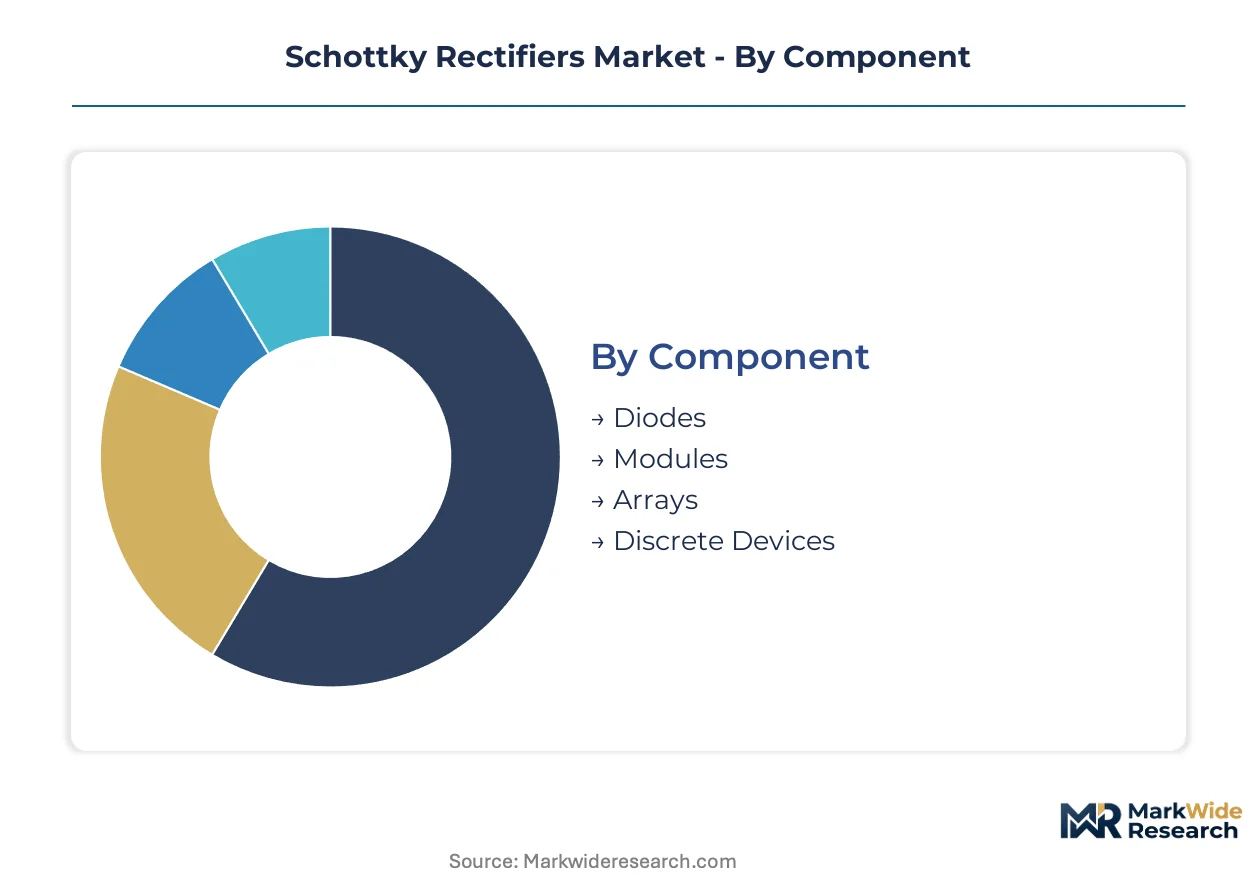
Schottky rectifier procurement patterns diverge sharply across component form factors and technology platforms, with aftermarket service requirements varying from module-level field replacement to discrete device swap-out programs. Technical support intensity and qualification documentation needs shape vendor selection criteria differently across each segment boundary.
Component:
After-sales service intensity escalates from discrete devices through integrated modules, with field failure analysis and thermal interface refurbishment driving recurring revenue attachment rates.
- Diodes:Single-junction metal-semiconductor devices dominate high-frequency rectification in telecommunications power supplies. Chinese and German automotive OEMs specify AEC-Q101 qualified variants for EV onboard chargers, with 18-24 month qualification timelines compressing supplier switching flexibility.
- Modules:Multi-die packages with integrated thermal management substrates anchor industrial motor drive retrofits. Data center operators in Singapore and Taiwan specify these for 100kW+ rack densities where junction temperatures exceed 175°C, requiring ceramic substrate expertise concentrated among Japanese material suppliers.
- Arrays:Common-cathode or common-anode multi-die configurations reduce PCB footprint in space-constrained consumer electronics. Smartphone and laptop manufacturers in South Korea and Taiwan prioritize these for DC-DC converter stages.
- Discrete Devices:Through-hole and surface-mount single packages persist in legacy industrial equipment maintenance. European machine tool operators maintain multi-decade service contracts requiring exact replacement compatibility.
Modules hold the largest share; momentum sits with silicon carbide diodes.
Application:
Cost tier stratification separates commodity power supply rectification from premium solar and automotive applications where efficiency certification drives pricing power.
- Power Supplies:Server and telecommunications rectification demands sub-nanosecond recovery characteristics for switching frequencies above 100kHz. EPA Energy Star mandates accelerate replacement cycles in United States data centers, with efficiency thresholds tightening procurement specifications.
- Solar Inverters:Maximum power point tracking circuits require 1200V+ blocking capability with minimal reverse leakage. Spain, Italy, and Poland deploy these under EU Green Deal industrial decarbonization programs, creating procurement pull for high-efficiency modules.
- Motor Drives:Variable frequency inverters utilize freewheeling diodes for inductive load protection. German and Japanese industrial automation OEMs specify merged PiN-Schottky structures for switching frequencies above 50kHz.
- Battery Chargers:EV onboard chargers demand 650V-1200V silicon carbide devices with integrated temperature sensing. Tier-one automotive suppliers negotiate direct wafer-level agreements bypassing traditional distribution channels.
Power supplies dominate current procurement volumes; solar inverters are climbing the fastest.
End User:
Customer type determines qualification burden and contract structure, with automotive and medical verticals imposing the most stringent traceability requirements.
- Telecommunications:Base station power supplies and optical network equipment demand hermetic packaging for outdoor deployment. TRAI efficiency guidelines and European ETSI standards shape technical specifications across Indian and EU procurement.
- Consumer Electronics:Smartphone, laptop, and tablet chargers prioritize compact footprint and low forward voltage drop. Chinese OEMs drive volume procurement with rapid product cycle turnover compressing margin recovery periods.
- Automotive:EV powertrains and 48V mild-hybrid systems require AEC-Q101 qualification with 1,000-hour high-temperature reverse bias testing. NHTSA fuel economy standards and California Air Resources Board regulations indirectly accelerate adoption through lightweighting mandates.
- Industrial:Factory automation, welding equipment, and uninterruptible power supplies specify ruggedized packages for harsh environments. REACH restrictions on hexavalent chromium force electroplating process conversions across European supply chains.
Automotive commands premium pricing; telecommunications shows steepest expansion trajectory.
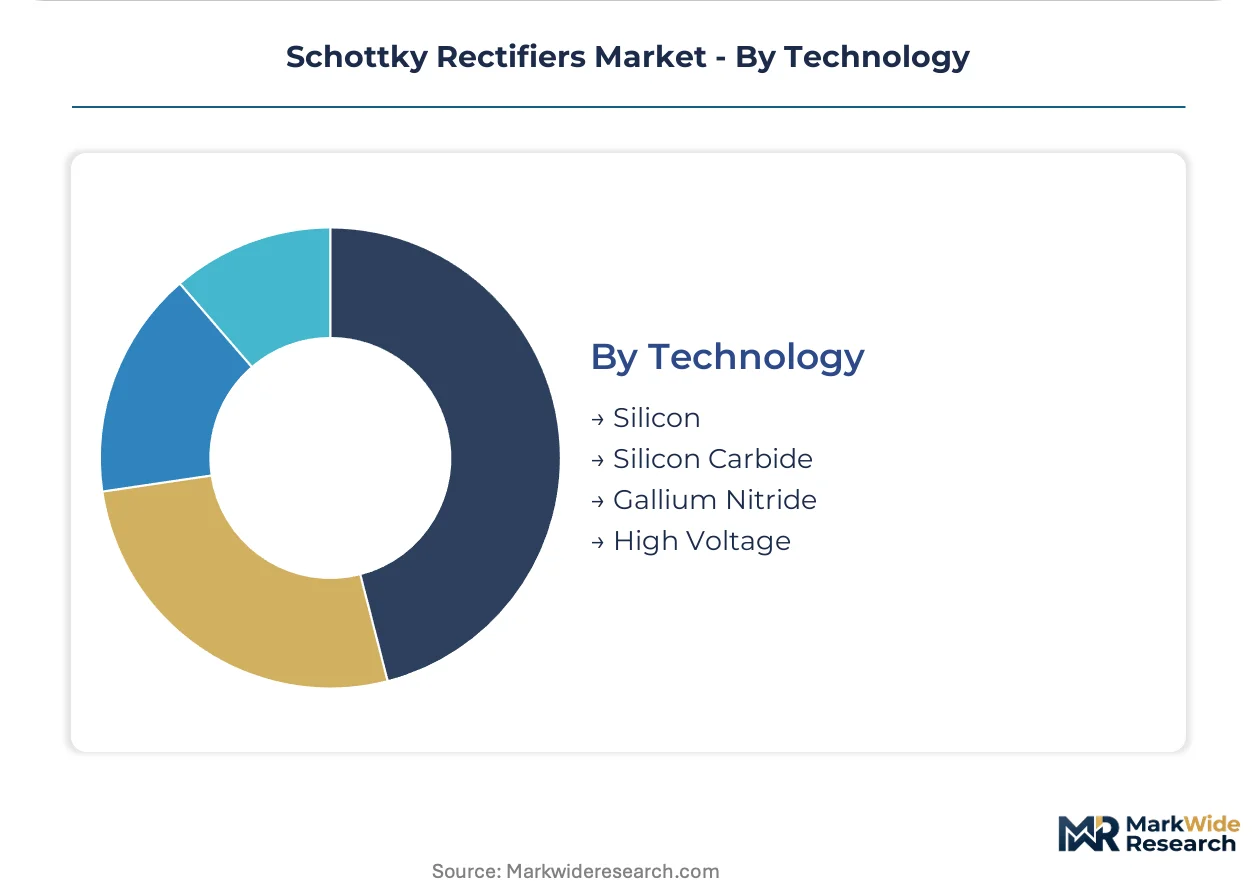
Technology:
Foundry capacity allocation between process nodes determines supply security, with silicon carbide and gallium nitride competing for limited wide-bandgap substrate supply.
- Silicon:Mature planar and trench Schottky structures serve cost-sensitive applications below 200V. Legacy industrial equipment retrofits in North America and Europe sustain demand despite wide-bandgap displacement pressure.
- Silicon Carbide:650V and 1200V devices with superior thermal conductivity anchor EV onboard chargers and solar inverters. Substrate scarcity from limited 150mm and 200mm wafer supply constrains unit output expansion.
- Gallium Nitride:Lateral heterostructure devices achieve sub-nanosecond switching for sub-100V telecommunications and server power supplies. GaN HEMT alternatives with integrated rectification functions threaten discrete Schottky adoption in low-voltage segments.
- High Voltage:Stacked and series-configured architectures extend blocking capability beyond 1,700V for traction inverters and grid-scale inverters. Japanese and German manufacturers lead qualification for avionics 270V DC bus architectures.
Silicon retains volume leadership; silicon carbide is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for Schottky rectifiers tilt toward net imports in automotive-intensive economies while semiconductor fabrication hubs maintain surplus positions in discrete power device trade.
China
Domestic EV production exceeding eight million units annually consumes silicon carbide Schottky devices for onboard chargers and DC-DC converters. MIIT dual carbon goals mandate efficiency improvements in power electronics manufacturing. Shenzhen and Shanghai host module assembly clusters where tier-one automotive suppliers negotiate direct wafer-level procurement agreements.
Germany
Industrial automation OEMs in Bavaria and Baden-Württemberg specify merged PiN-Schottky structures for motor drives operating above 50kHz switching frequencies. KBA emissions regulations and EU Green Deal industrial decarbonization targets compress payback periods for efficiency upgrades. Ingolstadt and Stuttgart automotive corridors anchor qualification activity for AEC-Q101 certified devices.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth demands 98%+ efficiency rectification for 100kW+ rack densities. EPA Energy Star mandates accelerate replacement cycles for legacy silicon rectifiers in server power supplies. NHTSA fuel economy standards indirectly drive lightweighting mandates through power electronics efficiency requirements.
Japan
Telecommunications equipment manufacturers source sub-nanosecond recovery devices for base station power supplies and optical networks. METI efficiency guidelines shape technical specifications for outdoor deployment hardware. Tokyo and Osaka metropolitan areas concentrate ceramic substrate expertise for thermal management of devices exceeding 175°C junction temperatures.
India
Solar inverter deployments under the PLI scheme for power electronics create procurement pull for high-efficiency rectification modules. TRAI efficiency guidelines and CEA renewable energy mandates establish performance thresholds. Gujarat and Karnataka host emerging module assembly investments targeting domestic solar and EV charger supply chains.
Schottky Rectifiers Market Competitive Landscape
On the supply side, the industry is consolidating around wide-bandgap semiconductor foundry capacity, with tier-one automotive suppliers disintermediating traditional distribution channels through direct procurement agreements. Three strategic archetypes dominate: integrated device manufacturers with captive silicon carbide fabrication, fabless specialists leveraging merchant foundry access, and discrete component houses serving legacy industrial retrofit markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with foundry allocation agreements and joint development programs for automotive qualification.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics N.V. exemplify the foundry-anchored archetype, occupying positions shaped by silicon carbide substrate investments and automotive module packaging capabilities. Vishay Intertechnology Inc. represents the discrete specialist tier, with its positioning reflecting through-hole and surface-mount heritage serving industrial equipment maintenance channels.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| onsemi |
| Vishay Intertechnology Inc. |
| Diodes Incorporated |
| ROHM Semiconductor |
| Microchip Technology Inc. |
| Nexperia B.V. |
| Central Semiconductor |
| Others |
Value Network & Pricing Analysis
Shenzhen and Shanghai module assembly clusters concentrate silicon carbide foundry capacity, amplifying pricing leverage for tier-one automotive suppliers negotiating direct wafer-level procurement agreements. This geographic concentration compresses margin recovery for distributors while accelerating cost transparency across the value chain.
Pricing Analysis
Silicon carbide devices command a generational premium over legacy silicon rectifiers, while gallium nitride variants occupy an emerging price tier targeting sub-100V telecommunications applications. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q101 automotive qualification from industrial-grade and consumer-grade alternatives. Cost compression in silicon carbide substrates intensifies as 150mm and 200mm wafer supply constraints persist. Consumer electronics OEMs exhibit highest price sensitivity, whereas automotive powertrain procurement prioritizes thermal performance over unit cost.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Germany and China strain working capital for merchant foundries competing against integrated device manufacturers with captive balance sheets. Raw material dependencies center on silicon carbide substrates from Japanese crystal growth facilities, platinum-group metals for Schottky barrier metallization, and ceramic substrates for thermal management. Single-source vulnerability concentrates in 150mm silicon carbide wafer supply from specialized facilities. Distribution runs through authorized distributors for legacy industrial segments, while direct procurement dominates automotive and data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where AEC-Q101 qualification timelines and foundry capacity allocation create structural switching costs that entrench incumbent positions.
For Market Incumbents: Harden automotive qualification pipelines by accelerating AEC-Q101 certification for 1200V silicon carbide portfolios before gallium nitride lateral devices mature for onboard charger integration. Deepen upstream control over silicon carbide substrate supply through long-term crystal growth agreements with Japanese and German material suppliers. Foundry allocation security represents the critical lever against fabless competitors. For New Entrants and Emerging Players: Establish a beachhead in solar inverter module assembly for EU Green Deal deployments across Spain, Italy, and Poland, where qualification burdens remain lighter than automotive verticals. Target industrial motor drive retrofits in Germany and Japan requiring merged PiN-Schottky structures above 50kHz. A technical service-led go-to-market model bypasses entrenched distribution relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated device manufacturers with captive silicon carbide fabrication and automotive module packaging capabilities over fabless specialists exposed to foundry allocation risk. Long-term viability hinges on securing substrate supply agreements before 200mm wafer capacity ramps. Watch for inflection when direct procurement contracts between automotive OEMs and foundries exceed threshold penetration in tier-one supplier negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Expansion | Secures substrate supply for EV onboard charger qualification under NHTSA efficiency mandates. |
| AEC-Q101 Certification Investment | Extends product release cycles to 18-24 months, creating defensive moats against unqualified competitors. |
| Direct Procurement Agreement | Bypasses authorized distributors for 70% of high-voltage volume, restructuring margin allocation. |
| Ceramic Substrate Partnership | Accesses Japanese and German thermal management expertise for devices exceeding 175°C junction temperatures. |
| India PLI Scheme Manufacturing | Captures domestic solar inverter and EV charger procurement under CEA renewable energy mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with semiconductor procurement managers, power electronics design engineers, and automotive tier-one supplier executives; and secondary validation through SEC 10-K filings, MIIT production statistics, EPA Energy Star certification databases, and customs trade records. Bottom-up and top-down triangulation cross-validated foundry capacity estimates against OEM procurement disclosures.
Forecast inputs considered technology platform adoption curves, foundry allocation shifts between silicon carbide and gallium nitride process nodes, and regulatory efficiency mandates across automotive and data center verticals. Segmentation modeling spanned component form factor, application end-use, and geographic production cluster. CAGRs were derived from installed base replacement cycles and efficiency upgrade payback periods.
Sensitivities concentrate around silicon carbide substrate supply expansion, platinum-group metal price volatility, and automotive OEM direct procurement penetration rates. Forecasts reflect assumptions regarding foundry yield improvements and qualification timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Power Transistor Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Flip Chip Market