
 North America Industrial Embedded Systems Market | 2026-2036
North America Industrial Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Embedded Systems Market Insights
The North America industrial embedded systems landscape is repositioning around a widening capability gap between hardened real-time controllers for mission-critical infrastructure and cost-optimized modules for peripheral sensing tasks. Texas Instruments leverages its analog-to-digital integration depth to dominate precision process control sockets. Infineon Technologies AG anchors high-voltage automotive inverter designs through its silicon carbide gate driver expertise. NXP Semiconductors N.V. competes on functional safety certification density across automotive and aerospace supply chains.
Industrial embedded systems integrate microprocessors, dedicated peripherals, and real-time operating environments within thermally constrained, electromagnetically harsh enclosures to execute deterministic control loops. These systems typically operate across temperature ranges from -40°C to +85°C with sub-millisecond interrupt latency for factory floor reliability. Microcontrollers retain the largest revenue footprint due to their ubiquity in discrete automation endpoints, while edge computing modules represent the fastest-expanding technology category as latency requirements push analytics closer to physical assets. System on Chip designs are capturing margin pools in aerospace and telecommunications by consolidating heterogeneous compute, security, and connectivity subsystems onto single die configurations.
The US EPA enforces energy efficiency and emissions standards that mandate embedded power management in industrial equipment, while FCC Part 15 governs electromagnetic compatibility for wireless-enabled controllers deployed across manufacturing plants. Canada's CSA Group certifies functional safety integrity levels for process control hardware in energy and mining operations. Stakeholders must monitor how NHTSA's evolving autonomous vehicle guidelines and the US Department of Energy's industrial decarbonization mandates reshape hardware qualification timelines and supplier qualification criteria.
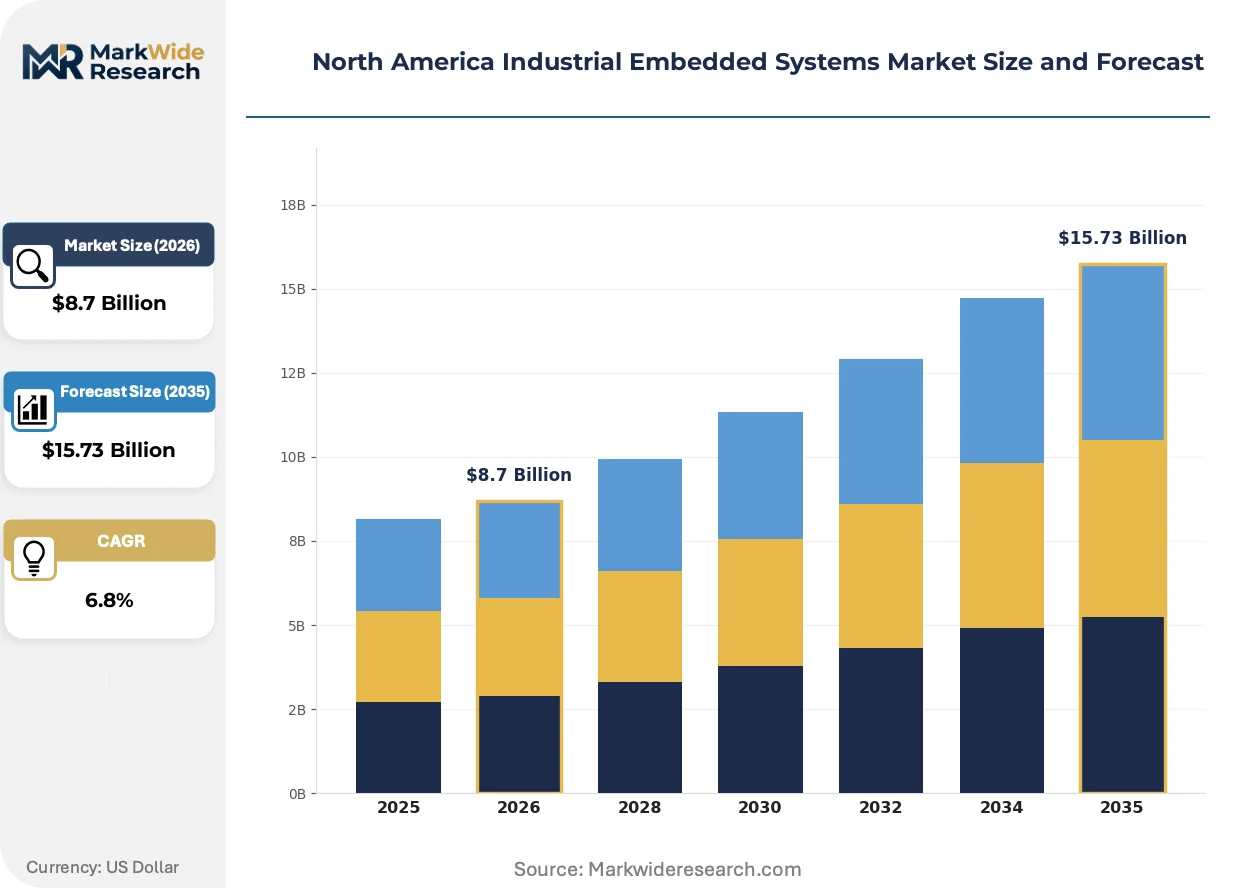
Market Dynamics
The North America industrial embedded systems market is reconfiguring around silicon carbide gate driver integration and functional safety certification density as automakers electrify powertrains and energy operators harden grid infrastructure against cyber-physical threats.
Growth Catalysts
- Automotive electrification mandates:The US EPA tailpipe emissions framework and Canada's net-zero industrial strategy are compelling Tier-1 suppliers to source ASIL-D certified motor controllers for battery-electric and hybrid platforms.
- Grid modernization programs:FERC Order 2222 is accelerating deployment of distributed energy resource management systems that rely on hardened embedded controllers for real-time frequency regulation.
- Silicon carbide substrate availability:Wider bandgap semiconductor supply from domestic foundries is reducing inverter switching losses in high-voltage industrial motor drives.
Market Restraints
- Advanced packaging cost escalation:Fan-out wafer-level packaging for system-in-package modules has widened the cost gap against traditional QFP alternatives.
- Foundry concentration risk:Leading-edge microcontroller fabrication remains concentrated in Taiwan, exposing North American module assemblers to geopolitical supply disruption.
- Legacy protocol persistence:Modbus and Profibus fieldbus architectures continue to delay Ethernet-APL adoption in brownfield process plants.
Strategic Opportunities
- Canadian mining automation:CSA Group functional safety certifications for autonomous haulage systems remain underpenetrated in Saskatchewan potash and Quebec lithium operations.
- Digital twin convergence:Real-time operating systems are merging with physics-based simulation engines to enable predictive maintenance in Texas oilfield equipment.
- Buy American incentives:The US Department of Defense is prioritizing domestic-source embedded computers for weapons platform upgrades.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 and IEC 61508 certified firmware architects command premium compensation and extended recruitment timelines.
- Multi-standard certification burden:Simultaneous UL 61010, FCC Part 15, and NRC cybersecurity qualification extends product launch cycles for nuclear instrumentation suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Embedded Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Digital Signal Processors, Field Programmable Gate Arrays, System on Chip End User: Manufacturing, Automotive, Aerospace, Telecommunications Technology: IoT, Edge Computing, Machine Learning, AI Application: Process Control, Robotics, Remote Monitoring, Predictive Maintenance |
| Companies Covered | Analog Devices Inc., STMicroelectronics N.V., Infineon Technologies AG, NXP Semiconductors N.V., Renesas Electronics Corporation, Texas Instruments Incorporated, Microchip Technology Inc., Intel Corporation, Advantech Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Embedded Systems Market Trends and Innovations
Deterministic edge computing is collapsing the latency boundary between factory-floor controllers and cloud analytics, while regulatory pressure on embodied carbon and electromagnetic resilience is reshaping hardware qualification protocols.
Time-sensitive networking over Ethernet-APL is automating the synchronization of sensor arrays in chemical processing plants. Dow and BASF are piloting TSN-enabled vibration monitoring systems that eliminate dedicated fieldbus infrastructure. This convergence is automating the consolidation of control and information layers that previously required separate cabling hierarchies.
The US Department of Energy's industrial decarbonization mandates are tightening standby power limits for embedded controllers in HVAC and pumping equipment. Manufacturers must now demonstrate sub-watt sleep states to qualify for federal procurement contracts. Semiconductor vendors are responding by integrating adaptive voltage scaling into 32-bit microcontroller product lines.
OEMs are consolidating supplier relationships around vertically integrated embedded module providers that deliver pre-certified hardware-software stacks. Automotive Tier-1s in Michigan are bypassing discrete component distributors to source complete motor control subsystems directly from semiconductor houses. This concentration is most visible in electrified powertrain programs where single-source accountability reduces warranty exposure.
North America Industrial Embedded Systems Market Segmentation
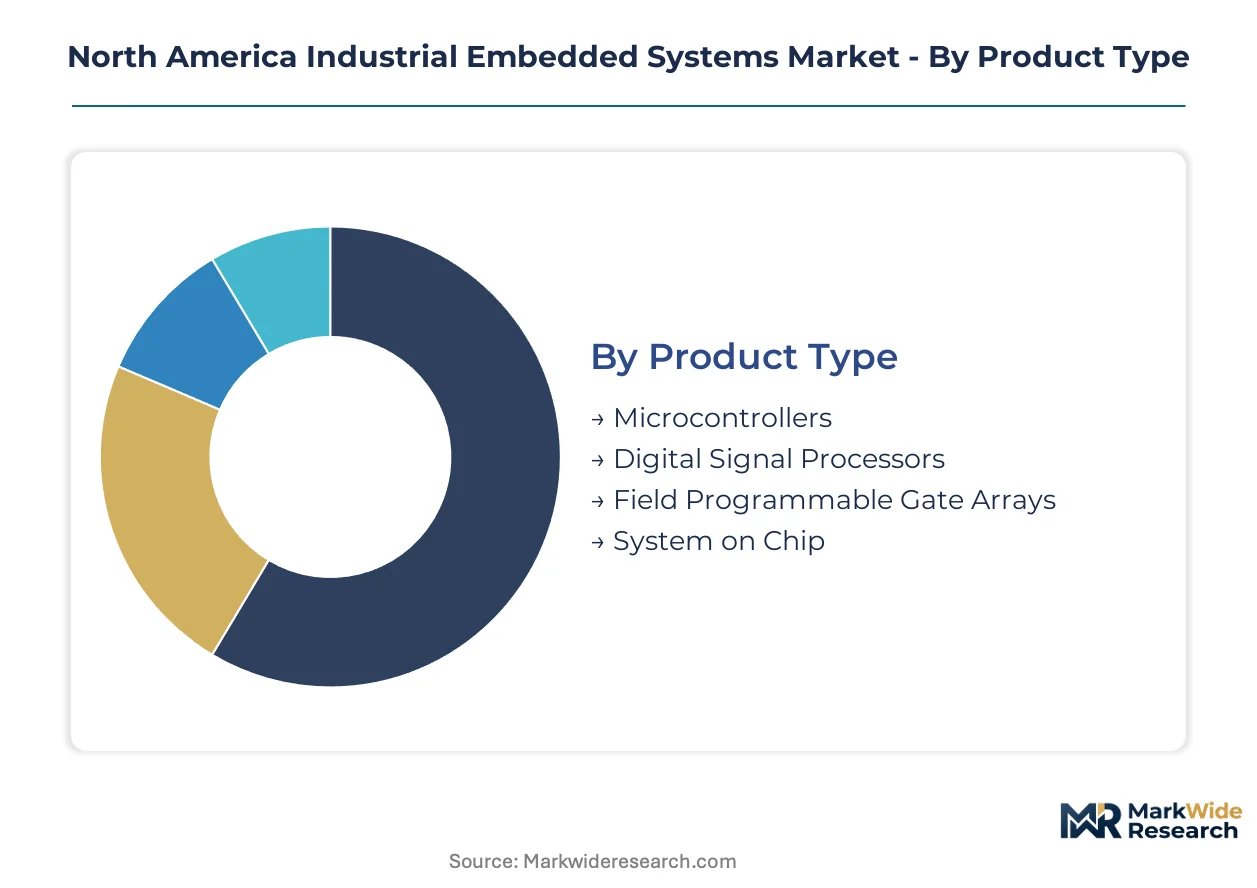
Industrial embedded systems fragment across four dimensions that determine procurement priorities for North American buyers. Product type dictates thermal envelope and real-time performance. End-user concentration shapes certification density requirements. Technology adoption curves separate latency-sensitive deployments from analytics-heavy installations. Application context drives the ruggedization-to-cost tradeoff.
Product Type:
Upgrade cycles in North American manufacturing and automotive plants are compressing as silicon carbide gate drivers and functional safety certifications reset replacement timelines for legacy controllers.
- Microcontrollers:These 8-bit to 32-bit integrated circuits embed flash memory, timers, and analog peripherals on single die configurations for discrete automation endpoints. Demand concentrates in Michigan automotive assembly plants where ASIL-D certified motor controllers are displacing legacy 8-bit architectures in electrified powertrain modules.
- System on Chip:Heterogeneous compute, security, and connectivity subsystems consolidate onto unified die configurations for aerospace and telecommunications payloads. Texas energy-tech manufacturing zones are sourcing hardened SoC modules for distributed energy resource management systems that must withstand -40°C to +85°C operational envelopes.
- Digital Signal Processors:Specialized architectures execute multiply-accumulate operations for real-time filtering in vibration monitoring and motor control loops.
- Field Programmable Gate Arrays:Reconfigurable logic arrays enable post-deployment algorithm updates for nuclear instrumentation and defense platforms requiring NRC cybersecurity qualification.
Microcontrollers sit at the top of the volume ranking, with System on Chip climbing the fastest.
End User:
Cost tier differentiation separates mission-critical applications demanding redundant certification stacks from peripheral sensing tasks tolerating commercial-grade reliability.
- Automotive:Battery-electric and hybrid platforms require ASIL-D certified motor controllers with sub-millisecond interrupt latency for inverter switching. The US EPA tailpipe emissions framework is compelling Tier-1 suppliers in Michigan's automotive corridor to source ruggedized gate driver modules from domestic semiconductor houses.
- Manufacturing:Factory floor controllers execute deterministic control loops across temperature ranges from -40°C to +85°C for process automation. Texas chemical processing plants are piloting TSN-enabled vibration monitoring systems that eliminate dedicated fieldbus infrastructure through Ethernet-APL convergence.
- Aerospace:Radiation-hardened embedded computers for satellite and weapons platforms require DO-178C software certification and MIL-STD-883 environmental screening.
- Telecommunications:Baseband processing and edge aggregation modules integrate real-time operating systems with 5G PHY layer acceleration.
Automotive commands the highest certification premium per unit, with Manufacturing delivering the steepest volume expansion trajectory.
Technology:
Application context determines whether deployments prioritize deterministic latency or analytics throughput, splitting procurement between hardened real-time stacks and cloud-connected inference engines.
- Edge Computing:Localized analytics modules collapse the latency boundary between factory-floor controllers and cloud infrastructure for predictive maintenance in Texas oilfield equipment. FERC Order 2222 is accelerating deployment of distributed energy resource management systems that rely on these hardened controllers for real-time frequency regulation.
- IoT:Wireless-enabled sensor nodes with FCC Part 15 electromagnetic compatibility certification monitor asset health across brownfield process plants. Canada's CSA Group certifies functional safety integrity levels for these modules in Saskatchewan potash and Quebec lithium mining automation.
- Machine Learning:Neural network accelerators embedded in motor controllers enable adaptive torque ripple compensation without cloud dependency.
- AI:Generative inference engines for digital twin convergence require heterogeneous compute fabrics beyond traditional microcontroller capabilities.
Edge Computing leads deployment velocity in energy and manufacturing, with IoT gaining share fastest in mining automation.
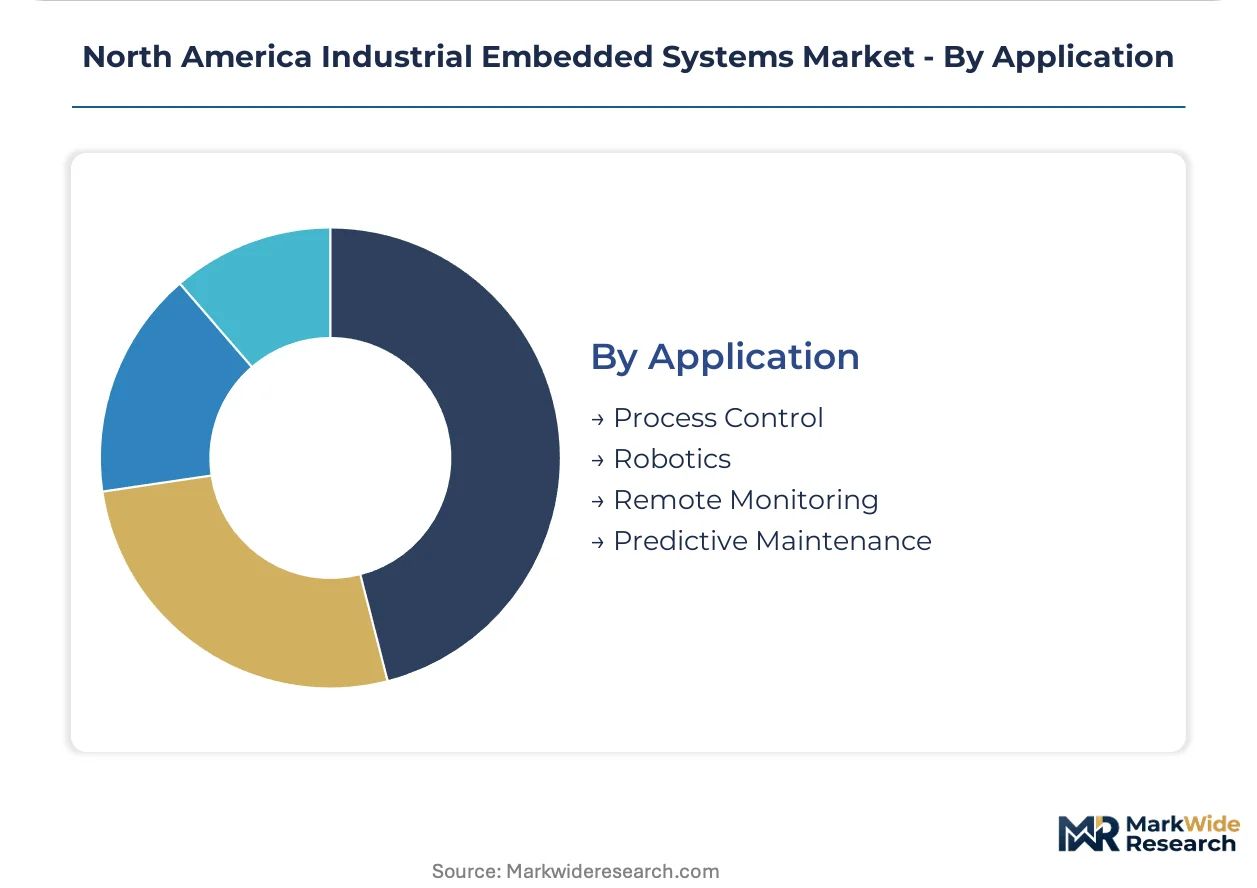
Application:
Margin structure varies with certification burden, where nuclear instrumentation and autonomous haulage systems command three- to five-year qualification timelines versus six-month cycles for standard process control.
- Process Control:Real-time loops regulate temperature, pressure, and flow in chemical processing and power generation. Dow and BASF are consolidating control and information layers through TSN-enabled architectures that synchronize sensor arrays without separate fieldbus cabling hierarchies.
- Predictive Maintenance:Physics-based simulation engines merge with real-time operating systems to forecast equipment failure before catastrophic shutdown. The US Department of Energy's industrial decarbonization mandates are tightening standby power limits for embedded controllers in HVAC and pumping equipment to qualify for federal procurement contracts.
- Robotics:Kinematic controllers with ISO 10218 safety certification execute multi-axis coordination for collaborative manufacturing cells.
- Remote Monitoring:Satellite and cellular telemetry modules track asset location and operational status across distributed infrastructure.
Process Control anchors revenue concentration, with Predictive Maintenance expanding most quickly as digital twin convergence matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in automotive electronics and power semiconductor design anchor North America's embedded systems concentration, with federal procurement incentives and state-level manufacturing tax credits reshaping facility location decisions across the continent.
United States
Michigan's automotive corridor drives ASIL-D certified motor controller procurement as OEMs electrify powertrains, while Texas energy-tech zones source hardened controllers for grid infrastructure. The US EPA tailpipe emissions framework and FERC Order 2222 accelerate embedded hardware deployment. Austin and Dallas-Fort Worth manufacturing zones concentrate silicon carbide inverter module assembly for industrial motor drives.
Canada
Saskatchewan potash and Quebec lithium operations generate demand for autonomous haulage system controllers with CSA Group functional safety certification. Canada's net-zero industrial strategy tightens hardware efficiency standards for mining and energy equipment. Toronto-Waterloo corridor engineering centers develop edge computing modules for predictive maintenance in oilfield equipment.
Mexico
Nuevo León and Baja California assembly plants import ruggedized embedded modules for automotive and aerospace subcontracting, leveraging USMCA tariff preferences. Mexico's federal energy efficiency standards align with US EPA frameworks for industrial equipment certification. Querétaro aerospace cluster demands DO-178C certified embedded computers for satellite component manufacturing.
North America Industrial Embedded Systems Market Competitive Landscape
Top-tier vendors anchor the premium certification tier, while mid-scale module assemblers compete on delivery velocity for standard industrial sockets. The vendor base stratifies across three layers: integrated semiconductor houses with captive foundry access, specialized embedded module providers with vertical software stacks, and regional distributors serving brownfield retrofit demand. Dominant competitive moves include backward integration into firmware certification capabilities and strategic partnerships with domestic automotive Tier-1s to secure electrification program slots.
Within the integrated semiconductor tier, Texas Instruments Incorporated and NXP Semiconductors N.V. exemplify vendors consolidating analog-to-digital integration depth with functional safety certification density. Infineon Technologies AG occupies a position bridging silicon carbide substrate expertise and automotive gate driver qualification. These three anchors represent the archetype of vendors bypassing traditional distribution channels to supply complete motor control subsystems directly to Michigan-based electrified powertrain programs.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Microchip Technology Inc. |
| Intel Corporation |
| Advantech Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide gate driver integration into automotive inverters is simultaneously compressing per-unit controller costs and concentrating procurement leverage among Michigan-based Tier-1 suppliers with direct semiconductor house relationships. This technology transition rewards buyers bundling hardware-software stacks while squeezing margins for discrete component distributors serving brownfield retrofit demand.
Pricing Analysis
The bundled-versus-unbundled service split separates complete motor control subsystems from discrete microcontroller sales. Three-tier pricing structure across ASIL-D certified, industrial-grade, and commercial-grade levels reflects functional safety certification density and thermal envelope specifications. Cost compression in commercial-grade sockets is intensifying because Texas energy-tech zones are consolidating supplier relationships around vertically integrated module providers. Automotive electrification programs demonstrate the lowest price sensitivity due to warranty exposure, while brownfield manufacturing retrofits exhibit acute sensitivity to per-unit controller costs.
Supply Chain Analysis
Workforce availability for ISO 26262 certified firmware architects in Austin and Dallas-Fort Worth manufacturing zones anchors domestic module assembly capacity. Leading-edge microcontroller fabrication draws from Taiwan and South Korea, while silicon carbide substrate supply rests on domestic foundry expansion in New York and Texas. Single-source vulnerability in advanced packaging for system-in-package modules exposes North American assemblers to geopolitical disruption. Distribution runs through direct OEM-semiconductor relationships for automotive electrification programs, with regional distributors retaining brownfield process control sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Michigan's automotive corridor certification premiums and Texas energy-tech manufacturing cost efficiencies, with the US EPA tailpipe emissions framework widening the regulatory compliance cost differential between the two zones.
For Market Incumbents: Anchor ASIL-D certification density in Michigan electrified powertrain programs through captive firmware engineering teams. Backward integration into silicon carbide gate driver design reduces exposure to Taiwan foundry concentration risk. Prioritize direct relationships with Tier-1 suppliers over distributor channels to capture complete motor control subsystem procurement. For New Entrants and Emerging Players: Begin with CSA Group functional safety certification for autonomous haulage systems in Saskatchewan potash and Quebec lithium operations, where incumbent penetration remains limited. Target digital twin convergence for predictive maintenance in Texas oilfield equipment as the most penetrable application. Pursue partnership-based go-to-market models with existing edge computing module providers to bypass extended qualification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale embedded module assemblers with vertical software stacks but limited certification breadth. Long-term viability over the coming decade hinges on securing positions in electrified automotive and grid modernization programs before qualification windows close. Watch FERC Order 2222 implementation velocity as the inflection signal for distributed energy resource management system demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Qualifies motor controllers for Michigan battery-electric powertrain procurement mandates. |
| Silicon Carbide Backward Integration | Captures margin pools in high-voltage inverter designs while reducing Taiwan foundry dependency. |
| CSA Group Safety Certification | Unlocks autonomous haulage system contracts in Saskatchewan and Quebec mining operations. |
| Direct OEM Relationship Development | Bypasses distributor channels to secure complete subsystem sourcing from Tier-1 suppliers. |
| Digital Twin Platform Partnership | Merges real-time operating systems with physics-based simulation for predictive maintenance. |
Research Methodology
Bottom-up automotive and energy sector modeling reconciled against top-down semiconductor supply tracking forms the analytical core. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, plant engineers at Dow and BASF facilities, and aftermarket service heads combined with secondary validation from SEC 10-K filings, FERC Order 2222 implementation records, EPA emissions compliance databases, and vehicle production registries. Triangulation across these sources ensures demand-side estimates align with supply-side capacity disclosures.
Historical trendline analysis of microcontroller unit shipments and silicon carbide inverter deployment patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user concentration, technology adoption curve, and application context, with CAGRs derived from regression analysis against automotive electrification program timelines and grid modernization investment flows. Forecast inputs incorporate FERC regulatory implementation schedules and US EPA tailpipe emissions phase-in requirements.
Several conditions sit outside the modeled scope, including unannounced geopolitical trade restrictions on semiconductor fabrication equipment, abrupt shifts in NHTSA autonomous vehicle guidelines, and unforeseen breakthroughs in gallium nitride power electronics that could displace silicon carbide architectures. Forecasts reflect documented assumptions regarding certification timeline stability and foundry capacity expansion plans. Material deviation in EPA enforcement intensity or Taiwan supply disruption severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market