
 Actuators Market | 2026-2036
Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Actuators Market Intelligence
The EU Green Deal's focus on industrial energy efficiency is pivoting actuator demand toward more precise and less wasteful motion control systems. This shift favors suppliers with advanced electric and servo-driven technologies. Emerson Electric Co. leverages its extensive portfolio to serve diverse end-markets from process automation to HVAC. Parker Hannifin Corp. specializes in high-performance hydraulic and pneumatic systems for heavy-duty applications. Rockwell Automation differentiates with its integrated architecture, combining actuators with control and software platforms.
An actuator is a device that converts a source of energy, such as electricity or fluid pressure, into controlled physical motion. These devices translate control signals into linear or rotary movement to operate valves, dampers, or other mechanical components. The electric product type is gaining share from traditional hydraulic and pneumatic systems due to superior energy efficiency and control precision. While the robotics application represents the fastest-growing demand segment, HVAC systems constitute a large, mature volume base for simpler actuator models.
Product design and market access are shaped by multiple regulatory frameworks. Key standards include ISO 50001 for energy management systems and the EU's Machinery Directive, which mandates CE marking for safety compliance. In the United States, OSHA regulations influence machine guarding and operational safety requirements for automated equipment. The critical decision for equipment manufacturers now involves balancing initial component cost against the total lifecycle cost, including energy consumption and maintenance.
Market Dynamics
The transition from fluid power to electric systems, driven by energy efficiency mandates like the EU Green Deal and precision needs in automation, is the central force shaping the actuator market.
Growth Catalysts
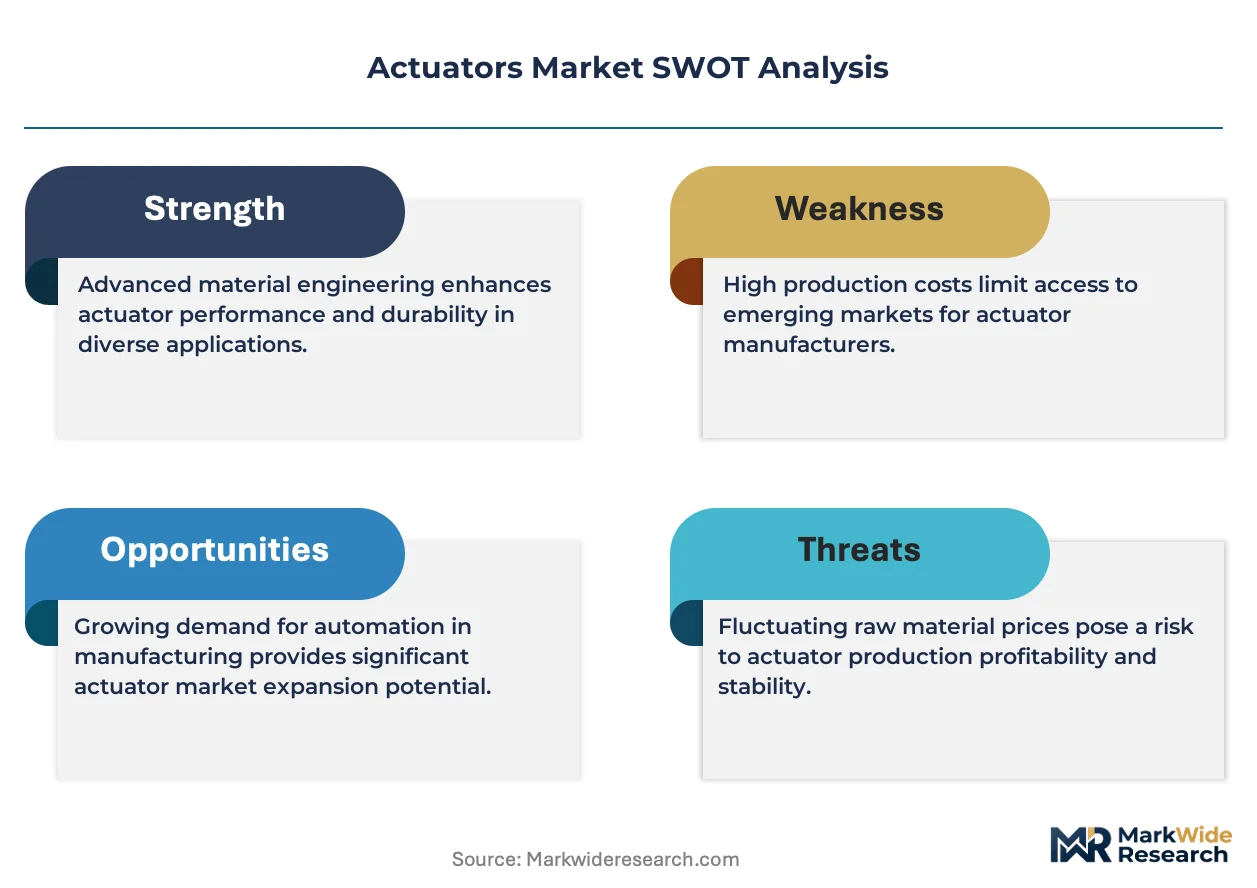
- Industrial Automation:Demand for high-precision motion control in China's robotics and automotive sectors accelerates adoption of advanced actuators.
- Energy Efficiency Mandates:Frameworks like the EU Green Deal and ISO 50001 favor electric actuators over less efficient hydraulic and pneumatic systems.
- Building Modernization:HVAC system upgrades in North America to meet stricter energy codes drive volume for specific actuator models.
Market Restraints
- Acquisition Cost:The higher initial price of advanced electric and servo-driven actuators is a barrier compared to legacy pneumatic systems.
- Power Density Limits:Hydraulic actuators retain a performance advantage in heavy-duty, high-force industrial applications where electric alternatives lack equivalent power.
- Component Dependency:Reliance on specialized microcontrollers from a concentrated supplier base in East Asia creates supply chain vulnerability.
Strategic Opportunities
- Emerging Robotics:Developing compact actuators for collaborative robots (cobots) and automated guided vehicles (AGVs) in logistics opens a new segment.
- Smart Actuators:Integrating IIoT sensors for onboard diagnostics and predictive maintenance creates higher-value, service-oriented revenue streams.
- Geographic Expansion:Automation initiatives in Southeast Asia, including Vietnam and Indonesia, present underpenetrated markets for motion control systems.
Industry Challenges
- System Integration:The complexity of connecting new digital actuators with legacy factory control systems and enterprise software can delay implementation.
- Regulatory Fragmentation:Navigating disparate safety standards, such as CE marking in Europe and OSHA rules in the US, increases design costs.
- Talent Scarcity:A shortage of technicians with mechatronics and control systems expertise hinders deployment and ongoing system maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actuators Market |
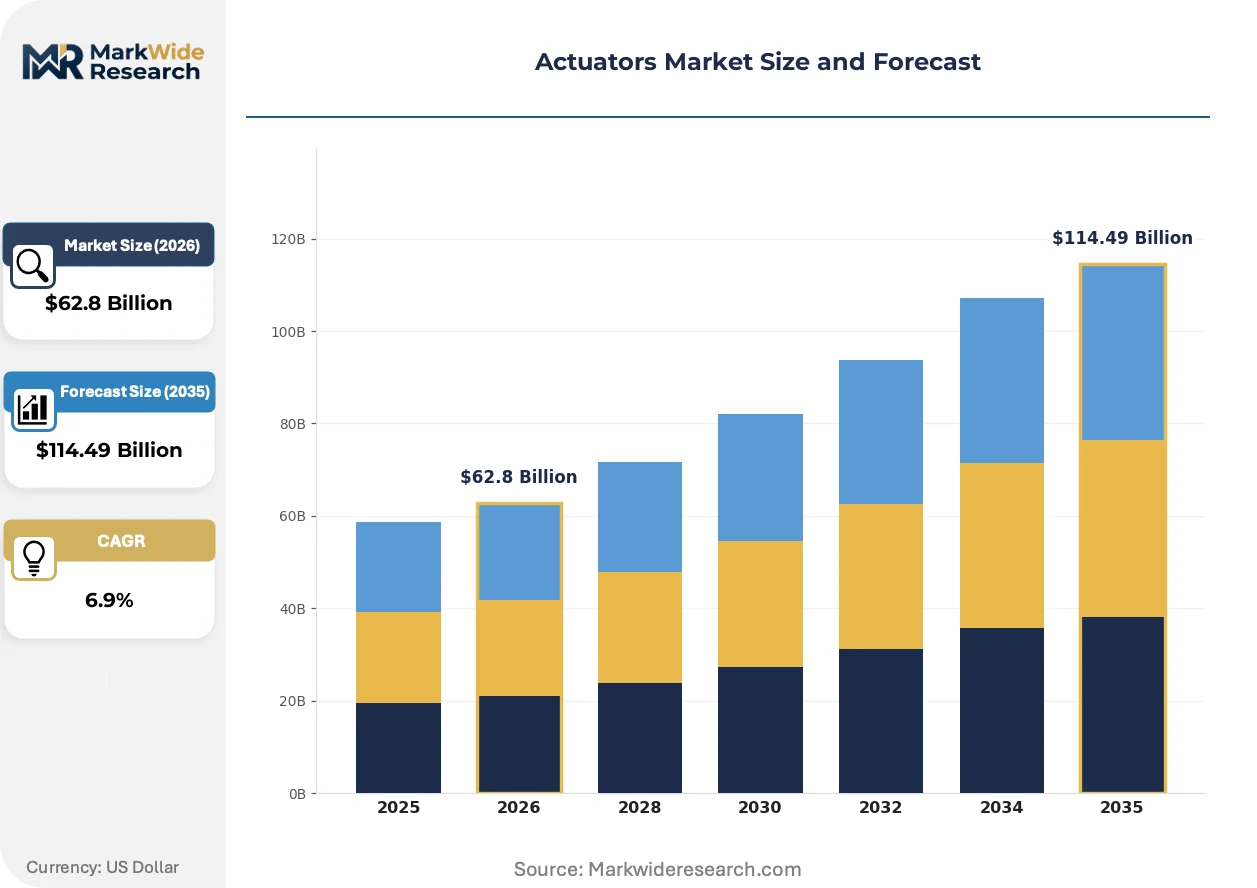
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $114.49 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Hydraulic, Mechanical, Thermal Technology: Stepper, Servo, Linear, Rotary, Piezoelectric, Voice Coil Application: Robotics, Aerospace Systems, Marine Equipment, HVAC Systems, Agricultural Machinery End User: Manufacturing Plants, Defense Contractors, Shipping Companies, Building Automation, Farming Enterprises |
| Companies Covered | Emerson Electric Co., Parker Hannifin Corp., Rockwell Automation, SMC Corporation, ABB, Rotork PLC, Eaton Corporation, Moog Inc., Festo AG & Co. K.G., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actuators Market Strategic Shifts & Innovations
The evolution toward intelligent and connected devices is altering actuator design. This shift transforms them from simple motion components into data-generating nodes within larger automated systems.
Smart actuators integrate onboard microprocessors and sensors for self-diagnosis and precise position feedback. The industrial automation sector in Germany and Japan is rapidly adopting these devices. This technology is converging with edge computing, allowing actuators to perform local data processing within an IIoT framework.
The EU's Machinery Regulation mandates stringent safety integrity levels, impacting design. This forces manufacturers to build in features like safe torque off (STO) and redundant feedback sensors. The fluid power segment is most affected, needing to add electronic controls to meet CE marking requirements.
End-users are shifting from component purchasing to specifying total lifecycle cost, including energy and maintenance. This model favors suppliers bundling actuators with system design and predictive services, displacing traditional distributors. This is most visible in automotive manufacturing in South Korea and semiconductor fabrication.
Actuators Market Segmentation
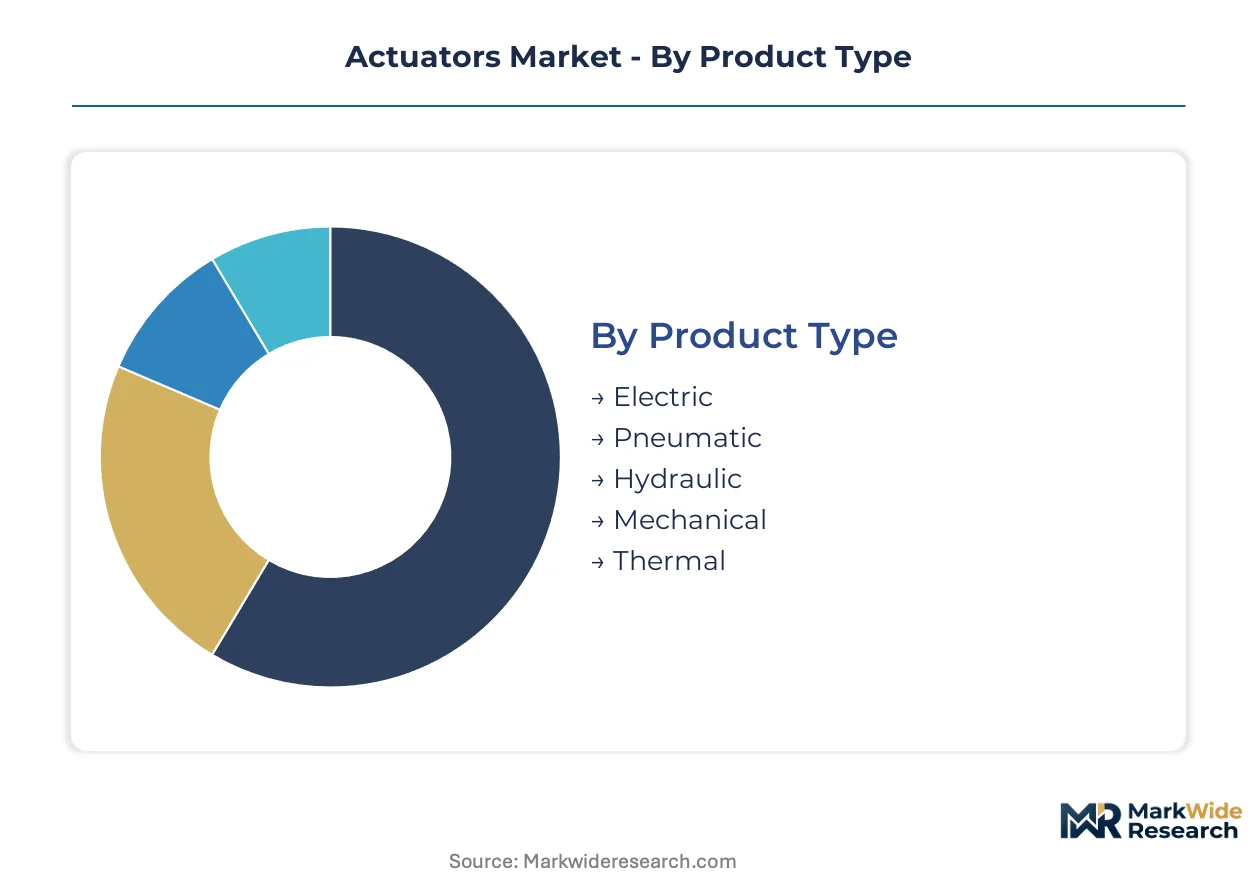
The segmentation of the actuators market provides critical insights into how different product types, technologies, applications, and end-users influence market dynamics. Understanding these distinctions helps stakeholders identify specific growth opportunities and tailor product development to meet evolving industrial requirements.
Product Type:
The actuator market's segmentation by product type reflects the ongoing upgrade and replacement cycles across various industrial sectors, emphasizing efficiency and performance gains.
- Electric:Electric actuators convert electrical energy into precise linear or rotary motion, utilizing motors and gearboxes for controlled movement. Demand concentrates in industrial automation in China and Germany, driven by stringent energy efficiency mandates like the EU Green Deal.
- Hydraulic:Hydraulic actuators employ pressurized fluid to generate high force and torque, suitable for heavy-duty applications requiring substantial power output. Their robust power density remains critical for construction equipment in the United States and marine systems, where electric alternatives cannot match the sheer force.
- Pneumatic:Pneumatic actuators use compressed air to generate linear or rotary motion, offering simplicity and cost-effectiveness for many industrial tasks.
- Mechanical:Mechanical actuators convert rotary motion into linear motion through physical components like screws, gears, or cams, providing reliable positioning.
- Thermal:Thermal actuators generate motion through temperature changes, often used in applications requiring controlled expansion or contraction for valve operations.
Volume placements concentrate in Hydraulic systems; the faster expansion belongs to Electric designs.
Technology:
Technology segmentation highlights the performance differentiation required for diverse motion control tasks, from high-speed positioning to heavy-load manipulation.
- Servo:Servo technology integrates a motor with a feedback control system, enabling highly accurate position, velocity, and torque control. Applications in robotics in Japan and semiconductor manufacturing demand this precision, driven by requirements for repeatable micro-positioning.
- Linear:Linear actuators produce straight-line motion, converting rotational input from motors into linear output using lead screws or belts. They find widespread use in material handling systems in North America and medical devices, where controlled linear displacement is essential.
- Stepper:Stepper motors move in discrete steps, providing precise positioning without a feedback mechanism in many open-loop control systems.
- Rotary:Rotary actuators produce angular motion, converting energy into rotational output for applications like valve opening and closing.
- Piezoelectric:Piezoelectric actuators utilize the inverse piezoelectric effect to generate very small, highly precise displacements, critical for nanotechnology and optics.
- Voice Coil:Voice coil actuators provide direct-drive linear motion with high acceleration and minimal hysteresis, often used in precise positioning and scanning applications.
The integration of Piezoelectric technology into micro-robotics demonstrates significant potential, with Stepper systems enabling cost-effective positioning in packaging machinery.
Application:
Application analysis reveals the primary demand drivers for actuators, spanning industries with unique operational requirements and regulatory landscapes.
- Robotics:Robotics applications utilize actuators for joint movement and end-effector control, requiring high precision, speed, and compact design. The rapid expansion of industrial automation in China and collaborative robot deployment drives this segment, emphasizing dynamic performance.
- HVAC Systems:HVAC systems employ actuators to control dampers, valves, and louvers for airflow and temperature regulation in buildings. This segment represents a large volume base in North America, driven by building modernization and energy efficiency codes.
- Aerospace Systems:Aerospace systems demand highly reliable and lightweight actuators for flight control surfaces, landing gear, and engine components, adhering to strict FAA regulations.
- Marine Equipment:Marine equipment requires robust actuators for steering, propulsion control, and cargo handling systems, designed to withstand harsh saltwater environments.
- Agricultural Machinery:Agricultural machinery uses actuators for precision farming tasks, such as steering guidance, implement control, and harvesting automation.
Demand across HVAC Systems remains robust, while Robotics exhibits accelerated growth due to the global push for factory automation.
End User:
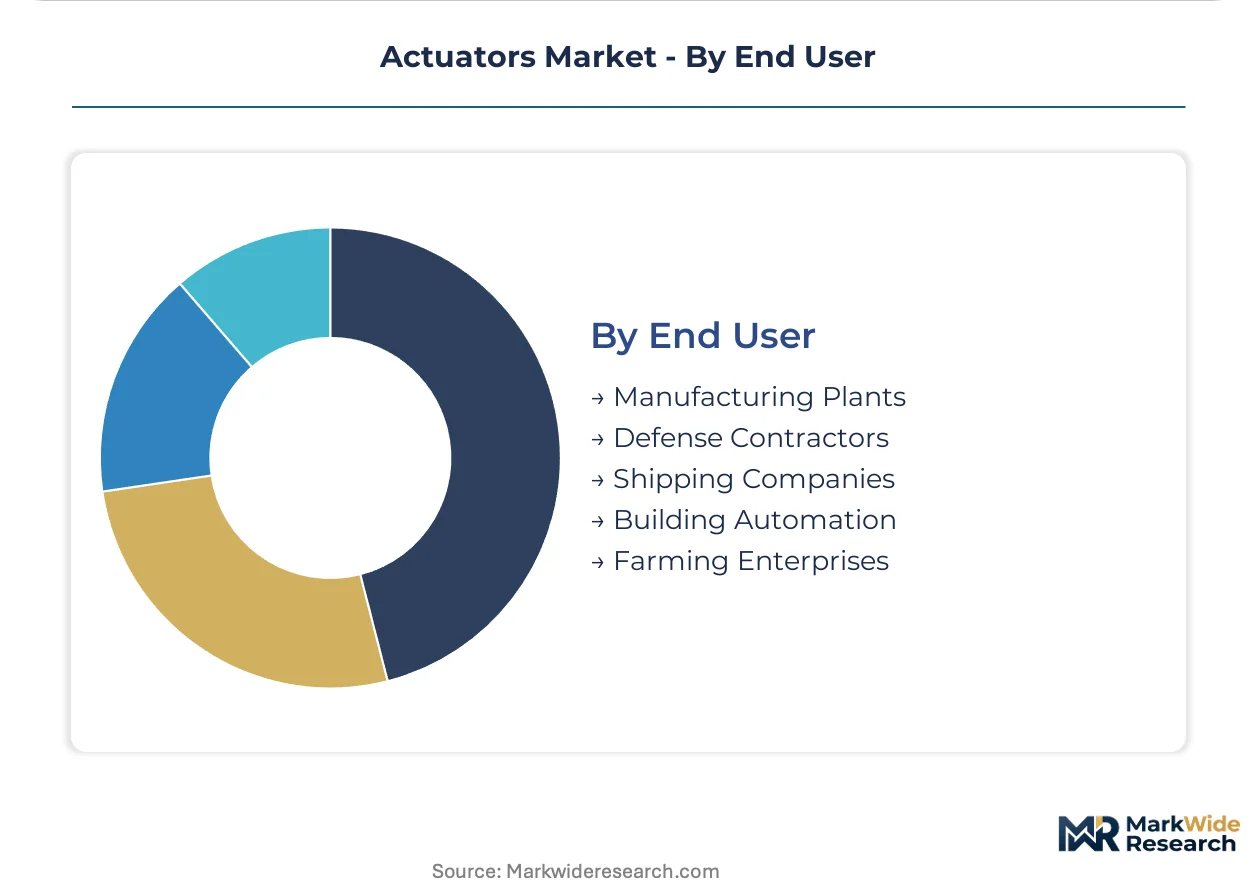
End user segmentation delineates actuator demand based on the operational scale and specific needs of industrial and commercial entities.
- Manufacturing Plants:Manufacturing Plants are primary consumers of actuators for assembly lines, material handling, and process control, demanding robustness and integration capabilities. The automotive sector in Germany and electronics production in South Korea are key drivers for advanced solutions.
- Building Automation:Building Automation relies on actuators for intelligent control of environmental systems, security access, and shading. This segment in Europe is driven by smart building initiatives and stringent energy performance directives.
- Defense Contractors:Defense Contractors require specialized actuators for military vehicles, weapon systems, and aerospace platforms, prioritizing reliability and extreme performance under challenging conditions.
- Shipping Companies:Shipping Companies utilize actuators in ship engines, cargo handling equipment, and navigation systems, demanding durability and compliance with IMO standards.
- Farming Enterprises:Farming Enterprises integrate actuators into modern agricultural equipment for tasks like automated seeding, spraying, and harvesting, enhancing efficiency and yield.
Significant investment from Manufacturing Plants drives market volume, with Farming Enterprises presenting emerging opportunities for specialized, robust solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The actuators market exhibits a dual dynamic, with established industrial economies driving demand for advanced, energy-efficient solutions, while rapidly industrializing nations serve as significant production hubs and emerging consumption centers. This creates a supply-demand interplay that influences global manufacturing and distribution strategies.
China
China's extensive industrial automation initiatives, particularly in robotics and automotive sectors, generate substantial demand for high-precision actuators. The country's dual carbon goals encourage the adoption of electric and servo-driven systems over less efficient fluid power alternatives. Manufacturing clusters in the Yangtze River Delta, including Shanghai and Suzhou, drive innovation in motion control technology.
Germany
Germany's robust automotive manufacturing and advanced industrial automation sectors require sophisticated actuator solutions. The EU Green Deal and stringent CE marking requirements compel manufacturers to integrate energy-efficient and safe actuator designs. Baden-Württemberg remains a hub for precision engineering, with companies developing next-generation electric actuators for diverse applications.
United States
Demand for actuators in the United States stems from HVAC system modernization and heavy-duty applications in construction equipment. OSHA regulations influence the design of automated systems, emphasizing operational safety and machine guarding. The Midwest region, particularly around Detroit and Chicago, continues to drive demand for industrial and automotive actuators.
Japan
Japan's leadership in robotics and semiconductor manufacturing creates a strong market for highly accurate servo and piezoelectric actuators. METI initiatives support smart factory development, pushing for integrated motion control solutions. The Kanto region, encompassing Tokyo, serves as a center for advanced manufacturing and research in micro-robotics.
South Korea
South Korea's advanced automotive manufacturing and electronics production sectors are significant consumers of precision actuators. The country's industrial safety regulations, overseen by MFDS, ensure compliance for automated equipment. The Seoul Capital Area drives innovation in smart actuator development for both domestic and export markets.
Actuators Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates that leverage extensive portfolios across multiple end-markets. Market participants often pursue strategic partnerships to expand technology capabilities or engage in portfolio diversification to mitigate reliance on single sectors. Specialized innovators also carve niches by focusing on specific high-precision applications.
Diversified industrial conglomerates like Emerson Electric Co. and Parker Hannifin Corp. occupy a strong position, offering a broad range of actuator types from electric to hydraulic systems. Rockwell Automation, Inc. represents a distinct archetype, integrating actuators with comprehensive control and software platforms. These companies anchor the market through their wide product offerings and established customer bases.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin Corp. |
| Rockwell Automation |
| SMC Corporation |
| ABB |
| Rotork PLC |
| Eaton Corporation |
| Moog Inc. |
| Festo AG & Co. K.G. |
| Others |
Cost & Logistics Intelligence
The high-performance electric actuator tier divergence, characterized by advanced servo and piezoelectric designs, manifests in both premium pricing and a supply chain concentrated around specialized component manufacturers. This contrasts sharply with the commodity pricing and broader supply base for simpler pneumatic and mechanical actuators.
Pricing Analysis
Cost-down pressure on standard electric actuators accelerates because of increasing competition from Asian manufacturers and the push for automation in cost-sensitive industries. The dominant pricing model remains per-unit transactional, though service contracts for smart actuators introduce a value-based component. Price differentiation stems from certification levels, such as CE marking for European markets, and the degree of customization for specific industrial applications. Manufacturing plants in China exhibit high price sensitivity for volume purchases, while aerospace systems prioritize performance over initial cost.
Supply Chain Analysis
CE marking compliance and ISO 50001 certification act as critical gating factors for market access, particularly for European customers. Geographic supply concentration for advanced microcontrollers and precision components centers on East Asia, specifically Japan, South Korea, and Taiwan. Reliance on specialized microcontrollers from this concentrated base creates a single-source vulnerability for smart actuator manufacturers. The supply chain for finished actuators primarily runs through established industrial distributors and direct sales channels to large OEM integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The actuators market is framed by a cost-of-compliance story, where the EU's Machinery Regulation creates a significant barrier-to-entry moat for compliant players.
For Market Incumbents:Lock in established customer relationships through bundled solutions that combine advanced electric actuators with integrated control software and predictive maintenance services. Diversify the component supply base beyond East Asia to mitigate geopolitical risks and potential disruptions in microcontroller availability. Invest in R&D for compact, energy-efficient designs to counter emerging competition in collaborative robotics. Expand service footprints in high-growth regions like Southeast Asia to capture aftermarket revenue.
For New Entrants and Emerging Players:The EU Green Deal in Europe opens a window for specialized manufacturers focused on ultra-efficient electric and servo actuators. Target the burgeoning collaborative robotics and automated guided vehicles (AGVs) segments, which demand compact, precise, and easily integrated motion control solutions. A go-to-market angle focusing on total lifecycle cost savings through superior energy efficiency and reduced maintenance can attract new customers. Focus on niche applications requiring high precision, such as micro-robotics or semiconductor fabrication.
For Investors and Strategic Acquirers:Re-rating potential sits with mid-cap specialists offering integrated smart actuator platforms, given the accelerating adoption of IIoT and predictive maintenance in manufacturing. Long-term viability hinges on companies that can vertically integrate key component production or secure long-term supply agreements for critical microelectronics. Acquisition targets should possess strong intellectual property in advanced control algorithms and sensor integration. A signal to watch is the increasing adoption rate of smart actuators in non-traditional industrial sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Integrated Smart Actuator Platforms | This initiative enhances value proposition by bundling hardware with advanced diagnostics for manufacturing plants. |
| Diversify Microcontroller Sourcing | This move mitigates supply chain risks from concentrated East Asian component dependencies for electronics production. |
| Expand into Collaborative Robotics | This strategy capitalizes on the fastest-growing application segment demanding compact, precise motion control. |
| Invest in Energy Efficiency R&D | This focus aligns with global mandates like the EU Green Deal, driving demand for electric actuator designs. |
| Acquire Niche IIoT Software Firms | This acquisition deepens capabilities in predictive maintenance and data analytics for smart actuator systems. |
Research Approach
Industry reports from METI and the International Energy Agency, coupled with company financial filings, formed the secondary backbone for this study, providing foundational market sizing and trend identification. Primary research involved in-depth interviews with plant engineers, procurement managers at automotive OEMs, and R&D directors specializing in motion control technology. This approach enabled bottom-up validation of market segment volumes and top-down triangulation of overall market values. Further insights were gathered from discussions with system integrators and regulatory compliance specialists.
A bottom-up analytical lens informed the market forecast, aggregating demand across various product types, technologies, applications, and end-user industries. The model further segmented demand by regional regulatory frameworks and specific industrial automation initiatives. Compound Annual Growth Rates were derived from historical data analysis and projected based on anticipated technological advancements and policy shifts across the analysis window. Key forecast inputs included industrial robotics deployment rates and global energy efficiency investment trends.
The model assumes a particular technology adoption path, favoring electric and servo systems; alternative pathways for hydraulic power could alter the outlook. Forecasts reflect assumptions regarding economic stability and consistent regulatory enforcement over the projection horizon. A model refresh is warranted upon material change in global trade policies affecting component supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Small Harmonic Reducer Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Pneumatic Strippers Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Global Industrial Weighing Machines Market