
 Coil Winding Machine Market | 2026-2036
Coil Winding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Coil Winding Machine Market Outlook
Buyer concentration among electric vehicle and renewable energy OEMs is shifting procurement power toward tier-one suppliers with high-volume, precision winding requirements. Nittoku Engineering leverages its heritage in automated transformer winding to anchor Japanese supply chains for power distribution equipment. Marsilli competes through specialized multi-spindle architectures that serve European automotive tier-one suppliers. Hangzhou JOIN Intelligent Technology extends cost-engineered CNC platforms across mid-tier electronics manufacturers in East Asia.
A coil winding machine is an electromechanical device that precisely wraps conductive wire around a core, bobbin, or form to create electromagnetic coils with controlled turns count, tension, and layer geometry, typically achieving tolerances within micrometers for critical applications. These machines produce inductors, transformers, electric motor windings, and solenoids that convert electrical energy into magnetic fields or regulate voltage and current in power systems. Automatic winding systems dominate volume production for automotive and consumer electronics where throughput and repeatability determine unit economics. CNC technology leads the premium segment by enabling programmable, complex winding patterns for aerospace and medical applications that require traceability and minimal scrap rates.
The EU F-Gas Regulation and REACH framework restrict fluorinated gas use and hazardous substance content in manufacturing equipment sold across Europe, compelling OEMs to certify winding machines for cleanroom-compatible, solvent-free operation. In the United States, OSHA electrical safety standards and NHTSA automotive quality mandates shape machine design for worker protection and component reliability in vehicle applications. China's GB standards and MIIT industrial policy directives enforce energy efficiency benchmarks and domestic content ratios for equipment deployed in state-backed renewable energy projects. Stakeholders must monitor how divergent regional certification regimes fragment platform standardization and force modular machine architectures that can be reconfigured for local compliance.
Market Dynamics
Precision winding requirements for traction motor production are consolidating procurement power among electric vehicle OEMs, forcing equipment suppliers to certify platforms for micrometer tolerances and closed-loop automation.
Growth Catalysts
- EU F-Gas Regulation:REACH compliance mandates are compelling European automotive tier-ones to replace solvent-based cleaning systems with closed-loop, fluorinated-gas-free winding architectures.
- Traction motor copper fill optimization:Hairpin winding processes for electric vehicle stators demand CNC-controlled tension systems that maximize slot fill factors above 70 percent.
- Hangzhou automation cluster:Cost-engineered CNC platforms from East Asian suppliers are penetrating mid-tier electronics manufacturers seeking precision without premium pricing.
Market Restraints
- Copper price volatility:Raw material swings in magnet wire commodity markets compress margins for winding equipment financed through long-delivery contracts.
- Specialized spindle supply concentration:High-precision ceramic bearing assemblies for multi-spindle architectures source predominantly from German and Japanese component houses.
- Technical limitation in ultra-fine wire handling:Below 25-micrometer conductor diameters, tension control systems face yield degradation from work-hardening and breakage rates.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for electric vehicle manufacturing are creating first-mover demand for localized winding equipment assembly.
- Regulatory tailwind from China's dual carbon goals:MIIT energy efficiency benchmarks for industrial motors mandate high-fill-factor windings that require precision equipment upgrades.
- Technology convergence of AI vision and CNC control:Real-time defect detection integrated into winding heads enables predictive tension adjustment during layer buildup.
Industry Challenges
- Mechatronics technician scarcity:Programming complex multi-axis winding patterns requires cross-trained engineers fluent in both electromagnetic design and G-code optimization.
- CE-MDR dual certification timelines:Medical device coil applications face extended validation periods for traceability systems under European machinery and medical device regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coil Winding Machine Market |
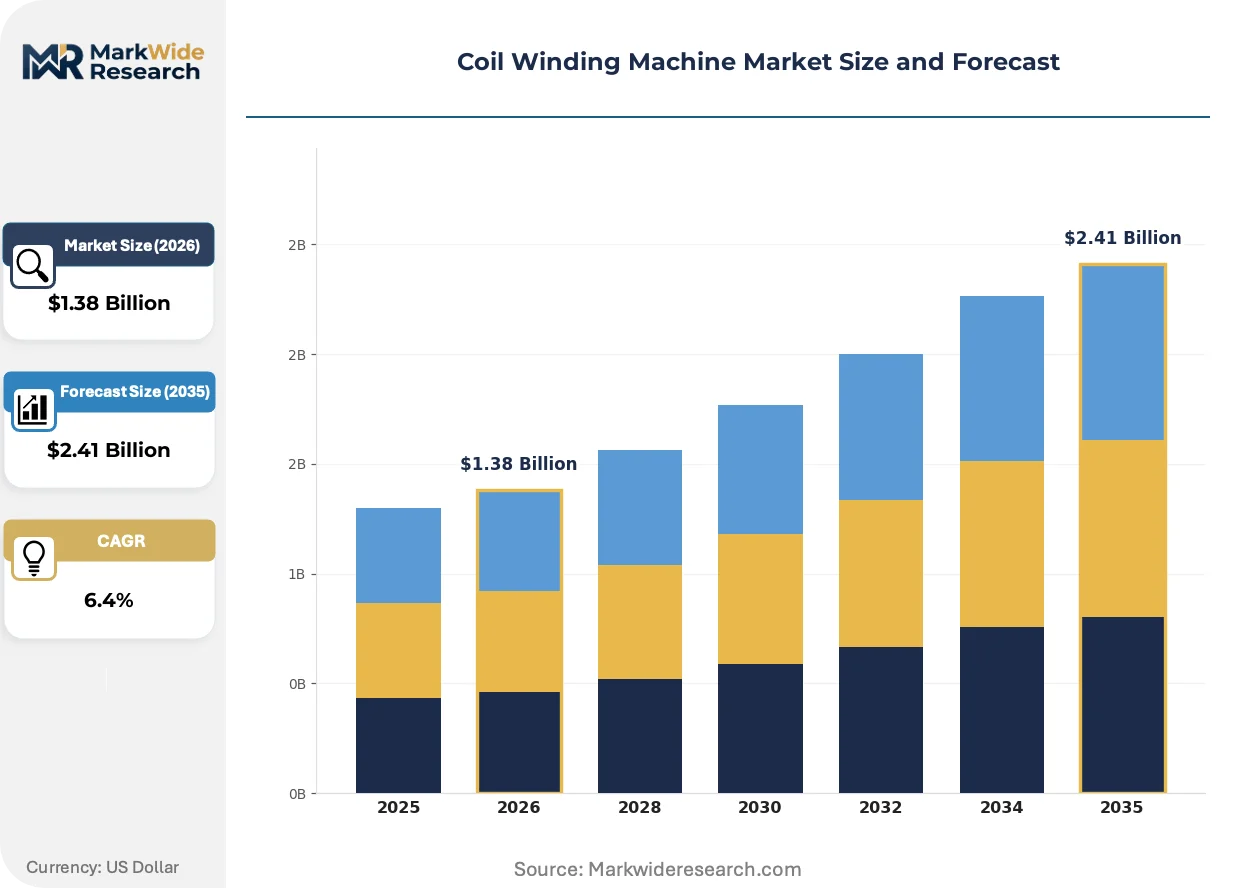
| Market Size in 2026 | $1.38 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Aerospace, Electronics, Automotive, Renewable Energy Technology: Capstan Winding, Multi-Spindle, CNC, Hybrid Application: Transformers, Motors, Inductors, Coils |
| Companies Covered | Nittoku Engineering, Odawara Automation, Marsilli, Bestec Co., Ltd., TANAC Automation, Hangzhou JOIN Intelligent Technology, Schleuniger, Jinkang Precision Mechanism, KOCOA Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coil Winding Machine Market Strategic Shifts
Active winding head architectures are displacing passive mechanical systems across high-volume automotive lines, while regulatory pressure on manufacturing emissions accelerates closed-loop platform adoption.
Direct-drive torque motors in winding spindles is electrifying speed-torque response curves for precision layer winding. Tier-one automotive suppliers in Germany and Japan are retrofitting existing CNC platforms with these motors to achieve 20,000 RPM with sub-micrometer runout. The technology is electrifying throughput benchmarks for hairpin stator production, compressing cycle times that previously required mechanical gearbox stages.
The EU F-Gas Regulation's phasedown schedule is forcing solvent-free cleaning process adoption across European winding equipment installations. Manufacturers must now certify closed-loop systems that eliminate perchloroethylene and fluorinated gas drying stages. Automotive tier-one suppliers in Stuttgart and Wolfsburg are responding by specifying vacuum-assisted resin impregnation lines that integrate directly with winding cells.
Consolidated procurement desks at major electric vehicle OEMs are unbundling after-sales service contracts from initial equipment purchases. Buyers now negotiate predictive maintenance subscriptions separately from capital expenditure, with uptime guarantees replacing traditional warranty terms. This restructuring is most visible in California and Shanghai, where Tesla and BYD procurement teams have established dedicated winding equipment category managers.
Coil Winding Machine Market Segmentation
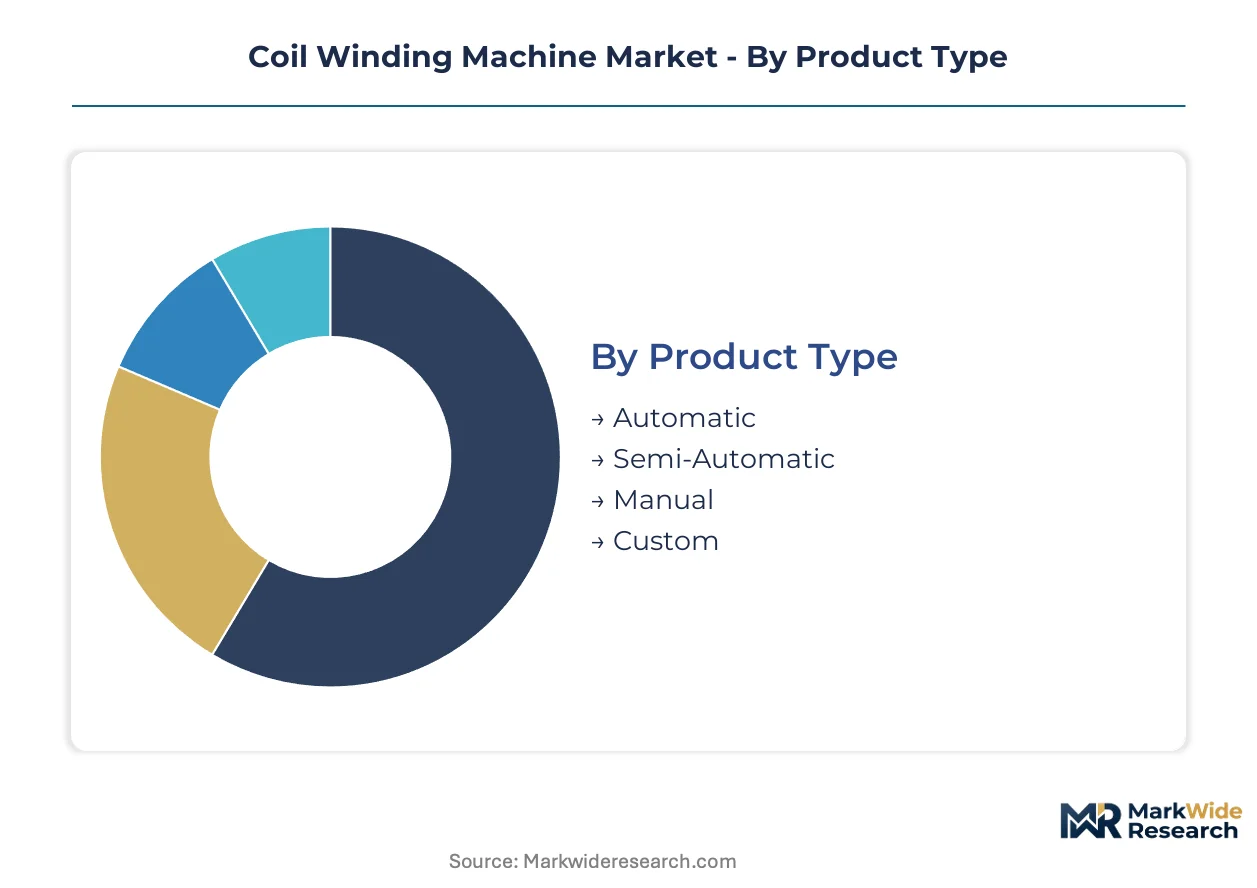
Coil winding equipment varies dramatically in automation intensity, precision capability, and integration complexity. Procurement decisions hinge on production volume, tolerance requirements, and regulatory compliance burdens specific to each end-use sector.
Product Type:
Capital intensity escalates sharply with automation level, from bench-mounted manual units to fully integrated automatic lines requiring seven-figure investments and cleanroom infrastructure.
- Automatic:These systems integrate programmable tension control, multi-axis servo positioning, and automated wire loading for continuous unattended operation. Electric vehicle OEMs in Germany and China specify automatic platforms for hairpin stator production, where throughput rates above 100 units per hour justify capital deployment despite extended commissioning timelines.
- Semi-Automatic:Operator-assisted machines combine motorized winding heads with manual core loading and wire termination. Mid-tier electronics manufacturers in South Korea and Taiwan favor this configuration for prototype-to-production flexibility, balancing labor costs against equipment amortization schedules.
- Manual:Hand-cranked or simple motorized bench units serve repair shops, educational institutions, and specialty coil producers. These systems require minimal capital outlay and occupy small footprints, appealing to artisanal transformer winders and R&D laboratories.
- Custom:Purpose-built architectures address non-standard core geometries, extreme wire gauges, or integration with downstream processes like resin impregnation. Medical device manufacturers commission custom platforms for implantable coil production under FDA and MDR traceability mandates.
Most installed capacity flows through Automatic systems. Expansion is steepest in Custom configurations serving medical and aerospace certification requirements.
End User:
Application-specific tolerance demands and regulatory exposure create divergent procurement patterns across industrial sectors.
- Automotive:Traction motor and auxiliary component production drives demand for high-speed, closed-loop winding with integrated quality verification. Tier-one suppliers in Stuttgart and Shanghai specify equipment certified to IATF standards, with predictive maintenance interfaces for zero-defect manufacturing commitments.
- Electronics:Inductor and choke manufacturing for consumer devices and telecommunications equipment emphasizes throughput and changeover speed. Contract manufacturers in Shenzhen and Hanoi prioritize platforms with quick-program CNC capability to accommodate short product lifecycles.
- Renewable Energy:Generator and grid-scale transformer winding requires heavy-gauge wire handling and large-form factor accommodation. Wind turbine OEMs in Denmark and Spain commission equipment with expanded bed dimensions and reinforced tension systems for copper conductors exceeding 10mm diameter.
- Aerospace:Satellite and aircraft electromagnetic component production mandates traceability documentation and materials pedigree verification. Suppliers to Airbus and Boeing programs invest in vacuum-compatible winding heads and automated inspection integration for AS9100 compliance.
Automotive applications command the largest equipment investment volumes. Aerospace represents the fastest-growing procurement segment as satellite constellation deployments accelerate.
Technology:
Control architecture sophistication determines achievable winding complexity, repeatability, and integration with factory information systems.
- CNC:Computer numerical control platforms enable programmable, non-cylindrical winding patterns with real-time trajectory correction. Precision motor manufacturers in Japan deploy five-axis CNC systems for concentrated windings with optimized copper distribution and minimal end-turn losses.
- Multi-Spindle:Parallel winding heads multiply throughput for high-volume, standardized coil geometries. Automotive tier-ones in Wolfsburg specify 12-spindle architectures for mass-produced solenoids and ignition coils, achieving unit economics that single-spindle systems cannot match.
- Capstan Winding:Traction-drive systems maintain constant wire tension through friction-based feed mechanisms. This mature technology persists in power transformer manufacturing where heavy conductors and simple layer structures predominate.
- Hybrid:Configurations combine mechanical cam actuation with limited programmable axes for cost-sensitive applications requiring pattern flexibility without full CNC investment. Domestic appliance manufacturers in Mexico and Poland favor hybrid platforms for motor stator production.
CNC platforms absorb the majority of premium-segment capital expenditure. Multi-Spindle installations are gaining share fastest in high-volume automotive electrification programs.
Application:
Electromagnetic function determines core geometry, wire specification, and insulation requirements that winding equipment must accommodate.
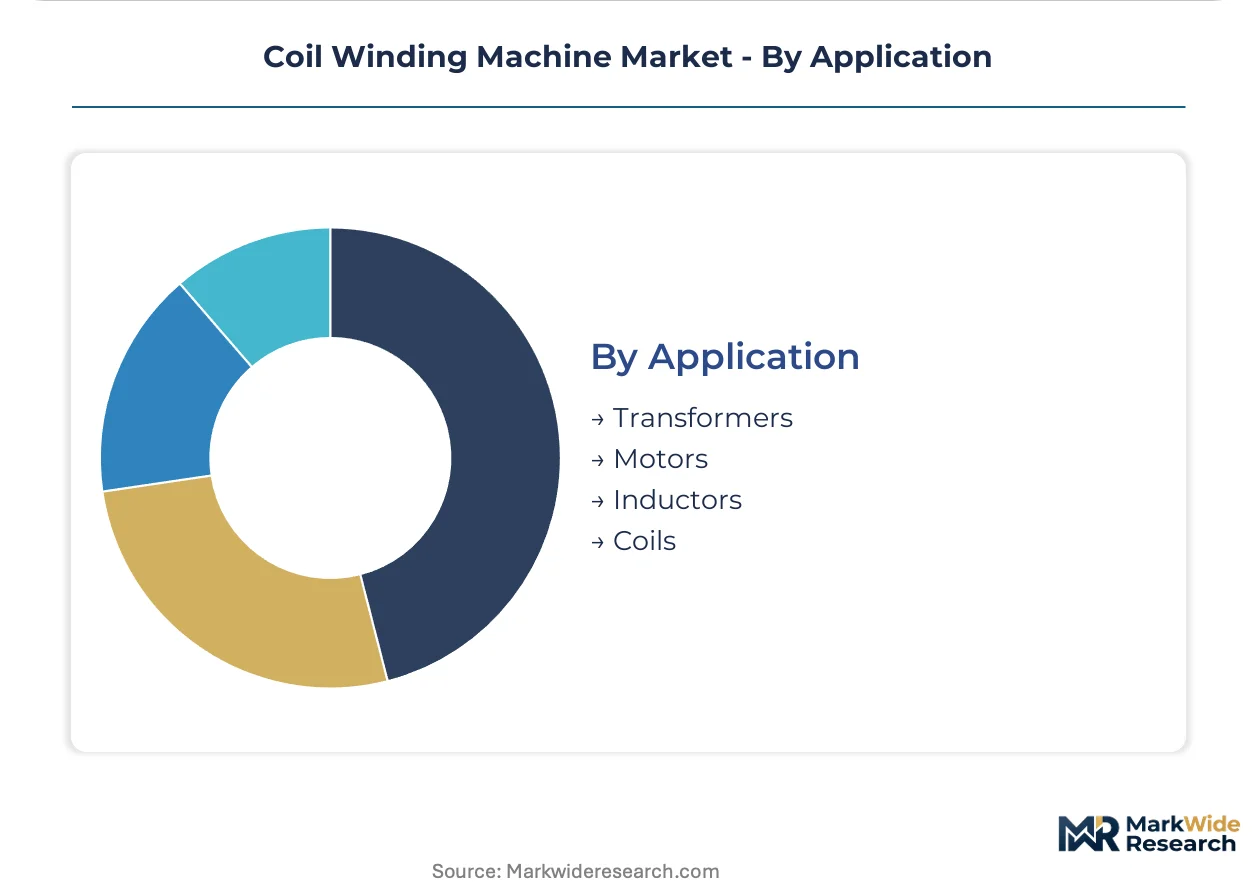
- Motors:Stator and rotor winding encompasses distributed, concentrated, and hairpin configurations with varying slot fill optimization challenges. Traction motor producers specify equipment with in-process resistance welding and paper insertion for EV powertrains.
- Transformers:Layer winding for power distribution and electronic applications requires precise turn counting and interlayer insulation placement. Grid infrastructure investments in India and Germany drive demand for large-form transformer winding systems.
- Inductors:High-frequency choke and filter component manufacturing emphasizes compact footprint and ferrite core handling. 5G base station deployments accelerate procurement of precision inductor winding equipment in Taiwan and Finland.
- Coils:General-purpose solenoid and electromagnetic actuator production spans automotive, industrial, and medical applications. This segment exhibits the broadest equipment specification range, from simple linear winding to complex orthocyclic patterns.
Transformer applications retain the largest installed equipment base. Motor winding represents the fastest-expanding application category driven by electric vehicle manufacturing scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronics engineers and CNC programmers concentrate in Germany, Japan, and China's industrial automation corridors, anchoring precision manufacturing ecosystems for winding equipment deployment.
United States
Tesla and Rivian procurement teams in California and Texas drive demand for hairpin stator winding systems. OSHA electrical safety standards and NHTSA automotive quality mandates shape equipment certification requirements. Detroit-area tier-one suppliers retrofit legacy plants with predictive maintenance interfaces for zero-defect manufacturing commitments.
Germany
BMW and Volkswagen electrification programs in Stuttgart and Wolfsburg consolidate procurement power among automotive tier-ones. EU F-Gas Regulation and REACH compliance push suppliers toward closed-loop, solvent-free winding architectures. The Baden-Württemberg automation cluster hosts precision spindle manufacturers serving both domestic OEMs and export markets.
China
BYD and CATL battery-motor integration projects in Shenzhen and Shanghai scale traction motor production. MIIT energy efficiency benchmarks and dual carbon goals mandate high-fill-factor winding equipment upgrades. The Yangtze River Delta manufacturing belt concentrates cost-engineered CNC platform suppliers for mid-tier electronics manufacturers.
Japan
Toyota and Honda hybrid-electric powertrain divisions in Nagoya and Tokyo specify five-axis CNC systems for concentrated windings. METI industrial policy supports precision equipment R&D through domestic content incentives. The Chubu region hosts ceramic bearing component houses supplying multi-spindle architectures globally.
India
Tata Motors and Mahindra electric vehicle programs in Pune and Chennai create first-mover demand for localized equipment assembly. PLI scheme production-linked incentives for automotive manufacturing attract winding machinery investments. The Maharashtra industrial corridor hosts emerging automation clusters serving renewable energy generator OEMs.
Coil Winding Machine Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation concentrates among Japanese and European heritage manufacturers with multi-decade transformer and automotive track records. Three archetypes dominate: precision CNC specialists, high-volume multi-spindle fabricators, and cost-engineered platform suppliers from East Asia. M&A activity targets predictive maintenance software capabilities, while capacity expansion focuses on India and Southeast Asia to serve localized automotive supply chains.
Within the heritage precision tier, Nittoku Engineering and Odawara Automation represent Japanese conglomerate subsidiaries with deep transformer winding legacies. Marsilli occupies a position among European multi-spindle specialists serving automotive tier-ones. Hangzhou JOIN Intelligent Technology exemplifies the cost-engineered CNC platform archetype penetrating mid-tier electronics manufacturers across East Asia.
| Leading Market Players |
|---|
| Nittoku Engineering |
| Odawara Automation |
| Marsilli |
| Bestec Co., Ltd. |
| TANAC Automation |
| Hangzhou JOIN Intelligent Technology |
| Schleuniger |
| Jinkang Precision Mechanism |
| KOCOA Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between CE-MDR medical platforms and standard industrial equipment manifests in both order-of-magnitude pricing spreads and geographically dispersed supply networks. Premium CNC systems for FDA-compliant medical coil production command capital commitments that standard automotive platforms cannot approach, while component sourcing for each tier traces through entirely different supplier ecosystems.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mid-tier CNC platforms serving electronics contract manufacturers. Three-tier pricing structure across premium CNC, multi-spindle automotive, and cost-engineered manual systems reflects certification burden and spindle precision grade. Cost compression in standard automotive tiers is intensifying because East Asian suppliers are exporting cost-engineered platforms at margins European incumbents cannot match. Mid-tier electronics manufacturers in Vietnam and Mexico exhibit highest price sensitivity, while medical device OEMs in Switzerland and Massachusetts demonstrate lowest sensitivity due to traceability mandates.
Supply Chain Analysis
CE marking and FDA 21 CFR Part 820 qualification requirements gate supplier entry for medical-grade ceramic bearing assemblies and vacuum-compatible winding heads. Precision spindle manufacturing concentrates in Germany, Japan, and China's coastal provinces. High-precision ceramic bearing supply draws from specialized component houses in Baden-Württemberg and the Chubu region. Single-source vulnerability runs through German ceramic bearing suppliers serving multi-spindle architectures for European automotive tier-ones. Distribution runs through direct OEM relationships for premium CNC platforms and regional distributor networks for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electric vehicle OEM procurement desks are consolidating specifications around closed-loop automation and predictive maintenance interfaces. Traction motor copper fill optimization is shifting demand toward premium CNC platforms with sub-micrometer tension control.
For Market Incumbents: To counter cost-engineered platform penetration from East Asian suppliers, German and Japanese heritage manufacturers should anchor backward integration into ceramic bearing production and expand captive service subscription revenue. Nittoku Engineering and Marsilli can defend position by certifying closed-loop architectures for EU F-Gas compliance before regulatory deadlines harden competitive moats. For New Entrants and Emerging Players: Begin with India's PLI scheme automotive corridor, where localized assembly requirements and first-mover equipment demand create white-space opportunity. Target mid-tier renewable energy generator manufacturers in Spain and Denmark seeking heavy-gauge transformer winding platforms without premium CNC investment. Partner with established European spindle suppliers for technology transfer rather than greenfield R&D. For Investors and Strategic Acquirers: Consolidation pressure builds where predictive maintenance software capabilities remain fragmented across legacy equipment install bases. Long-term viability favors platforms with recurring service revenue attachment above pure hardware margins. Acquire specialists with AI vision integration for real-time defect detection during layer buildup. Watch for inflection when Tesla or BYD procurement teams unbundle predictive maintenance subscriptions as standalone category spend.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Integration | BYD and Tesla procurement teams now negotiate uptime guarantees separately from capital expenditure. |
| Closed-Loop Solvent-Free Architecture Certification | EU F-Gas Regulation deadlines force automotive tier-ones in Stuttgart to specify vacuum-assisted resin impregnation. |
| Ceramic Bearing Backward Integration | Baden-Württemberg suppliers face margin pressure from Japanese and Chinese precision component houses. |
| India PLI Scheme Localization | Tata Motors and Mahindra electric vehicle programs in Pune require domestic content-compliant equipment assembly. |
| AI Vision Tension Control Development | Real-time defect detection during layer buildup enables predictive adjustment for hairpin stator production. |
Study Parameters
Coverage spans Germany, Japan, China, India, and the United States, with primary inputs from each region's automotive and electronics manufacturing corridors. The analysis combines structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, and aftermarket service heads with secondary validation from MIIT policy directives, EU F-Gas Regulation filings, and SEC equipment supplier disclosures. Bottom-up triangulation across end-user demand segments and top-down reconciliation against industrial automation capex data anchor volume estimates.
Granularity-level modeling distinguishes automatic, semi-automatic, manual, and custom product configurations across automotive, electronics, renewable energy, and aerospace end-use sectors. Technology segmentation captures CNC, multi-spindle, capstan, and hybrid control architectures. CAGRs derive from equipment replacement cycles, regulatory compliance deadlines, and electric vehicle production ramp schedules across the projection horizon. Forecast inputs incorporate copper price volatility scenarios and ceramic bearing supply concentration risk.
Several conditions sit outside the modeled scope, including sudden tariff escalations on precision spindle imports and unanticipated breakthroughs in ultra-fine wire handling below 25 micrometers. Forecasts reflect assumptions about MIIT energy efficiency benchmark enforcement and EU F-Gas phasedown adherence. A model refresh is warranted upon material change in electric vehicle OEM procurement consolidation patterns or ceramic bearing supply disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Global Fans and Blowers Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Digital Servo Press Market
Industrial Equipment
Global High Speed Dispenser Market