
 Modular Instruments Market | 2026-2036
Modular Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Instruments Market Intelligence
REACH and the EU F-Gas Regulation are broadening the cost-of-entry calculus for modular instrument vendors serving European aerospace and automotive clients. Keysight Technologies leverages its software-defined instrumentation portfolio to sustain R&D intensity across 5G and satellite communication test beds. National Instruments anchors its position through LabVIEW-integrated hardware ecosystems that dominate research lab procurement in North America.
Modular instruments comprise interchangeable hardware components—typically PXI, PXIe, or AXIe chassis-based modules with 12-bit to 16-bit resolution and sampling rates exceeding 1 GS/s—configured for automated test, measurement, and validation workflows in high-mix electronics production. Signal generators and oscilloscopes occupy the largest product type positions, while software-defined technology captures the fastest expansion as engineers trade fixed-function hardware for FPGA-reconfigurable measurement channels. Data acquisition systems compete in mature industrial process monitoring segments where margin pools have compressed to single-digit percentages.
FDA 21 CFR Part 11 validation requirements and ECHA substance restrictions shape instrument firmware documentation and material composition decisions for vendors selling into pharmaceutical and semiconductor end markets. FCC Part 15 emissions compliance and CE marking directives determine market access timelines for wireless test modules shipped across North American and European borders. Stakeholders must weigh calibration traceability investments against the operational flexibility that software-defined architectures deliver as end users consolidate vendor relationships.
Market Dynamics
Software-defined architectures are compressing validation cycles across aerospace and semiconductor end uses, forcing incumbent vendors to reconfigure hardware roadmaps around FPGA-reconfigurable measurement channels rather than fixed-function instrument platforms.
Growth Catalysts
- EU AI Act and MDR compliance timelines:Medical device and aerospace manufacturers in Germany and France are accelerating replacement of legacy test benches with automated measurement systems to meet compressed validation deadlines.
- China's domestic equipment sourcing mandates:Semiconductor fabrication corridors in Shanghai and Hefei are accelerating local deployment of PXIe-based modular instruments under MIIT localization directives.
- 5G and satellite communication test beds:Aerospace manufacturers in the United States are expanding procurement of software-defined platforms for avionics validation as constellation deployment accelerates.
Market Restraints
- High-precision ADC and FPGA input costs:16-bit resolution modules with sampling rates exceeding 1 GS/s depend on concentrated foundry supply from Taiwan, creating margin pressure during capacity constraints.
- REACH and EU F-Gas Regulation compliance:Material composition restrictions on cooling systems and chassis materials broaden cost-of-entry calculus for vendors serving European aerospace and automotive clients.
- Calibration traceability infrastructure:NIST-traceable calibration chains require sustained capital deployment that disadvantages smaller regional instrument assemblers.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Semiconductor test and assembly investments in Gujarat and Tamil Nadu are creating demand for localized modular instrument supply and service capabilities.
- Convergence of AI-driven analytics with software-defined hardware:Machine learning-based signal processing is enabling predictive maintenance applications in industrial process monitoring segments.
- Subscription-based firmware and calibration services:Channel partners in North American research lab procurement are unbundling hardware sales from ongoing validation support contracts.
Industry Challenges
- FPGA programming expertise scarcity:Systems integrators face recruitment gaps for LabVIEW and VHDL specialists capable of configuring reconfigurable measurement channels.
- FDA 21 CFR Part 11 documentation burdens:Pharmaceutical end users require instrument firmware validation protocols that extend sales cycles by six to nine months.
- Legacy GPIB and VXI system integration:Defense and aerospace facilities with decades-old test infrastructure resist chassis migration paths despite performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Instruments Market |
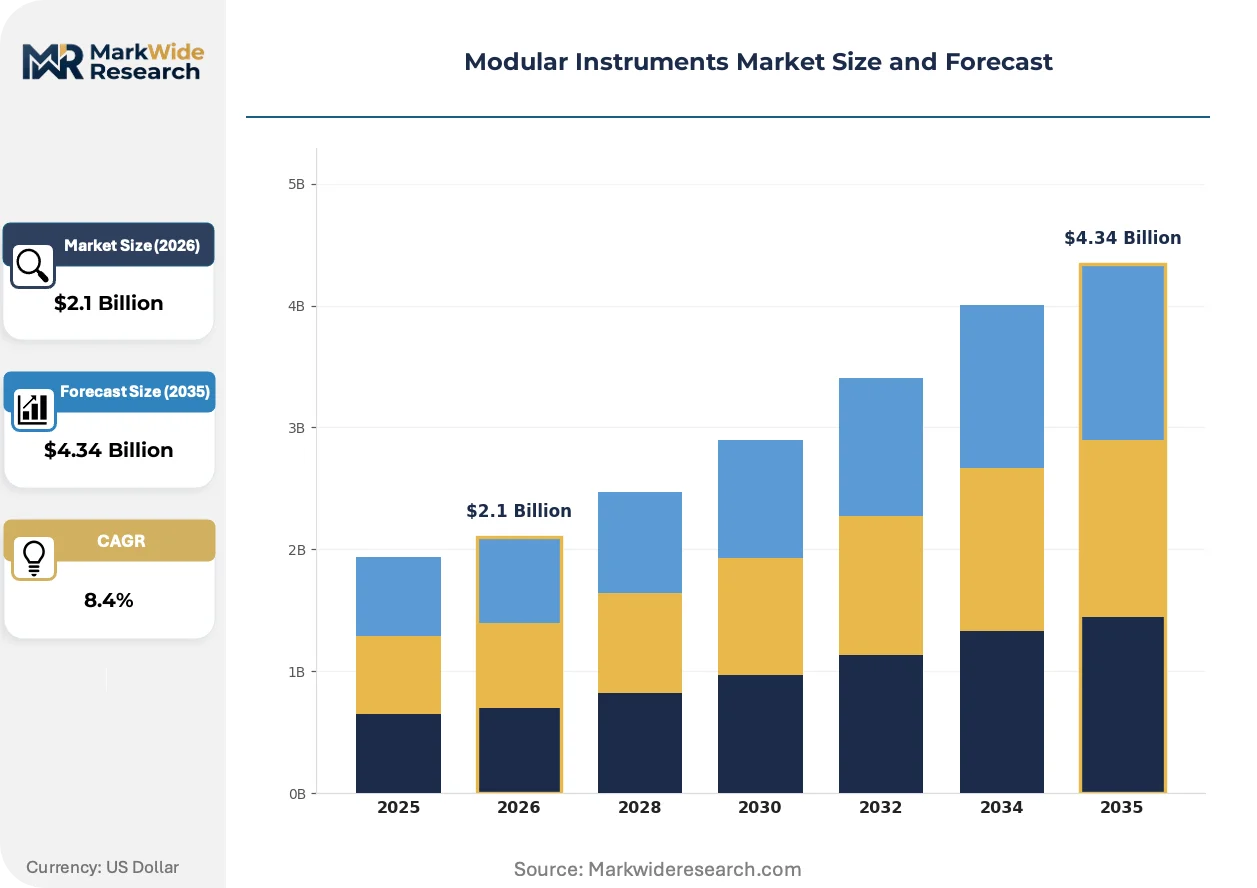
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
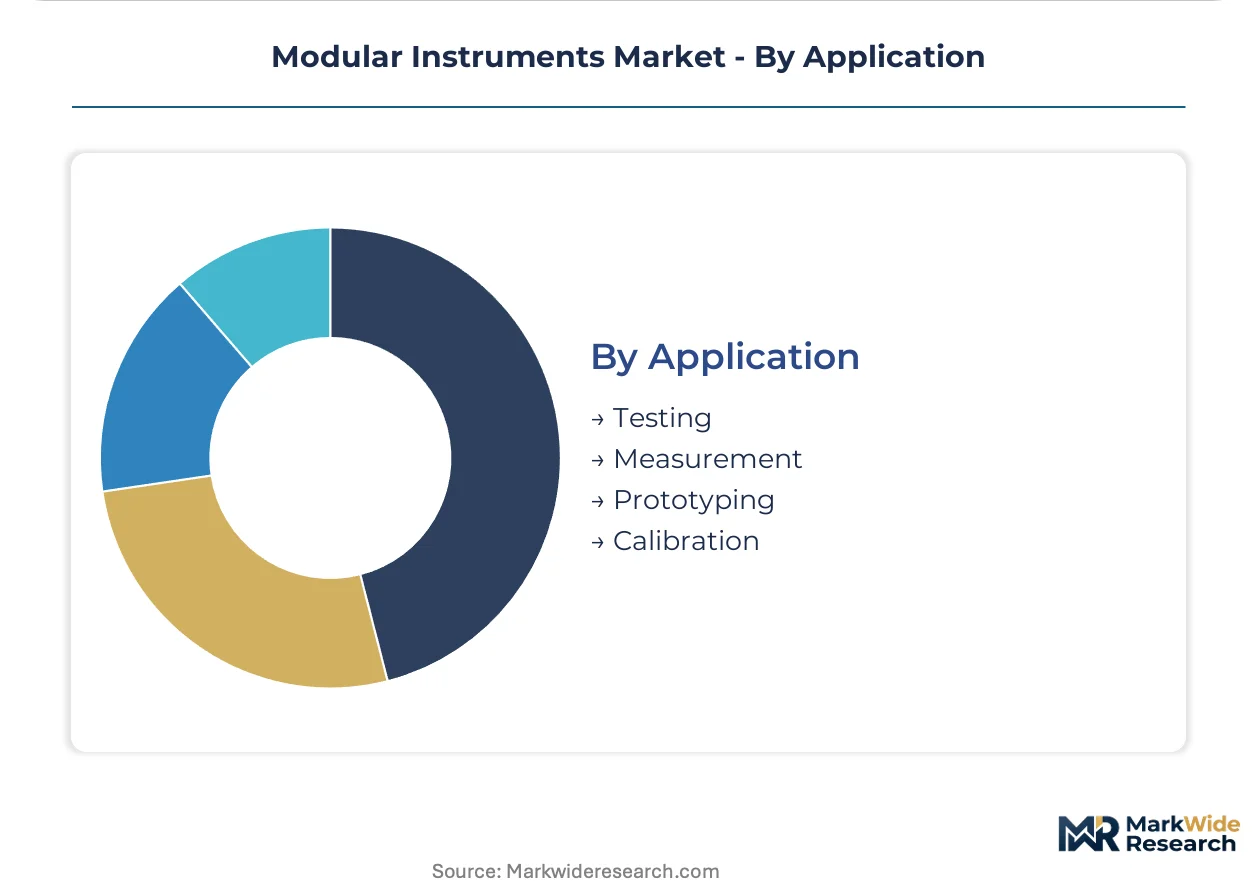
| Segmentation | Product Type: Signal Generators, Data Acquisition Systems, Oscilloscopes, Multimeters End User: Aerospace, Telecommunications, Research Labs, Automotive Technology: Digital, Analog, Mixed-Signal, Software-Defined Application: Testing, Measurement, Prototyping, Calibration |
| Companies Covered | Fortive Corporation, Anritsu Corporation, Keysight Technologies, Viavi Solutions, Yokogawa Electric Corporation, National Instruments, Advantest Corporation, Astronics Corporation, Rohde & Schwarz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Instruments Market Strategic Shifts & Innovations
Measurement hardware is absorbing software capabilities at the firmware layer, blurring traditional boundaries between instrument vendors and test automation software providers while compressing the value capture available to pure hardware manufacturers.
FPGA-reconfigurable digitizer modules are absorbing signal processing functions previously executed in external computing clusters. Aerospace and satellite communication test engineers in the United States and Germany are adopting these modules at replacement-cycle velocity. This absorption is compressing the addressable market for standalone signal analyzers while expanding margin pools in firmware-licensing arrangements.
REACH substance restrictions and the EU F-Gas Regulation are forcing chassis redesigns and cooling system substitutions across instrument portfolios serving European aerospace and automotive clients. Industrial consequences include extended qualification timelines and material cost inflation for vendors without advance supply chain positioning. Semiconductor test module manufacturers are responding by qualifying alternative thermal interface materials ahead of regulatory enforcement windows.
Consolidated vendor relationships are displacing multi-source procurement strategies among high-mix electronics manufacturers. Tier-one automotive and aerospace OEMs are collapsing supplier panels to three to four strategic instrument partners with full-stack software-defined capabilities. This concentration is most visible in Germany and Japan, where procurement organizations prioritize calibration traceability and firmware update continuity over unit cost minimization.
Modular Instruments Market Segmentation

Modular instrument procurement varies sharply by deployment context, with capital allocation patterns diverging between high-frequency semiconductor validation and lower-bandwidth industrial monitoring. Engineers configure chassis-based systems around specific measurement tasks, creating distinct margin pools across product categories and end-use verticals.
Product Type:
Capital intensity peaks in high-resolution digitizer modules, where 16-bit ADCs and FPGA signal processing cores concentrate component costs.
- Signal Generators:RF and microwave signal sources with frequency synthesis capabilities from kHz to mmWave bands. Aerospace manufacturers in the United States deploy these for radar cross-section validation as satellite constellation programs accelerate hardware-in-the-loop test requirements.
- Oscilloscopes:Time-domain measurement modules with real-time sampling rates exceeding 1 GS/s and deep memory buffers. Semiconductor fabrication corridors in Shanghai and Hefei absorb the bulk of high-bandwidth units under MIIT localization directives.
- Data Acquisition Systems:Multi-channel voltage and sensor input modules for industrial process monitoring. Mature segments face compressed margin pools as channel density commoditizes.
- Multimeters:Precision DC and AC measurement modules with 6.5-digit to 8.5-digit resolution. Research labs in North America standardize procurement around these for benchtop automation.
Signal generators absorb the bulk of installed capacity; oscilloscopes are expanding most quickly.
End User:
Application complexity and validation stringency shape procurement budgets across verticals, with aerospace and pharmaceutical end users commanding premium pricing tiers.
- Aerospace:Avionics and satellite subsystem validation requiring DO-160 and MIL-STD compliance documentation. German manufacturers accelerate replacement of legacy GPIB test benches to meet EU AI Act verification timelines.
- Telecommunications:5G base station and optical network equipment test workflows. FPGA-reconfigurable modules displace fixed-function analyzers as 3GPP release timelines compress.
- Research Labs:University and government laboratory procurement dominated by LabVIEW-integrated ecosystems. Funding cycles drive replacement velocity more than technological obsolescence.
- Automotive:EV powertrain and ADAS sensor validation with ISO 26262 functional safety requirements. Tier-one OEMs in Germany and Japan consolidate supplier panels to three strategic partners.
Aerospace commands the highest per-channel pricing; telecommunications shows the steepest expansion trajectory.
Technology:
Architecture selection determines firmware upgrade pathways and total cost of ownership across multi-year deployment cycles.
- Software-Defined:FPGA-reconfigurable measurement channels with downloadable personality modules. Engineers in satellite communication test beds trade hardware obsolescence risk for higher upfront licensing costs.
- Mixed-Signal:Combined analog front-end and digital processing modules for power integrity analysis. Semiconductor wafer probe stations drive concentrated demand.
- Digital:Logic analyzer and pattern generator modules with state and timing acquisition modes. Digital-only architectures face displacement pressure from software-defined alternatives.
- Analog:Traditional swept-tuned spectrum analysis and precision source-measure units. Legacy installations in defense facilities resist chassis migration despite performance gaps.
Software-defined architectures claim the fastest share gains; analog systems retain the largest installed base.
Application:
Workflow positioning determines calibration frequency, documentation burden, and service contract attachment rates.
- Testing:Production-line automated test equipment with high-throughput pass-fail determination. High-mix electronics manufacturers in China's semiconductor corridors deploy PXIe chassis for parallel multi-site testing.
- Measurement:Characterization and validation workflows requiring NIST-traceable uncertainty budgets. FDA 21 CFR Part 11 compliance extends sales cycles by six to nine months in pharmaceutical end markets.
- Prototyping:R&D bench configurations with frequent reconfiguration and module swapping. Research labs prioritize chassis expansion slots over per-channel specifications.
- Calibration:Metrology-grade reference systems with embedded standards and automated uncertainty calculations. Calibration traceability infrastructure disadvantages smaller regional assemblers.
Testing applications dominate unit shipments; measurement commands the highest service contract penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and semiconductor fabrication corridors in Shanghai concentrate modular instrument deployment under MIIT localization mandates. Aerospace validation clusters in Germany and the United States absorb premium-tier PXIe chassis for avionics test beds.
United States
Aerospace manufacturers in California and Texas expand procurement of software-defined platforms for satellite constellation validation. FCC Part 15 emissions compliance governs wireless test module shipments across state borders. The Greater Boston research corridor anchors LabVIEW-integrated hardware procurement for university and government laboratories.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg consolidate supplier panels to three strategic partners with ISO 26262 traceability. EU AI Act and MDR compliance timelines compress validation cycles for medical device manufacturers. The Stuttgart aerospace cluster accelerates replacement of legacy GPIB test benches with automated measurement systems.
China
Semiconductor fabrication corridors in Shanghai and Hefei deploy PXIe-based modular instruments under MIIT domestic equipment sourcing directives. GB standards and SAMR certification requirements shape firmware documentation for pharmaceutical end markets. The Yangtze River Delta concentration absorbs high-bandwidth oscilloscope modules for wafer probe stations.
Japan
Automotive and telecommunications equipment manufacturers in Kanto and Kansai regions prioritize calibration traceability and firmware update continuity. METI industrial standards influence chassis design decisions for export-oriented instrument vendors. The Nagoya automotive cluster drives demand for mixed-signal modules in EV powertrain validation.
India
Electronics manufacturing investments in Gujarat and Tamil Nadu under the PLI scheme create demand for localized modular instrument supply capabilities. BIS certification requirements extend market access timelines for imported test modules. The Bangalore semiconductor test ecosystem anchors service and calibration infrastructure development.
Modular Instruments Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: full-stack software-defined platform providers, chassis-agnostic module specialists, and regional calibration service integrators. Dominant competitive moves include portfolio diversification into FPGA-reconfigurable architectures and geographic expansion through localized service partnerships.
Among diversified measurement and test conglomerates, Fortive Corporation and Keysight Technologies exemplify scale-driven platform strategies. National Instruments anchors the pure-play specialist tier through LabVIEW-integrated hardware ecosystems. These three companies occupy positions spanning software-defined instrumentation, automated test equipment, and research laboratory procurement channels.
| Leading Market Players |
|---|
| Fortive Corporation |
| Anritsu Corporation |
| Keysight Technologies |
| Viavi Solutions |
| Yokogawa Electric Corporation |
| National Instruments |
| Advantest Corporation |
| Astronics Corporation |
| Rohde & Schwarz |
| Others |
Cost & Logistics Intelligence
Compressed EU AI Act and MDR validation timelines in Germany and France are forcing aerospace and medical device manufacturers to absorb premium pricing for rapid-deployment PXIe chassis with pre-validated firmware documentation, compressing procurement cycles and concentrating supplier power among vendors with established calibration traceability infrastructure.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above standard delivery pricing apply to 16-bit digitizer modules with FPGA signal processing cores, reflecting Taiwan foundry capacity constraints for high-precision ADCs. Three-tier pricing structure across premium, standard, and economy levels stratifies by calibration certification tier and firmware update continuity guarantees. Pricing pressure stems from China's domestic equipment sourcing mandates accelerating local production scale, eroding margin pools for imported chassis in Shanghai semiconductor corridors. Research labs in North America demonstrate lowest price sensitivity due to grant-funded procurement cycles, while high-mix electronics contract manufacturers in India negotiate aggressively on per-channel economics.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns for chassis and module fulfillment, with inventory positioning tied to aerospace cluster proximity in California, Texas, and Stuttgart. Manufacturing concentration in Taiwan, the United States, and Japan feeds precision ADC and FPGA component dependencies, while cooling system suppliers in Germany and South Korea face REACH and EU F-Gas Regulation compliance costs. Single-source vulnerability concentrates in Taiwan foundry capacity for 1 GS/s sampling rate modules. Distribution runs through authorized channel partners with embedded calibration service capabilities, privileging vendors with NIST-traceable infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular instruments market functions as a cost-of-compliance arena where EU AI Act documentation burdens and FDA 21 CFR Part 11 validation requirements erect barrier-to-entry moats favoring incumbents with sustained firmware development resources.
For Market Incumbents: To counter FPGA programming expertise scarcity constraining systems integrator recruitment, anchor competitive position through backward integration into firmware-licensing revenue streams and captive calibration service networks in Germany and Japan. Prioritize chassis expansion slot density in research lab procurement channels where LabVIEW ecosystem lock-in sustains replacement-cycle velocity. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing in Gujarat and Tamil Nadu opens a window for localized assembly partnerships serving semiconductor test corridors with BIS-certified modules. Target industrial process monitoring segments where data acquisition system margins have compressed incumbent R&D investment, enabling service-based differentiation through subscription calibration contracts. For Investors and Strategic Acquirers: The window for entry favors pure-play software-defined instrumentation specialists with FPGA-reconfigurable architectures and established pharmaceutical validation protocols. Long-term viability hinges on firmware update continuity and calibration traceability infrastructure rather than hardware unit economics. Watch for MIIT localization directive enforcement intensity in China as inflection indicator for import substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA-Reconfigurable Platform Expansion | Enables personality module licensing revenue from satellite communication test beds in the United States. |
| Calibration Service Network Localization | Captures recurring revenue from pharmaceutical end markets requiring FDA 21 CFR Part 11 documentation. |
| REACH-Compliant Chassis Redesign | Preserves European aerospace access as ECHA substance restrictions tighten thermal interface material qualifications. |
| India PLI Scheme Manufacturing Partnership | Positions for semiconductor test corridor demand in Gujarat and Tamil Nadu with BIS-certified supply. |
| AI-Driven Predictive Maintenance Integration | Opens industrial process monitoring segments through machine learning-based signal processing applications. |
Research Approach
Independent corroboration across test and measurement OEM product managers, aerospace procurement officers, semiconductor fabrication facility engineers, and research lab instrumentation coordinators underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC 10-K filings, MIIT equipment localization directives, ECHA substance restriction databases, and NIST calibration infrastructure disclosures. Bottom-up channel partner interviews and top-down vendor revenue segmentation triangulate market sizing across PXIe, PXI, and AXIe chassis architectures.
Comparable-period anchoring to historical replacement cycles in aerospace and pharmaceutical end markets shaped the projection horizon analytical framework. Modeled dimensions span product type, end user vertical, technology architecture, and application workflow positioning, with additional segmentation by regional regulatory cluster. CAGRs derive from installed base depreciation rates and compliance-driven upgrade velocity. Forecast inputs incorporate FPGA foundry capacity utilization and EU AI Act enforcement timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for software-defined instrumentation displacing fixed-function analyzers would alter the outlook. Forecasts reflect documented assumptions regarding MIIT localization compliance rates and REACH substance restriction phase-in schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Microchip Electrophoresis Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Life Science and Analytical Instruments Market