
 High-Precision Confocal Sensor Market | 2026-2036
High-Precision Confocal Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
High-Precision Confocal Sensor Market Insights
Sensor-as-a-service and predictive maintenance contracts is hardening into a core revenue layer for vendors serving semiconductor fabs and automotive tier-1 suppliers. Keyence Corporation leverages its direct sales force to control channel access across Asia-Pacific industrial corridors. Micro-Epsilon sustains R&D intensity in chromatic confocal chromatic technology, anchoring its position in European precision engineering. Precitec specializes in fiber optic interferometer configurations for aerospace fabricators, competing on measurement stability in vibration-prone environments.
High-precision confocal sensors employ chromatic aberration principles to achieve axial resolution below one micron, using spectrally-encoded light focused through objective lenses with calibrated depth-to-wavelength mapping for non-contact dimensional metrology. The confocal chromatic segment leads in semiconductor wafer inspection where sub-micron thickness measurement tolerances dominate procurement specifications, while white light interferometry occupies premium niches in research laboratories requiring nanometer-scale surface profiling. Fiber optic configurations are extending into embedded process control applications where electromagnetic immunity and small form factors determine design wins.
EMA medical device regulations and EU AI Act conformity requirements are reshaping validation protocols for sensors deployed in automated optical inspection systems across European precision instrument manufacturing. FDA quality system regulations and ISO 10360 calibration standards govern market access for suppliers targeting North American medical device and aerospace metrology buyers. Stakeholders must monitor how NMPA certification timelines in China and evolving dual carbon goals affecting optical glass supply chains redirect procurement toward domestic sensor vendors.
Market Dynamics
Semiconductor wafer metrology specifications below one micron are compressing sensor replacement cycles and forcing vendors to embed predictive calibration algorithms directly into chromatic confocal probe electronics.
Growth Catalysts
- EU MDR and FDA quality system mandates:Medical device manufacturers in Germany and Massachusetts now require ISO 10360 traceable sensors for automated optical inspection, expanding validation-grade procurement.
- Chromatic confocal miniaturization:Fiber optic probe diameters below four millimeters are penetrating embedded process control in vibration-prone aerospace fabrication cells.
- South Korean memory fab concentration:Samsung and SK Hynix supplier ecosystems in Gyeonggi-do are standardizing on non-contact thickness metrology for 3D NAND layer stacks.
Market Restraints
- Optical glass supply concentration:Schott AG and Hoya Corporation control specialty low-dispersion glass for objective lenses, exposing sensor vendors to dual carbon goal compliance costs in China and Germany.
- Chromatic aberration physics limits:Axial resolution below fifty nanometers remains inaccessible without white light interferometry, segmenting the addressable market.
- REACH substance restrictions:ECHA scrutiny of lead-containing optical coatings is forcing reformulation timelines that extend sensor development cycles by eight to fourteen months.
Strategic Opportunities
- India PLI scheme for precision manufacturing:Semiconductor and medical device incentives in Gujarat and Karnataka are creating first-mover advantages for localized sensor assembly partnerships.
- Sensor-as-a-service contracts:Predictive maintenance subscriptions for automotive tier-1 suppliers are hardening into recurring revenue streams that decouple vendor economics from unit shipments.
- AI Act conformity automation:EU automated optical inspection systems now require algorithmic transparency documentation, opening validation software attach-rate expansion for incumbent probe vendors.
Industry Challenges
- Interferometry-chromatic calibration skill scarcity:Metrology engineers capable of cross-platform correlation studies command premium compensation in Munich, Tokyo, and Boston clusters.
- NMPA certification timeline variability:Chinese medical device registration timelines for optical inspection systems fluctuate unpredictably, complicating revenue forecasting for multinational sensor vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Precision Confocal Sensor Market |
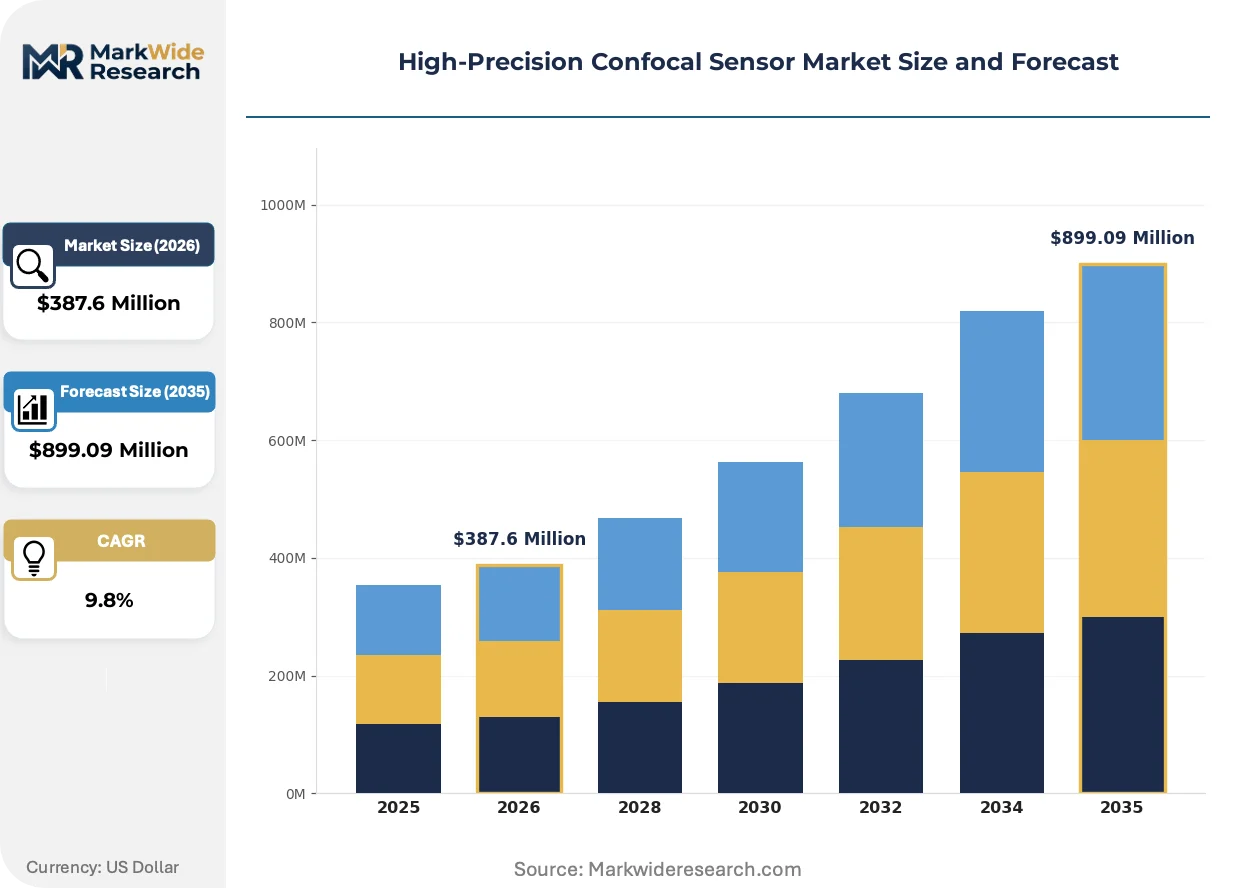
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $899.09 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Laser Displacement, Chromatic, Tunable, Fiber Optic Interferometer, Capacitive Technology: Optical, Phase Measuring, Triangulation, Spectral, Confocal Chromatic, White Light Interferometry Application: Surface Profiling, Thickness Measurement, Distance Sensing, Material Inspection, Microelectronics Testing, Precision Engineering End User: Semiconductor Manufacturers, Aerospace Fabricators, Precision Instruments, Research Laboratories, Automotive OEMs, Optical Component Producers |
| Companies Covered | Keyence Corporation, Micro-Epsilon, Precitec, STIL, Omron Corporation, SICK AG, Renishaw, ZEISS, Hypersen Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Precision Confocal Sensor Market Trends and Innovations
Three intersecting vectors are restructuring how dimensional metrology value is captured: probe miniaturization enabling embedded deployment, regulatory documentation burdens shifting toward software, and procurement consolidation around outcome-based sensor availability.
Chromatic confocal probe miniaturization is decentralizing metrology authority from centralized quality labs to production line stations. Automotive powertrain manufacturers in Stuttgart and Nagoya are embedding sub-millimeter fiber probes directly into grinding machine feedback loops. Real-time thickness compensation is compressing rework rates and collapsing the traditional segregation between process control and final inspection functions.
EU AI Act algorithmic transparency requirements are mandating interpretability documentation for automated defect classification systems. Medical device contract manufacturers in Ireland and Switzerland must now maintain sensor decision audit trails that satisfy notified body scrutiny. Probe vendors are responding by embedding edge computing modules that log spectral data and classification confidence intervals for seven-year retention periods.
Buying committees at semiconductor fabs are consolidating vendor relationships around sensor availability guarantees rather than capital purchase terms. Korean and Taiwanese memory manufacturers now negotiate uptime-based contracts with automatic probe replacement clauses. This behavioral pivot privileges vendors with regional spare inventory positioning over those optimizing for equipment margin extraction.
High-Precision Confocal Sensor Market Segmentation
Segmentation in high-precision confocal sensors determines procurement pathways, with upgrade cycles varying sharply across product architectures. Technology choices lock customers into specific calibration protocols and replacement timelines, while application requirements dictate resolution thresholds that filter vendor eligibility.
Product Type:
Replacement cycles accelerate where probe miniaturization enables embedded deployment, compressing the traditional boundary between process control and final inspection functions.
- Chromatic:Spectrally-encoded depth measurement achieves sub-micron axial resolution through calibrated wavelength-to-position mapping in semiconductor wafer metrology. Samsung and SK Hynix fabs in Gyeonggi-do specify chromatic probes for 3D NAND layer stack thickness verification, with REACH compliance costs extending development cycles.
- Fiber Optic:Sub-millimeter probe diameters penetrate vibration-prone aerospace grinding cells in Stuttgart and Nagoya, delivering electromagnetic immunity for real-time feedback loops. Demand concentrates where machine-integrated metrology collapses rework rates.
- Laser Displacement:Triangulation-based systems serve high-speed production lines requiring millimeter-range standoff distances.
- Tunable:Wavelength-swept architectures address research laboratory applications demanding configurable measurement windows.
- Fiber Optic Interferometer:Phase-resolving configurations compete on stability in precision instrument manufacturing across Switzerland and Germany.
- Capacitive:Proximity-based alternatives occupy cost-sensitive niches where optical contamination risks exclude laser-based methods.
Volume placements concentrate in Chromatic; the faster expansion belongs to Fiber Optic.
Technology:
Cost tiers separate validation-grade installations from production-floor deployments, with calibration traceability premiums widening price spreads.
- Confocal Chromatic:Depth-encoded spectral analysis dominates semiconductor inspection where sub-micron tolerances govern procurement specifications. German and South Korean precision manufacturing clusters anchor demand, with EU AI Act documentation requirements shifting value toward embedded edge computing modules.
- White Light Interferometry:Nanometer-scale surface profiling serves research laboratories and medical device contract manufacturers in Ireland requiring ISO 10360 traceability. FDA quality system mandates in Massachusetts expand validation-grade procurement for automated optical inspection.
- Optical:Broad category encompassing laser and LED illumination architectures for general metrology applications.
- Phase Measuring:Interferometric techniques address precision engineering in vibration-controlled environments.
- Triangulation:Angular displacement methods compete on speed for automotive powertrain measurement cells.
- Spectral:Wavelength-dispersive approaches support material identification alongside dimensional measurement.
Procurement volumes favor Confocal Chromatic; White Light Interferometry commands the steepest expansion trajectory in medical device validation.
Application:
Customer type differentiation separates capital equipment buyers from sensor-as-a-service subscribers, with uptime guarantees restructuring vendor economics.
- Thickness Measurement:Non-contact layer stack verification drives replacement demand in memory fab process control, with Korean and Taiwanese manufacturers negotiating availability-based contracts. NMPA certification timeline variability complicates revenue forecasting for optical inspection system vendors targeting Chinese medical device registration.
- Surface Profiling:Nanometer-scale topography mapping serves aerospace fabricators and research laboratories requiring algorithmic transparency documentation under EU AI Act conformity protocols. Swiss and Irish contract manufacturers must maintain seven-year spectral data retention.
- Distance Sensing:Standoff measurement for automated positioning in precision engineering applications.
- Material Inspection:Defect classification systems subject to EMA medical device regulations across European precision instrument manufacturing.
- Microelectronics Testing:Wafer-level verification for semiconductor packaging and interconnect inspection.
- Precision Engineering:General metrology supporting optical component producers and automotive tier-1 suppliers.
Thickness Measurement captures the largest installed base; Surface Profiling is gaining share fastest in regulated medical device environments.
End User:
Supply concentration in optical glass shapes procurement leverage, with Schott AG and Hoya Corporation specialty low-dispersion materials exposing sensor vendors to dual carbon goal compliance costs.
- Semiconductor Manufacturers:Wafer metrology specifications below one micron compress sensor replacement cycles and force predictive calibration algorithm embedding into probe electronics. Gyeonggi-do memory fab concentration standardizes chromatic confocal procurement.
- Aerospace Fabricators:Vibration-prone production cells in Nagoya and Stuttgart embed fiber optic probes directly into grinding machine feedback loops, with fiber optic configurations extending into electromagnetic-sensitive environments.
- Precision Instruments:European manufacturers face ECHA scrutiny of lead-containing optical coatings forcing reformulation timelines.
- Research Laboratories:White light interferometry requirements for nanometer-scale resolution anchor premium niche demand.
- Automotive OEMs:Powertrain manufacturers negotiate sensor-as-a-service contracts with automatic probe replacement clauses.
- Optical Component Producers:Lens and prism fabricators requiring in-process thickness control for specialty glass processing.
Semiconductor Manufacturers represent the dominant volume segment; Aerospace Fabricators are expanding most quickly through embedded process control adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Japanese precision engineering clusters while consumption tilts toward South Korean semiconductor fabs and Chinese medical device manufacturers. This geographic split shapes procurement patterns and regulatory compliance burdens across vendor supply chains.
Germany
EMA medical device regulations and EU AI Act conformity requirements are reshaping validation protocols for automated optical inspection systems. REACH substance restrictions from ECHA scrutinize lead-containing optical coatings, forcing eight-to-fourteen month reformulation timelines. Stuttgart and Munich industrial corridors anchor chromatic confocal probe demand from automotive powertrain manufacturers embedding real-time thickness compensation.
South Korea
Samsung and SK Hynix memory fab ecosystems in Gyeonggi-do standardize non-contact thickness metrology for 3D NAND layer stacks. MFDS medical device registration requirements govern sensor deployment in pharmaceutical manufacturing automation. Busan-Ulsan precision engineering clusters are expanding fiber optic probe adoption for electromagnetic-immune process control in shipbuilding fabrication cells.
United States
FDA quality system regulations and ISO 10360 calibration standards govern market access for medical device and aerospace metrology buyers. Massachusetts and California precision instrument manufacturers require traceable sensors for automated optical inspection validation. Greater Boston medical device contract manufacturers negotiate sensor-as-a-service contracts with predictive maintenance subscriptions.
Japan
METI industrial standards and PMDA quality mandates shape procurement specifications for precision manufacturing equipment. Nagoya aerospace fabricators embed sub-millimeter fiber probes directly into grinding machine feedback loops. Tokyo-Yokohama semiconductor equipment suppliers compress sensor replacement cycles through predictive calibration algorithm integration.
China
NMPA certification timelines for medical device registration fluctuate unpredictably, complicating revenue forecasting for multinational sensor vendors. Dual carbon goals affect optical glass supply chains, redirecting procurement toward domestic sensor vendors in Yangtze River Delta manufacturing hubs. Shenzhen precision engineering clusters are localizing chromatic confocal assembly partnerships under India PLI scheme competitive pressure.
High-Precision Confocal Sensor Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across sensor architecture development. The vendor base separates into three tiers: integrated metrology system builders, specialized probe manufacturers, and regional component assemblers. Dominant competitive moves include sensor-as-a-service contract structuring and predictive maintenance software attach-rate expansion.
Within the precision probe tier, Keyence Corporation, Micro-Epsilon, and Precitec exemplify contrasting geographic anchoring strategies. Japanese direct sales infrastructure, German R&D-intensive chromatic technology specialization, and French fiber optic interferometer configuration expertise each represent distinct competitive positioning archetypes.
| Leading Market Players |
|---|
| Keyence Corporation |
| Micro-Epsilon |
| Precitec |
| STIL |
| Omron Corporation |
| SICK AG |
| Renishaw |
| ZEISS |
| Hypersen Technologies |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of chromatic confocal probe electronics anchors both supply security and pricing power for vendors serving semiconductor fabs in Gyeonggi-do and automotive powertrain manufacturers in Stuttgart. This backward integration into calibration algorithm development insulates tier-one suppliers from optical glass cost volatility while enabling premium positioning against assembly-only competitors.
Pricing Analysis
Margin tightening in validation-grade sensor tiers reflects REACH-driven reformulation costs for lead-free optical coatings extending development timelines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10360-traceable medical device configurations from production-floor chromatic probes and capacitive proximity alternatives. Semiconductor manufacturers in South Korea and Taiwan exhibit lowest price sensitivity due to uptime-based contract structures, while precision instrument manufacturers in China face acute cost compression from domestic vendor substitution.
Supply Chain Analysis
Freight cost differentials between German precision engineering clusters and South Korean memory fab ecosystems favor regional inventory positioning over centralized distribution. Specialty low-dispersion glass draws from Schott AG in Germany and Hoya Corporation in Japan, with objective lens fabrication tethered to these supplier geographies. Single-source vulnerability in ECHA-compliant coating chemistries concentrates risk in eight-to-fourteen month qualification windows. Distribution runs through direct sales forces for probe vendors and systems integrators for turnkey metrology installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase where fiber optic chromatic confocal probes displace laser triangulation systems in vibration-prone aerospace fabrication cells. This displacement accelerates as electromagnetic immunity requirements harden into procurement specifications.
For Market Incumbents: To counter algorithmic transparency documentation burdens from EU AI Act conformity requirements, embed edge computing modules with seven-year spectral data retention directly into probe electronics. Prioritize captive supply of REACH-compliant optical coating formulations to compress reformulation timelines. Channel control through regional spare inventory positioning in Busan-Ulsan and Nagoya industrial corridors sustains sensor availability guarantees against price-competitive domestic assemblers. For New Entrants and Emerging Players: The mid-tier pricing gap between Keyence direct-sales premiums and economy capacitive alternatives opens white-space in localized assembly partnerships for India PLI scheme beneficiaries in Gujarat and Karnataka. Target embedded process control applications in shipbuilding fabrication cells where electromagnetic immunity specifications filter out laser-based competitors. Pursue sensor-as-a-service contract structures with automotive tier-1 suppliers to decouple revenue from capital equipment procurement cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated metrology system builders seeking probe technology verticalization. Five-to-ten year viability hinges on regulatory documentation software attach rates outpacing hardware margin compression. Acquisition target archetype: German R&D-intensive chromatic specialists with embedded algorithm IP and EU AI Act validation protocols. Monitor NMPA certification timeline variability as inflection indicator for Chinese market access risk.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Calibration Algorithm Development | Embedded edge computing in probe electronics satisfies EU AI Act audit trail requirements for medical device manufacturers in Ireland. |
| REACH-Compliant Coating Formulation Investment | In-house optical coating capability compresses eight-to-fourteen month reformulation timelines forced by ECHA lead restrictions. |
| Regional Spare Inventory Positioning | Gyeonggi-do and Nagoya stocking hubs enable uptime-based contracts with Korean and Japanese memory fab procurement committees. |
| Fiber Optic Probe Miniaturization | Sub-millimeter diameters penetrate electromagnetic-sensitive aerospace grinding cells in Stuttgart competing against laser triangulation. |
| Sensor-as-a-Service Contract Structuring | Predictive maintenance subscriptions with automatic probe replacement clauses decouple vendor economics from unit shipment volatility. |
Research Methodology
Document review covered SEC filings from precision instrument manufacturers, EMA medical device registration databases, and MFDS pharmaceutical automation records, complemented by interviews with metrology system procurement managers at semiconductor fabs, biomedical engineers in hospital purchasing committees, and aftermarket service heads at automotive tier-1 suppliers. Secondary validation drew from customs trade data for optical component imports, ISO 10360 calibration laboratory accreditations, and REACH substance restriction notifications. Bottom-up probe shipment estimates triangulated against top-down precision manufacturing capital equipment expenditure patterns.
Historical capacity expansion announcements cross-referenced against panel input from plant engineers and OEM procurement teams anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, application resolution threshold, end-user regulatory environment, and regional manufacturing cluster concentration. CAGRs derived from slope-consistency checks against semiconductor wafer metrology specification trajectories and medical device validation-grade procurement growth curves.
Inputs from notified body auditors and GPO contracts managers were available through the study window; gaps in real-time NMPA certification timeline data introduce uncertainty bands for Chinese medical device market penetration assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Europe Machine Condition Monitoring Market