
 Conveyor Drive Market | 2026-2036
Conveyor Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Drive Market Insights
Direct distribution through system integrators is fragmenting as end users seek localized service networks for conveyor drive maintenance and retrofit. SEW-EURODRIVE leverages its German engineering base to dominate precision gearmotor supply for European automotive OEMs. Siemens competes through digital twin integration, anchoring its drives portfolio to Industry 4.0 software stacks. Sumitomo Drive Technologies specializes in heavy-duty cycloidal reducers, occupying niche positions in Asian mining operations.
A conveyor drive is an electromechanical power transmission unit comprising motors, gearboxes, and control electronics that convert electrical energy into regulated mechanical motion for bulk material transport. Typical units deliver torque outputs from 50 Nm to over 50,000 Nm with efficiency ratings governed by IEC 60034-30-1 motor classifications. Electric drives command the largest installed base due to energy efficiency mandates, while servo drives represent the fastest-expanding technology segment where positioning accuracy below 0.1 degree justifies premium pricing. Material handling applications generate the deepest margin pools as warehouse automation projects bundle drives with controls and software.
The US Department of Energy enforces minimum efficiency standards through NEMA MG-1, directly shaping motor procurement specifications for domestic manufacturing plants. Europe's Ecodesign Directive and REACH compliance requirements constrain material choices in gearbox lubricants and housing alloys, raising compliance costs for exporters. China's GB 18613 efficiency tiers and MIIT industrial upgrade programs accelerate domestic replacement cycles. Stakeholders must monitor how regional carbon border adjustments reshape total cost of ownership calculations for cross-border drive procurement.
Market Dynamics
Industrial motor efficiency mandates across Germany, the United States, and China are compressing replacement cycles while fragmenting procurement channels toward localized service networks. This regulatory convergence is redrawing competitive boundaries between precision gearmotor specialists and integrated automation platforms.
Growth Catalysts
- GB 18613 efficiency tiers:China's MIIT industrial upgrade programs accelerate domestic motor replacement in material handling facilities across Jiangsu and Guangdong provinces.
- Automotive OEM demand:European electric vehicle battery plants in Hungary and Poland require precision torque control for automated assembly lines.
- Servo positioning accuracy:Warehouse robotics in German distribution centers demand sub-0.1-degree motion control for high-speed sortation systems.
Market Restraints
- Rare earth magnet supply:Permanent magnet motor production depends on concentrated neodymium processing in China's Inner Mongolia region.
- REACH compliance costs:ECHA restrictions on gearbox lubricant formulations raise alloy and seal material expenses for European exporters.
- Hydraulic substitution:Heavy mining conveyors in Australian iron ore operations retain fluid power drives for shock-load tolerance above 50,000 Nm.
Strategic Opportunities
- Indian PLI scheme:Production-linked incentives for advanced manufacturing equipment create entry paths for servo-integrated conveyor systems in Gujarat and Tamil Nadu.
- Digital twin convergence:Real-time drive diagnostics fused with predictive maintenance software unlocks subscription revenue from automotive OEMs.
- Retrofit channel expansion:Independent service networks in the US Midwest capture margin pools from aging NEMA MG-1 motor replacements.
Industry Challenges
- IEC 60034-30-1 certification timelines:Multi-jurisdiction efficiency testing delays product launches by 8-14 months for cross-border suppliers.
- Legacy control integration:Brownfield facilities in US Rust Belt manufacturing clusters struggle to interface modern variable frequency drives with 1990s-era PLC architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Drive Market |
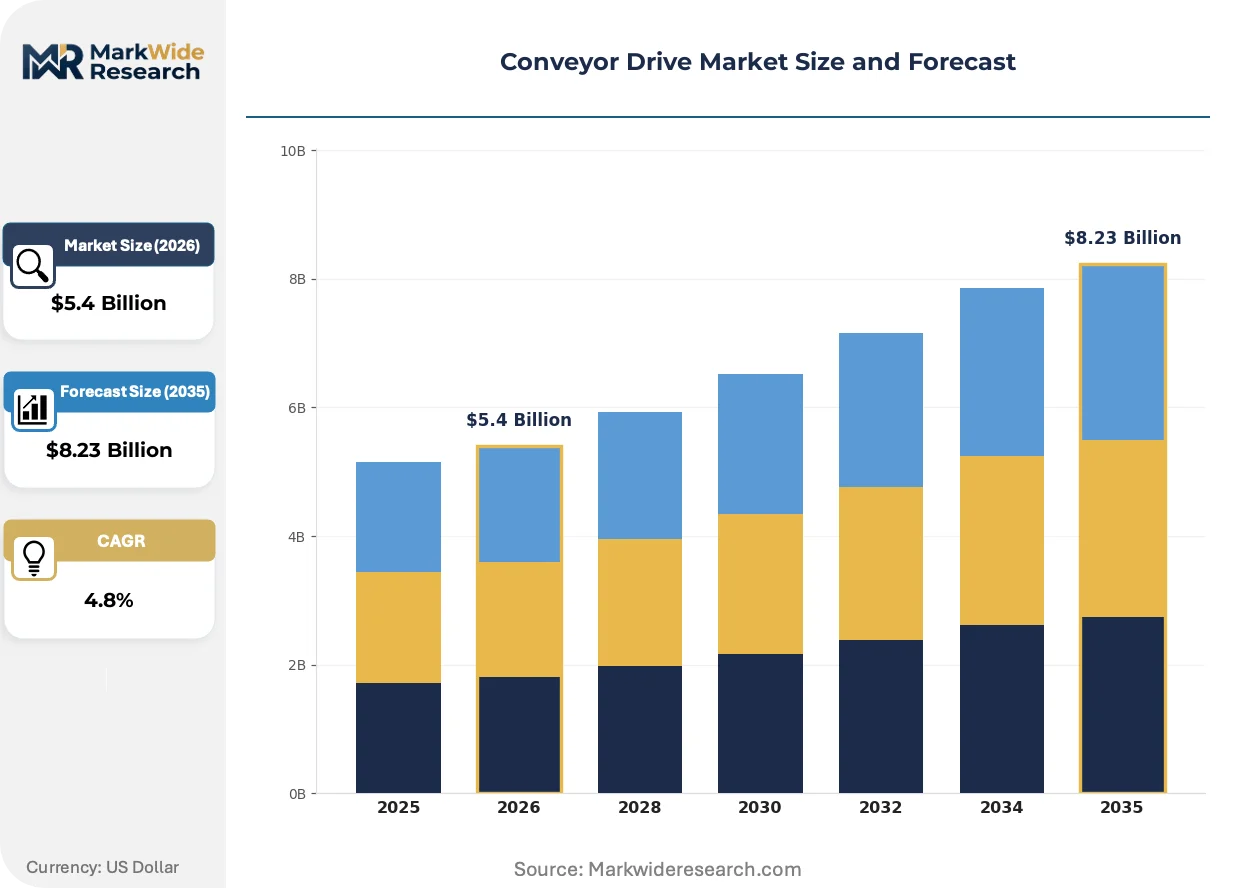
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Drives, Hydraulic Drives, Pneumatic Drives, Mechanical Drives Technology: Variable Frequency Drives, DC Drives, AC Drives, Servo Drives Application: Mining, Food Processing, Packaging, Material Handling, Textile End User: Manufacturing Plants, Logistics Companies, Warehousing Facilities, Automotive OEMs |
| Companies Covered | SEW-EURODRIVE, ABB, Bonfiglioli, Interroll, Lenze, NORD DRIVESYSTEMS, Regal Rexnord, Siemens, Sumitomo Drive Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Drive Market Trends and Innovations
Motion control architectures are fragmenting into two competitive camps: precision servo systems for positioning-intensive applications and high-efficiency asynchronous motors for bulk material transport. This bifurcation is reshaping R&D allocation and partnership strategies across the supply base.
Permanent magnet synchronous motors are migrating from premium servo applications into mid-range material handling equipment as ferrite magnet formulations reduce rare earth dependency. Food and beverage processors in the Netherlands and Belgium adopt these drives for washdown-compatible conveyor lines. The technology is migrating from niche positioning systems toward standardized bulk transport, compressing margins for conventional induction motor suppliers in the 1-50 kW range.
The EU Ecodesign Directive's 2025 recast tightens minimum efficiency requirements for motors operating above 8,000 annual hours. Industrial bakeries and cold storage facilities in northern France and Denmark face accelerated replacement schedules for continuous-duty conveyor systems. German gearbox manufacturers are responding with aluminum housing alloys and synthetic lubricants that satisfy both REACH substance restrictions and thermal dissipation targets.
End users in the US Southeast are unbundling drive procurement from system integrator contracts, establishing direct relationships with regional distributors for spare parts and field service. E-commerce fulfillment operators in Georgia and Tennessee now specify localized technician response times below four hours in RFQ documents. This disintermediation pressures OEM margins while elevating inventory carrying costs for distributors maintaining IEC and NEMA motor stock concurrently.
Conveyor Drive Market Segmentation
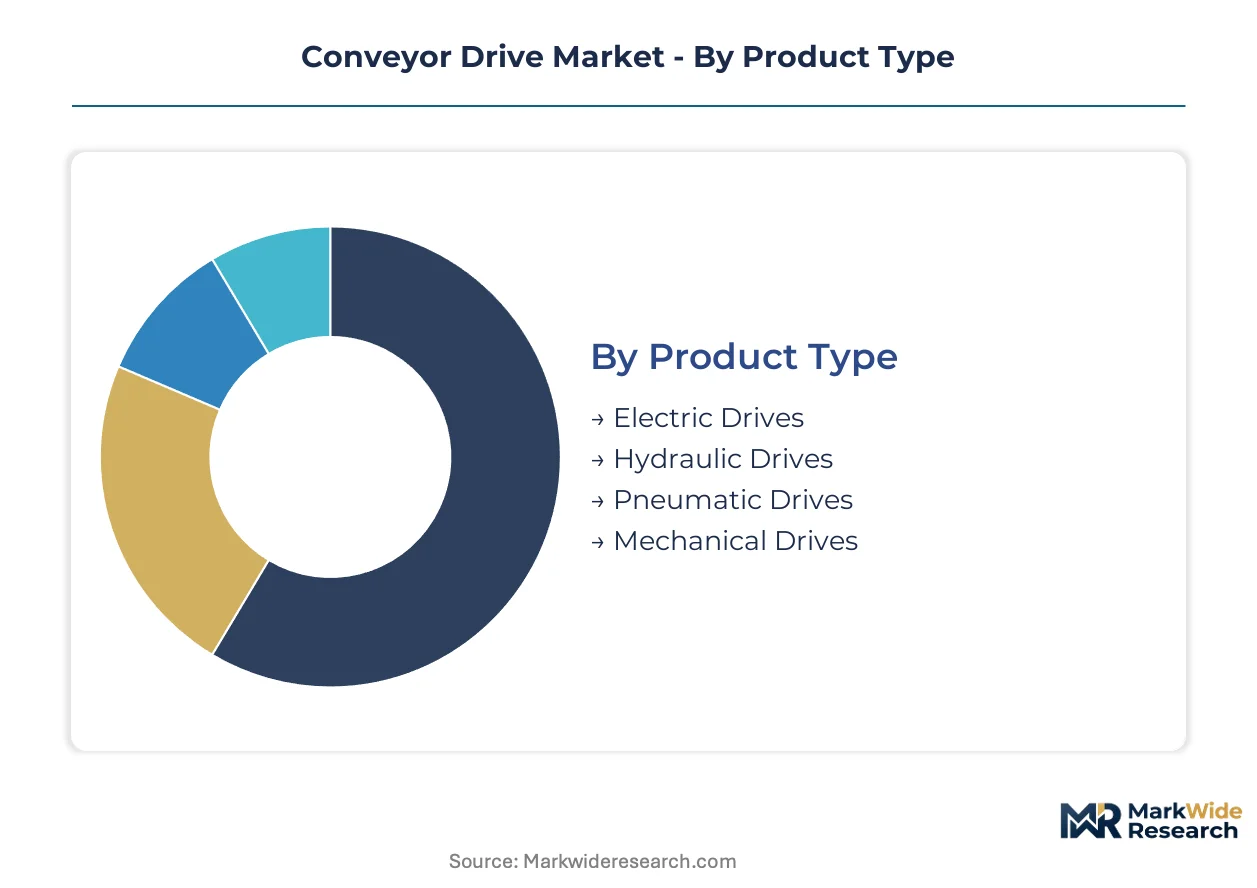
Conveyor drive procurement patterns diverge sharply across product architectures, with maintenance complexity and spare parts availability dicting supplier selection criteria. Segmentation reveals how efficiency mandates and automation intensity reshape technology adoption curves across end-use verticals.
Product Type:
After-sales service intensity varies dramatically across drive architectures, with electric systems requiring predictive diagnostics and hydraulic units demanding fluid management protocols.
- Electric Drives:Electromechanical systems converting grid power to regulated torque through IEC-classified motors, typically 50 Nm to 50,000 Nm output. German automotive battery plants in Hungary and Poland specify these for precision assembly line synchronization under NEMA MG-1 efficiency tiers.
- Hydraulic Drives:Fluid power transmission using pressurized oil circuits for shock-load absorption above 50,000 Nm. Australian iron ore mining operations in Western Australia retain these for heavy-duty bulk transport where mechanical overload protection outweighs energy efficiency targets.
- Pneumatic Drives:Compressed air systems for light-load intermittent duty cycles. Food processors in the Netherlands deploy these for washdown-compatible conveyor sections where electrical ingress protection costs exceed pneumatic infrastructure.
- Mechanical Drives:Direct chain or belt linkages without electronic control. Legacy installations in US Rust Belt manufacturing clusters persist where PLC retrofit budgets remain constrained.
By volume, Electric Drives leads. By growth pace, Servo-integrated electric variants are climbing the fastest.
Technology:
Control sophistication determines margin architecture, with digital integration capabilities separating premium positioning from commodity supply.
- Variable Frequency Drives:AC motor speed control through inverter-fed voltage modulation, enabling 20-90% energy recovery versus direct-on-line starting. Chinese material handling facilities in Jiangsu province accelerate adoption under GB 18613 efficiency mandates.
- Servo Drives:Closed-loop positioning systems achieving sub-0.1-degree accuracy through encoder feedback. German e-commerce distribution centers in Saxony specify these for high-speed sortation robotics where motion precision justifies 3-5x cost premiums over standard VFDs.
- AC Drives:Fixed-speed asynchronous motor controllers for continuous-duty bulk transport. Industrial bakeries in northern France deploy these under EU Ecodesign Directive recast timelines for motors exceeding 8,000 annual operating hours.
- DC Drives:Brushed or brushless motor control for legacy equipment compatibility. US Midwest retrofit channels maintain inventory for aging NEMA MG-1 motor replacements in brownfield manufacturing plants.
By installed base, Variable Frequency Drives dominates. By expansion trajectory, Servo Drives is gaining share fastest.
Application:
Operating environment severity shapes specification requirements, with dust exposure, washdown cycles, and duty continuity driving technology selection.
- Material Handling:Warehouse automation and distribution center conveyor networks bundling drives with controls and software. E-commerce logistics providers in Germany and the United States expand automated sorting facilities, generating the deepest margin pools through integrated system procurement.
- Mining:Continuous bulk ore transport under extreme shock loads and abrasive contamination. Asian mining operations in Indonesia and Mongolia specify heavy-duty cycloidal reducers for reliability above 50,000 Nm torque thresholds.
- Food Processing:Hygienic design requirements for washdown compatibility and lubricant safety. Belgian and Dutch processors adopt ferrite magnet synchronous motors to satisfy REACH restrictions on gearbox formulations.
- Packaging:Intermittent high-speed indexing for filling and labeling operations. Automotive OEMs in Poland integrate servo drives for precision torque control in battery module assembly.
- Textile:Tension-sensitive fiber handling requiring smooth acceleration profiles. Gujarat and Tamil Nadu manufacturing clusters in India explore PLI scheme incentives for servo-integrated systems.
By revenue contribution, Material Handling leads. By automation intensity, Packaging is expanding most quickly.
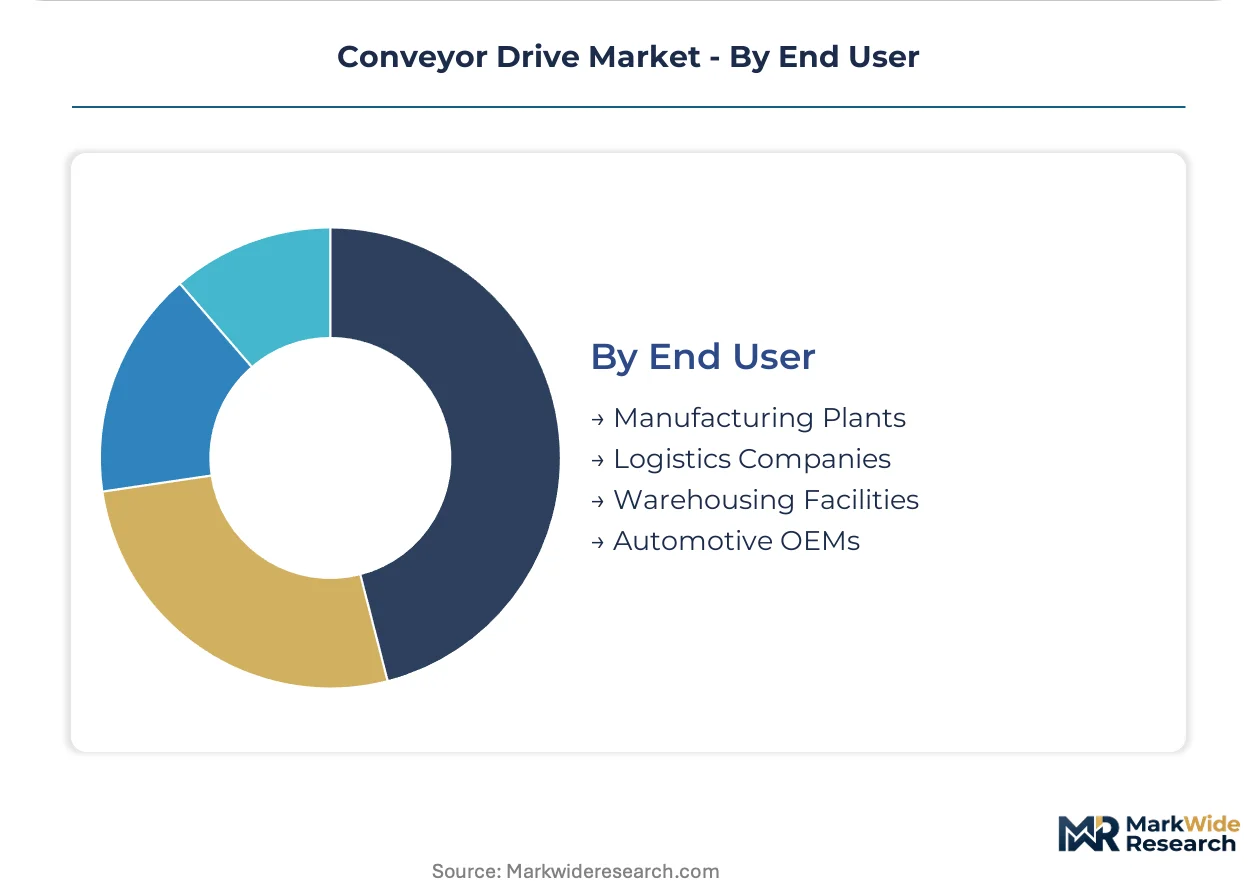
End User:
Procurement centralization versus distributed maintenance authority determines channel structure and pricing leverage.
- Logistics Companies:Third-party operators specifying localized technician response below four hours in RFQ documents. E-commerce fulfillment operators in Georgia and Tennessee unbundle drive procurement from system integrator contracts to establish direct distributor relationships.
- Automotive OEMs:Vertically integrated manufacturers demanding digital twin integration for predictive maintenance subscriptions. European electric vehicle battery plants anchor precision gearmotor demand through Industry 4.0 software stack requirements.
- Manufacturing Plants:Discrete and process industry facilities with mixed legacy and modern control architectures. US Rust Belt clusters struggle to interface variable frequency drives with 1990s-era PLC systems.
- Warehousing Facilities:Dedicated storage and distribution operations with continuous-duty conveyor networks. Cold storage operators in Denmark face accelerated replacement schedules under EU Ecodesign Directive efficiency thresholds.
By contract value, Automotive OEMs leads. By channel disintermediation velocity, Logistics Companies is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems anchor European conveyor drive demand, while China's Belt and Road rail corridors and Australia's iron ore export terminals shape procurement patterns across Asia-Pacific mining operations.
United States
E-commerce fulfillment centers in Georgia and Tennessee specify four-hour technician response times in RFQ documents. The Department of Energy enforces NEMA MG-1 minimum efficiency standards for domestic manufacturing plant motor procurement. Rust Belt manufacturing clusters in Ohio and Michigan struggle to interface modern variable frequency drives with 1990s-era PLC architectures.
Germany
Automotive battery plants in Hungary and Poland source precision gearmotors for electric vehicle assembly line synchronization. The Ecodesign Directive and REACH compliance requirements constrain gearbox lubricant formulations and housing alloy choices. Engineering clusters in Baden-Württemberg and Bavaria dominate servo-integrated system supply for high-speed sortation robotics.
China
Material handling facilities in Jiangsu and Guangdong provinces accelerate motor replacement under GB 18613 efficiency tiers mandated by MIIT industrial upgrade programs. Neodymium processing concentration in Inner Mongolia creates supply vulnerability for permanent magnet synchronous motor production. Yangtze River Delta logistics hubs deploy automated sorting infrastructure for domestic e-commerce distribution networks.
Australia
Western Australian iron ore mining operations retain hydraulic drives for shock-load tolerance exceeding 50,000 Nm in heavy-duty bulk transport applications. The country's national resources regulator enforces equipment reliability standards for continuous-duty conveyor systems in Pilbara extraction zones. Perth-based engineering contractors service remote mine sites with localized maintenance networks for fluid power transmission units.
India
Production-linked incentive schemes for advanced manufacturing equipment create entry paths for servo-integrated conveyor systems in Gujarat and Tamil Nadu textile clusters. The Bureau of Indian Standards certifies motor efficiency classifications for domestic industrial upgrade programs. Manufacturing hubs in Ahmedabad and Coimbatore explore automation bundling for tension-sensitive fiber handling applications.
Conveyor Drive Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision gearmotor and reducer supply. The market structures around three tiers: integrated automation platforms bundling drives with software stacks, precision gearmotor specialists serving automotive OEMs, and heavy-duty component fabricators for mining applications. Strategic moves concentrate on digital twin convergence for predictive maintenance subscriptions and retrofit channel expansion through independent service networks.
Within the precision gearmotor tier, SEW-EURODRIVE GmbH represents German engineering-base dominance for European automotive supply. Siemens AG exemplifies platform integrators anchoring drive portfolios to Industry 4.0 software stacks. Sumitomo Drive Technologies occupies a position among heavy-duty cycloidal reducer specialists serving Asian mining operations.
| Leading Market Players |
|---|
| SEW-EURODRIVE |
| ABB |
| Bonfiglioli |
| Interroll |
| Lenze |
| NORD DRIVESYSTEMS |
| Regal Rexnord |
| Siemens |
| Sumitomo Drive Technologies |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet concentration in China's Inner Mongolia region determines both pricing tier spreads and supply chain shape for permanent magnet synchronous motors. Buyers face procurement bifurcation between ferrite-based mid-range systems and neodymium-dependent premium servo drives.
Pricing Analysis
Volume-discount tiering structures separate precision servo-integrated systems from standard variable frequency drive configurations. Pricing stratifies across premium, standard, and economy tiers based on IEC 60034-30-1 efficiency certification levels and after-sales service bundling depth. Cost compression in the standard tier is intensifying because ferrite magnet formulations are displacing rare earth dependencies in mid-range material handling applications. Logistics companies with unbundled procurement contracts exhibit highest price sensitivity, while automotive OEMs anchoring Industry 4.0 software stacks demonstrate lowest sensitivity to unit cost premiums.
Supply Chain Analysis
Upstream feedstock for gearbox housings and motor laminations draws from steel processing clusters in Germany, China, and Japan. Copper winding supply rests on Chilean and Peruvian mining output, while synthetic lubricant formulations hinge on petrochemical feedstocks from the US Gulf Coast and Rotterdam refining hubs. Single-source vulnerability concentrates in neodymium oxide processing for permanent magnet production. Distribution runs through system integrator channels fragmenting toward independent regional service networks in the US Midwest and German engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance software subscriptions represent a service-attach opportunity expanding faster than hardware unit sales. Digital twin integration layers command recurring revenue multiples above traditional spare parts margins.
For Market Incumbents: Pre-empt channel disintermediation by captive control over independent service networks in high-velocity logistics corridors. Defend against hydraulic substitution in heavy mining through shock-load certification investment above 50,000 Nm thresholds. Vertical integration into ferrite magnet sourcing reduces rare earth exposure while preserving mid-range positioning. For New Entrants and Emerging Players: Retrofit channels for aging NEMA MG-1 motor replacements in US Rust Belt manufacturing clusters represent the most penetrable entry point. Indian PLI scheme incentives for servo-integrated textile systems in Gujarat and Tamil Nadu offer second-mover advantage without incumbent channel lock-in. Direct distributor relationships bypassing system integrator markups provide the clearest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors precision gearmotor specialists with localized service footprints. Long-term viability over the coming decade hinges on software stack integration rather than component manufacturing scale. Acquisition targets should demonstrate predictive maintenance platform deployment with automotive OEM anchor customers. The signal to watch is GB 18613 tier advancement timelines as inflection indicator for Chinese domestic replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Magnet Supply | Reduces neodymium dependency for mid-range conveyor drive production. |
| Digital Twin Platform Deployment | Locks automotive OEMs into predictive maintenance subscription revenue streams. |
| Regional Service Network Expansion | Captures unbundled procurement demand from US Southeast logistics operators. |
| GB 18613 Tier Certification Investment | Accelerates market access for Chinese material handling facility replacements. |
| REACH-Compliant Lubricant Formulation | Satisfies ECHA restrictions for European food processing conveyor applications. |
Research Methodology
Cross-validation between maintenance director interviews and customs trade data anchors the qualitative findings for aftermarket channel dynamics. Primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and system integrator account managers combines with secondary validation from IEC efficiency certification databases, NEMA MG-1 technical standards, MIIT industrial policy filings, and SEC equipment manufacturer disclosures. Bottom-up unit shipment estimates triangulate against top-down manufacturing value-added aggregates.
Calibration against historical replacement cycle patterns and regulatory mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include drive architecture type, control technology sophistication, end-use application severity, and regional regulatory cluster. CAGRs derive from installed base turnover rates and efficiency tier adoption curves. Forecast inputs incorporate neodymium price volatility indices and e-commerce fulfillment center buildout permits.
Practitioners should monitor rare earth export licensing shifts and carbon border adjustment mechanism proposals for early signals of supply cost revision. Forecasts reflect assumptions about regulatory enforcement continuity and commodity processing capacity expansion. Cross-checking against customs data for motor and gearbox trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
ROV Tether Management System Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market