
 Battery Spot Welder Market | 2026-2036
Battery Spot Welder Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Spot Welder Market Insights
Chinese equipment builders is recalibrating output schedules to match the surge in cylindrical cell gigafactory commitments across Southeast Asia. Sunkko leverages its domestic supply chain density to dominate entry-level manual welder exports. Telsonic AG sustains premium positioning through ultrasonic welding R&D for solid-state cell interfaces. Amada Miyachi America, Inc. anchors North American service networks with localized calibration and training infrastructure.
A battery spot welder is a resistance welding machine that delivers controlled electrical current through copper alloy electrodes to fuse thin metal tabs—typically nickel-plated steel or pure nickel strip ranging from 0.1 mm to 0.3 mm thickness—to battery cell terminals without filler material. The equipment serves as the critical joining stage in lithium-ion battery pack manufacturing, where thermal damage to electrolyte or separator must stay below degradation thresholds. Automatic systems now lead volume shipments as OEMs eliminate human variability from high-throughput cylindrical cell lines, while robotic welding configurations represent the fastest-growing configuration category as module designs diversify. Resistance welding technology still occupies the dominant margin pool due to electrode material and control algorithm specialization, though laser welding segments are capturing share in prismatic cell formats where access geometry restricts electrode placement.
FDA oversight of medical device batteries and EPA hazardous material handling rules indirectly shape welder specifications for US-based pack producers, while China's GB standards for lithium-ion safety mandate pulse waveform documentation that only digitally controlled welders can generate. The EU Battery Regulation's due diligence and recycled content thresholds will force welding equipment suppliers to certify process traceability by 2030. Stakeholders must decide whether to develop in-house pulse control firmware or license platforms from industrial automation specialists before regulatory verification becomes a binding tender requirement.
Market Dynamics
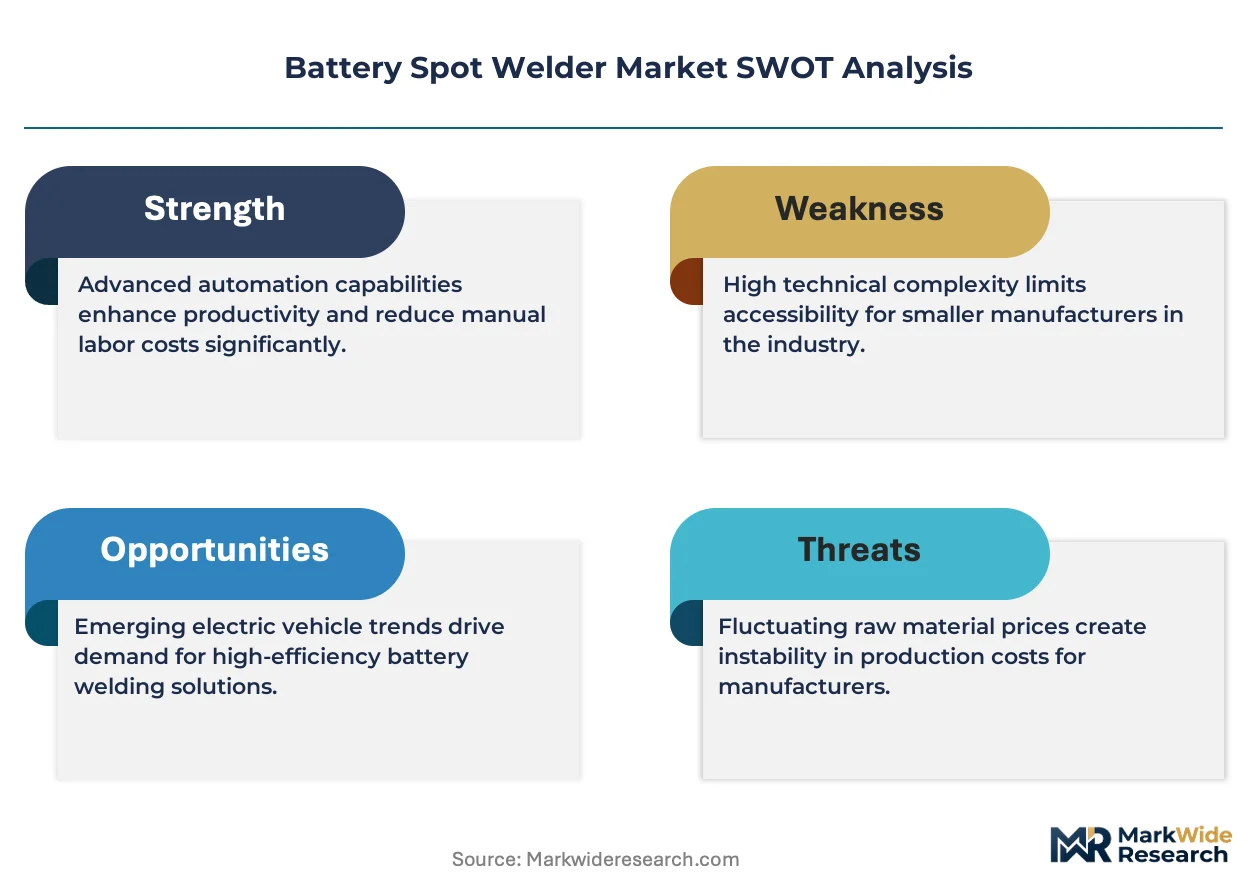
Cell-to-pack architecture migration is compressing joint counts per battery module while demanding higher amperage pulse precision, forcing equipment suppliers to recalibrate control firmware for fewer but more critical weld points per pack.
Growth Catalysts
- EU Battery Regulation traceability mandates:Carbon footprint declaration rules now require documented pulse waveform data that only digitally controlled resistance welders can generate, pulling European automotive suppliers toward upgrade cycles.
- Cylindrical cell gigafactory buildouts:Southeast Asian manufacturing commitments for 4680-format cells are scaling procurement of automatic resistance welding systems with robotic electrode positioning.
- Solid-state interface development:Ultrasonic welding R&D for ceramic-electrolyte cell architectures is creating parallel demand streams alongside conventional resistance equipment.
Market Restraints
- Copper alloy electrode cost volatility:Spot welding consumables face price pressure from refined copper market fluctuations, compressing margin pools for mid-tier equipment vendors.
- Prismatic cell laser substitution:Fiber laser welding systems are capturing joint-formation share where electrode access geometry restricts resistance welding placement in pouch and prismatic formats.
- China supply chain concentration:Sunkko and domestic equipment builders control entry-level manual welder export channels, limiting pricing power for second-tier international competitors.
Strategic Opportunities
- Medical device battery certification:FDA oversight of implantable power sources creates premium niches for welders with validated process documentation and electrode contamination controls.
- Service network localization:North American buyers now prioritize on-site calibration and training infrastructure over equipment-only transactions, favoring vendors with regional technical presence.
- Recycled content verification:EU due diligence thresholds will require welding equipment suppliers to certify process traceability by 2030, creating first-mover advantage for firmware-integrated platforms.
Industry Challenges
- Pulse control firmware development:Equipment builders must decide between in-house algorithm investment and licensing from industrial automation specialists before regulatory verification becomes a binding tender requirement.
- Electrode material specialization:Shortage of engineers with expertise in copper-chromium-zirconium alloy behavior under high-current cycling limits R&D velocity for next-generation electrode geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Spot Welder Market |
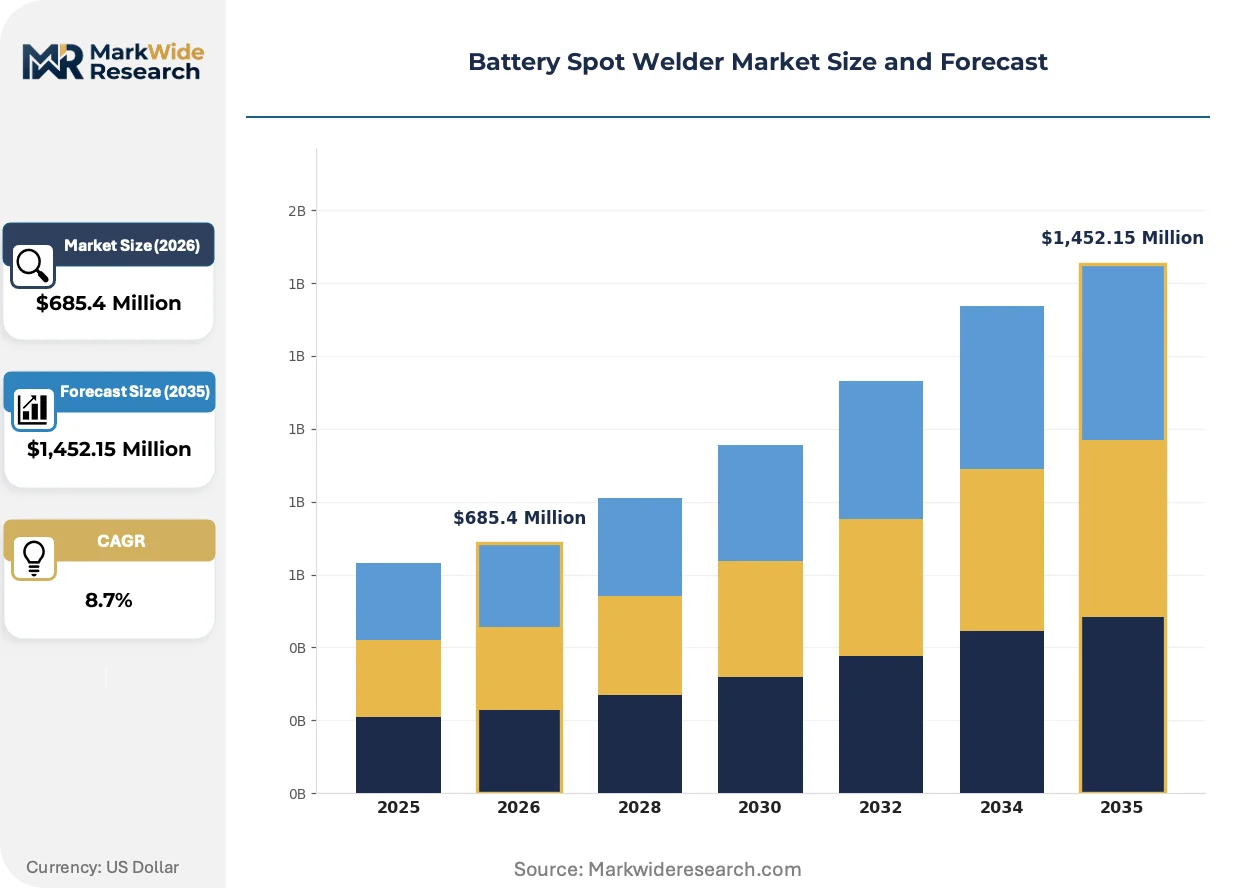
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Robotic Industry Vertical: Automotive, Electronics, Manufacturing, Aerospace End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Maintenance Services Technology: Resistance Welding, Laser Welding, Ultrasonic Welding, Others |
| Companies Covered | Sunkko, Acey, Xiamen Tmax Battery Equipments Limited, Xiamen TOB New Energy Technology Co., Ltd., Will-Best Welding Equipment Co., Ltd., Guangzhou Dragon Welding Co., Ltd, Telsonic AG, Amada Miyachi America, Inc., Miller Electric Mfg. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Spot Welder Market Trends and Innovations
Adaptive pulse algorithms and real-time weld quality monitoring are displacing fixed-parameter machines across high-throughput battery lines, while regulatory data-logging requirements are embedding traceability as a core equipment function.
Transistor-controlled inverter power supplies are electrifying resistance welding precision by enabling microsecond-level current modulation. Cylindrical cell gigafactories in Germany and China are adopting these systems for 4680-format production. The technology is electrifying competitive positioning around energy efficiency and thermal damage reduction in high-speed lines.
China's GB standards for lithium-ion safety now mandate pulse waveform documentation that analog-controlled equipment cannot generate. This regulatory friction is forcing domestic and export-oriented manufacturers toward digital control platform adoption. European pack producers sourcing from Chinese cell suppliers face compliance verification complexity at import.
Buyer concentration among automotive OEMs is compressing vendor negotiation cycles and unbundling after-sales service from equipment sales. Tier-1 battery manufacturers now demand predictive maintenance integration and remote diagnostics as standard. This pattern is most visible in Germany's automotive supplier corridor and China's Yangtze River Delta manufacturing clusters.
Battery Spot Welder Market Segmentation
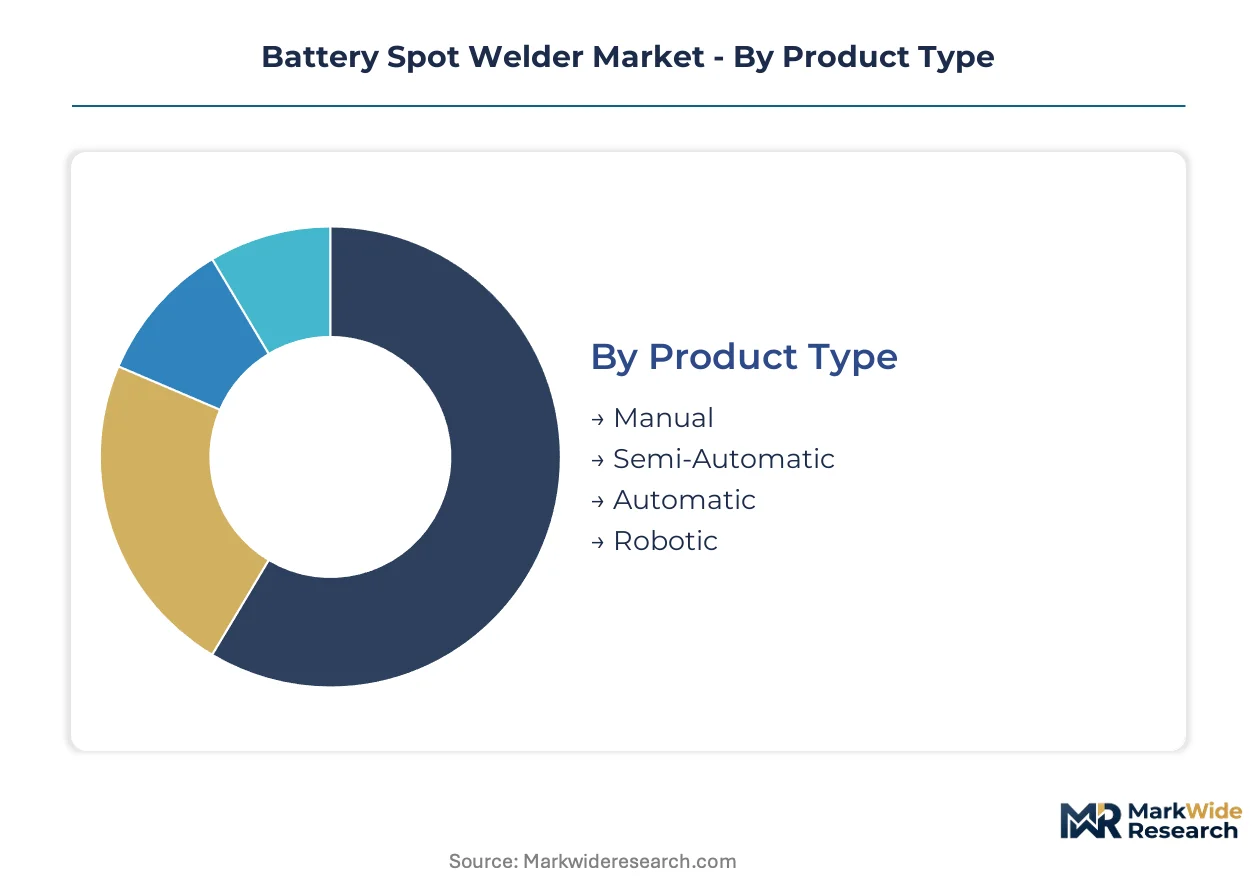
Equipment buyers in this market face sharply divergent capital deployment profiles depending on segment selection. Procurement decisions hinge on balancing throughput requirements against electrode precision needs and regulatory documentation capabilities.
Product Type:
Automatic and robotic configurations demand the heaviest upfront capital outlays due to servo-controlled electrode positioning and integrated data-logging architectures.
- Automatic:These systems deploy programmable logic controllers with real-time current feedback loops to maintain pulse consistency across high-throughput cylindrical cell lines. German automotive suppliers along the supplier corridor are scaling procurement of these units to meet EU Battery Regulation traceability mandates.
- Robotic:Articulated arm configurations with vision-guided electrode alignment enable complex joint geometries required by cell-to-pack architectures. Southeast Asian gigafactory buildouts for 4680-format cells are driving the steepest demand acceleration for this configuration.
- Semi-Automatic:Operator-assisted systems with foot-pedal activation bridge manual precision and production speed for mid-volume pack assemblers.
- Manual:Entry-level benchtop units with fixed-parameter controls dominate hobbyist and small-scale repair segments, with Chinese supply chains controlling export pricing.
Automatic systems absorb the bulk of installed capacity; robotic configurations are expanding most quickly.
Industry Vertical:
Automotive applications generate the highest equipment margins due to certification burdens and process validation requirements.
- Automotive:Battery pack assembly lines for electric vehicles require pulse waveform documentation and electrode contamination controls that only digitally controlled welders can deliver. EU carbon footprint declaration rules are accelerating replacement cycles among European Tier-1 suppliers.
- Electronics:Compact power tool and consumer device battery production favors semi-automatic systems with rapid changeover capabilities for diverse cell formats.
- Manufacturing:Industrial equipment and stationary storage applications prioritize equipment durability and electrode longevity over cycle speed.
- Aerospace:Satellite and unmanned vehicle battery systems demand validated process documentation under FAA oversight, creating premium pricing tiers for certified equipment.
Automotive verticals command the dominant share of equipment revenue; aerospace applications carry the highest unit margins.
End User:
OEMs and Tier-1 suppliers exercise divergent procurement patterns shaped by in-house versus outsourced pack assembly strategies.
- OEMs:Vehicle manufacturers with captive battery operations specify automatic systems with predictive maintenance integration and remote diagnostics as standard requirements.
- Tier-1 Suppliers:Independent pack producers serving multiple automotive clients prioritize flexible robotic configurations that accommodate varying module designs.
- Aftermarket Providers:Repair and replacement battery specialists favor manual and semi-automatic equipment for low-volume, high-mix production environments.
- Maintenance Services:Field service operations require portable welding systems with battery power options for on-site pack refurbishment.
Tier-1 suppliers represent the largest installed base; OEM captive operations are gaining share fastest.
Technology:
Resistance welding maintains technology leadership through electrode material specialization, though laser alternatives are capturing share in restricted-access geometries.
- Resistance Welding:Copper alloy electrode systems with transistor-controlled inverter power supplies enable microsecond-level current modulation for thermal damage reduction. This technology dominates cylindrical cell production due to established control algorithm expertise and consumables availability.
- Laser Welding:Fiber laser systems penetrate prismatic and pouch cell formats where electrode placement geometry restricts resistance welding access, particularly in Korean and Japanese battery manufacturing.
- Ultrasonic Welding:Solid-state cell interface development is creating parallel demand for ceramic-electrolyte joining without thermal degradation.
- Others:Emerging friction stir and diffusion bonding approaches serve niche applications in aerospace battery systems requiring minimal heat-affected zones.
Resistance welding retains the dominant margin pool; laser welding is climbing the fastest among alternative technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper-chromium-zirconium electrode supply chains in Germany's industrial belt anchor European procurement patterns for precision welding equipment.
United States
Domestic pack producers serving medical device OEMs face FDA battery safety oversight that mandates validated process documentation. EPA hazardous material handling rules indirectly shape welder specifications for US-based manufacturers. The Great Lakes automotive corridor concentrates demand from electric vehicle battery assembly operations.
Germany
EU Battery Regulation carbon footprint declaration requirements are accelerating replacement cycles among automotive Tier-1 suppliers. KBA vehicle-type approval processes extend to battery pack welding traceability standards. The supplier corridor stretching from Stuttgart to Wolfsburg hosts the densest concentration of cell-to-pack welding system deployments.
China
GB standards for lithium-ion safety mandate pulse waveform documentation that only digitally controlled welders generate. MIIT industrial policy supports domestic equipment builder capacity expansion for export markets. Yangtze River Delta manufacturing clusters absorb the majority of automatic resistance welding system installations for cylindrical cell production.
Japan
METI energy transition targets drive solid-state battery R&D investment requiring novel joining technologies. JIS standards for industrial equipment safety shape welder certification requirements for domestic and export sales. Nagoya-area automotive component suppliers are piloting ultrasonic welding systems for next-generation cell architectures.
South Korea
MFDS medical device battery regulations create parallel demand streams alongside automotive applications. Government-backed battery R&D consortia fund welding process development for prismatic cell formats. Busan-Ulsan industrial complexes host specialized equipment testing facilities for laser welding system validation.
Battery Spot Welder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ultrasonic and laser alternatives to resistance welding dominance. The vendor base stratifies across three tiers: multinational industrial automation specialists, regional equipment builders with captive domestic markets, and niche specialists serving medical or aerospace certification requirements. Strategic archetypes include electrode material specialists, firmware platform licensors, and integrated line builders. Capacity expansion and technology licensing represent the dominant competitive moves as regulatory documentation requirements reshape procurement criteria.
Within the Chinese equipment builder tier, Sunkko exemplifies supply chain density advantages for entry-level manual welder exports. Among Swiss-German precision specialists, Telsonic AG occupies a position representing ultrasonic welding R&D investment for solid-state interfaces. Amada Miyachi America, Inc. anchors North American service network localization strategies that prioritize calibration infrastructure over equipment-only transactions. These three archetypes illustrate divergent pathways for defending margin position amid electrode cost volatility and regulatory traceability mandates.
| Leading Market Players |
|---|
| Sunkko |
| Acey |
| Xiamen Tmax Battery Equipments Limited |
| Xiamen TOB New Energy Technology Co., Ltd. |
| Will-Best Welding Equipment Co., Ltd. |
| Guangzhou Dragon Welding Co., Ltd |
| Telsonic AG |
| Amada Miyachi America, Inc. |
| Miller Electric Mfg. Co. |
| Others |
Pricing and Supply Chain Analysis
Engineers with copper-chromium-zirconium alloy expertise concentrate in Germany's industrial belt, creating labor-cost differentials that separate premium precision welders from economy-grade Chinese exports by three-to-fivefold pricing spreads.
Pricing Analysis
Warranty and service bundling now determines effective price tiers across the Battery Spot Welder Market, with German and Swiss vendors unbundling calibration contracts from equipment sales while Chinese suppliers include basic support in headline pricing. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and after-sales infrastructure depth. Cost compression in entry-level segments is intensifying because Sunkko and domestic Chinese equipment builders control export channel density. Aftermarket repair providers exhibit highest price sensitivity; aerospace battery pack producers demonstrate lowest sensitivity due to FAA documentation requirements.
Supply Chain Analysis
CE and UL certification gating restricts electrode alloy sourcing to qualified German, Japanese, and American specialty metal producers. Copper-chromium-zirconium electrode stock, transistor-controlled inverter power modules, and vision-guided positioning systems constitute critical input dependencies. Single-source vulnerability concentrates in refined copper cathode supply from Chilean and Indonesian smelters. Distribution runs through direct OEM relationships for automatic systems, with regional equipment distributors handling semi-automatic and manual configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Spot Welder Market functions as a vertical-integration race where control over pulse control firmware development represents the decisive upstream lever separating premium vendors from component assemblers.
For Market Incumbents: Hedge against laser welding substitution in prismatic cell formats by accelerating ultrasonic welding R&D partnerships with solid-state battery developers. Deepen backward integration into copper-chromium-zirconium electrode production to offset refined copper price volatility compressing margin pools. Prioritize firmware platform licensing to mid-tier equipment builders before regulatory verification becomes mandatory.
For New Entrants and Emerging Players: Medical device battery specialists with FDA-validated process documentation represent the most penetrable buyer archetype underserved by incumbent service networks. Target portable welding system development for maintenance services requiring battery-powered on-site refurbishment capabilities. Pursue white-label manufacturing partnerships with Chinese equipment builders to access Yangtze River Delta supply chain density while building North American calibration infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with electrode material specialists given EU Battery Regulation traceability mandates forcing certification investment. Long-term viability favors firms with captive firmware development capabilities and regional service presence across multiple automotive production clusters. Monitor MIIT industrial policy announcements regarding domestic equipment builder export subsidies as inflection indicator for Chinese competitor pricing aggression.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Platform Licensing | Industrial automation specialists like Siemens enable mid-tier vendors to meet EU traceability mandates without in-house R&D. |
| Electrode Alloy Backward Integration | Captive copper-chromium-zirconium production insulates margin pools from London Metal Exchange price volatility. |
| Ultrasonic Welding R&D Partnership | Solid-state cell developers at Toyota and QuantumScape require ceramic-electrolyte joining without thermal degradation. |
| North American Service Network Expansion | Localized calibration infrastructure wins procurement from Great Lakes automotive corridor battery pack producers. |
| Medical Device Certification Investment | FDA-validated process documentation unlocks premium pricing tiers for implantable power source welding equipment. |
Research Methodology
Document review covered SEC filings from industrial automation specialists, EU Battery Regulation implementation guidance, and MIIT industrial policy announcements, complemented by interviews with equipment procurement managers at German Tier-1 automotive suppliers, maintenance directors at North American battery pack producers, and technical directors at Chinese electrode alloy producers. Secondary validation drew from customs trade data, GB standards documentation for lithium-ion safety, and FERC filings for stationary storage project equipment procurement. Bottom-up unit economics and top-down market sizing were cross-referenced for triangulation.
Historical shipment data from resistance welding equipment associations was cross-referenced against panel input from OEM platform engineers and aftermarket service heads to construct the projection framework. Segmentation modeling spanned product type, industry vertical, end user category, and technology platform across the analysis window. CAGRs were derived from regression analysis of equipment procurement cycles against battery gigafactory construction timelines and regulatory compliance deadline clustering.
Revisions become necessary when solid-state battery commercialization timelines accelerate, copper market volatility exceeds historical bands, or EU due diligence thresholds advance beyond current implementation schedules. Forecasts reflect assumptions regarding cylindrical cell format dominance and resistance welding technology retention in high-throughput lines. A model refresh is warranted upon material change in Chinese export subsidy policy or breakthrough fiber laser cost reductions in prismatic cell welding applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial I/O Modules Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Equipment Cases Market